
 Portable Conveyor Belt Market | 2026-2036
Portable Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Conveyor Belt Market Analytics
Skilled maintenance technician availability is bifurcating the portable conveyor belt competitive landscape into equipment-plus-service bundles versus bare-hardware sales. Continental AG leverages its dense regional service-station network to lock in long-term aftermarket contracts across European quarry operations. Fenner Dunlop anchors its position in Australian surface mining through captive rubber-compounding facilities that shorten replacement-belt lead times. Daifuku Co., Ltd. competes in Asian package-handling installations by integrating portable modules with its broader warehouse-automation stack.
A portable conveyor belt is a self-contained, wheel-mounted or skid-based material-transport apparatus using fabric-reinforced rubber or thermoplastic carcasses rated typically between 200 and 3,200 newtons per millimeter of belt width, designed for rapid relocation without fixed civil foundations. Its primary industrial purpose is to bridge temporary gaps between extraction, processing, and loading points in operations where permanent infrastructure proves uneconomical or geologically impractical. Belt Systems still occupy the largest revenue share among product types due to their lower first cost and universal parts availability, though Modular Systems are recording the fastest adoption curves in food-processing plants where sanitation protocols demand frequent configuration changes. Mining dominates end-user demand by tonnage handled, while Recycling represents the fastest-growing end-user category as municipal solid-waste sorting facilities retrofit static lines with mobile feed conveyors.
OSHA mandates in the United States govern conveyor guarding and emergency-stop spacing, directly shaping belt-guard designs and control-panel placements for equipment sold into American construction and recycling yards. The EU Machinery Directive and its harmonized EN 620 standards enforce CE-marking requirements that limit market access for non-compliant Asian manufacturers. Australia's state-level mining regulators, including the Queensland Department of Resources, impose site-specific conveyor-risk assessments that favor suppliers with local engineering-certification capabilities. Stakeholders must weigh whether to absorb compliance costs through in-house certification teams or to cede margin to third-party notified bodies as regulatory fragmentation intensifies across target geographies.
Market Dynamics
Construction firms and mining operators are compressing equipment replacement cycles from seven years to four years as modular belt architectures reduce site reconfiguration downtime by eliminating civil foundation work.
Growth Catalysts
- OSHA emergency-stop mandates:American construction yards must retrofit unguarded legacy lines, creating replacement demand for certified portable systems with integrated pull-cord stations.
- Iron ore corridor clustering:Australia's Pilbara region concentrates relocatable conveyor deployments to bridge extraction faces with remote processing hubs as pit geometry shifts quarterly.
- Thermoplastic carcass advances:Polyurethane-reinforced belts rated above 1,600 N/mm now withstand oil-saturated recycling environments previously requiring rubber compounds.
Market Restraints
- Steel input volatility:Fabric-reinforced carcasses depend on galvanized cord steel whose price swings compress margin predictability for European manufacturers.
- Rubber compound supply concentration:Specialty fire-resistant formulations rely on Malaysian and Indonesian feedstock processors vulnerable to export licensing disruptions.
- EN 620 certification friction:CE-marking timelines for Asian manufacturers stretch fourteen to eighteen months, freezing market access during design validation.
Strategic Opportunities
- Canadian surface mining underpenetration:Alberta oil sands and Saskatchewan potash operations still rely on truck haulage for fifty percent of material movement, creating conversion whitespace.
- Food-grade sanitation convergence:Modular thermoplastic systems combined with quick-release belt tensioners allow protein processors to swap configurations between shifts without tool-based disassembly.
- EU Green Deal embodied-carbon tracking:Equipment-plus-service bundles that document lifecycle emissions gain preferential procurement status in Dutch and German municipal waste contracts.
Industry Challenges
- Certified technician scarcity:Vulcanized splicing and computerized tensioning diagnostics require skills concentrated in aging workforces across Australian and Canadian mining districts.
- Legacy control integration:Portable belt modules must interface with fifty-year-old SCADA architectures in American aggregates operations, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Conveyor Belt Market |
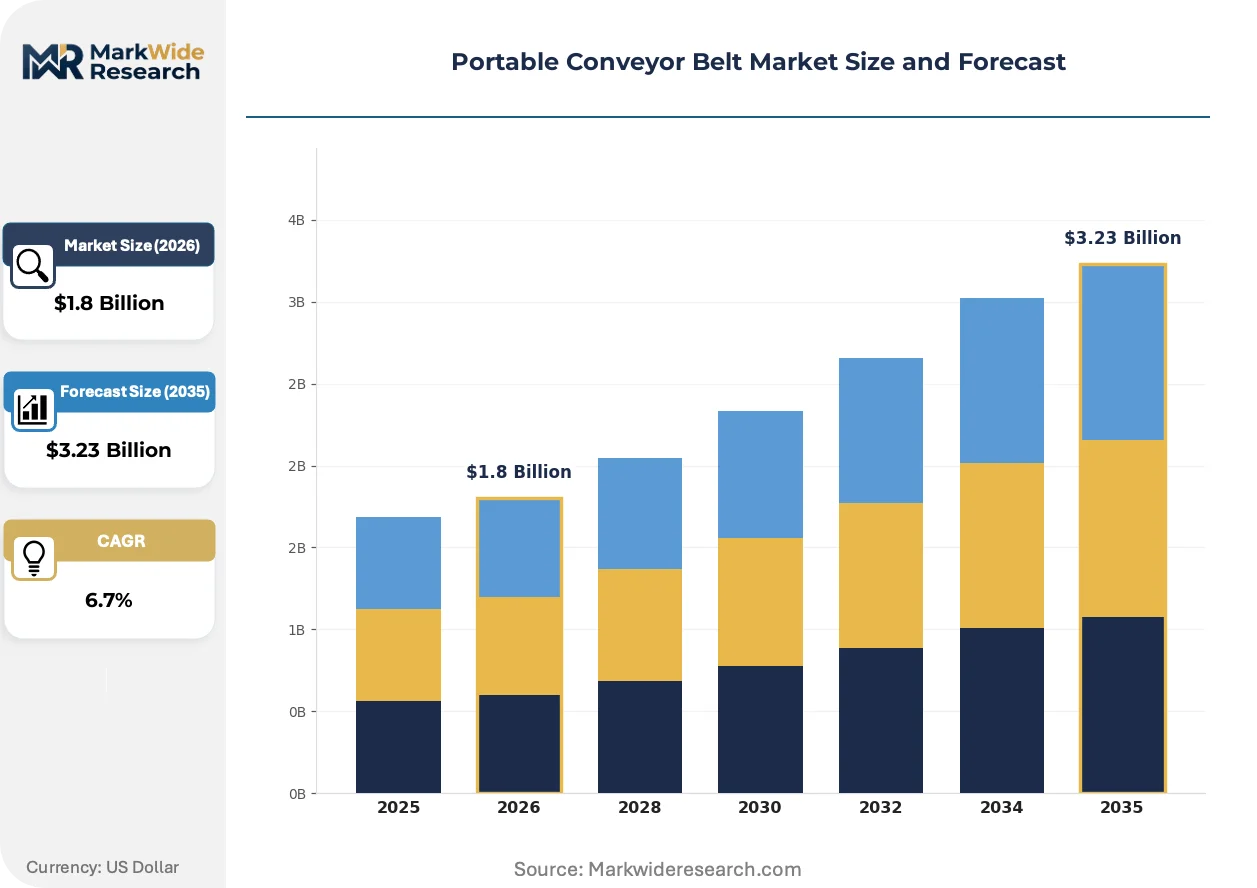
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Systems, Modular Systems, Zero-Pressure Systems, Adjustable Height Systems End User: Mining, Construction, Agriculture, Recycling Material: Rubber, PVC, Steel, Composite Materials Application: Bulk Material Handling, Package Handling, Food Processing, Automotive Assembly |
| Companies Covered | Continental AG, Daifuku Co., Ltd., Fives Group, Intralox, BEHA Belt, Fenner Dunlop, Habasit AG, Forbo Holding AG, Dorner Mfg. Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Conveyor Belt Market Evolving Landscape
Equipment architecture is pivoting from standalone hardware sales toward integrated mobility platforms where wheel-mounted frames, self-aligning idlers, and plug-and-play power connections ship as unified subsystems rather than field-assembled components.
Radio-frequency identification tracking embedded in belt carcasses is supplanting manual thickness-gauge inspections by transmitting real-time wear data to maintenance tablets. Surface mining operators in Western Australia deploy this capability across hundred-unit fleets, compressing preventive maintenance windows from monthly to continuous monitoring and reducing unplanned downtime events.
REACH restrictions on polycyclic aromatic hydrocarbons in rubber formulations are forcing compounders to reformulate fire-resistant grades around halogen-free alternatives. German quarry operators now specify these certified belts exclusively, while Asian manufacturers without in-house compounding capabilities face eighteen-month reformulation cycles to regain CE-marking eligibility.
Service unbundling is fragmenting traditional aftermarket relationships. North American recycling yards now procure belt segments through distributor stock programs while commissioning third-party mobile vulcanization crews for field splicing, bypassing OEM service networks that previously captured replacement revenue through exclusive technician deployment.
Portable Conveyor Belt Market Segmentation
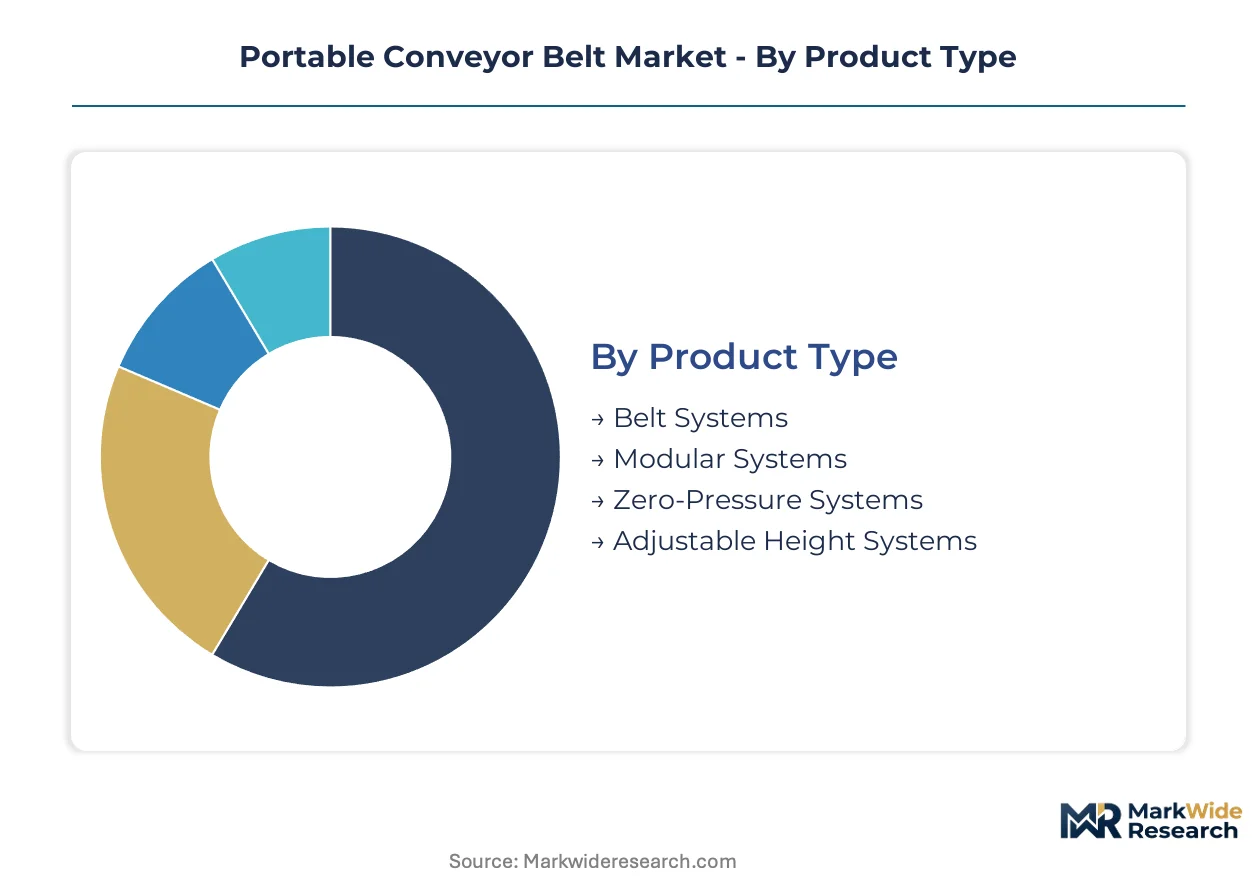
Portable conveyor belt segmentation reflects divergent compliance burdens and site-specific mobility requirements. Regulatory fragmentation across mining, food, and automotive end-uses forces suppliers to maintain parallel certification portfolios rather than unified product architectures.
Product Type:
OSHA emergency-stop mandates and EU Machinery Directive guarding requirements split this category between certified integrated systems and component-level sales.
- Belt Systems:Fabric-reinforced rubber or thermoplastic carcasses rated 200-3,200 N/mm dominate Australian Pilbara iron ore corridors where pit geometry shifts demand quarterly relocation. Queensland Department of Resources site-risk assessments favor these systems for their established fire-resistance documentation and local engineering certification.
- Modular Systems:Thermoplastic segments with quick-release tensioners expand fastest in protein processing plants where USDA sanitation protocols and shift-based configuration changes converge. Dutch municipal waste contracts under EU Green Deal embodied-carbon tracking prefer these for documented lifecycle emissions.
- Zero-Pressure Systems:Accumulation zones with pneumatic or motorized roller brakes suit package-handling operations requiring gentle product separation.
- Adjustable Height Systems:Telescoping frame architectures serve construction yards with variable loading dock heights and uneven terrain.
Established volume favors Belt Systems; emerging adoption favors Modular Systems.
End User:
Customer procurement sophistication ranges from lifecycle service contracts in mining to spot-buy replacement segments in agriculture.
- Mining:Surface operations in Western Australia and Canadian oil sands deploy hundred-unit fleets with RFID-embedded carcasses for continuous wear monitoring. Tightening mine safety protocols in Alberta and Saskatchewan push operators toward certified systems with enhanced emergency-stop ratings.
- Recycling:Municipal solid-waste sorting facilities retrofit static lines with mobile feed conveyors, climbing fastest as oil-saturated environments adopt thermoplastic carcasses rated above 1,600 N/mm.
- Construction:North American and European firms compress replacement cycles to four years as modular architectures eliminate civil foundation work.
- Agriculture:Grain handling and bulk commodity transfer drive seasonal demand with lower certification stringency.
Installed base concentrates in Mining; steepest expansion trajectory appears in Recycling.
Material:
REACH restrictions on polycyclic aromatic hydrocarbons and fire-resistance ratings determine compound selection authority between suppliers and third-party processors.
- Rubber:Fabric-reinforced carcasses with galvanized cord steel cores retain cost advantage in mining tonnage applications despite steel input volatility.
- PVC:Thermoplastic formulations gain share in food-processing and recycling environments where oil saturation previously mandated rubber compounds.
- Steel:Solid plate or mesh constructions serve heavy-aggregate applications with extreme impact loading.
- Composite Materials:Hybrid carcasses combining synthetic fibers with metallic elements target weight-sensitive portable deployments.
Margin stability favors PVC; specification authority favors Rubber.
Application:
Sanitation tier and control-system integration complexity separate commodity from premium positioning.
- Bulk Material Handling:Iron ore, aggregates, and construction debris dominate tonnage throughput with standardized guarding configurations.
- Package Handling:E-commerce fulfillment and warehouse automation demand plug-and-play power connections compatible with Daifuku-style integrated mobility platforms.
- Food Processing:USDA and FDA sanitation mandates force halogen-free compound reformulations, extending CE-marking timelines for non-compliant Asian manufacturers.
- Automotive Assembly:Precision indexing and legacy SCADA interface requirements extend commissioning timelines in fifty-year-old American aggregates operations.
Scale economies favor Bulk Material Handling; integration complexity favors Package Handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA emergency-stop mandates in the United States anchor the most stringent compliance environment, while Australia's state-level mining regulators and the EU Machinery Directive create parallel certification tracks that fragment supplier access across major demand centers.
United States
Construction firms compress replacement cycles to four years as modular architectures eliminate civil foundation work. OSHA mandates govern conveyor guarding and emergency-stop spacing, directly shaping belt-guard designs for equipment sold into American construction and recycling yards. The Permian Basin aggregates operations and Great Lakes bulk terminals deploy hundred-unit fleets with RFID-embedded carcasses for continuous wear monitoring.
Australia
Surface mining operators in Western Australia's Pilbara region deploy relocatable conveyor fleets to bridge extraction faces with remote processing hubs as pit geometry shifts quarterly. The Queensland Department of Resources imposes site-specific conveyor-risk assessments that favor suppliers with local engineering-certification capabilities. Perth-based engineering clusters anchor aftermarket service networks across the mining corridor.
Germany
Quarry operators specify halogen-free fire-resistant belts exclusively following REACH restrictions on polycyclic aromatic hydrocarbons. The EU Machinery Directive and harmonized EN 620 standards enforce CE-marking requirements that limit market access for non-compliant manufacturers. The Ruhr industrial basin and Bavarian aggregates districts drive demand for equipment-plus-service bundles with documented lifecycle emissions under EU Green Deal procurement rules.
Canada
Alberta oil sands and Saskatchewan potash operations still rely on truck haulage for fifty percent of material movement, creating conversion whitespace for certified portable systems. Tightening mine safety protocols push operators toward enhanced emergency-stop and fire-resistance ratings. The Athabasca oil sands region and Saskatoon potash belt concentrate pilot deployments of relocatable conveyor fleets.
China
Domestic manufacturers face eighteen-month CE-marking timelines that freeze European market access during design validation. GB standards and MIIT industrial equipment regulations shape domestic procurement specifications for construction and mining applications. The Yangtze River Delta manufacturing clusters and Shanxi coal belt drive volume demand for thermoplastic carcass systems in bulk material handling.
Portable Conveyor Belt Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium-tier suppliers capture aftermarket service revenue while commodity fabricators compete on first-cost metrics. The vendor base spans multinational industrial conglomerates with dense regional service networks, specialized belting manufacturers with captive compounding capabilities, and modular automation integrators. Three archetypes dominate: equipment-plus-service bundlers, bare-hardware volume producers, and integrated warehouse-automation stack providers. Competitive moves concentrate on strategic partnerships for certification compliance and geographic expansion through distributor stock programs.
Among European-based industrial conglomerates, Continental AG and Forbo Holding AG occupy positions anchored by dense service-station networks and material-science expertise. Fenner Dunlop exemplifies the specialist archetype with captive rubber-compounding capabilities. Daifuku Co., Ltd. sits within the automation-integrator tier, representing the convergence of portable modules with broader warehouse-automation infrastructure. These three anchors illustrate how competitive positioning fragments across service intensity, material control, and system integration vectors.
| Leading Market Players |
|---|
| Continental AG |
| Daifuku Co., Ltd. |
| Fives Group |
| Intralox |
| BEHA Belt |
| Fenner Dunlop |
| Habasit AG |
| Forbo Holding AG |
| Dorner Mfg. Corp. |
| Others |
Value Network & Pricing Analysis
Thermoplastic carcass substitution for fabric-reinforced rubber is redrawing procurement geography while compressing margin structures for traditional compounders. This material transition simultaneously diversifies supplier bases toward Asian thermoplastic processors and intensifies price competition in mid-tier belt segments previously dominated by European rubber specialists.
Pricing Analysis
Price spreads between Australian mining-grade systems and North American construction units exceed fifty percent, reflecting divergent certification burdens and service-attach intensity. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated systems with lifecycle service contracts from distributor-sourced bare hardware and spot-market replacement segments. Cost compression in standard-tier rubber belts is intensifying because Malaysian feedstock licensing disruptions compound steel cord volatility. Municipal recycling yards exhibit highest price sensitivity due to fragmented procurement authority, while Pilbara iron ore operators prioritize availability over unit cost.
Supply Chain Analysis
Malaysia and Indonesia anchor specialty fire-resistant rubber compounding, while Germany and Japan control precision thermoplastic extrusion equipment manufacturing. Galvanized cord steel draws from Chinese and South Korean metallurgical processors, with polyurethane resin feeds concentrated in German and Belgian chemical clusters. Single-source vulnerability concentrates in Indonesian export licensing for halogen-free compound precursors. Distribution runs through OEM-direct channels for mining fleet contracts and distributor stock programs for North American construction spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable conveyor belt economics increasingly hinge on aftermarket service attach rates, with RFID-enabled predictive maintenance contracts expanding at double the pace of hardware shipments. This recurring-revenue layer justifies reorienting commercial strategy around lifecycle customer value rather than transactional equipment margins.
For Market Incumbents: Shield installed-base relationships by embedding proprietary diagnostics into belt carcasses that lock out third-party service crews. Captive vulcanization networks in Australian mining districts defend against distributor stock programs eroding replacement revenue. CE-marking investment in halogen-free compounds preserves European quarry access as REACH enforcement tightens. For New Entrants and Emerging Players: EN 620 fast-track certification through notified-body partnerships in Germany or the Netherlands accelerates European market entry ahead of eighteen-month Asian validation timelines. Canadian oil sands and Saskatchewan potash corridors offer penetrable whitespace where truck haulage still dominates material movement. Target municipal recycling retrofits with thermoplastic modular systems positioned for oil-saturated environments. For Investors and Strategic Acquirers: EU Green Deal embodied-carbon tracking reshapes the acquisition landscape by privileging equipment-plus-service bundles with documented lifecycle emissions. Five-to-ten-year viability favors specialists with captive compounding capabilities over bare-hardware assemblers exposed to commodity input swings. Monitor Queensland Department of Resources risk-assessment tightening as inflection signal for certification-capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive halogen-free formulation capability secures CE-marking autonomy and eighteen-month lead time advantage. |
| RFID-Enabled Predictive Maintenance Platform | Continuous wear monitoring compresses preventive maintenance windows and locks in long-term service contracts. |
| Alberta Oil Sands Fleet Conversion Program | Truck-to-conveyor substitution in fifty-percent haulage corridors opens hundred-unit deployment opportunities. |
| EU Green Deal Certification Bundle | Documented lifecycle emissions documentation gains preferential procurement status in Dutch and German municipal contracts. |
| Third-Party Vulcanization Network Bypass | Direct mobile splicing crews capture replacement revenue previously ceded to distributor technician pools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at Australian iron ore operations, plant engineers in North American construction aggregates, aftermarket service heads at European quarry OEMs, and procurement leads at Dutch municipal waste facilities. Secondary validation drew from customs trade data, SEC equipment-manufacturer filings, Queensland Department of Resources safety bulletins, and EU Machinery Directive harmonized standards documentation. Bottom-up unit deployment estimates triangulated against top-down end-use industry capital expenditure patterns.
Across the analysis window, volume and value outputs segment by product architecture, material carcass type, end-use industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted replacement cycle compression and greenfield conversion penetration curves. Modeled inputs include steel cord price volatility indices, CE-marking timeline distributions, and RFID adoption saturation thresholds in Western Australian surface mining.
Underlying assumptions cover stable Malaysian and Indonesian feedstock export licensing, with deviation risk concentrated in REACH compound reformulation timelines and Canadian provincial safety protocol harmonization. Recalibration cycles align with material shifts in regulatory enforcement intensity and thermoplastic carcass performance validation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market