
 Global Elevator Market | 2026-2036
Global Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elevator Market Analysis
EN 81-20/50 compliance is collapsing the vendor landscape for new high-rise projects across Europe and Asia. Otis Elevator Company leverages its global service network to sustain aftermarket revenue streams in mature markets. Schindler Group anchors its competitiveness through digital twin integration for predictive maintenance. KONE Corporation differentiates via machine room-less traction systems that reduce shaft footprint in dense urban cores.
An elevator is a vertically guided transportation platform operating on steel wire ropes or hydraulic pistons, rated for speeds from 0.5 m/s in residential units to over 10 m/s in supertall structures, designed to move passengers or freight between building levels under automated control. Passenger elevators dominate volume but face margin compression from commoditization, while home elevators represent the fastest-expanding category as aging-in-place demographics reshape residential architecture. Traction technology leads in new installations above six stories due to energy efficiency, whereas hydraulic systems retain strongholds in low-rise commercial and industrial settings where load capacity exceeds 4,500 kg.
Europe's EMA and CE marking frameworks enforce strict safety and accessibility protocols that extend product development cycles but create barriers against uncertified imports. China's SAMR and GB standards mandate escalator and elevator inspections that accelerate modernization demand in aging building stock. India's BIS certification requirements for electrical and mechanical safety are tightening as urban vertical construction intensifies. Stakeholders must weigh regulatory compliance investments against the margin structure of emerging-market expansion where local certification partnerships determine market access speed.
Market Dynamics
AI-driven predictive maintenance systems are restructuring procurement criteria across commercial high-rise developments, forcing vendors to bundle software subscriptions with hardware contracts rather than competing on equipment alone.
Growth Catalysts
- Urban densification in Asia-Pacific megacities:Vertical construction in Mumbai, Shanghai, and São Paulo is generating concentrated demand for high-speed traction systems as land scarcity intensifies.
- EN 81-20/50 safety mandates:European standards are accelerating replacement cycles in aging building stock, creating mandatory modernization revenue streams.
- Machine room-less traction technology:Reduced shaft footprints enable developers to reclaim leasable floor area in dense urban cores.
Market Restraints
- Steel and copper price volatility:Wire rope and motor winding materials expose manufacturers to commodity margin compression.
- Concentrated control system supply:Proprietary controller firmware from German and Japanese suppliers creates single-source vulnerability.
- Hydraulic system substitution ceiling:Traction technology caps addressable market for low-rise hydraulic installations above six stories.
Strategic Opportunities
- Home elevator underpenetration:Aging-in-place demographics in Japan and Italy are expanding residential retrofit demand.
- China's dual carbon goals:Energy efficiency mandates favor regenerative drive systems with power recovery capabilities.
- Digital twin convergence:Integration of IoT sensors with building management systems enables predictive service bundling.
Industry Challenges
- Certified technician scarcity:Elevator mechanic apprenticeship pipelines in Germany and the US lag replacement demand.
- Legacy system integration friction:Retrofitting smart diagnostics into 1980s electromechanical controllers requires custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elevator Market |
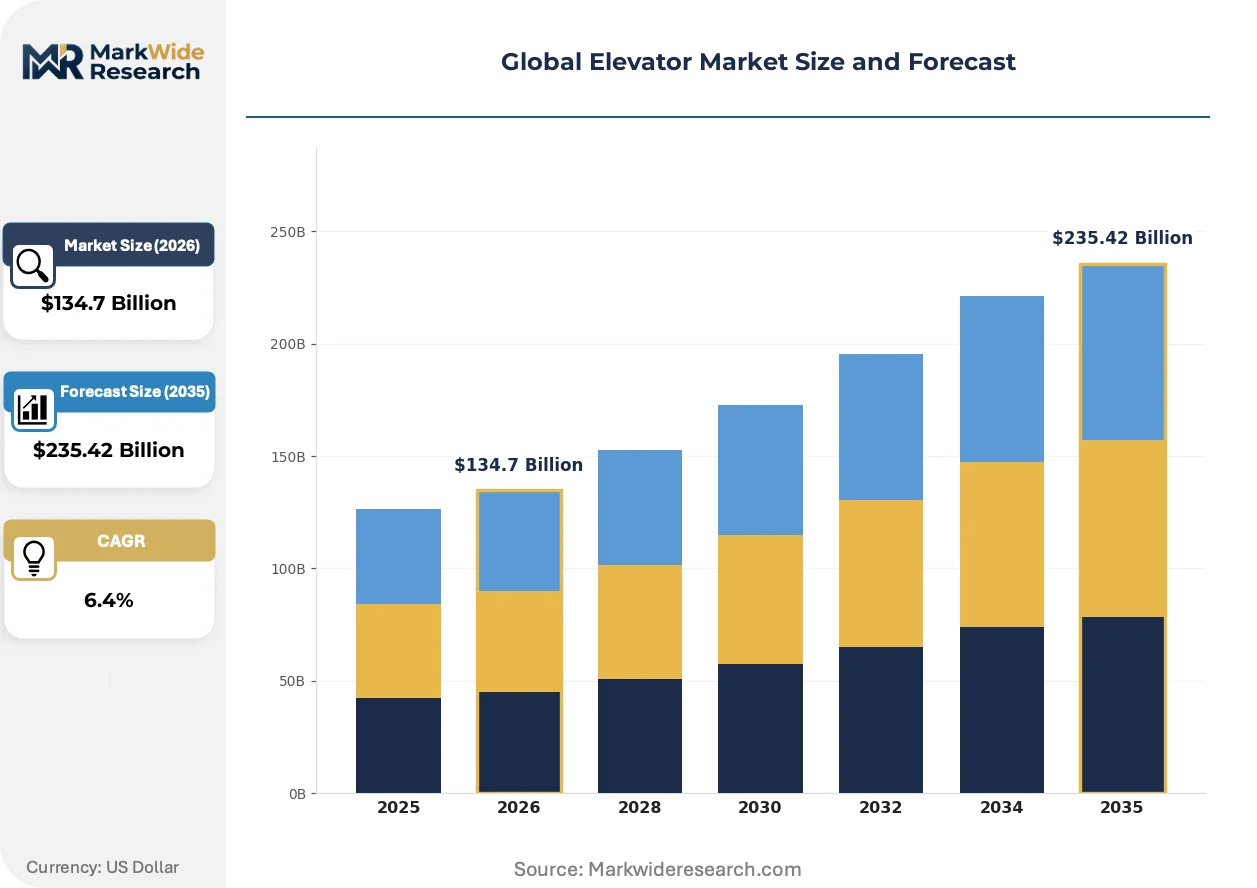
| Market Size in 2026 | $134.7 Billion |
| Market Size in 2035 | $235.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Elevator, Freight Elevator, Service Elevator, Home Elevator Technology: Traction, Hydraulic, Machine Room-Less, Vacuum End User: Residential, Commercial, Industrial, Institutional Installation: New Installation, Modernization, Maintenance, Repair |
| Companies Covered | Otis Elevator Company, Schindler Group, KONE Corporation, TK Elevator, Mitsubishi Electric Corporation, Hitachi Ltd., Fujitec Co., Ltd., Hyundai Elevator Co., Ltd., Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elevator Market Emerging Trajectories
Predictive algorithms and regenerative drives are redefining equipment valuation models, shifting buyer focus from upfront capital expenditure to total lifecycle cost optimization.
Regenerative drive technology is supplanting traditional resistor-based braking systems in mid-rise and high-rise installations. Property developers in Singapore and Dubai are specifying power-recovery capabilities as standard for new commercial towers. This shift is compressing margins for manufacturers lacking in-house power electronics expertise.
China's SAMR inspection mandates are tightening compliance windows for aging elevator populations. GB standards now require documented safety upgrades for installations exceeding fifteen years of service. Building operators in tier-one cities are responding with accelerated modernization schedules rather than risk operational shutdowns.
Service contract unbundling is fragmenting traditional vendor relationships in North American commercial real estate. Facility managers are separating maintenance procurement from original equipment agreements, favoring independent service providers with AI-enabled diagnostic platforms. This pattern is most visible in Class-A office portfolios across Chicago and Toronto.
Global Elevator Market Segmentation
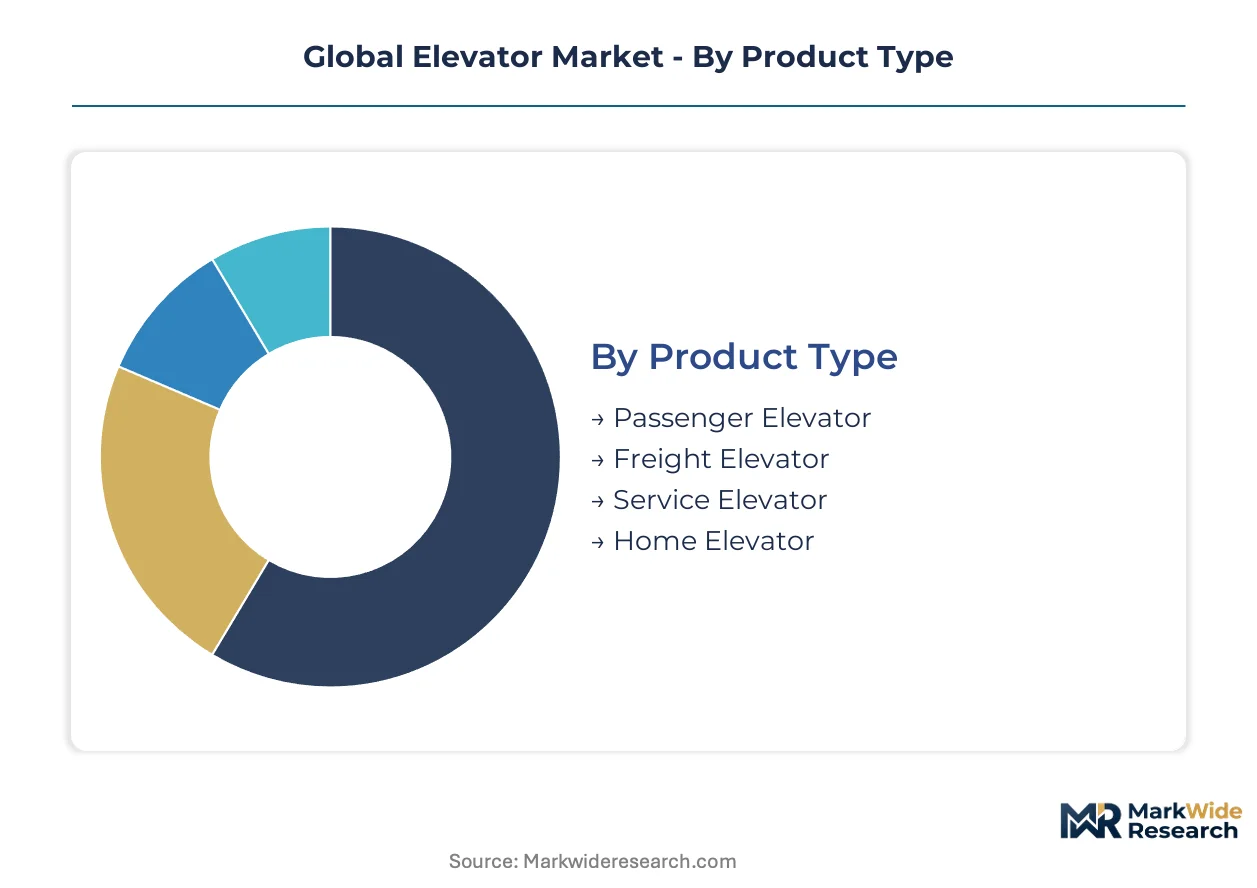
Elevator procurement channels diverge sharply by segment. Commercial high-rise developers source through engineering-procurement-construction consortia. Residential retrofits flow through architectural specifiers and accessibility contractors. Industrial buyers favor direct manufacturer relationships for load-rated systems.
Product Type:
Channel mix varies by building use case. Passenger elevators move through construction procurement networks. Home elevators reach end-users via accessibility specialists and aging-in-place remodelers.
- Passenger Elevator:Steel wire rope or belt-driven platforms rated for 630-2,500 kg capacity, serving 8-21 passengers. Demand concentrates in Mumbai, Shanghai, and São Paulo high-rise cores where land scarcity mandates vertical densification. EN 81-20/50 compliance is collapsing vendor options for European new-build tenders.
- Home Elevator:Compact traction or hydraulic units with 250-450 kg ratings for 2-4 passengers, designed for residential shaft retrofits. Aging-in-place demographics in Japan and Italy are accelerating retrofit demand through accessibility remodeling channels. Machine room-less configurations dominate where basement mechanical space is unavailable.
- Freight Elevator:Heavy-duty platforms with 1,600-10,000 kg capacity for warehouse and manufacturing vertical logistics.
- Service Elevator:Staff-only transport systems with restricted access controls for hospital and hotel back-of-house operations.
By volume, Passenger Elevator leads. By growth pace, Home Elevator is climbing the fastest.
Technology:
Cost tier stratification separates premium regenerative traction from economy hydraulic alternatives. Power electronics capability determines vendor positioning across tiers.
- Traction:Electric motor-driven sheave systems with counterweight balancing, achieving 1.0-10.0 m/s speeds. Commercial towers in Singapore and Dubai specify regenerative variants as standard. GB standards in China favor energy recovery capabilities for new installations above six stories.
- Machine Room-Less:Compact traction motors mounted within the hoistway, eliminating penthouse mechanical floors. Dense urban cores in São Paulo and Mumbai reclaim 15-25 square meters of leasable floor area per shaft. Reduced construction costs offset premium equipment pricing.
- Hydraulic:Piston-driven systems for low-rise applications under six stories with high load requirements.
- Vacuum:Pneumatic tube transport for residential retrofits where conventional shafting is structurally impractical.
Traction systems command the largest installed base. Machine Room-Less is gaining share fastest in urban infill projects.
End User:
Application-specific performance requirements shape procurement specifications. Speed, capacity, and duty cycle ratings align with building operational intensity.
- Commercial:High-cycle passenger systems with destination dispatch and traffic management algorithms. Class-A office portfolios in Chicago and Toronto unbundle maintenance contracts from original equipment agreements. AI-enabled predictive service platforms are restructuring vendor selection criteria.
- Residential:Lower-duty systems with aesthetic customization for multi-family and single-family applications. Aging building stock in China's tier-one cities drives modernization demand under SAMR inspection mandates.
- Industrial:Heavy-load freight systems with corrosion-resistant finishes for manufacturing and warehouse environments.
- Institutional:Accessibility-compliant platforms with emergency power and fire service features for hospitals and government facilities.
Commercial generates the highest equipment revenue per project. Residential retrofit is expanding most quickly as demographic shifts accelerate.
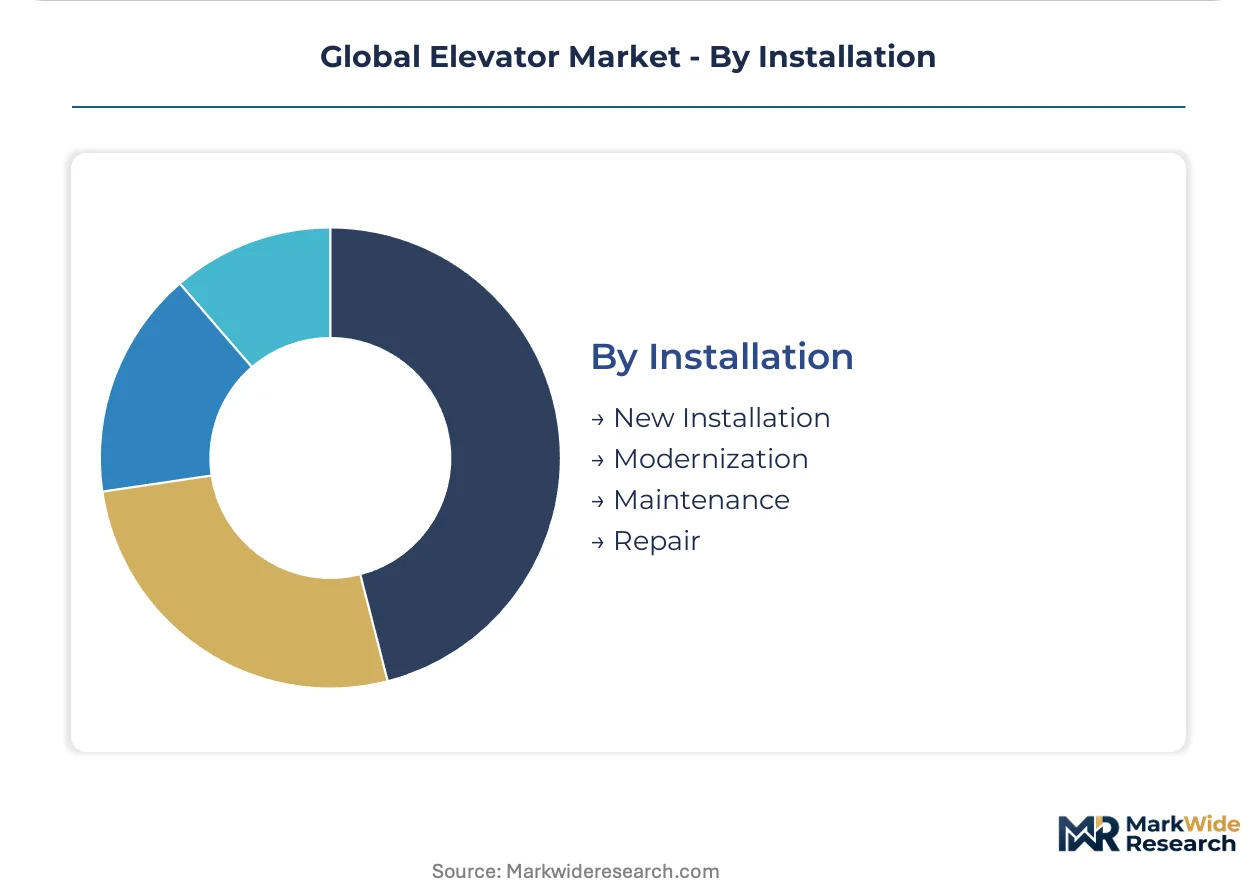
Installation:
Customer type and asset life stage determine service mix. New construction favors bundled equipment-installation contracts. Aging installed base shifts revenue toward discrete modernization and maintenance events.
- New Installation:Greenfield equipment deployment with integrated building management system interfaces. Infrastructure investment waves in Brazil and India concentrate demand in São Paulo and Mumbai metropolitan corridors. Local certification partnerships determine market access speed.
- Modernization:Component replacement and control system upgrades for installations exceeding fifteen years of service. China's GB standards mandate documented safety upgrades, accelerating replacement cycles in aging building stock.
- Maintenance:Scheduled inspection and preventive service contracts sustaining aftermarket revenue streams.
- Repair:Reactive intervention for component failure and emergency restoration.
New Installation dominates absolute spend. Modernization is climbing the fastest as regulatory compliance windows tighten across mature building stocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate developers in China, India, and Brazil concentrate new equipment procurement through engineering-procurement-construction consortia. Residential retrofit demand clusters in aging urban cores across Japan and Italy. Regulatory compliance windows in Europe and China are accelerating modernization cycles in mature building stocks.
China
Vertical construction in Shanghai and Shenzhen drives high-speed traction system demand as land scarcity intensifies. SAMR inspection mandates under GB standards require documented safety upgrades for installations exceeding fifteen years. Tier-one cities including Beijing and Guangzhou are responding with accelerated modernization schedules.
India
Mumbai's high-rise densification generates concentrated demand for machine room-less configurations that reclaim leasable floor area. BIS certification requirements for electrical and mechanical safety are tightening as urban vertical construction accelerates. The Delhi-NCR corridor and Bengaluru metropolitan area anchor infrastructure investment waves.
United States
Class-A office portfolios in Chicago and Toronto unbundle maintenance contracts from original equipment agreements. OSHA safety protocols and ASME elevator codes govern modernization timelines in aging commercial stock. The Southeast corridor from Atlanta to Miami exhibits concentrated residential retrofit activity for aging-in-place demographics.
Germany
EN 81-20/50 compliance is collapsing vendor options for European new-build tenders. CE marking frameworks enforce strict accessibility protocols that extend product development cycles. The Rhine-Ruhr industrial cluster and Munich metropolitan area concentrate certified technician training pipelines.
Brazil
Infrastructure investment waves concentrate demand in São Paulo metropolitan corridors. ANVISA and local safety regulators mandate inspection protocols that accelerate replacement cycles. Rio de Janeiro's commercial high-rise sector specifies regenerative drive capabilities under emerging efficiency guidelines.
Global Elevator Market Vendor Landscape
Player mix skews toward integrated multinational equipment manufacturers with captive service networks. Market structure exhibits tiered concentration with premium traction specialists, mid-scale regional fabricators, and price-competitive hydraulic providers. Strategic archetypes include full-lifecycle service bundlers, machine room-less technology specialists, and predictive maintenance platform operators. Dominant competitive moves encompass vertical integration into power electronics manufacturing and strategic partnerships with building management system providers.
Within the premium-tier multinational segment, Otis Elevator Company, Schindler Group, and KONE Corporation exemplify divergent competitive positioning. Otis leverages its global service network archetype. Schindler anchors digital twin integration for predictive maintenance. KONE occupies a position emphasizing machine room-less traction systems for dense urban cores.
| Leading Market Players |
|---|
| Otis Elevator Company |
| Schindler Group |
| KONE Corporation |
| TK Elevator |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Fujitec Co., Ltd. |
| Hyundai Elevator Co., Ltd. |
| Toshiba Corporation |
| Others |
Supply Flow & Price Mechanics
EN 81-20/50 certification gates both vendor qualification and price differentiation in European and Asian procurement simultaneously, compressing margins for uncertified suppliers while enabling premium positioning for compliant manufacturers with documented safety upgrade capabilities.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate commercial high-rise procurement in São Paulo and Mumbai. Price differentiation rests on regenerative drive integration and predictive maintenance bundling rather than equipment alone. Cost compression in standard traction systems is intensifying because Chinese and Indian fabricators are expanding capacity for machine room-less configurations. Residential retrofit buyers in Japan and Italy show highest price sensitivity, while Class-A office developers in Singapore and Dubai prioritize lifecycle cost over upfront capital.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Shenzhen ports to São Paulo and Mumbai construction sites have elevated landed equipment costs for German and Japanese controller assemblies. Manufacturing concentrates in China, Germany, and Japan for traction motors and control systems. Supply chains draw from steel wire rope producers in South Korea, copper winding suppliers in Chile, and power electronics from Taiwan. Single-source vulnerability in proprietary controller firmware creates structural risk. Distribution runs through engineering-procurement-construction consortia for new installations and independent service providers for aftermarket maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across residential retrofit and modernization segments as aging-in-place demographics and regulatory compliance windows create service niches underserved by integrated multinationals.
For Market Incumbents: Consolidate aftermarket service networks in China's tier-one cities before SAMR inspection mandates accelerate third-party maintenance capture. Deepen backward integration into power electronics manufacturing to defend margin position against regenerative drive commoditization. Lock in long-term service contracts with Class-A office portfolios in Chicago and Toronto before unbundling patterns spread.
For New Entrants and Emerging Players: Differentiate on AI-enabled diagnostic platforms for legacy electromechanical controller retrofit in Europe's aging building stock. Target home elevator accessibility contractors in Japan and Italy with machine room-less traction configurations priced below multinational premiums. Pursue certification partnerships with India's BIS for faster market access in Mumbai and Delhi-NCR corridors.
For Investors and Strategic Acquirers: China's dual carbon goals reshaping the acquisition landscape toward regenerative drive specialists and predictive maintenance platform operators. Five-to-ten year viability favors targets with captive technician training pipelines and documented GB standards compliance. Watch for SAMR enforcement intensity in tier-two cities as inflection signal for modernization demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | In-house regenerative drive production defends margins against controller firmware suppliers from Germany and Japan. |
| Certification Partnership Expansion | BIS and SAMR alignment in India and China accelerates market access speed for new installation tenders. |
| Predictive Maintenance Platform Launch | AI-enabled diagnostics capture unbundled service contracts from Class-A office portfolios in North America. |
| Machine Room-Less Capacity Buildout | Compact traction configurations reclaim leasable floor area for developers in São Paulo and Mumbai dense cores. |
| Technician Apprenticeship Pipeline Investment | Certified mechanic scarcity in Germany and the US creates competitive moat through service network coverage. |
Methodological Framework
Initial hypotheses were tested against primary input from elevator OEM procurement directors, facility management executives at Class-A office portfolios, certified technician training program administrators, and aftermarket service provider operators, and refined through secondary validation against customs trade data, SAMR inspection disclosure filings, BIS certification registries, and SEC 10-K equipment manufacturer disclosures. Bottom-up project pipeline analysis across São Paulo, Mumbai, and Shanghai construction databases triangulated with top-down equipment shipment tracking from German and Japanese controller suppliers.
Variance decomposition across product type, technology tier, end-use application, installation mode, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro construction indicators and energy efficiency mandate trajectories. Modeled inputs included GB standards compliance cost curves, steel and copper price volatility bands, and machine room-less adoption penetration rates by building height class.
Material uncertainties — commodity price spikes, regulatory enforcement intensity variations, and technician training pipeline bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about urban densification continuity and carbon mandate durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Automated Material Handling (AMH) Market