
 Debris Loaders Market | 2026-2036
Debris Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Debris Loaders Market Analysis
Certified heavy equipment operator availability is collapsing across North American waste management and municipal fleets, constraining deployment timelines for debris removal programs. Caterpillar sustains manufacturing scale across multiple loader categories, ensuring supply continuity for large municipal contracts. Komatsu specializes in hydraulic system integration, differentiating its offerings in high-moisture debris environments. Volvo competes through channel control, leveraging its dealer network to secure fleet replacement cycles in coastal municipalities.
Debris loaders are specialized material handling machines engineered to collect, lift, and transport vegetative waste, construction rubble, and storm-generated refuse, typically featuring reinforced buckets with capacities exceeding three cubic yards and hydrostatic drivetrains for variable terrain traction. Their primary purpose centers on post-disaster clearance and routine urban maintenance where conventional excavation equipment lacks precision or efficiency. Truck-mounted loaders dominate municipal procurement due to mobility requirements across dispersed service zones, while vacuum loaders represent the fastest-expanding technology segment as cities prioritize dust suppression and airborne particulate containment. Waste management companies anchor the highest-margin end-user pool, driven by long-term service contracts that justify premium equipment specifications.
EPA emission standards under the Clean Air Act shape engine certification requirements, compelling manufacturers to integrate Tier 4 Final powertrains or electrified alternatives. OSHA workplace safety directives govern operator protection structures and rollover protection, directly influencing cab design and fleet compliance timelines. Municipalities navigating tighter federal procurement guidelines must evaluate total cost of ownership against operational uptime guarantees when specifying loader configurations for climate-adapted infrastructure programs.
Market Dynamics
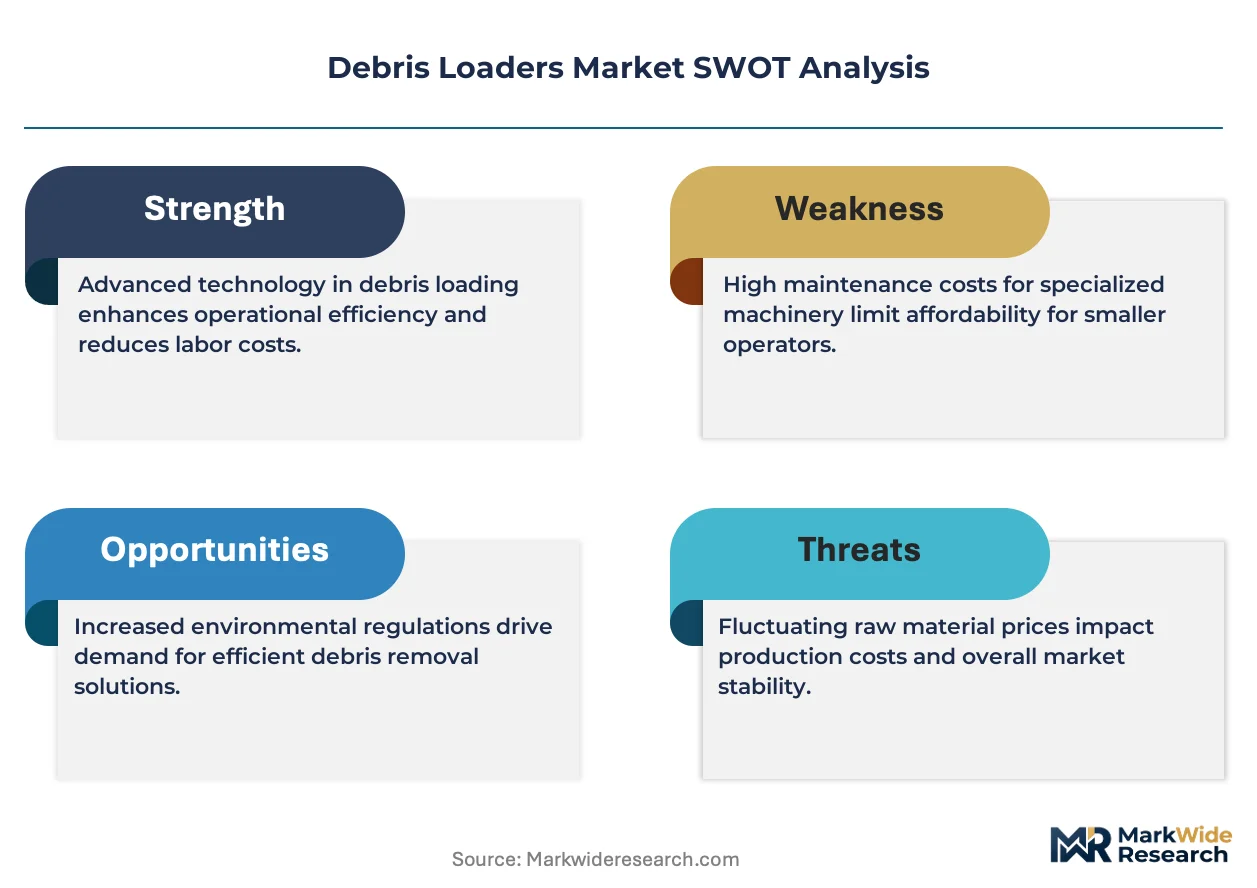
EPA Tier 4 Final emissions mandates are compressing diesel engine availability while hydraulic and electric drivetrain architectures scramble to fill the performance gap in high-torque debris handling applications. This regulatory compression is restructuring supplier relationships and accelerating technology substitution timelines across municipal procurement cycles.
Growth Catalysts
- Storm Intensity Escalation:Gulf Coast municipalities in the United States are expanding fleet procurement to address intensified hurricane seasons, with FEMA disaster relief funding accelerating replacement cycles for aging truck-mounted loader inventories.
- REACH Particulate Standards:European cities are mandating vacuum loader specifications for urban construction waste removal, creating specification pull for dust-suppression technologies in high-density environments.
- Hydraulic System Maturation:Variable-displacement pump architectures now deliver sufficient torque for wet vegetative debris without diesel auxiliary power, opening electrification pathways previously blocked by performance constraints.
Market Restraints
- Steel Input Volatility:Reinforced bucket fabrication depends on high-yield plate steel grades subject to tariff-driven price swings, compressing margin predictability for equipment manufacturers.
- Certified Operator Scarcity:OSHA heavy equipment certification backlogs in the United States extend deployment timelines by four to eight months, constraining fleet utilization rates for municipal customers.
- Compact Excavator Substitution:Mini-excavator rentals with grapple attachments capture small-scale debris removal contracts at one-third the capital commitment, eroding entry-loader market penetration.
Strategic Opportunities
- Battery-Electric Traction:California Air Resources Board fleet electrification mandates create first-mover advantage for manufacturers delivering validated electric debris loaders before 2027 compliance deadlines.
- Wildland-Urban Interface Expansion:Colorado, Arizona, and Montana municipalities are establishing dedicated fuel reduction crews requiring specialized compact loaders for steep-slope vegetation management.
- Telematics-Enabled Uptime Contracts:Predictive maintenance platforms allow manufacturers to offer guaranteed availability service models, shifting revenue from equipment sale to performance-based subscription.
Industry Challenges
- Electrical Infrastructure Gaps:Rural municipal yards lack three-phase charging capacity for electric loader deployment, requiring parallel utility upgrade negotiations that extend procurement cycles.
- Cross-Manufacturer Control Interface Standardization:Proprietary joystick and display protocols prevent operator transferability across fleet brands, inflating training costs for mixed-vendor municipalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Debris Loaders Market |
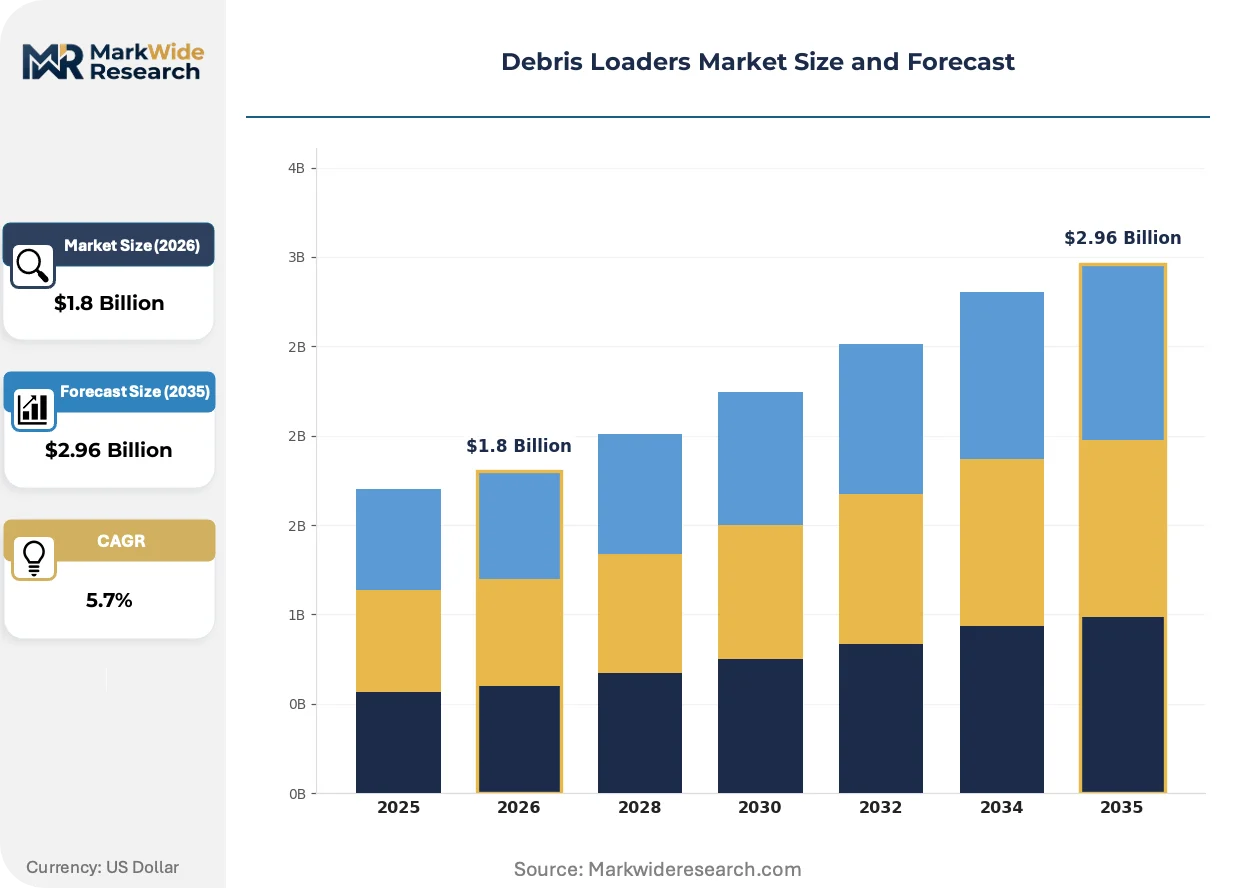
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck-Mounted Loaders, Stand-Alone Loaders, Compact Loaders, High-Performance Loaders End User: Municipalities, Contractors, Landscaping Firms, Waste Management Companies Application: Road Maintenance, Storm Cleanup, Construction Sites, Park Maintenance Technology: Mechanical Loaders, Hydraulic Loaders, Vacuum Loaders, Pneumatic Loaders |
| Companies Covered | Liebherr, XCMG, Caterpillar, Volvo, Hitachi, Komatsu, Terex, JCB, BelAZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debris Loaders Market Emerging Trajectories
Debris loader technology is bifurcating between electrified precision systems for urban corridors and hardened mechanical architectures for extreme weather response, with software-defined controls bridging operational modes.
Brushless permanent-magnet electric traction motors paired with silicon carbide inverters are decomposing the historical diesel-hydraulic monopoly in sub-50-horsepower loader categories. California municipal fleets are piloting these configurations for zero-emission zone compliance. The technology is decomposing traditional powertrain supplier relationships as battery pack integrators capture value previously held by engine manufacturers.
EPA SmartWay equipment certification requirements are extending from transport refrigeration to material handling equipment, mandating verified fuel consumption and idle-time reporting. This creates compliance documentation burdens for smaller rental fleet operators. Waste management companies with centralized telematics infrastructure are capturing specification advantages in RFP evaluations against decentralized municipal fleets.
Municipal procurement officers are consolidating debris loader specifications into multi-year fleet framework agreements, displacing spot-market equipment rental for recurring seasonal demand. National waste service providers with captive maintenance networks are winning these consolidated contracts. This concentration is most visible across Texas and Florida counties where hurricane season predictability justifies owned-fleet economics over emergency rental premiums.
Debris Loaders Market Segmentation
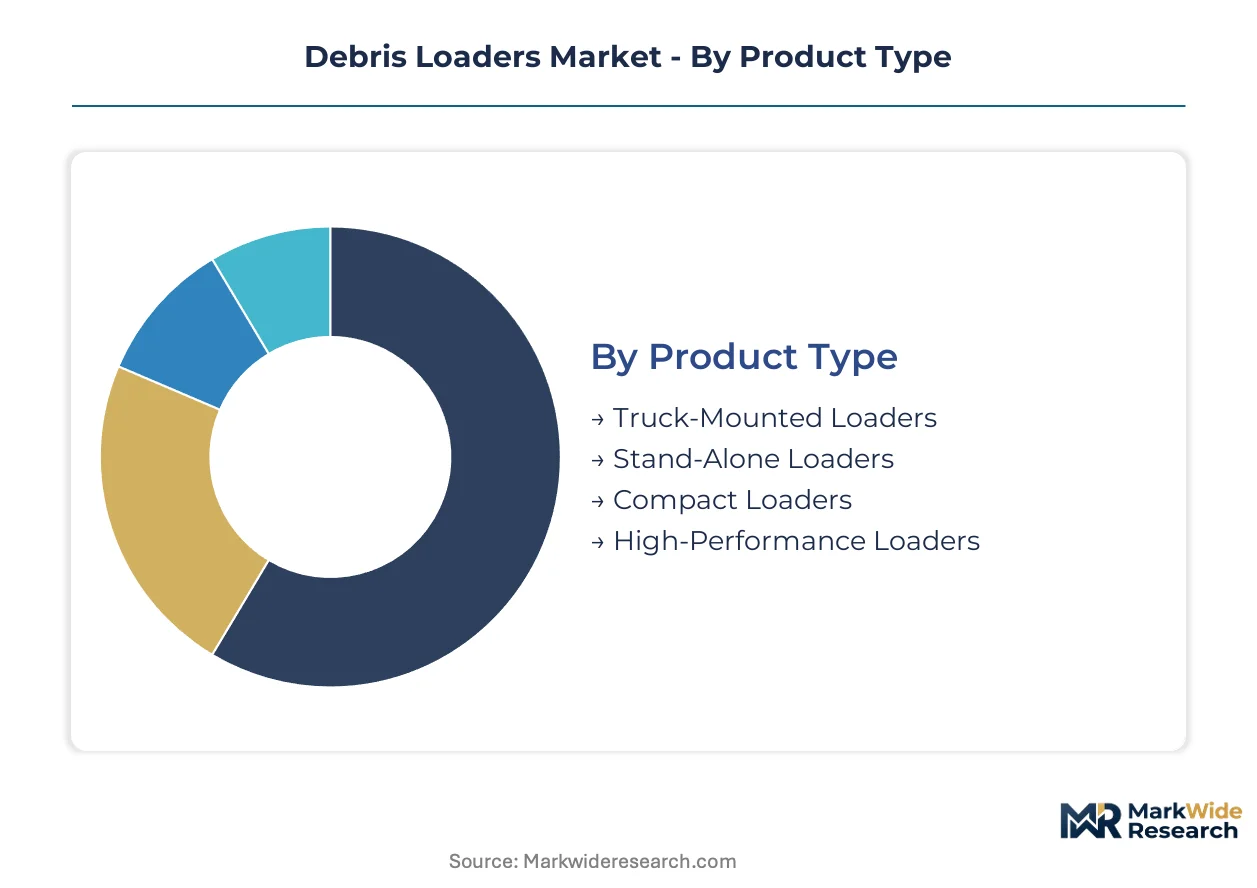
Debris loader procurement patterns diverge sharply across operational contexts, with fleet specifications driven by mobility requirements, debris composition, and regulatory compliance burdens rather than unit economics alone. Understanding these segment boundaries reveals where equipment margins concentrate and which technology substitutions threaten incumbent positions.
Product Type:
Margin pools concentrate in configurations that balance capital efficiency with deployment flexibility, favoring equipment that transitions between routine maintenance and emergency response without reconfiguration.
- Truck-Mounted Loaders:These units integrate chassis-mounted booms with hydraulic lift systems rated for three to five cubic yard bucket capacities, enabling rapid relocation across dispersed municipal service zones. Gulf Coast municipalities in the United States anchor procurement volume, with FEMA disaster relief funding accelerating replacement cycles for aging fleets facing intensified hurricane seasons.
- Stand-Alone Loaders:Fixed-base configurations with dedicated power plants and reinforced undercarriages for continuous-duty material processing. Waste management companies in high-volume vegetative debris corridors capture operational economies that justify premium capital commitments over rental alternatives.
- Compact Loaders:Sub-50-horsepower units with articulated steering for confined urban corridors and steep-slope wildland interface zones.
- High-Performance Loaders:Heavy-duty architectures with hydrostatic drivetrains and reinforced booms for construction rubble and mixed demolition debris.
The dominant share belongs to Truck-Mounted Loaders, while Compact Loaders are closing the gap fastest through wildland-urban interface expansion in Colorado and Arizona.
End User:
Customer-type segmentation tracks procurement authority structures, with centralized fleet managers demanding performance guarantees that fragmented operators cannot underwrite.
- Municipalities:Public works departments with multi-year capital improvement budgets and federal procurement guideline compliance obligations. Texas and Florida counties are consolidating debris loader specifications into framework agreements that displace spot-market rental for recurring seasonal demand.
- Waste Management Companies:National service providers with captive maintenance networks and centralized telematics infrastructure. These operators capture specification advantages in RFP evaluations through guaranteed uptime contracts and predictive maintenance platforms.
- Contractors:Project-based procurement with rental-heavy fleet strategies and limited maintenance capabilities.
- Landscaping Firms:Seasonal demand patterns favoring compact equipment with lower capital thresholds and flexible financing terms.
Municipalities command the largest procurement volume, though Waste Management Companies are expanding share fastest through performance-based subscription models.
Application:
Operational context dictates equipment specifications more sharply than purchase price, with debris composition and environmental exposure driving technology selection.
- Storm Cleanup:Emergency response operations requiring rapid deployment, dust suppression capabilities, and compatibility with federal incident command structures. Gulf Coast states face intensified hurricane seasons that compress procurement timelines and prioritize reliability over efficiency metrics.
- Construction Sites:Continuous-duty material handling with reinforced bucket architectures for mixed demolition debris and aggregate transport.
- Road Maintenance:Routine vegetative debris collection along highway corridors with intermittent usage patterns favoring truck-mounted mobility.
- Park Maintenance:Precision operations in sensitive ecological zones requiring low-ground-pressure configurations and noise restrictions.
Storm Cleanup absorbs the dominant equipment allocation, while Construction Sites are gaining share through urban densification and infrastructure renewal programs.
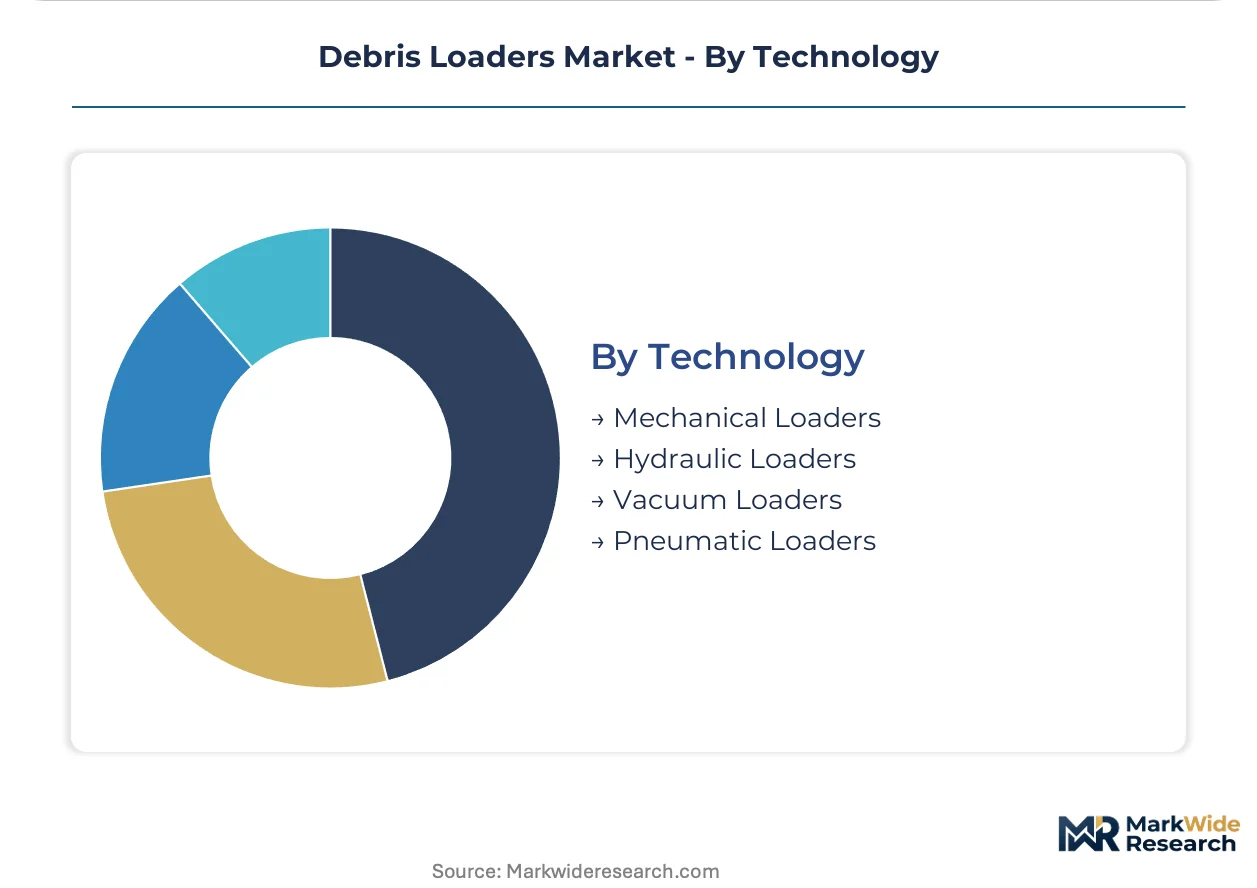
Technology:
Powertrain architecture segmentation reflects regulatory pressure on diesel emissions and the maturation of electrified alternatives in sub-50-horsepower categories.
- Vacuum Loaders:Negative-pressure collection systems with cyclonic separation and HEPA filtration for airborne particulate containment. European cities under REACH particulate standards are mandating these specifications for urban construction waste removal, creating specification pull in high-density environments.
- Hydraulic Loaders:Variable-displacement pump architectures delivering sufficient torque for wet vegetative debris without diesel auxiliary power, opening electrification pathways previously blocked by performance constraints.
- Mechanical Loaders:Direct-drive configurations with lower capital costs but reduced precision control for delicate surface operations.
- Pneumatic Loaders:Compressed-air systems for specialized dry material transport in confined industrial settings with explosion-risk requirements.
Hydraulic Loaders retain the dominant installed base, though Vacuum Loaders are climbing the fastest through European regulatory mandates and urban dust suppression priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions mandates under the Clean Air Act dominate procurement specifications across the United States, the world's largest debris loader market, while European REACH standards and Asian infrastructure programs create parallel regulatory gravity in their respective territories.
United States
Gulf Coast municipalities from Houston to Miami are expanding fleet procurement to address intensified hurricane seasons, with FEMA disaster relief funding accelerating replacement cycles. EPA Tier 4 Final standards compress diesel engine availability while pushing hydraulic and electric alternatives. Texas and Florida counties are consolidating specifications into multi-year framework agreements that displace spot-market rental.
Germany
Industrial machinery demand concentrates in the Ruhr corridor and Bavarian manufacturing zones, where construction waste processing requires precision-engineered hydraulic systems. ECHA REACH particulate standards mandate vacuum loader specifications for urban demolition projects. Stuttgart-based waste management operators are piloting telematics-enabled uptime contracts for municipal fleet modernization.
China
Urban densification in the Yangtze River Delta and Pearl River Delta drives compact loader demand for confined corridor operations. MIIT emission standards and GB certification requirements shape domestic manufacturing specifications. XCMG anchors production scale in Xuzhou, supplying belt-and-road infrastructure projects across Southeast Asia with cost-optimized mechanical configurations.
Japan
Precision manufacturing clusters in Aichi Prefecture and the Kansai region demand compact loaders for delicate surface operations in sensitive ecological zones. METI energy efficiency directives accelerate electrification pathways in sub-50-horsepower categories. Komatsu leverages Nagano engineering expertise to integrate variable-displacement pump architectures for wet vegetative debris handling.
Australia
Mining-adjacent communities in Western Australia and Queensland require hardened mechanical architectures for extreme weather response and bulk material processing. State-level environmental protection agencies enforce dust suppression mandates for construction waste removal. Brisbane-based contractors are consolidating procurement through national rental networks with captive maintenance capabilities.
Debris Loaders Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the debris loader market. The vendor base organizes into three tiers: diversified heavy equipment conglomerates with full-category manufacturing scale, specialized hydraulic system integrators, and regional fabricators serving price-sensitive municipal segments. Consolidation pressure concentrates among premium-tier manufacturers seeking guaranteed uptime service models, while entry-loader positions fragment across rental-heavy contractor markets. Dominant competitive moves include backward integration into battery pack assembly for electrified product lines and strategic partnerships with telematics platform providers.
Among diversified heavy equipment conglomerates, Caterpillar and Volvo exemplify scale-driven archetypes with multi-category manufacturing footprints and dealer network control. Komatsu occupies a position within the specialized hydraulic integration tier, differentiating through high-moisture debris performance. XCMG represents the regional fabricator archetype, anchoring cost-optimized production for price-sensitive procurement in emerging infrastructure markets. These three patterns—scale dominance, technical specialization, and manufacturing cost leadership—structure competitive positioning across municipal, waste management, and contractor end-user segments.
| Leading Market Players |
|---|
| Liebherr |
| XCMG |
| Caterpillar |
| Volvo |
| Hitachi |
| Komatsu |
| Terex |
| JCB |
| BelAZ |
| Others |
Supply Flow & Price Mechanics
Multi-year framework agreements with guaranteed uptime clauses lock in supply access for Gulf Coast municipalities while compressing price visibility for spot-market rental operators facing hurricane-season demand spikes. These contracts tether equipment availability to performance metrics, shifting procurement economics from capital expenditure to operational subscription models across Texas and Florida counties.
Pricing Analysis
Texas municipalities pay 15-25% premiums over Midwestern equivalents for identical truck-mounted loader specifications due to storm-season urgency and FEMA reimbursement structures. Three-tier pricing structure across premium, standard, and economy levels separates waste management companies with captive maintenance networks from contractor rental fleets and municipal spot buyers. Pricing pressure stems from compact excavator rentals capturing small-scale debris contracts at lower capital thresholds. Municipal procurement officers exhibit lowest price sensitivity due to federal disaster relief funding, while landscaping firms face acute margin constraints.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Long Beach have compressed margin predictability for steel-intensive bucket fabrication, with container availability fluctuations extending component lead times. Manufacturing concentrates in China, Japan, and Germany, with XCMG anchoring cost-optimized mechanical configurations and Komatsu feeding precision hydraulic systems. High-yield plate steel grades, silicon carbide inverters, and battery pack assemblies constitute critical input dependencies. Single-source vulnerability runs through Taiwanese semiconductor suppliers for telematics control modules. Distribution runs through dealer networks with captive service capabilities rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics platform interoperability is transforming debris loader procurement into an ecosystem play where guaranteed uptime contracts displace equipment ownership, with predictive maintenance APIs enabling cross-manufacturer fleet management.
For Market Incumbents: Secure backward integration into battery pack assembly for electrified product lines before California Air Resources Board mandates take effect. Deepen channel control through exclusive service agreements with Gulf Coast municipal fleets facing intensified hurricane seasons. Counter compact excavator substitution by bundling precision attachments with truck-mounted loader leases.
For New Entrants and Emerging Players: Lead with wildland-urban interface applications in Colorado and Arizona municipalities establishing dedicated fuel reduction crews, where steep-slope vegetation management demands specialized compact configurations. Target vacuum loader specifications for European cities under REACH particulate standards. Pursue telematics platform partnerships rather than proprietary hardware development to accelerate time-to-revenue.
For Investors and Strategic Acquirers: Capital is best deployed toward hydraulic system integrators with demonstrated wet vegetative debris performance and established relationships with national waste management providers. Long-term viability hinges on electrification readiness and software-defined control architectures. Monitor California fleet electrification compliance deadlines as inflection indicators for technology substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Product Validation | California Air Resources Board mandates create first-mover advantage for compliant manufacturers. |
| Telematics Platform Integration | Predictive maintenance APIs enable guaranteed uptime contracts shifting revenue to subscriptions. |
| Backward Integration into Battery Assembly | In-house production of powertrains captures value previously held by diesel engine suppliers. |
| Wildland-Urban Interface Specialization | Colorado and Arizona fuel reduction crews require compact loaders for steep-slope operations. |
| Dealer Network Expansion | Channel control secures fleet replacement cycles in coastal municipalities with FEMA funding. |
Methodological Framework
Operator-level perspectives from municipal fleet managers, waste management procurement directors, heavy equipment maintenance supervisors, and certified operator training coordinators anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through EPA emission certification databases, OSHA workplace safety directives, FEMA disaster relief procurement records, and equipment registration data from state-level transportation departments. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, application, and technology segmentation dimensions.
Sensitivity analysis tested forecast robustness against steel price volatility, certified operator availability constraints, and electrification compliance timeline variations across the projection horizon. The analytical framework modeled truck-mounted versus stand-alone configurations, municipal versus waste management company procurement authority, storm cleanup versus construction site application intensity, and hydraulic versus vacuum technology adoption curves. CAGRs derived from equipment replacement cycle analysis, federal funding authorization patterns, and regulatory mandate phase-in schedules.
Forecasts assume regulatory continuity in EPA Tier 4 Final and California Air Resources Board regimes; material policy shifts would require re-modeling. Hurricane season intensity trajectories and steel tariff structures constitute primary forecast risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Industrial Parts Feeders Market