
 North America Forklift Market | 2026-2036
North America Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
North America Forklift Market Outlook
Midwestern industrial equipment manufacturing capacity is hardening as domestic supply chains rebuild following pandemic-era disruptions. Toyota Material Handling North America leverages its vertically integrated production network to control lead times across the region. Crown Equipment Corporation specializes in narrow-aisle electric designs that dominate high-density warehousing applications. Hyster-Yale, Inc. sustains a broad portfolio spanning internal combustion and emerging hydrogen fuel cell platforms.
A forklift is a powered industrial truck featuring hydraulically actuated vertical masts with load capacities typically ranging from 3,000 to 70,000 pounds, designed primarily for lifting, transporting, and stacking materials within confined operational envelopes. Electric forklifts now lead product type dynamics as lithium-ion battery chemistry eliminates traditional lead-acid maintenance burdens and enables opportunity charging during shift breaks. Warehousing end users represent the fastest-expanding demand pool, driven by omnichannel distribution center buildouts and same-day delivery service level commitments that require higher fleet utilization rates.
OSHA enforces operator certification and workplace design standards that directly shape fleet procurement specifications and facility layout requirements across United States operations. EPA Tier 4 Final emissions regulations constrain diesel forklift deployments in indoor and mixed-use environments, accelerating electric conversion timelines. Canada's CSA B335 safety standard and Mexico's NOM operational codes create additional compliance layers for cross-border fleet standardization. Stakeholders must monitor hydrogen infrastructure buildout velocity and battery recycling policy development to time capital deployment decisions effectively.
Market Dynamics
Lithium-ion battery chemistry is compressing fleet replacement cycles as e-commerce fulfillment operators abandon lead-acid maintenance burdens for opportunity-charging architectures.
Growth Catalysts
- OSHA workplace safety mandates:Operator certification requirements and facility design standards are forcing warehouse operators toward electric fleets with enhanced stability controls and collision avoidance systems.
- E-commerce fulfillment buildouts:Omnichannel distribution centers across the Great Lakes corridor are driving demand for narrow-aisle designs that maximize cubic storage density.
- EPA Tier 4 Final emissions constraints:Diesel forklift deployments face operational restrictions in mixed-use environments, accelerating electric conversion timelines among indoor logistics operators.
Market Restraints
- Lithium supply concentration:Cathode material dependencies on concentrated upstream processing create input cost volatility for domestic battery pack assembly.
- Hydrogen infrastructure gaps:Fuel cell forklift adoption remains constrained by limited refueling station networks and uneven regional distribution of green hydrogen production capacity.
- Skilled technician shortages:High-voltage battery maintenance and fuel cell system diagnostics require specialized training that outpaces current vocational program output.
Strategic Opportunities
- Mexico nearshoring corridors:Manufacturing relocation from Asia is creating greenfield warehouse demand in Nuevo León and Baja California for standardized fleet deployments.
- Battery recycling policy development:Emerging extended producer responsibility frameworks in California and Canada are creating closed-loop service revenue streams for OEMs.
- Telematics-ERP convergence:Integration of fleet management platforms with warehouse management systems enables predictive maintenance contracts that shift revenue toward recurring service models.
Industry Challenges
- Cross-border certification complexity:CSA B335, OSHA 1910.178, and NOM operational code misalignment forces multinational operators to maintain fragmented training and inspection protocols.
- Legacy fleet integration friction:Retrofitting existing facilities with lithium-ion charging infrastructure requires electrical upgrades that compress project timelines and capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Forklift Market |
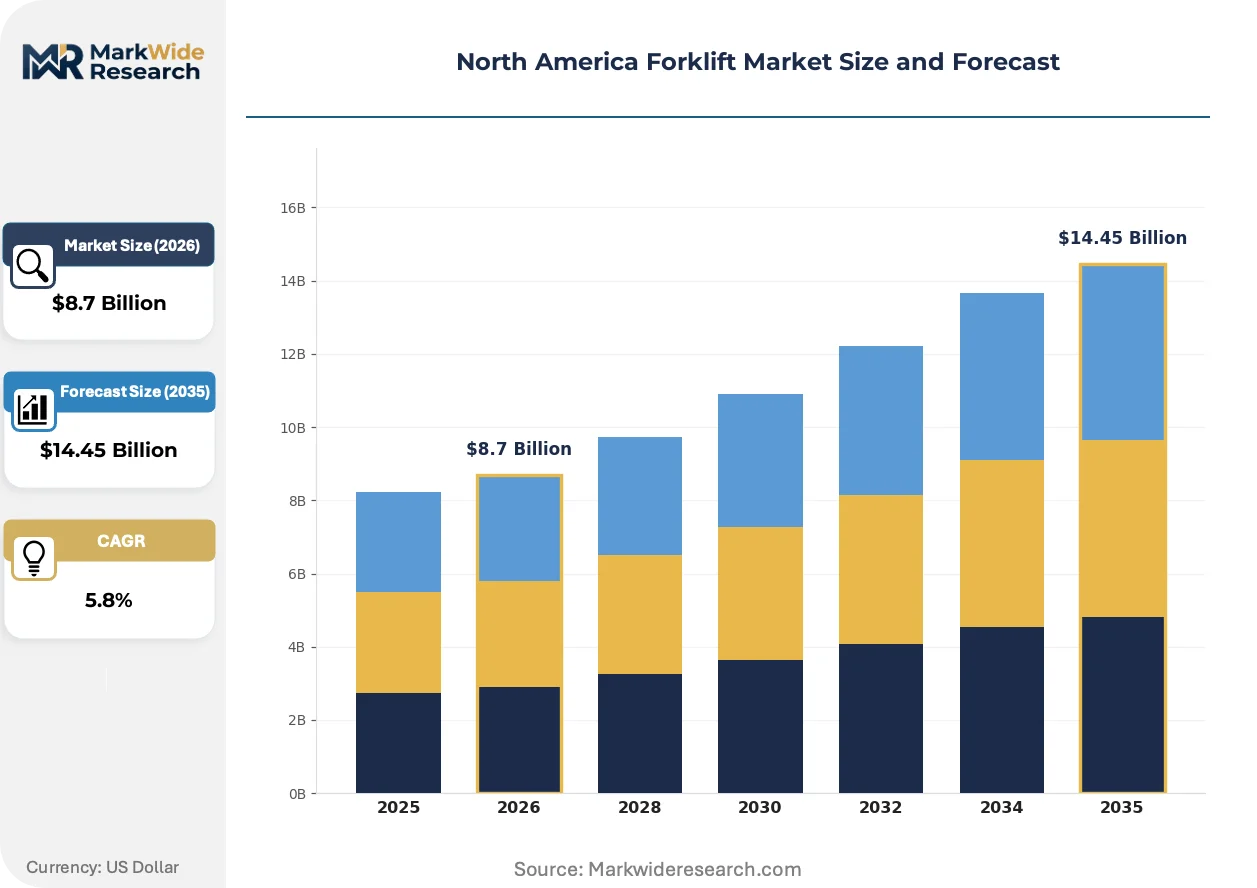
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Diesel Forklifts, LPG Forklifts, Hydraulic Forklifts End User: Warehousing, Manufacturing, Retail, Construction Application: Material Handling, Loading/Unloading, Inventory Management, Order Picking Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | Toyota Material Handling North America, Crown Equipment Corporation, Hyster-Yale, Inc., KION Group AG, Jungheinrich AG, Caterpillar Inc., Doosan Bobcat North America Inc., Mitsubishi Logisnext Co., Ltd., Raymond Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Forklift Market Strategic Shifts
Automation readiness is reshaping procurement specifications as warehouse operators specify forklifts with pre-integrated sensor architectures for future autonomous retrofit.
Lithium-ion phosphate battery packs are overtaking traditional lead-acid systems in three-shift operations. Food and beverage cold storage facilities in the Midwest are adopting these configurations fastest due to elimination of battery changing rooms and reduced ventilation requirements. This chemistry is overtaking incumbent power systems by enabling continuous operation without dedicated battery swap infrastructure.
EPA enforcement of Tier 4 Final emissions in California and the Northeast corridor is constraining diesel forklift registrations for indoor applications. Industrial equipment lessors are accelerating electric fleet rotations to avoid stranded asset risk in regulated jurisdictions. Material handling operators in Michigan and Ohio are responding by consolidating procurement specifications around zero-emission platforms.
Full-service lease structures are displacing traditional capital purchase models among mid-market warehousing operators. Third-party logistics providers in Illinois and Pennsylvania are unbundling maintenance from equipment financing to preserve balance sheet flexibility. This shift is most visible among regional distributors serving grocery and pharmaceutical verticals with seasonal volume volatility.
North America Forklift Market Segmentation
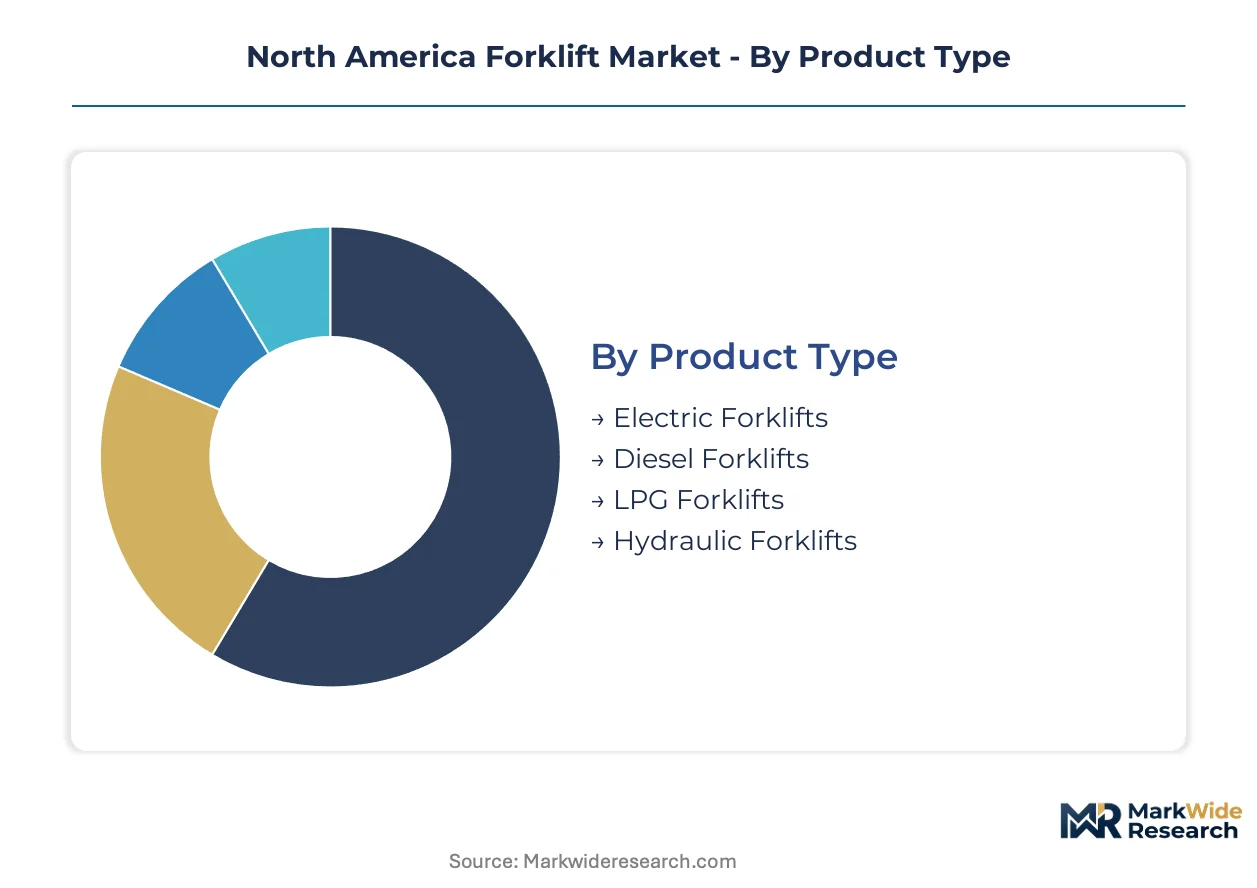
Fleet procurement specifications diverge sharply across operational contexts in the North America Forklift Market. Equipment buyers calibrate powertrain selection, mast configuration, and financing structure against duty cycles, facility constraints, and regulatory exposure.
Product Type:
Replacement-cycle timing separates winners as lithium-ion chemistry compresses payback periods against legacy lead-acid infrastructure.
- Electric Forklifts:Lithium-ion phosphate battery packs deliver continuous operation across three-shift warehousing without dedicated battery swap rooms. Demand concentrates in Michigan and Ohio cold storage facilities where ventilation reduction and opportunity charging during breaks eliminate downtime.
- Diesel Forklifts:Internal combustion platforms with Tier 4 Final aftertreatment retain dominance in outdoor yard operations and heavy-capacity applications exceeding 15,000 pounds. EPA enforcement in California and the Northeast corridor is accelerating fleet rotation toward zero-emission alternatives in mixed-use environments.
- LPG Forklifts:Liquid petroleum gas systems bridge indoor-outdoor flexibility for construction and seasonal retail operations lacking electrical infrastructure.
- Hydraulic Forklifts:Specialized high-lift configurations serve port and intermodal container handling with extended mast reach.
Volume placements concentrate in Electric Forklifts; the faster expansion belongs to lithium-ion variants displacing lead-acid across three-shift operations.
End User:
Customer scale and utilization intensity create divergent procurement economics across operational archetypes.
- Warehousing:Omnichannel distribution centers in Illinois and Pennsylvania drive narrow-aisle specification dominance. Same-day delivery service level commitments force fleet utilization rates above 85 percent, compressing replacement cycles to 5-7 years.
- Manufacturing:Automotive and industrial equipment producers in the Great Lakes corridor specify ruggedized chassis for just-in-time component sequencing. OSHA 1910.178 compliance mandates shape operator training and inspection protocol investments.
- Retail:Big-box and grocery chains prioritize maneuverability for seasonal volume spikes with lease structures preserving balance sheet flexibility.
- Construction:Rough-terrain and telehandler variants serve project-based demand with rental-heavy procurement patterns.
Warehousing generates the steepest unit expansion trajectory; Manufacturing retains the largest installed base requiring systematic replacement.
Application:
Task-specific duty cycles determine mast geometry, attachment configuration, and telematics integration requirements.
- Material Handling:Horizontal transport and vertical stacking across manufacturing floors and distribution centers. Food and beverage facilities in the Midwest specify stainless steel cladding for washdown compliance.
- Loading/Unloading:Dock-to-trailer operations demand tight turning radius and gradeability for yard ramps. Third-party logistics providers in Nuevo León nearshoring corridors standardize on electric pneumatic designs.
- Inventory Management:Cycle counting and put-away workflows integrate RFID and warehouse management system connectivity.
- Order Picking:Low-level and high-level picker configurations serve e-commerce fulfillment with operator elevation for dense rack systems.
Material Handling accounts for the dominant share of fleet hours; Order Picking is climbing the fastest as SKU proliferation drives piece-pick automation.
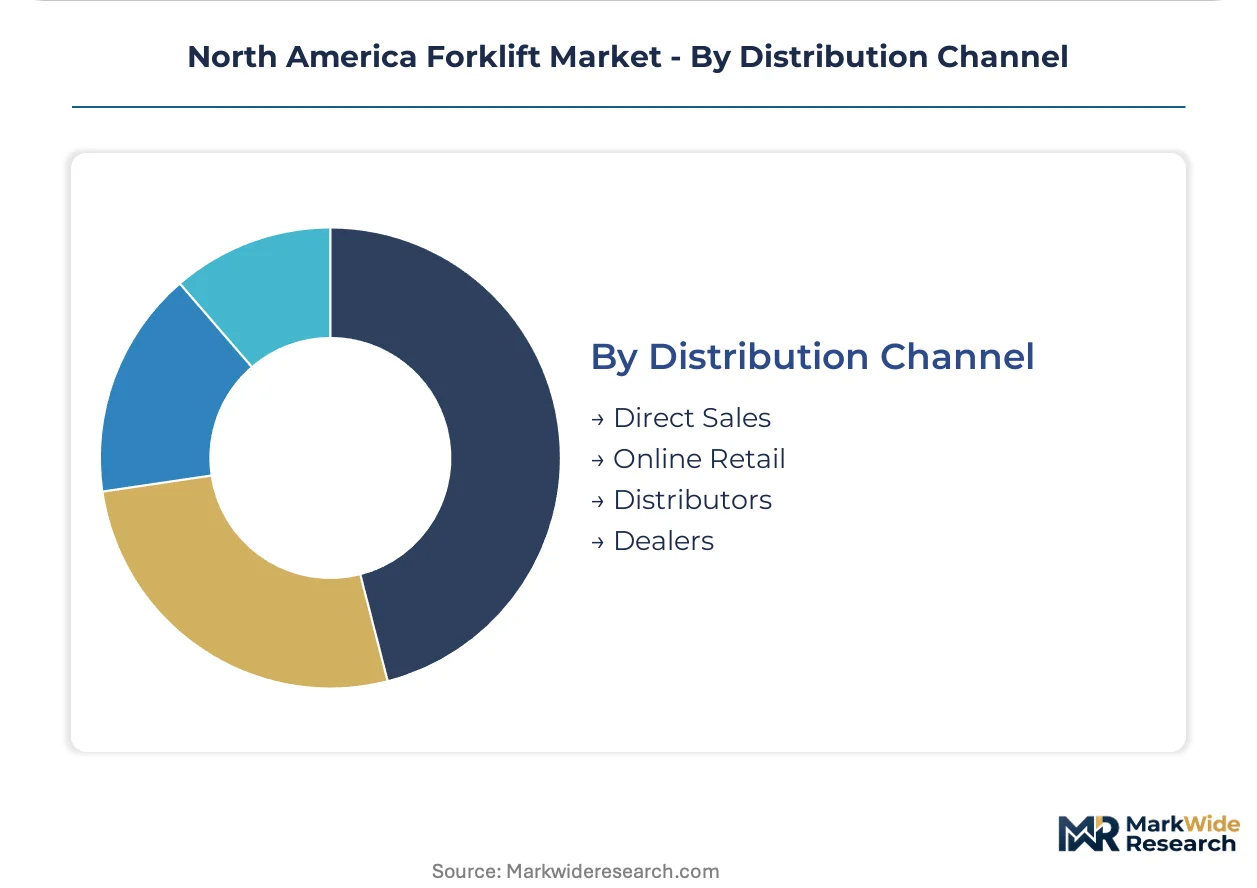
Distribution Channel:
Customer sophistication and fleet scale determine channel preference and contract structure complexity.
- Direct Sales:National accounts and large warehousing operators negotiate enterprise-wide fleet management agreements with embedded maintenance and telematics. Toyota Material Handling North America and Crown Equipment Corporation field dedicated account teams for multi-site standardization.
- Distributors:Regional material handling specialists serve mid-market manufacturing with localized service response and parts availability. Illinois and Ohio distributors consolidate procurement specifications around zero-emission platforms to align with customer sustainability mandates.
- Dealers:Independent dealer networks cover construction and seasonal retail segments with rental and short-term lease flexibility.
- Online Retail:Digital procurement platforms capture small fleet and replacement unit transactions with standardized configuration and expedited delivery.
Direct Sales captures the highest contract value concentration; Distributors are gaining share fastest among mid-market warehousing operators seeking localized service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Nevada's Thacker Pass and Quebec's James Bay region anchor North American battery supply chain ambitions. These upstream resource nodes feed cathode material processing facilities in Ontario and Kentucky. Regional demand clusters concentrate where automotive manufacturing corridors intersect with e-commerce distribution networks.
United States
Great Lakes manufacturing states drive fleet replacement intensity. OSHA 1910.178 mandates operator certification and facility design standards that accelerate electric conversion timelines. Michigan's automotive component suppliers and Ohio's cold storage facilities standardize on lithium-ion configurations to eliminate battery swap infrastructure.
Canada
Ontario's warehousing sector and Quebec's mining logistics operations generate concentrated equipment demand. CSA B335 safety standards create certification complexity for cross-border fleet operators. Toronto-Waterloo corridor distribution centers adopt narrow-aisle electric designs for cubic density optimization.
Mexico
Nuevo León nearshoring corridors and Baja California manufacturing parks attract greenfield warehouse investment. NOM operational codes govern forklift deployment in industrial zones. Monterrey logistics hubs standardize fleet specifications for multinational operators seeking supply chain continuity.
North America Forklift Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hydrogen fuel cell integration and telematics-enabled service models. The vendor base stratifies across three tiers: integrated manufacturers with captive battery supply, specialized narrow-aisle designers, and diversified industrial conglomerates with material handling divisions. Strategic moves concentrate on fleet management platform acquisitions and lithium-ion battery pack assembly partnerships.
Within the integrated manufacturing tier, Toyota Material Handling North America and Crown Equipment Corporation exemplify vertical production control over lead times and configuration flexibility. Hyster-Yale, Inc. anchors the diversified portfolio archetype spanning internal combustion and emerging alternative powertrains. These three entities represent distinct competitive positioning strategies: geographic production network density, application-specific design specialization, and broad technology platform coverage.
| Leading Market Players |
|---|
| Toyota Material Handling North America |
| Crown Equipment Corporation |
| Hyster-Yale, Inc. |
| KION Group AG |
| Jungheinrich AG |
| Caterpillar Inc. |
| Doosan Bobcat North America Inc. |
| Mitsubishi Logisnext Co., Ltd. |
| Raymond Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists anchor the North American forklift supply base, translating generational balance sheet discipline into stable pricing architectures that resist cyclical discounting. Their captive service networks bundle maintenance contracts with equipment financing, creating switching costs that protect margin structures even when lithium-ion battery cost volatility pressures upstream component economics.
Pricing Analysis
Warranty and service bundling separates capital purchase quotations from full-service lease structures, with unbundled maintenance contracts commanding premium rates for high-utilization warehousing fleets. Three-tier pricing structure across premium, standard, and economy levels reflects lithium-ion battery capacity, mast reach configuration, and telematics integration depth. Cost compression in the economy tier is intensifying because lead-acid forklift lessors liquidate aging inventory ahead of EPA enforcement timelines. Small fleet operators in seasonal retail applications exhibit the highest price sensitivity, while national third-party logistics providers with 85 percent utilization rates prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Ontario, Kentucky, and Nevada form a hub-and-spoke pattern that positions finished equipment within 48-hour delivery windows of Great Lakes manufacturing clusters. Cathode active material processing draws from concentrated upstream capacity in China, South Korea, and emerging domestic facilities at Thacker Pass. Single-source vulnerability in lithium hydroxide refining creates input cost volatility that feeds through to battery pack assembly. Distribution runs through manufacturer-direct account teams for national warehousing operators and regional distributor networks for mid-market manufacturing customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
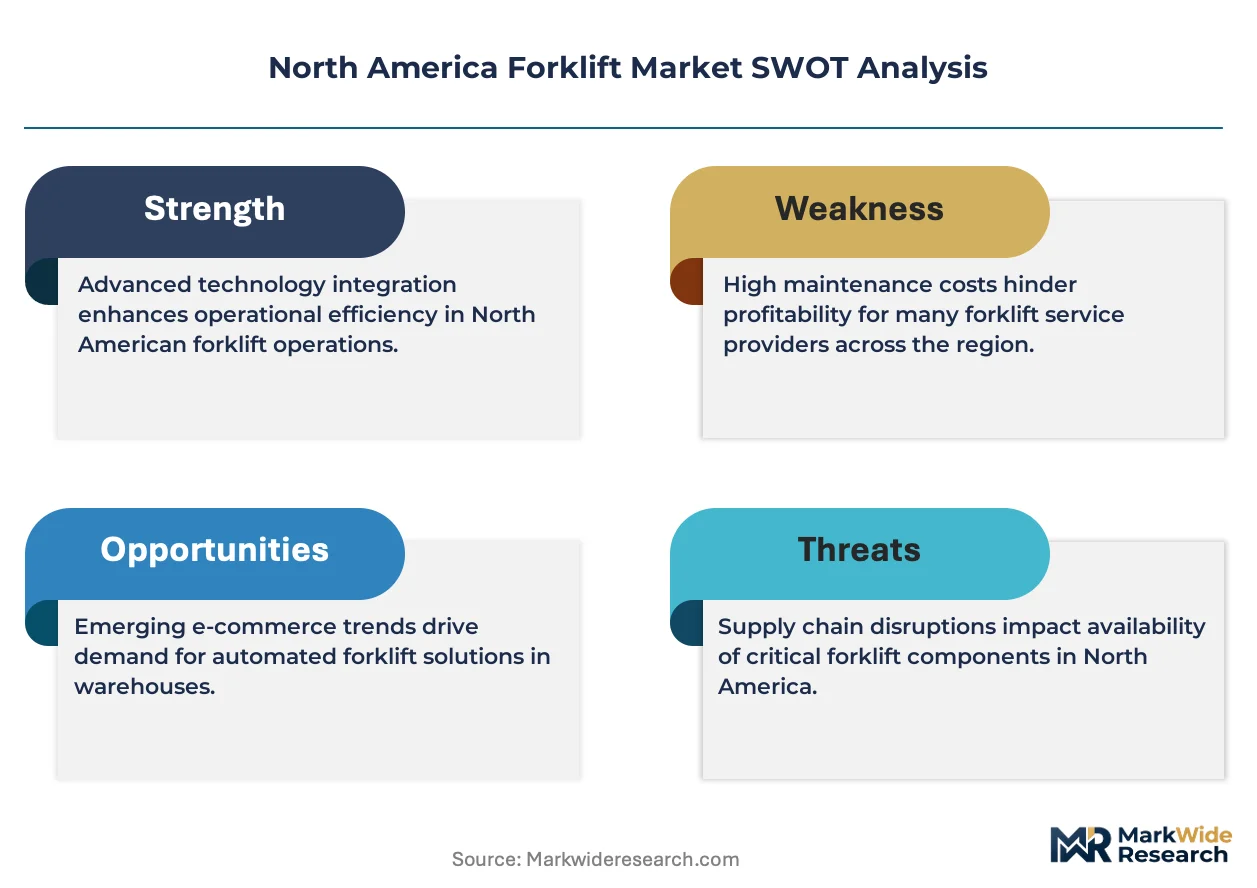
The North America forklift market functions as a vertical-integration race where captive lithium-ion battery pack assembly determines lead-time competitiveness and configuration flexibility. Players are pursuing upstream control over cathode material processing to decouple from concentrated Asian supply.
For Market Incumbents: Deploy telematics platform acquisitions to capture recurring service revenue and lock out aftermarket competitors. Consolidate procurement specifications around zero-emission platforms to align with customer sustainability mandates and preempt stranded asset risk from EPA Tier 4 Final enforcement. Capacity addition in Kentucky and Ontario battery assembly facilities will defend margin position against emerging hydrogen fuel cell entrants.
For New Entrants and Emerging Players: EPA Tier 4 Final emissions constraints in California and the Northeast corridor open a window for electric forklift specialists to capture diesel displacement demand. Mexico nearshoring corridors in Nuevo León present the most penetrable geography, with greenfield warehouse operators seeking standardized fleet deployments without legacy infrastructure entanglements. Pursue battery recycling service contracts as the go-to-market angle, leveraging emerging extended producer responsibility frameworks in California and Canada.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with established service technician benches in the Great Lakes corridor, where skilled labor shortages create defensive moats. Long-term viability over a decade horizon hinges on lithium-ion chemistry dominance versus hydrogen fuel cell disruption. Monitor hydrogen infrastructure buildout velocity in California as the inflection indicator for capital reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Pack Assembly Partnership | Cathode material supply agreements with Nevada and Quebec mining operations secure upstream lithium access. |
| Telematics Platform Acquisition | Fleet management software integration with warehouse management systems enables predictive maintenance contracts. |
| Service Network Expansion | Technician training programs in Michigan and Ohio address high-voltage battery maintenance skill gaps. |
| Hydrogen Fuel Cell Pilot | Green hydrogen production partnerships in California test zero-emission alternatives for heavy-capacity applications. |
| Battery Recycling Infrastructure | Closed-loop service facilities in Ontario and Kentucky capture emerging extended producer responsibility revenue streams. |
Study Parameters
Multi-period observation of fleet replacement cycles, lithium-ion battery cost curves, and EPA enforcement patterns anchored the trend analysis, supplemented by interviews with maintenance directors at automotive component suppliers, plant engineers at cold storage facilities, OEM procurement teams at material handling distributors, and aftermarket service heads at regional equipment lessors. Secondary validation drew from OSHA 1910.178 compliance filings, EPA Tier 4 Final registration databases, CSA B335 safety standard documentation, and customs records of lithium compound imports. Bottom-up unit shipment modeling triangulated against top-down manufacturing capacity assessments.
Segment-weighting applied differential growth assumptions across powertrain types, end-use industries, and application contexts throughout the forecast period. The analytical framework modeled electric, diesel, LPG, and hydrogen fuel cell forklift demand separately, with lithium-ion and lead-acid battery chemistries disaggregated within the electric category. CAGRs were derived from replacement cycle compression rates and e-commerce fulfillment center buildout trajectories. Industry-specific forecast inputs included OSHA operator certification mandates and hydrogen refueling station deployment timelines.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell integration would alter the outlook if green hydrogen production scales faster than projected. Forecasts reflect documented assumptions about lithium supply chain localization and battery recycling policy development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Truck Mounted Loader Cranes Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Precision Gearbox Machinery Market