
 Carry Deck Crane Market | 2026-2036
Carry Deck Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Carry Deck Crane Market Analysis
The capital-intensity gap between full-line manufacturers and niche assemblers is collapsing as Tier 4 engine compliance costs reshape the competitive floor. Terex Corporation leverages its vertically integrated boom fabrication to sustain margin discipline across mid-capacity classes. Broderson Manufacturing anchors its position through dedicated production of compact carry deck units for refinery maintenance. XCMG Group competes on scaled output from its Chinese manufacturing base, though North American certification remains a hurdle.
A carry deck crane is a compact, self-propelled lifting machine featuring a rotating boom mounted on a deck with four-wheel steering, typically rated between 5 and 25 tons, designed for maneuvering in confined industrial spaces such as petrochemical facilities and manufacturing floors. Its primary purpose centers on material handling, equipment installation, and maintenance operations where overhead clearance restrictions and tight turning radii exclude larger all-terrain or crawler alternatives. Hydraulic systems dominate current fleet composition due to proven load control and aftermarket parts availability, while electric and hybrid configurations are gaining traction in indoor warehousing and food-processing environments where emissions restrictions apply. The 15-ton and 20-ton capacity bands capture the majority of rental revenue as infrastructure owners standardize around single-machine flexibility for diverse lift profiles.
OSHA crane operator certification requirements and EPA Tier 4 Final emissions standards collectively elevate replacement demand across aging diesel fleets in the United States. The American Society of Mechanical Engineers B30.5 mobile crane standard shapes load chart validation and structural inspection protocols that manufacturers must satisfy for commercial insurance acceptance. Stakeholders should monitor state-level prevailing-wage legislation and utility rebate programs for electric material handling equipment, as these will determine regional payback periods for hybrid fleet conversions.
Market Dynamics
EPA Tier 4 Final emissions compliance is compressing replacement cycles across diesel-powered carry deck fleets while simultaneously elevating the capital threshold for fleet ownership, forcing rental houses toward hybrid-electric configurations.
Growth Catalysts
- Refinery Turnaround Cycles:Scheduled maintenance at Gulf Coast petrochemical facilities is extending rental utilization windows for compact lifting equipment in Texas and Louisiana.
- OSHA Crane Operator Certification:Federal mandates for qualified operator documentation are accelerating fleet turnover as owners retire non-compliant units rather than retrain personnel.
- Dual-Fuel Hydraulic Systems:Diesel-electric hybrid powertrains are penetrating indoor manufacturing environments where emissions restrictions previously excluded internal combustion equipment.
Market Restraints
- Engine Cost Concentration:Tier 4-compliant diesel powerplants from Cummins and Perkins now represent 35-40% of total machine cost, squeezing assembler margins.
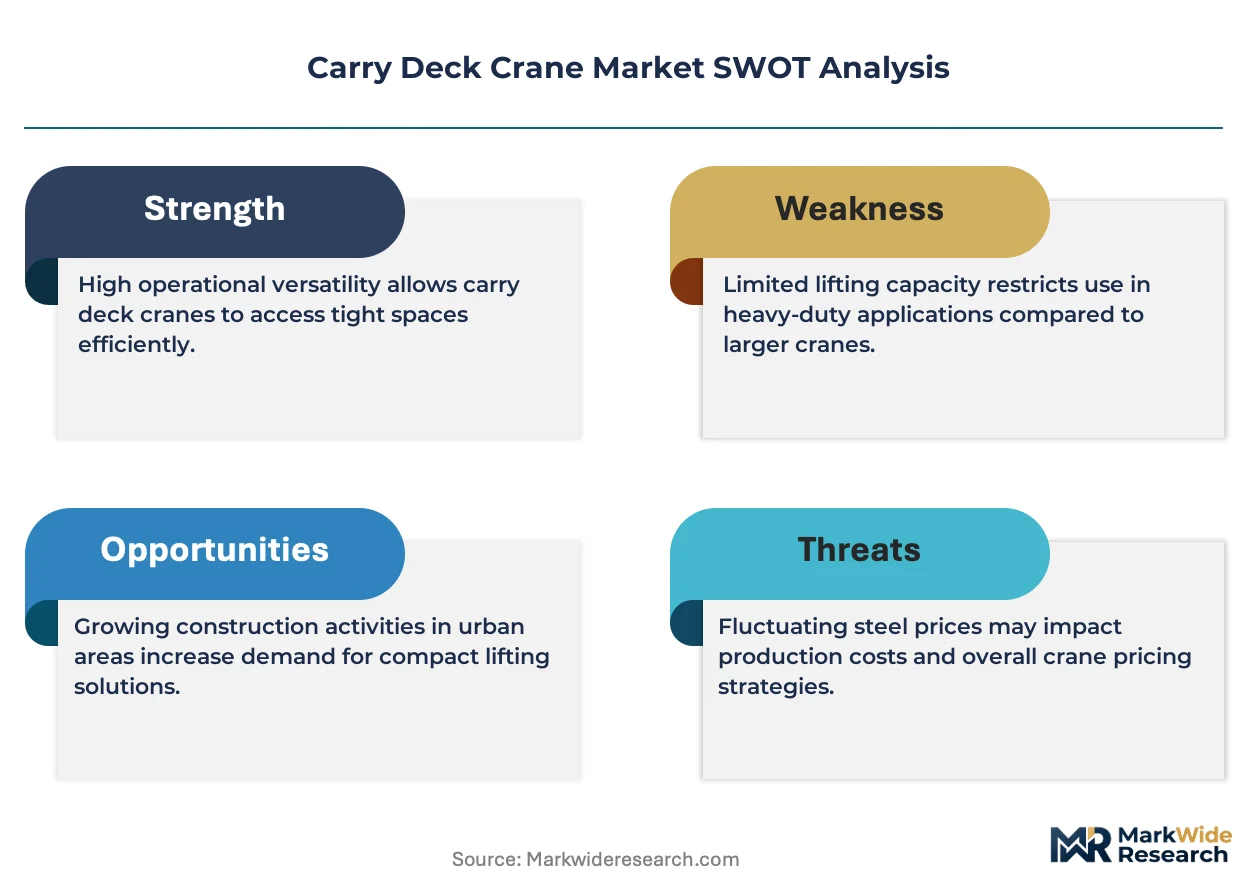
- Steel Input Volatility:Boom fabrication relies on high-strength alloy plate subject to tariff-adjusted pricing swings from domestic mill capacity constraints.
- Certification Bottleneck:Chinese manufacturers face 18-24 month delays securing ANSI B30.5 validation for North American commercial insurance acceptance.
Strategic Opportunities
- Utility Electrification Rebates:State-level incentive programs in California and New York are shortening payback periods for battery-electric fleet conversions in warehousing applications.
- Food-Processing Indoor Lifts:Zero-emission carry deck units are penetrating USDA-inspected facilities where propane and diesel bans are expanding.
- Telematics-Enabled Rental Models:Usage-based billing platforms are displacing fixed-term contracts in municipal infrastructure maintenance departments.
Industry Challenges
- Certified Operator Scarcity:NCCCO-accredited crane operators command 25-30% wage premiums in tight labor markets, inflating total cost of ownership for self-operated fleets.
- Legacy Fleet Integration:Tier 4 Final machines require ultra-low sulfur diesel infrastructure that many remote industrial sites lack, complicating deployment logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carry Deck Crane Market |
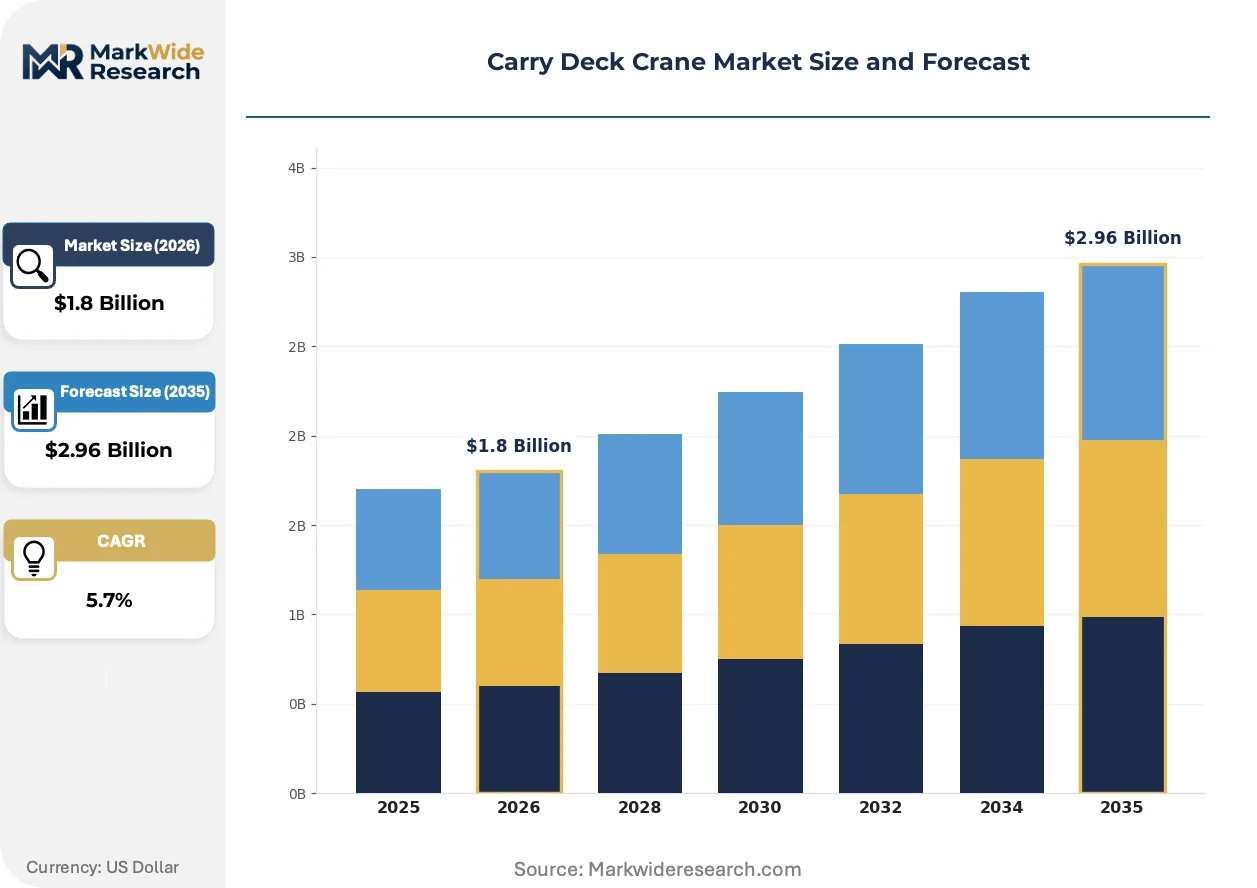
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Diesel, Hybrid End User: Construction, Manufacturing, Warehousing, Marine Capacity: 5 Ton, 10 Ton, 15 Ton, 20 Ton Installation: Fixed, Portable, Customized, Temporary |
| Companies Covered | Terex Corporation, XCMG Group, Liebherr Group, Broderson Manufacturing, Kobelco Construction Machinery, Manitowoc Cranes, Sany Group, Shuttlelift, Tadano Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carry Deck Crane Market Emerging Trajectories
Electrification architectures and predictive maintenance platforms are rewriting equipment economics for compact industrial cranes. These shifts compress capital recovery timelines while expanding addressable use cases beyond traditional petrochemical maintenance.
Lithium-ion battery packs paired with onboard regenerative braking are displacing conventional diesel-hydraulic powertrains in 8-15 ton capacity bands. Food-processing facilities in California and Pacific Northwest states are specifying these configurations to satisfy indoor air quality mandates. The displacement is compressing residual values for Tier 3 diesel inventory and accelerating write-downs across rental house balance sheets.
EPA enforcement of Tier 4 Final standards for non-road diesel engines is eliminating grandfathering provisions that previously shielded older fleet units. Refinery operators in Texas and Louisiana now face inspection-triggered replacement requirements that override historical run-to-failure maintenance philosophies. The regulatory pressure is elevating demand for certified remanufactured powertrains as a bridge compliance strategy.
Rental customers are unbundling operator services from equipment contracts, preferring to source NCCCO-certified personnel independently. This pattern concentrates pricing power with specialized labor brokers and compresses margins for full-service rental providers. The shift is most pronounced in Gulf Coast petrochemical corridors where prevailing-wage legislation inflates operator costs.
Carry Deck Crane Market Segmentation
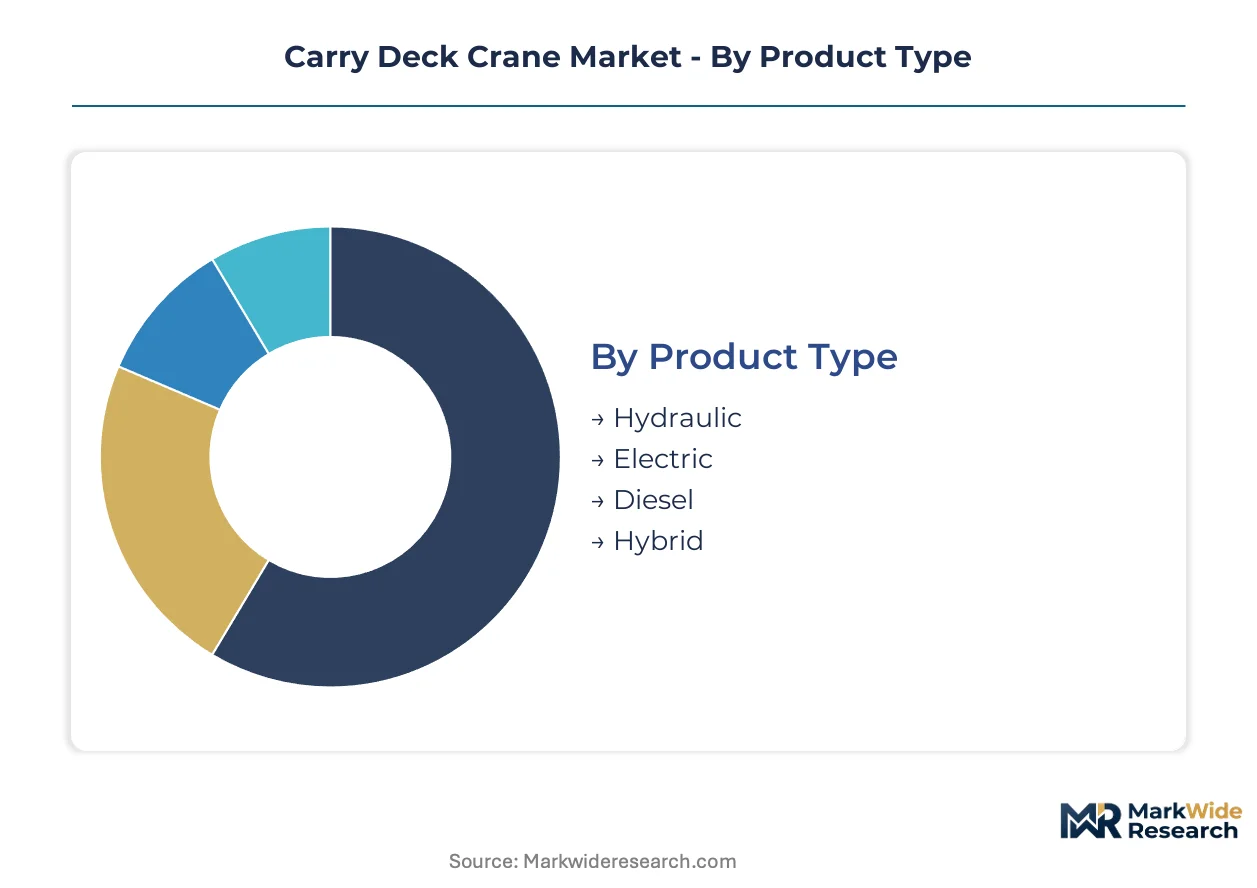
Segmentation in the carry deck crane market reveals how powertrain technology and capacity banding align with distinct operational environments. Refinery operators, warehouse managers, and marine contractors each impose incompatible technical requirements that fragment procurement patterns across the installed base.
Product Type:
Domestic demand concentrates in EPA-compliant configurations, while export markets retain flexibility for legacy diesel architectures.
- Hydraulic:Proportional valve controls deliver precise load positioning through variable displacement pumps. Gulf Coast petrochemical facilities specify these units for catalyst changeouts and vessel maintenance where hydraulic reliability outweighs electrification premiums.
- Electric:Battery-powered systems with onboard charging infrastructure eliminate exhaust emissions in enclosed processing areas. Food-processing plants in California and New York specify these for USDA-inspected facilities where propane bans are expanding.
- Diesel:Tier 4 Final powertrains from Cummins and Perkins dominate outdoor construction deployments where refueling infrastructure exists.
- Hybrid:Diesel-electric architectures switch power sources based on duty cycle, penetrating indoor manufacturing where intermittent lifting combines with mobility requirements.
Hydraulic holds the largest share; momentum sits with Hybrid.
End User:
Cost tier stratification separates capital-intensive process industries from price-sensitive general construction.
- Construction:General contractors prioritize rental flexibility over ownership for short-duration infrastructure projects. Texas highway maintenance departments specify 15-ton units for bridge component placement where maneuverability constraints exclude larger alternatives.
- Manufacturing:Heavy equipment assembly lines require synchronized lifting for production line reconfiguration. Automotive plants in Michigan and Ohio deploy electric carry deck cranes for press die changes where overhead clearance restrictions apply.
- Warehousing:Third-party logistics operators specify compact electric units for mezzanine installation and racking maintenance.
- Marine:Shipyard repair facilities demand corrosion-resistant finishes and sealed electrical systems for waterfront exposure.
Construction commands the dominant volume position; Manufacturing shows the steepest expansion trajectory.
Capacity:
Volume concentration in mid-capacity bands reflects rental house standardization around single-machine fleet flexibility.
- 5 Ton:Compact footprint with four-wheel steering navigates 8-foot aisle widths in distribution centers. Indoor warehousing operators in California specify these for rack maintenance where building column spacing constrains equipment dimensions.
- 10 Ton:Balanced reach-to-weight ratio serves general maintenance across process industries. Refinery contractors in Louisiana deploy these for heat exchanger bundle extraction during turnaround cycles.
- 15 Ton:Extended boom configurations reach 60-foot radii for vessel access in petrochemical facilities.
- 20 Ton:Maximum structural capacity within compact carrier dimensions for heavy component installation.
15 Ton anchors rental revenue; 10 Ton gains share fastest in fleet refresh cycles.
Installation:
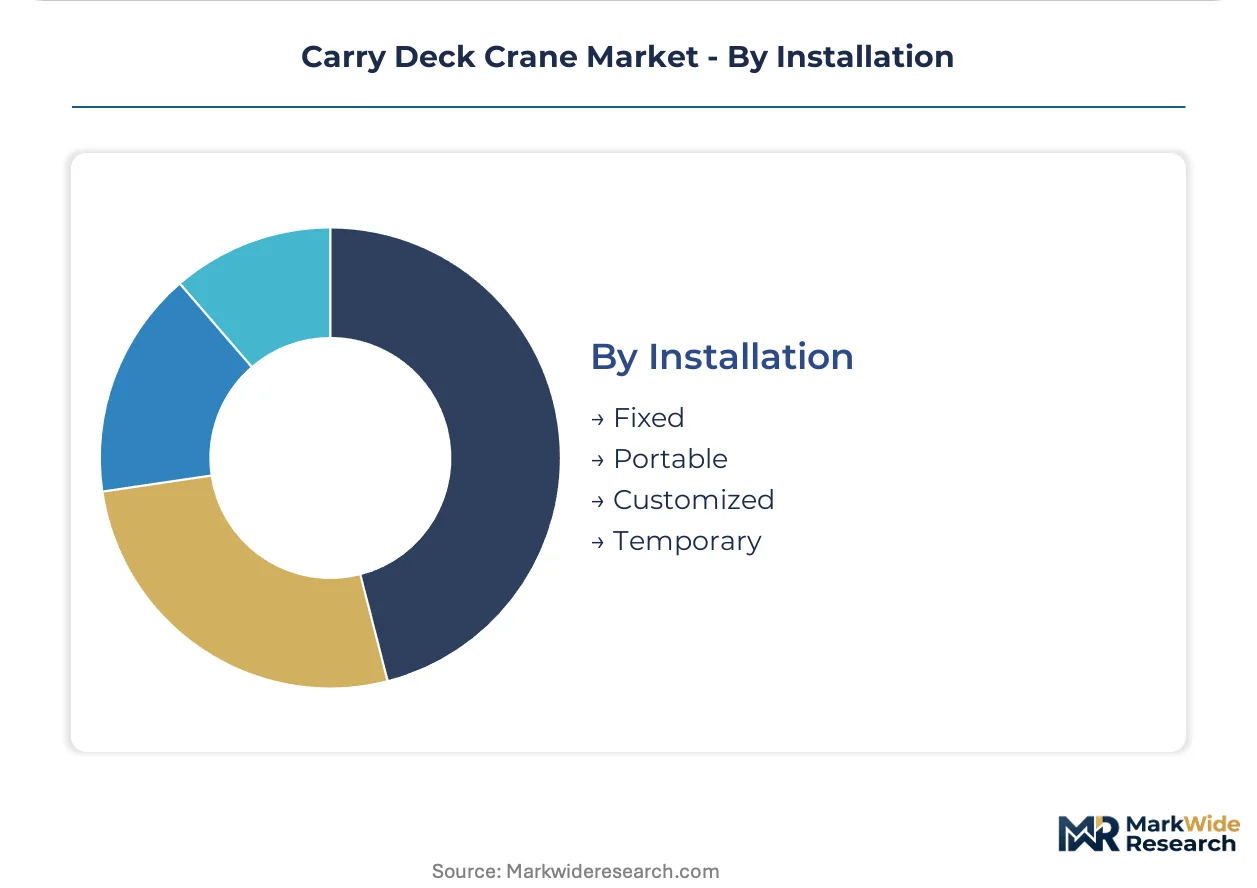
Customer type determines attachment permanence, with owner-operators favoring fixed configurations and rental houses emphasizing portability.
- Fixed:Permanent mounting on reinforced concrete pads eliminates daily setup procedures. Steel mills in Pennsylvania install these at blast furnace maintenance stations where repetitive lifting cycles justify capital investment.
- Portable:Self-propelled carriers with rapid deployment features serve multi-site contractors. Municipal infrastructure departments in Texas specify these for bridge inspection platforms requiring frequent relocation.
- Customized:Modified outrigger spans and boom articulation address facility-specific constraints.
- Temporary:Short-term rental agreements with operator provision serve peak maintenance windows.
Portable dominates rental channel volume; Customized captures premium pricing in process industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in carry deck cranes tilt toward net importing regions with dense downstream energy infrastructure, while manufacturing concentration in East Asia creates supply-side export dependencies. Tariff-adjusted steel pricing and emissions certification timelines reshape procurement geography.
United States
Gulf Coast petrochemical maintenance cycles drive rental utilization in Texas and Louisiana. EPA Tier 4 Final enforcement accelerates fleet replacement at Houston-area refineries. Port Arthur and Lake Charles anchor demand clusters where turnaround contractors standardize around 15-ton hybrid configurations.
Germany
Industrial machinery OEMs source compact lifting equipment for automated assembly line integration. REACH compliance on hydraulic fluids elevates total cost of ownership calculations. The Ruhr industrial corridor and Baden-Württemberg manufacturing belt concentrate procurement from rental houses serving automotive press shops.
China
Domestic construction stimulus absorbs scaled output from Xuzhou and Changzhou fabrication centers. MIIT equipment safety certification creates 18-month validation windows for export-bound units. Yangtze River Delta port infrastructure projects specify electric carry deck units for confined shipyard environments.
Saudi Arabia
NEOM and Red Sea tourism developments generate demand for desert-rated compact cranes. The country's national industrial regulator mandates third-party inspection protocols for imported lifting equipment. Eastern Province oilfield maintenance contractors deploy portable units across dispersed wellhead facilities.
India
Petrochemical capacity expansion at Gujarat and Maharashtra refineries outstrips domestic crane manufacturing. BIS certification requirements for mobile cranes extend procurement timelines for international suppliers. Hazira and Mundra industrial zones concentrate demand from process industry maintenance contractors.
Carry Deck Crane Market Vendor Landscape
Concentration sits with full-line construction equipment manufacturers who amortize engine compliance costs across multiple product categories. The competitive structure tiers into three archetypes: vertically integrated boom fabricators with captive steel processing, specialized compact crane assemblers focused on refinery maintenance segments, and scale-driven Chinese manufacturers exporting on price. Dominant competitive moves include backward integration into high-strength alloy supply chains and technology licensing partnerships for hybrid powertrain architectures.
Among North American fabricators, Terex Corporation and Broderson Manufacturing exemplify divergent strategic positions—one leveraging multi-product scale for emissions compliance cost absorption, the other occupying a specialist niche in compact refinery-duty configurations. XCMG Group anchors the export-oriented tier, representing the scale-driven Chinese manufacturing archetype that competes on unit economics despite North American certification bottlenecks.
| Leading Market Players |
|---|
| Terex Corporation |
| XCMG Group |
| Liebherr Group |
| Broderson Manufacturing |
| Kobelco Construction Machinery |
| Manitowoc Cranes |
| Sany Group |
| Shuttlelift |
| Tadano Ltd. |
| Others |
Supply Flow & Price Mechanics
Scaled output from East Asian fabrication centers compresses unit economics for Tier 4 powertrain integration, concentrating supply-side leverage with full-line manufacturers who amortize engine compliance costs across multiple product categories while elevating price floors for niche assemblers lacking comparable volume.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, where EPA Tier 4 Final certification grade and after-sales service bundling drive differentiation. Cost compression in the standard tier is intensifying because Tier 4 engine cost concentration now represents 35-40% of total machine cost, squeezing assembler margins. General construction contractors exhibit highest price sensitivity due to rental flexibility preferences, while petrochemical facility operators show lowest sensitivity given prevailing-wage maintenance budgets and turnaround schedule rigidity.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for alloy steel plate shipments, reshaping procurement calendars for boom fabricators. Supply concentrates in China, Germany, and the United States, with high-strength alloy plate and Tier 4-compliant diesel powertrains from Cummins and Perkins serving as critical inputs. Single-source vulnerability around EPA-certified engine supply creates structural risk for North American assemblers. Distribution runs through rental house networks and direct OEM sales to process industry operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final enforcement is accelerating fleet replacement cycles and compressing residual values for legacy diesel inventory, creating a high-growth disruption window for hybrid-electric configurations and certified remanufactured powertrains.
For Market Incumbents: Shield margin position through backward integration into high-strength alloy supply chains and captive boom fabrication capacity. Engine compliance cost absorption across multi-product portfolios provides defensive leverage against Chinese price competition. Prioritize ANSI B30.5 certification investment to maintain commercial insurance acceptance barriers.
For New Entrants and Emerging Players: Anchor in food-processing indoor lift segments where zero-emission specifications and USDA facility bans on propane and diesel create penetrable white space. California and New York utility rebate programs shorten payback periods for battery-electric fleet conversions. Pursue telematics-enabled rental models with usage-based billing platforms to displace fixed-term municipal contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rental houses with NCCCO-certified operator networks and Gulf Coast petrochemical corridor density. Long-term viability over a 5-10 year window favors targets with hybrid powertrain technology licensing partnerships and backward integration into alloy supply. Monitor state-level prevailing-wage legislation and utility electrification rebate program expansions as inflection indicators for regional payback period compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive high-strength plate sourcing insulates Terex and Broderson from tariff-adjusted pricing volatility. |
| Hybrid Powertrain Technology Licensing | Diesel-electric architectures from Cummins partnerships penetrate indoor manufacturing environments with emissions restrictions. |
| ANSI B30.5 Certification Investment | Validation timelines of 18-24 months create defensive moats against Chinese manufacturers seeking North American entry. |
| Telematics-Enabled Rental Platform | Usage-based billing displaces fixed-term contracts in Texas municipal infrastructure maintenance departments. |
| Zero-Emission Product Line Expansion | Battery-electric units satisfy California and New York indoor air quality mandates in food-processing facilities. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with maintenance directors at Gulf Coast refineries, fleet managers at national rental houses, OEM procurement teams, and aftermarket service heads, combined with secondary validation against EPA enforcement records, OSHA certification databases, customs/trade data, and SEC 10-K filings from publicly traded equipment manufacturers. Bottom-up unit economics and top-down market sizing were triangulated to ensure consistency.
Across the projection horizon, the analytical framework modeled segmentation dimensions including powertrain technology, capacity band, end-use industry, and installation type. CAGRs were derived from fitted growth curves incorporating refinery turnaround cycle frequency, Tier 4 fleet replacement rates, and state-level electrification incentive program adoption trajectories. Steel input cost indices and certified operator wage premium data served as industry-specific forecast inputs.
Material uncertainties — steel tariff adjustments, EPA enforcement intensity variations, and NCCCO certification pipeline bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory continuity and petrochemical maintenance spending levels. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Reach Trucks Market