
 Chute Liners Market | 2026-2036
Chute Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Chute Liners Market Insights
The gap between premium composite-lined systems and commodity rubber replacements is realigning procurement patterns across heavy industry. Metso Outotec leverages its integrated minerals-processing footprint to bundle liner contracts with crusher service agreements. Trelleborg AB anchors its position through proprietary polyurethane formulations that extend wear life in high-abrasion copper circuits. Weir Group PLC competes on foundry-to-site vertical control, casting alloy steel liners at captive facilities.
Chute liners are abrasion-resistant protective surfaces installed inside material transfer chutes to deflect impact, reduce wear on structural steel, and control flow dynamics in bulk-handling operations. Typical rubber formulations specify 40-70 Shore A durometer with embedded fabric reinforcement, while polyurethane variants achieve 85-95 Shore A for sharper, heavier ores. Steel and composite materials command the deepest margin pools where ore hardness exceeds 400 BHN and replacement intervals compress below six months. Polyurethane segments are gaining fastest in gold and lithium concentrators where chemical resistance to reagents matters as much as mechanical durability. Rubber retains volume leadership in thermal coal and construction aggregates where cost-per-ton metrics dominate capital committees.
OSHA silica exposure limits and EPA National Emission Standards for Hazardous Air Pollutants shape liner specification by mandating enclosed transfer points that depend on precise liner fit and sealing geometry. MEE enforcement of GB standards on particulate matter in China's mining provinces adds parallel compliance pressure for dust-tight chute designs. Stakeholders must monitor how tightening alloy steel tariffs and evolving REACH restrictions on isocyanate-based polyurethanes recast material selection economics before the next replacement cycle.
Market Dynamics
The replacement-cycle compression in Australia's Pilbara iron ore corridor and China's Shanxi coal belt is forcing suppliers to restructure service contracts around uptime guarantees rather than unit sales. Mining operators now demand integrated lining systems that reduce unplanned shutdowns below 48 hours annually.
Growth Catalysts
- EPA dust-emission standards:The United States EPA National Emission Standards for Hazardous Air Pollutants mandate enclosed transfer points, requiring precision-fit liners that eliminate fugitive dust at material discharge zones.
- Polyurethane formulations:Gold and lithium concentrators specify 85-95 Shore A polyurethane variants for chemical resistance to cyanide and sulfuric acid reagents, extending service intervals in aggressive leaching circuits.
- Pilbara replacement acceleration:Australian iron ore operators compress liner changeout cycles from 18 months to 9 months as ore hardness exceeds 400 BHN in deeper pit benches.
Market Restraints
- Alloy steel tariff volatility:Section 232 and retaliatory duties on chromium-molybdenum castings inflate landed costs for captive foundry operators serving remote mine sites.
- Isocyanate regulatory friction:ECHA REACH restrictions on aromatic diisocyanates in polyurethane curing systems force reformulation investments that lag qualification timelines by 14-18 months.
- Natural rubber supply concentration:73% of sheet rubber feedstock originates from Southeast Asian smallholder cooperatives, exposing procurement to climate-induced yield shocks and export quota volatility.
Strategic Opportunities
- Lithium brine expansion corridors:Argentina's Catamarca and Jujuy provinces require acid-resistant chute architectures for evaporation pond feed systems, creating first-mover positioning for fluoropolymer-lined suppliers.
- MEE air-quality directives:China's Ministry of Ecology and Environment enforcement of GB 31571 standards on particulate matter creates mandatory upgrade windows for 340+ coal preparation plants in Shanxi and Inner Mongolia.
- Digital wear-monitoring convergence:Embedded RFID thickness sensors paired with predictive maintenance platforms enable outcome-based liner contracts that capture value from avoided downtime rather than material tonnage.
Industry Challenges
- Polymer-ceramic bonding certification:Qualifying multi-layer composite liners for 6,000-hour service guarantees requires 18-month field trials that delay commercial rollout and strain R&D budgets.
- Legacy chute geometry retrofit:Bolt-pattern incompatibility between 1980s-era steel chutes and modern modular lining systems forces costly structural modifications or custom fabrication that erodes margin on replacement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chute Liners Market |
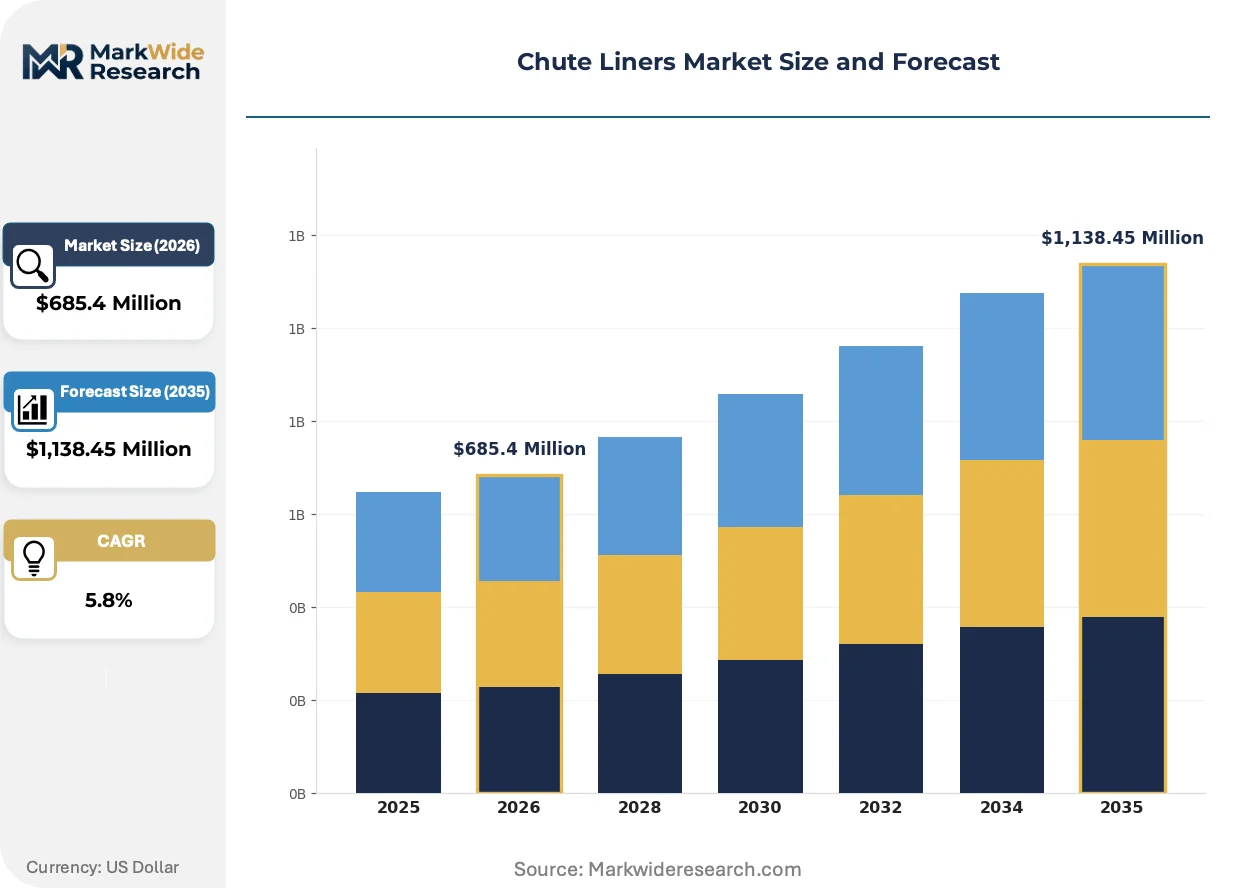
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, Polyurethane, Steel, Composite End Use Industry: Mining, Construction, Waste Management, Agriculture Installation Method: Direct Installation, Adhesive Bonding, Welding, Mechanical Fastening Size: Small, Medium, Large, Custom |
| Companies Covered | Metso Outotec, Trelleborg AB, Weir Group PLC, FLSmidth & Co., Metso Corporation, Iracore, Tega Industries, Thyssenkrupp, Ashross, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chute Liners Market Trends and Innovations
Material science advances and regulatory enforcement timelines are compressing product development cycles while fragmenting procurement authority across engineering, EHS, and finance functions. Suppliers must now demonstrate compliance documentation alongside wear-life performance.
Modular ceramic-polymer hybrid liners combine alumina oxide tiles with energy-absorbing polyurethane substrates to deflect impact in high-drop copper concentrator circuits. Chilean state-owned copper operators specify these systems for transfer heights exceeding 12 meters where traditional rubber fails within 90 days. The technology is converging with digital twin simulations that optimize tile placement patterns before physical installation.
China's MEE enforcement of GB 31570-2015 emissions limits for petroleum refining and coal processing mandates sealed chute architectures with negative-pressure dust collection. Operators in Shanxi province retrofit 2,400 transfer points annually to avoid production suspensions. Steel and cement sectors face parallel compliance pressure as provincial environmental bureaus tighten inspection frequencies.
Engineering-procurement-construction firms now bundle liner specification into turnkey conveyor contracts, displacing direct mine-site purchasing. Fluor, Bechtel, and Wood Group specify approved vendor lists that exclude commodity rubber suppliers lacking ISO 14001 certification. This concentration is most visible in African copperbelt developments where EPC contractors control 80% of capital equipment selection.
Chute Liners Market Segmentation
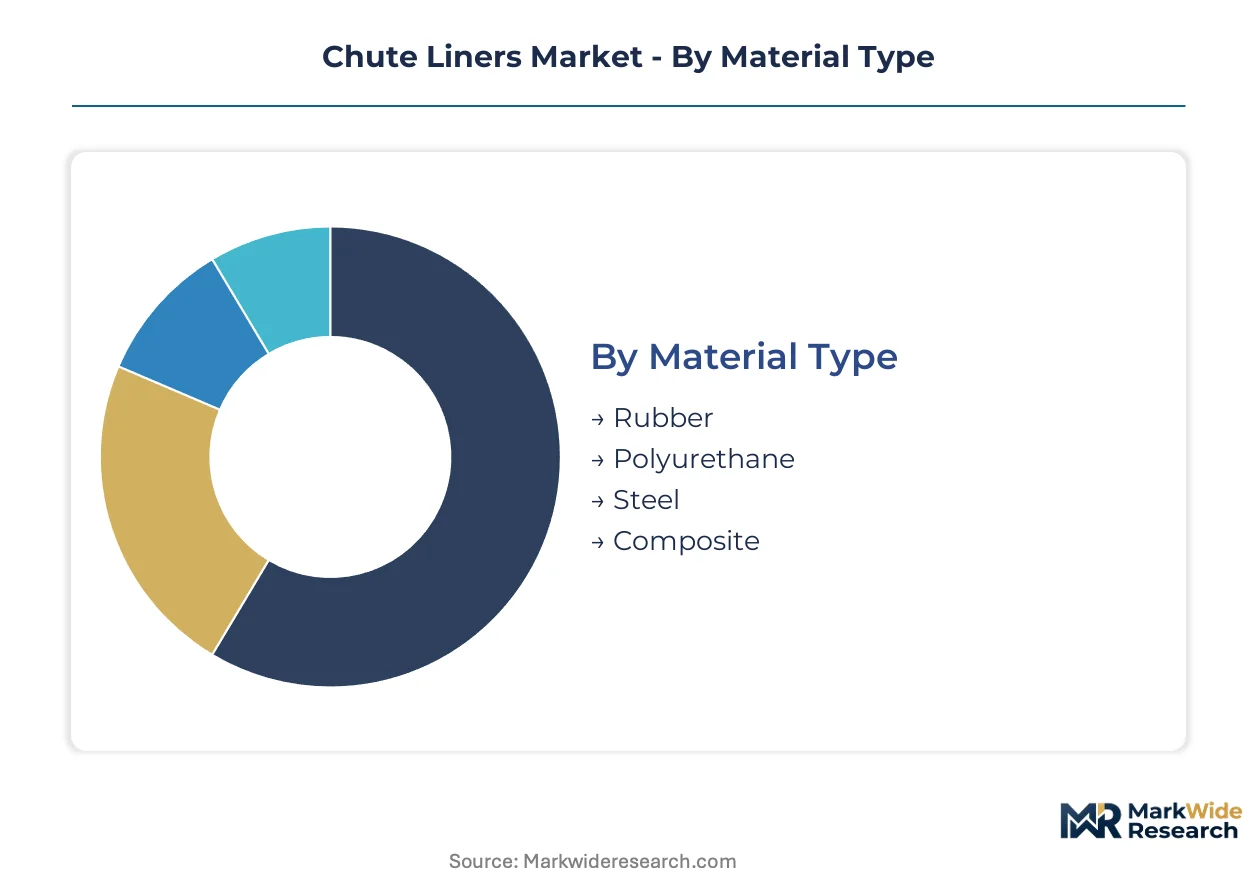
Chute liner procurement splits across four distinct category systems. Material selection dictates wear-life economics. End-use concentration determines specification stringency. Installation method shapes total cost of ownership. Size tiering reflects site-specific engineering constraints.
Material Type:
Buyers in this category differentiate by ore hardness, chemical exposure, and replacement interval tolerance rather than upfront unit cost.
- Rubber:Formulated at 40-70 Shore A durometer with embedded fabric reinforcement. Thermal coal operators in Australia's Hunter Valley and construction aggregate handlers prioritize rubber for its cost-per-ton efficiency in low-abrasion, high-volume transfers.
- Polyurethane:Achieves 85-95 Shore A hardness for sharper, heavier ores. Gold concentrators in Nevada and lithium brine operations in Argentina's Catamarca province specify polyurethane for chemical resistance to cyanide and sulfuric acid reagents.
- Steel:Chromium-molybdenum castings serve copper circuits where ore hardness exceeds 400 BHN. Captive foundry operators compete on vertical control from casting to site delivery.
- Composite:Multi-layer ceramic-polymer hybrids combine alumina oxide tiles with energy-absorbing substrates. Chilean state-owned copper operators deploy these for transfer heights exceeding 12 meters where traditional materials fail within 90 days.
Rubber leads volumes today; polyurethane is gaining share fastest.
End Use Industry:
Specification authority concentrates with engineering teams in mining, while procurement in construction and agriculture prioritizes standard catalog offerings.
- Mining:Iron ore corridors in Australia's Pilbara and coal belts in China's Shanxi drive demand for wear-resistant systems with sub-48-hour annual unplanned shutdown guarantees. EPA dust-emission standards and MEE air-quality directives mandate sealed chute architectures.
- Construction:Aggregate handling for infrastructure projects specifies medium-duty rubber liners with mechanical fastening for rapid field replacement. Volume concentrates with ready-mix concrete and asphalt batching operations.
- Waste Management:Municipal solid waste transfer stations and recycling facilities require impact-absorbing surfaces for heterogeneous material streams. Chemical resistance matters less than tear strength and ease of maintenance.
- Agriculture:Grain elevators and fertilizer handling specify food-grade polyurethane formulations. Demand fragments across cooperatives and regional processors with limited capital budgets.
Mining commands the deepest margin pools; waste management presents the steepest expansion trajectory as circular economy infrastructure scales.
Installation Method:
Site access constraints and skilled labor availability determine method selection more than liner material itself.
- Direct Installation:Bolt-in modular systems suit new chute construction and planned shutdown windows. Engineering-procurement-construction firms in African copperbelt developments specify these for turnkey conveyor contracts.
- Adhesive Bonding:Polyurethane and rubber sheets bond to prepared steel substrates for irregular geometries. Field cure times of 24-48 hours limit application to scheduled maintenance periods.
- Welding:Steel liner attachment requires qualified welders and hot-work permits. Remote mine sites with captive maintenance crews favor this method for permanent, high-impact zones.
- Mechanical Fastening:Stud-and-washer systems enable rapid replacement without surface preparation. Construction aggregates and waste management operators prioritize uptime over bond integrity.
Mechanical fastening dominates replacement contracts; adhesive bonding is climbing the fastest as modular polyurethane systems penetrate gold and lithium circuits.
Size:
Production scale and chute geometry complexity segment buyers between standard catalog dimensions and engineered-to-order solutions.
- Small:Pre-cut sheets and tiles serve maintenance departments for patch repairs and minor transfer points. Catalog availability and same-day shipment determine supplier selection.
- Medium:Standard chute dimensions in coal preparation and aggregate processing accommodate semi-custom fabrication. Volume concentrates with regional distributors serving multiple mine sites.
- Large:Integrated lining systems for primary crusher discharge and high-tonnage conveyors require project-specific engineering. Weir Group and Metso Outotec compete on foundry-to-site vertical control for these contracts.
- Custom:Legacy chute retrofits and specialized geometries force bespoke solutions. Bolt-pattern incompatibility with 1980s-era steel structures erodes margins through structural modification requirements.
Medium sizes capture the highest transaction frequency; custom solutions deliver the steepest margin expansion as replacement cycles compress in mature mining districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining engineers and maintenance crews concentrate in Australia's Pilbara, Brazil's Carajás, and China's Shanxi province. These talent clusters anchor regional demand patterns for wear-resistant lining systems. Procurement authority increasingly sits with site reliability teams rather than centralized corporate engineering.
Australia
Rio Tinto and BHP compress replacement cycles to nine months as Pilbara iron ore hardness exceeds 400 BHN. The country's national environmental regulator enforces dust-monitoring protocols at transfer points. Perth-based service contractors now embed technicians permanently at Newman and Port Hedland hub sites.
Brazil
Vale accelerates liner changeouts at Serra Sul and Serra Norte complexes amid ore abrasiveness shifts. IBAMA air-quality enforcement mandates enclosed chute architectures at expansion projects. Maintenance talent concentrates in Pará state's Carajás mineral province where captive foundry partnerships dominate procurement.
China
State-owned coal operators in Shanxi and Inner Mongolia face MEE enforcement of GB 31571 particulate standards. The Ministry of Ecology and Environment suspends production at non-compliant preparation plants. Datong and Taiyuan clusters drive retrofit demand across 340+ facilities upgrading sealed transfer systems.
United States
Copper concentrators in Arizona and Nevada specify chemical-resistant polyurethane for cyanide leaching circuits. EPA National Emission Standards for Hazardous Air Pollutants mandate precision-fit liners at enclosed discharge zones. Phoenix and Tucson maintenance hubs stock modular systems for 48-hour turnaround guarantees.
Chile
Codelco deploys ceramic-polymer hybrids at El Teniente and Chuquicamata for transfer heights exceeding 12 meters. The national mining regulator enforces dust-control protocols at state-owned operations. Santiago-based engineering firms bundle liner specification into turnkey concentrator expansion contracts.
Chute Liners Market Competitive Landscape
Top-tier vendors anchor premium composite and alloy steel segments, while regional fabricators compete on rubber and standard polyurethane replacement contracts. The structure consolidates around foundry-to-site vertical control and proprietary formulation advantages. Three archetypes dominate: integrated minerals-processing conglomerates, specialized polymer compounders, and captive foundry operators. Competitive moves center on bundling liner contracts with broader equipment service agreements and accelerating qualification timelines for multi-layer composite systems.
Within the integrated processing tier, Metso Outotec and Weir Group PLC occupy positions defined by captive manufacturing assets and site-level service integration. Trelleborg AB exemplifies the specialized compounder archetype through proprietary polyurethane expertise. These three anchors represent distinct strategic vectors—bundled minerals processing, vertical foundry control, and advanced materials science—rather than direct product competition.
| Leading Market Players |
|---|
| Metso Outotec |
| Trelleborg AB |
| Weir Group PLC |
| FLSmidth & Co. |
| Metso Corporation |
| Iracore |
| Tega Industries |
| Thyssenkrupp |
| Ashross |
| Others |
Pricing and Supply Chain Analysis
Captive foundry-to-site vertical integration anchors both supply security and pricing power for alloy steel liner producers serving remote mining districts. Weir Group and Metso Outotec leverage in-house chromium-molybdenum casting capacity to command premium positioning where ore hardness exceeds 400 BHN and replacement cycles compress below twelve months. This integration insulates against tariff volatility while locking in multi-year service contracts with uptime guarantees.
Pricing Analysis
Bundled service contracts now separate premium composite suppliers from unbundled commodity rubber vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by wear-life certification and after-sales support intensity. Cost compression in standard rubber tiers intensifies because Southeast Asian feedstock concentration exposes procurement to climate-induced yield shocks. Thermal coal operators in Australia's Hunter Valley exhibit highest price sensitivity, while copper concentrators in Chile's high-drop circuits accept premium positioning for ceramic-polymer hybrids.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian smallholder cooperatives supplying 73% of natural rubber sheet feedstock. Raw material procurement draws from Thailand, Indonesia, and Malaysia for rubber; China and Germany for polyurethane precursor chemicals; and domestic captive facilities for alloy steel castings. Tariff exposure on chromium-molybdenum imports strains foundry economics under Section 232 enforcement. Distribution runs through engineering-procurement-construction contractors in African copperbelt developments and direct mine-site procurement in mature districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where MEE air-quality enforcement in China's Shanxi province accelerates upgrade demand faster than EPA compliance timelines in the United States, compressing replacement windows and shifting procurement authority toward site reliability teams.
For Market Incumbents: Anticipate displacement risk from digital wear-monitoring platforms by embedding RFID thickness sensors in liner systems before qualification timelines lapse. Secure backward integration into polyurethane precursor supply through partnerships with German chemical compounders to hedge REACH restriction delays. Prioritize certification investment for multi-layer ceramic-polymer bonding to capture 6,000-hour service guarantee contracts in Chilean copper circuits. For New Entrants and Emerging Players: Fluoropolymer-lined acid-resistant architectures for Argentina's lithium brine expansion corridors offer the most penetrable white-space target where incumbent qualification lags create temporary supply gaps. Target waste management transfer stations in North American circular economy infrastructure builds where specification stringency remains lower than mining. Pursue go-to-market angles through EPC contractor approved-vendor list accreditation rather than direct mine-site sales. For Investors and Strategic Acquirers: Roll-up economics work for regional polyurethane fabricators because fragmented maintenance-contractor relationships in Australia's Pilbara create consolidation leverage without customer concentration risk. Five-to-ten year viability hinges on capturing lithium and gold circuit share as chemical resistance specifications tighten. Watch MEE production suspension enforcement frequency in Shanxi as the inflection indicator for sealed chute architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Precursors | Mitigates ECHA REACH restriction delays for isocyanate curing systems. |
| Digital Wear-Monitoring Platform Deployment | Enables outcome-based contracts capturing value from avoided downtime. |
| Ceramic-Polymer Hybrid Qualification Acceleration | Secures 6,000-hour guarantees for Chilean high-drop copper concentrators. |
| EPC Contractor Approved-Vendor List Accreditation | Unlocks African copperbelt turnkey conveyor contract bundling. |
| Captive Foundry Capacity Expansion | Insures against Section 232 tariff exposure on alloy steel castings. |
Research Methodology
Direct dialogue with maintenance directors at Pilbara iron ore operators, procurement leads at Chilean state-owned copper mines, EPC contractor engineering teams, and aftermarket service heads anchored qualitative findings. Secondary validation drew from EPA National Emission Standards filings, MEE GB standard enforcement records, SEC 10-K disclosures from listed minerals-processing conglomerates, and customs data on chromium-molybdenum casting imports. Bottom-up segment sizing triangulated against top-down macroeconomic mineral production forecasts.
Segment-level projections across material type, end-use industry, installation method, and size tier generated value and volume trajectories over the projection horizon. CAGRs derived from replacement-cycle compression rates in mature mining districts and regulatory compliance upgrade windows in China's coal preparation sector. Modeled inputs incorporated ore hardness progression data from deeper pit benches and MEE inspection frequency escalation assumptions.
The model holds under continued enforcement of EPA and MEE particulate standards; deviation in regulatory suspension intensity or alloy steel tariff relief would shift replacement timing and material selection economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Pipe Jacking Machines Market