
 Overhead Hoist Transport (OHT) Market | 2026-2036
Overhead Hoist Transport (OHT) Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Hoist Transport (OHT) Market Insights
CE marking under the EU Machinery Directive is broadening the compliance burden for OHT suppliers seeking European manufacturing contracts. DAIFUKU leverages its integrated logistics systems footprint to anchor automated OHT installations across Asian semiconductor fabs. Murata Machinery competes through precision-engineered cleanroom-compatible hoist designs. SYNUS Tech specializes in software-driven fleet management for multi-vendor OHT environments.
Overhead Hoist Transport (OHT) systems are electrically or pneumatically powered material handling mechanisms suspended from elevated tracks, typically rated from under 1 ton to over 15 tons capacity, designed to move loads horizontally and vertically within fixed facility layouts. These systems serve primarily in automated manufacturing environments where floor space constraints and contamination control demand ceiling-mounted transport infrastructure. Electric hoists dominate installed capacity due to energy efficiency and fine positioning accuracy, while automated technology segments capture expanding margin pools as semiconductor and flat-panel display fabs pursue lights-out production targets. Chain hoists retain cost advantages in heavy-capacity construction and warehousing applications where cycle speed matters less than lifting reliability.
FCC electromagnetic compatibility rules govern wireless control systems in US-deployed OHT units, while China's GB standards and MIIT equipment certification shape product specifications for domestic manufacturing installations. Japan's METI energy efficiency guidelines and JIS structural standards influence hoist motor and rail system designs across East Asian supply chains. Stakeholders must weigh regulatory divergence against platform standardization strategies when scaling OHT offerings across multiple national manufacturing bases.
Market Dynamics
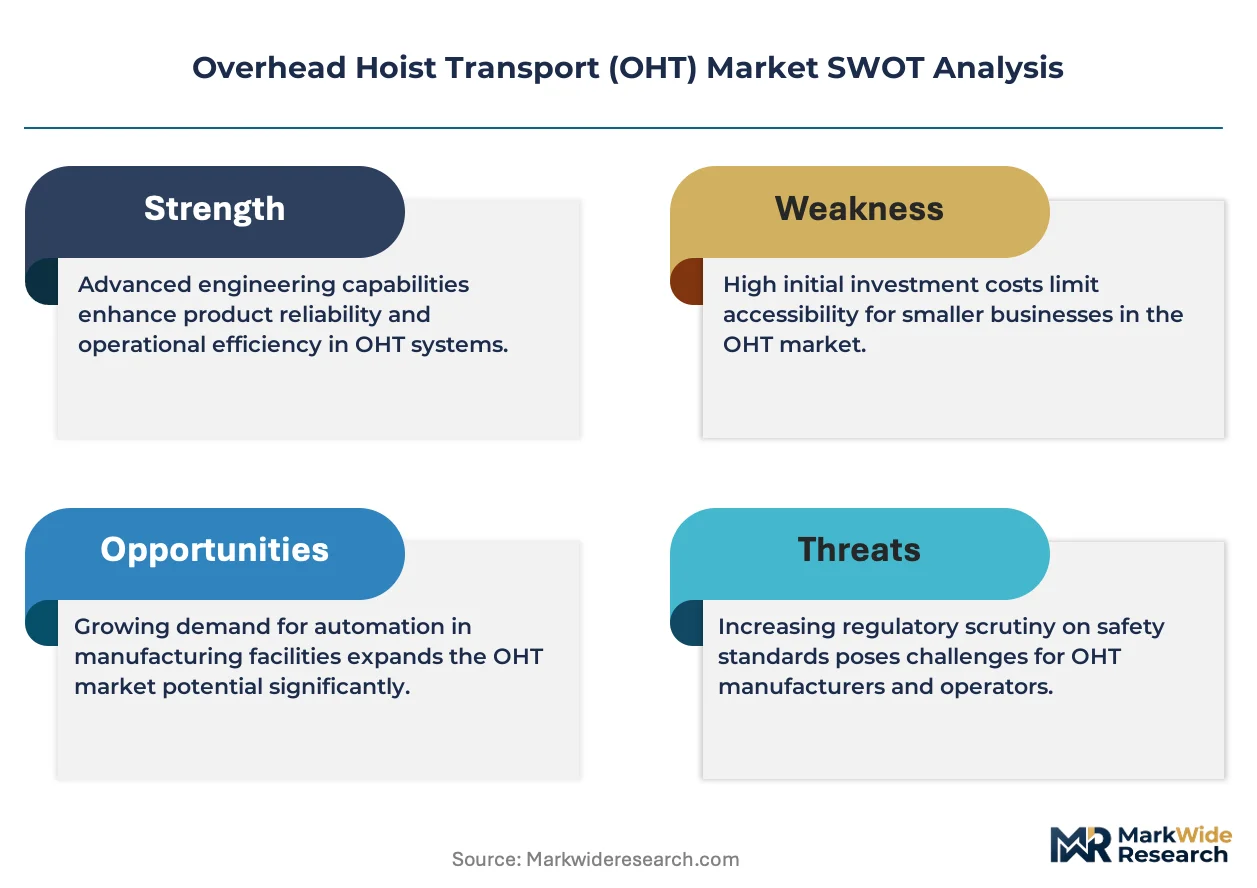
Semiconductor fabs in Taiwan and South Korea are compressing installation timelines for ceiling-mounted transport infrastructure as wafer throughput requirements intensify. This demand concentration is forcing OHT suppliers to reconfigure engineering capacity around cleanroom-compatible rail systems.
Growth Catalysts
- EU Machinery Directive CE marking:European manufacturing contracts now require certified safety interlocks and emergency stop protocols, pulling upgrade demand from legacy hoist installations.
- Flat-panel display fabs:Gen 10.5+ substrate handling requirements in China and South Korea are mandating higher-capacity OHT configurations with sub-millimeter positioning accuracy.
- Lights-out production targets:Fully automated wafer transport is eliminating manual intervention points in East Asian semiconductor clusters, expanding fleet management software attach rates.
Market Restraints
- Rare-earth magnet supply concentration:Permanent magnet motors for precision hoists depend on Chinese-processed neodymium, creating input cost volatility and geopolitical exposure.
- Cleanroom rail fabrication bottleneck:Only a handful of Japanese and German suppliers produce vacuum-compatible aluminum extrusions with the required surface finish specifications.
- Legacy chain hoist substitution:Pneumatic and manual hoists retain installed base in heavy-capacity warehousing where cycle speed requirements remain modest.
Strategic Opportunities
- India semiconductor manufacturing:PLI scheme incentives for domestic chip fabrication are creating first-mover advantage for OHT vendors establishing local installation and service networks.
- AI-driven predictive maintenance:Machine learning integration with hoist vibration sensors and rail wear monitors is opening recurring revenue streams beyond equipment sales.
- Vietnam electronics assembly:Samsung and Foxconn facility expansions in Bac Ninh and Bac Giang provinces are generating demand for mid-capacity automated transport systems.
Industry Challenges
- Multi-vendor fleet integration:Semiconductor fabs operate mixed OHT generations from Daifuku, Murata, and SYNUS Tech, complicating unified control software deployment.
- Cleanroom certification timelines:ISO 14644 compliance testing for new rail installations adds 8-14 weeks to project schedules, compressing vendor cash conversion cycles.
- Electromagnetic compatibility validation:Wireless control systems must pass FCC, CE, and MIIT certification regimes simultaneously, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Hoist Transport (OHT) Market |
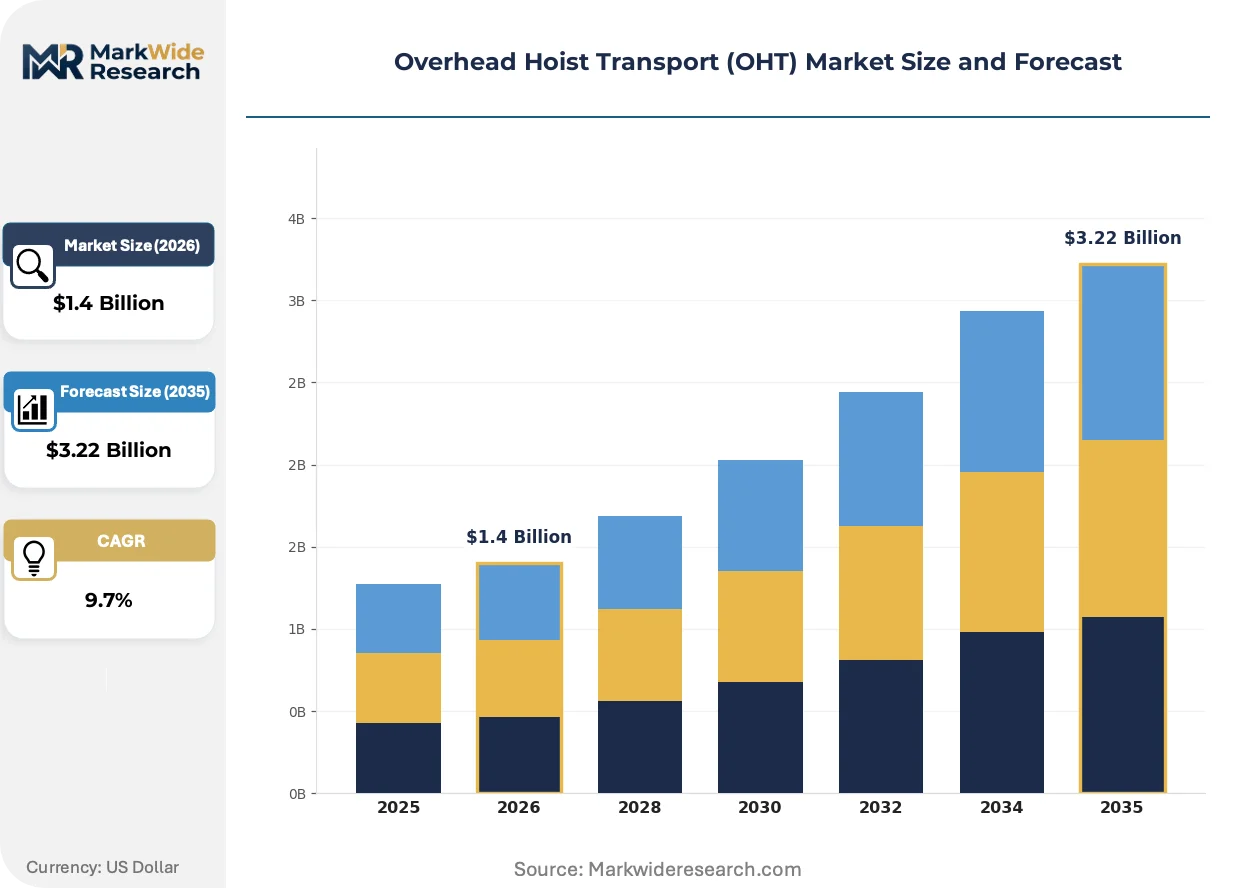
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Rope Hoist, Chain Hoist, Electric Hoist, Pneumatic Hoist End User: Manufacturing, Construction, Warehousing, Aerospace Technology: Manual, Remote Control, Automated, Electric Capacity: Under 1 Ton, 1-5 Tons, 5-15 Tons, Over 15 Tons |
| Companies Covered | SYNUS Tech, Mirle Automation Inter, DAIFUKU, TOTA, SFA Engineering Corporation, Murata Machinery, Shinsung E&G, Kenmec Mechanical Engineering, SMCore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Hoist Transport (OHT) Market Trends and Innovations
Linear motor propulsion is displacing traditional belt-and-pulley drive systems in premium OHT installations, enabling faster acceleration profiles and eliminating mechanical wear points. This shift is compressing maintenance intervals and expanding uptime guarantees.
Electrification of hoist drive architectures is electrifying the competitive landscape for high-precision applications. Permanent magnet synchronous motors now deliver positioning accuracy within 0.1 millimeters for semiconductor wafer transport. Taiwan Semiconductor Manufacturing and Samsung Foundry are specifying all-electric fleets for new greenfield fabs. This technology is electrifying vendor R&D priorities away from pneumatic and hydraulic alternatives.
Japan's METI energy efficiency guidelines are tightening motor performance standards for industrial equipment sold into East Asian markets. Manufacturers must now document power consumption at variable load profiles to qualify for preferential procurement status. Semiconductor fabrication facilities in South Korea are responding by specifying IE4-class premium efficiency motors for all new OHT installations.
Consolidated vendor relationships are displacing fragmented multi-source procurement in large-scale fab construction. Turnkey automation contractors now bundle OHT systems with AMR fleets and warehouse management software. This pattern is most visible in Chinese flat-panel display manufacturing, where BOE and CSOT are awarding single-source contracts for complete intralogistics infrastructure.
Overhead Hoist Transport (OHT) Market Segmentation
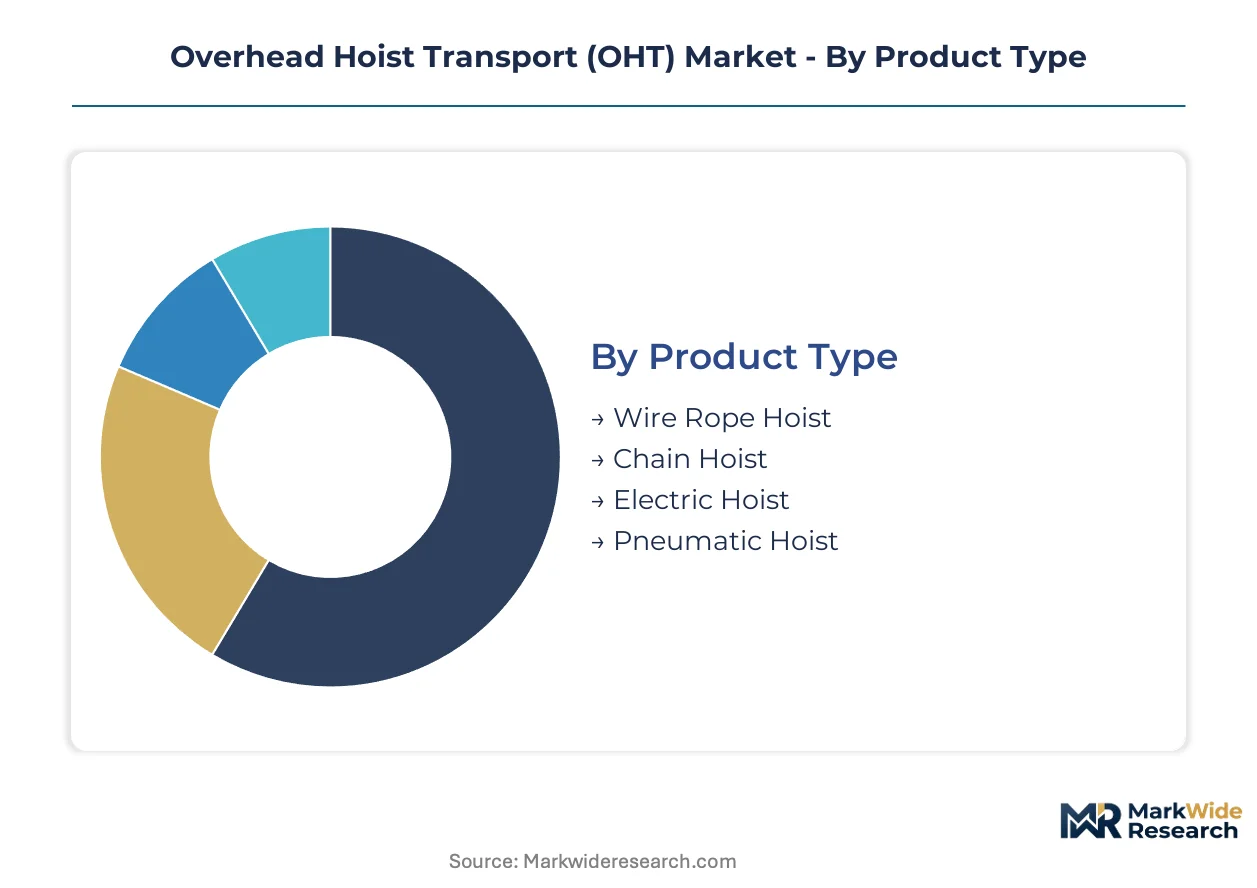
Overhead Hoist Transport systems fragment across four distinct axes that determine specification intensity, regulatory burden, and margin architecture. Product type and technology choices dominate capital allocation in semiconductor fabs, while capacity ratings and end-use verticals shape aftermarket service attach rates.
Product Type:
Hoist architecture selection pivots on load precision requirements and contamination sensitivity in cleanroom environments.
- Electric Hoist:Permanent magnet synchronous motors deliver positioning accuracy within 0.1 millimeters for semiconductor wafer transport. Taiwan Semiconductor Manufacturing and Samsung Foundry specify all-electric fleets for greenfield fabs, with IE4-class premium efficiency motors now mandatory under South Korean procurement guidelines.
- Chain Hoist:Roller chain and link chain mechanisms retain cost advantages in heavy-capacity construction and warehousing where cycle speed matters less than lifting reliability. Pneumatic and manual variants still dominate legacy installations in Southeast Asian electronics assembly.
- Wire Rope Hoist:Multi-strand cable drum systems handle higher lifting heights and heavier loads in aerospace maintenance hangars and flat-panel display glass substrate transport.
- Pneumatic Hoist:Compressed-air drive units serve explosion-risk environments in chemical processing and paint finishing operations where electrical ignition hazards are prohibited.
Mature deployment sits with chain hoists in warehousing and construction. Newer deployment is concentrated in electric hoists for semiconductor and flat-panel display manufacturing.
End User:
Vertical application determines rail system complexity, cleanroom certification tier, and software integration depth.
- Manufacturing:Semiconductor fabs in Taiwan and South Korea compress installation timelines for ceiling-mounted transport as wafer throughput requirements intensify. This demand concentration forces suppliers to reconfigure engineering capacity around cleanroom-compatible rail systems.
- Warehousing:E-commerce fulfillment centers in Vietnam and India deploy mid-capacity automated systems for pallet handling, with Bac Ninh and Bac Giang provinces generating fresh demand from Samsung and Foxconn expansions.
- Construction:Heavy-capacity temporary installations rely on wire rope and chain configurations for steel erection and precast concrete placement where mobility outweighs precision.
- Aerospace:Aircraft assembly hangars require explosion-proof pneumatic units and precision electric hoists for engine and fuselage component positioning.
Revenue concentration tilts toward manufacturing for premium-margin automated systems. Volume expansion is climbing the fastest in warehousing as third-party logistics operators retrofit Asian distribution centers.
Technology:
Control modality selection reflects labor cost trajectories and lights-out production targets across East Asian electronics clusters.
- Automated:Fleet management software from SYNUS Tech and integrated logistics contractors enables multi-vendor OHT coordination in large-scale fab construction. BOE and CSOT in China award single-source contracts for complete intralogistics infrastructure bundling OHT with AMR fleets.
- Remote Control:Wireless systems must pass FCC, CE, and MIIT certification regimes simultaneously, fragmenting engineering resources for suppliers scaling across multiple national manufacturing bases.
- Manual:Pendant and lever controls persist in construction and maintenance applications where operator judgment adapts to variable load conditions.
- Electric:Hardwired control architectures dominate permanent installations in manufacturing facilities with stable layout configurations.
Technology migration favors automated systems in semiconductor and display manufacturing. Remote control retains installed base in construction and heavy maintenance.
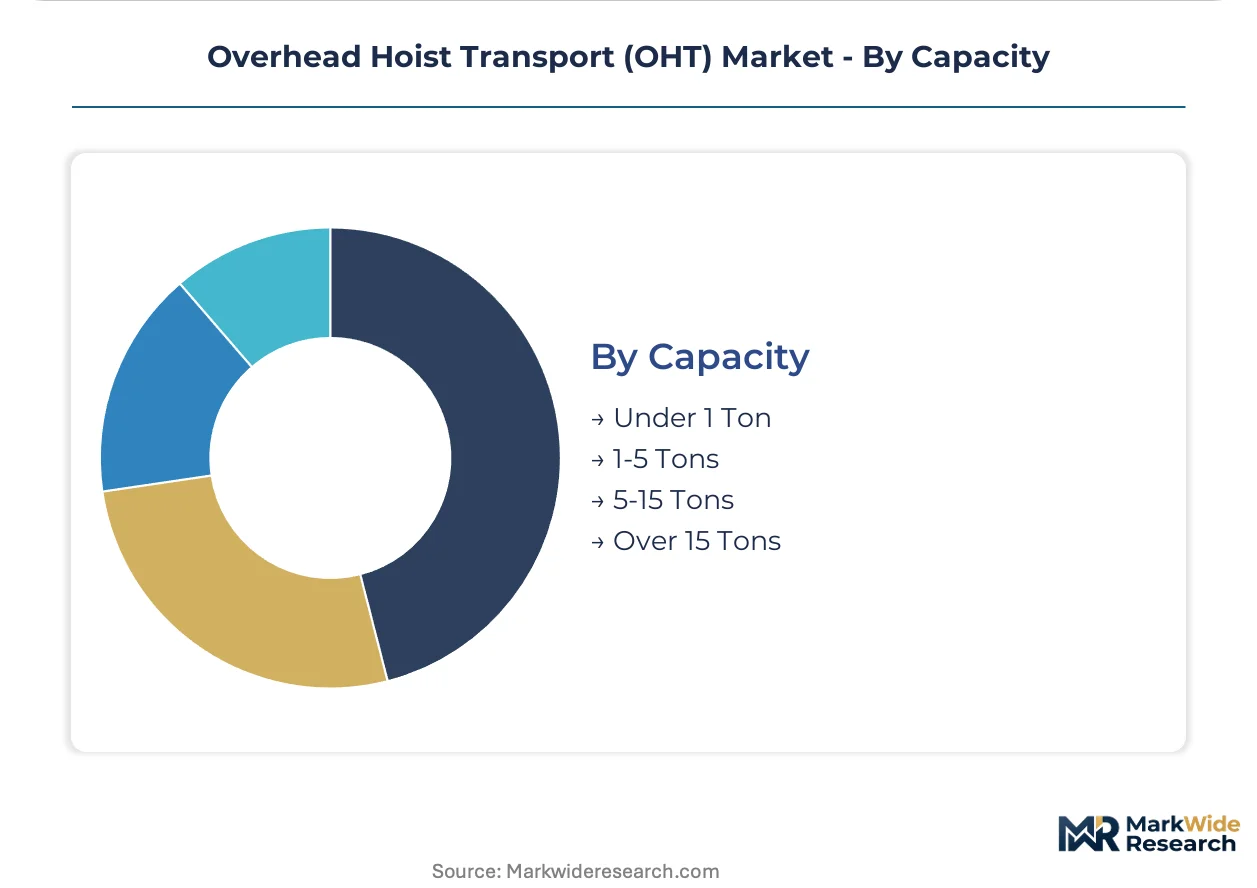
Capacity:
Load rating segmentation aligns with facility scale, substrate dimensions, and crane bridge specifications in electronics manufacturing.
- Under 1 Ton:Single-wafer and small-batch transport systems serve semiconductor front-end processing with sub-millimeter vibration damping requirements.
- 1-5 Tons:Flat-panel display Gen 10.5+ substrate handling in China and South Korea mandates higher-capacity configurations with precision positioning.
- 5-15 Tons:Automotive assembly and heavy machinery manufacturing deploy these ratings for powertrain and component transport.
- Over 15 Tons:Steel processing, shipbuilding, and aerospace structural assembly require specialized heavy-lift rail and bridge configurations.
Specification intensity peaks in sub-5-ton segments for electronics manufacturing. Heavy-capacity systems above 15 tons command premium pricing but slower replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taoyuan's Hsinchu Science Park anchors semiconductor OHT demand concentration. South Korea's Yongin cluster drives flat-panel display substrate handling requirements. China's Yangtze River Delta fabs generate automated transport infrastructure procurement.
China
BOE and CSOT award single-source intralogistics contracts bundling OHT with AMR fleets. MIIT equipment certification and GB standards shape domestic product specifications for vacuum-compatible rail systems. Suzhou and Hefei manufacturing zones compress installation timelines for Gen 10.5+ substrate handling capacity.
South Korea
Samsung Foundry and SK Hynix specify all-electric OHT fleets with IE4-class premium efficiency motors. MFDS procurement guidelines and METI-aligned energy standards influence motor performance requirements. Yongin and Pyeongtaek semiconductor clusters mandate sub-millimeter positioning accuracy for wafer transport infrastructure.
Taiwan
TSMC expands ceiling-mounted transport infrastructure across Tainan and Taichung fab complexes. National Development Council incentives accelerate cleanroom rail fabrication timelines. Hsinchu Science Park suppliers reconfigure engineering capacity around ISO 14644 certification requirements.
Japan
METI energy efficiency guidelines tighten motor performance standards for industrial equipment sold into East Asian markets. JIS structural specifications influence hoist motor and rail system designs across regional supply chains. Kyoto and Osaka precision engineering clusters produce vacuum-compatible aluminum extrusions with required surface finishes.
Vietnam
Samsung and Foxconn facility expansions in Bac Ninh and Bac Giang provinces generate demand for mid-capacity automated transport systems. Ministry of Industry and Trade localization requirements shape vendor establishment of installation networks. Northern electronics assembly corridors adopt OHT infrastructure for component handling efficiency.
Overhead Hoist Transport (OHT) Market Competitive Landscape
Japanese producers anchor one tier; South Korean specialists hold integrated fab automation positions. The vendor structure concentrates around turnkey logistics contractors bundling OHT with complementary material handling systems. Three archetypes dominate: integrated automation conglomerates, precision hoist engineering specialists, and software-centric fleet management vendors. Competitive dynamics center on cleanroom rail fabrication partnerships and multi-vendor fleet integration capabilities.
Within the integrated automation tier, DAIFUKU and Murata Machinery occupy established positions. SYNUS Tech exemplifies the software-driven archetype specializing in multi-vendor coordination. SFA Engineering Corporation sits within the precision engineering cluster serving display substrate handling requirements. These companies represent divergent strategic approaches to fab automation procurement consolidation.
| Leading Market Players |
|---|
| SYNUS Tech |
| Mirle Automation Inter |
| DAIFUKU |
| TOTA |
| SFA Engineering Corporation |
| Murata Machinery |
| Shinsung E&G |
| Kenmec Mechanical Engineering |
| SMCore |
| Others |
Pricing and Supply Chain Analysis
IE4-class motor procurement mandates from South Korean semiconductor fabs are compressing supplier margins and forcing motor vendors to absorb certification costs or lose fab automation contracts. This specification tightening cascades into rail system pricing as cleanroom-compatible aluminum extrusions become the binding constraint on project delivery.
Pricing Analysis
Lead-time premiums now dominate OHT contract negotiations, with fabs in Taiwan and South Korea paying substantial uplifts for 12-week versus 26-week rail fabrication schedules. Pricing stratifies across ISO 14644-certified premium tiers, CE-marked standard configurations, and economy-grade warehouse installations lacking cleanroom validation. Cost compression in the economy tier is intensifying because Chinese warehousing operators are standardizing on domestic GB-certified alternatives. Semiconductor fabs remain the least price-sensitive buyers, prioritizing sub-millimeter positioning guarantees over unit cost.
Supply Chain Analysis
Freight costs for vacuum-compatible aluminum extrusions from Japan and Germany to East Asian fab sites have become a material line item in project economics, with specialized surface-finish requirements precluding nearshoring alternatives. Supply concentrates in Japanese and German precision extrusion specialists for cleanroom rail systems, while Chinese suppliers dominate standard-grade warehouse configurations. Permanent magnet motors draw from Chinese-processed neodymium, creating single-source vulnerability for precision hoist assemblies. Distribution runs through turnkey automation contractors bundling OHT with AMR fleets and fleet management software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The OHT market functions as a cost-of-compliance arena where EU Machinery Directive CE marking and ISO 14644 cleanroom certification create substantial barrier-to-entry moats for vendors lacking established testing relationships and certified manufacturing partnerships.
For Market Incumbents: Extend cleanroom rail fabrication partnerships with Japanese and German extrusion specialists to lock in capacity ahead of Taiwan and South Korean fab expansion waves. Deepen backward integration into permanent magnet motor assembly to mitigate Chinese neodymium supply volatility threatening margin stability in precision hoist lines. For New Entrants and Emerging Players: Begin with mid-capacity automated systems for Vietnam's Bac Ninh and Bac Giang electronics corridors, where Samsung and Foxconn facility expansions generate demand without requiring sub-millimeter positioning credentials. A software-first positioning—fleet management integration for mixed-vendor environments—offers the most penetrable entry vector against entrenched hardware incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with precision engineering specialists possessing vacuum-compatible aluminum extrusion capabilities given the structural bottleneck in cleanroom rail supply. Long-term viability over a multi-year horizon hinges on semiconductor fab automation intensity remaining elevated. Watch for India PLI scheme disbursement acceleration as the signal indicating whether domestic chip fabrication creates viable OHT demand outside East Asian clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Rail Fabrication Partnership | Secures ISO 14644-certified capacity from Japanese and German extrusion specialists for Taiwan and South Korean fab contracts. |
| Fleet Management Software Integration | Enables SYNUS Tech-style multi-vendor coordination in semiconductor fabs operating mixed Daifuku and Murata generations. |
| Permanent Magnet Motor Backward Integration | Reduces exposure to Chinese neodymium price volatility for IE4-class precision hoist assemblies. |
| India Installation Network Establishment | Positions for PLI scheme-driven domestic chip fabrication demand before competitor infrastructure hardens. |
| AI Predictive Maintenance Platform Launch | Converts OHT hardware sales into recurring revenue through vibration sensor and rail wear monitoring subscriptions. |
Research Methodology
Document review covered customs and trade data for vacuum-compatible aluminum extrusions, SEC filings from listed automation conglomerates, and METI energy efficiency guideline disclosures, complemented by interviews with fab automation procurement directors, cleanroom certification specialists, and aftermarket service heads. Primary fieldwork with OEM procurement teams at TSMC and Samsung Foundry validated specification intensity trends, while secondary triangulation against Japan's JIS structural standards and China's GB equipment certification frameworks anchored regional divergence analysis. Bottom-up project pipeline tracking across Taoyuan, Yongin, and Suzhou manufacturing zones was cross-checked against top-down semiconductor capital expenditure disclosures.
Installed base estimates and revenue projections across the analysis window reflect segment-level modeling of electric versus chain hoist technology splits, cleanroom certification tier penetration, and automated versus manual control modality adoption. The analytical framework incorporated capacity rating distributions, end-use vertical concentration in semiconductor versus warehousing applications, and regional procurement guideline alignment with METI, MFDS, and MIIT standards. CAGRs were derived from fab construction timeline compression observed in Taiwan and South Korea, cross-referenced against flat-panel display Gen 10.5+ substrate handling requirements in China.
Underlying measurement precision varies by segment; automated electric hoist installations in certified cleanroom environments carry tighter precision than economy-grade chain hoist deployments in Southeast Asian warehousing. Forecasts reflect assumptions about semiconductor fabrication automation intensity, rare-earth magnet supply continuity, and cleanroom rail fabrication capacity expansion that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Vibrating Screen Market