
 United States Transportation Infrastructure Construction Market | 2026-2036
United States Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
United States Transportation Infrastructure Construction Market Outlook
Enhanced durability specifications for concrete bridge decks is reorganizing contractor qualification standards across the sector. Bechtel Corporation leverages its integrated engineering-procurement-construction model to capture complex tunnel projects in mountainous terrain. Kiewit Corporation anchors its position through self-performing concrete and steel operations that control schedule risk on billion-dollar interstate corridors.
United States transportation infrastructure construction encompasses the planning, engineering, and physical assembly of mobility systems including highways, bridges, tunnels, and airports, typically requiring Portland cement concrete with minimum 28-day compressive strength of 4,000 psi and asphalt binder grades specified by performance grade testing for thermal cracking resistance. Highway Construction dominates project type segment value due to the scale of interstate rehabilitation and expansion programs, while Public-Private Partnership funding sources represent the fastest-growing capital formation channel as state budgets face pension and healthcare cost pressures. Design-Build contracting methods command premium fee structures by transferring design liability to contractors and compressing project delivery timelines.
FHWA, EPA, and state DOTs enforce Buy America provisions, National Environmental Policy Act reviews, and stormwater management standards that dictate material sourcing and project sequencing. OSHA mandates govern fall protection and trench safety protocols on active construction sites, adding compliance cost layers that influence bid pricing. Stakeholders must monitor how IIJA formula fund allocations interact with inflation-adjusted cost thresholds for major project classification.
Market Dynamics
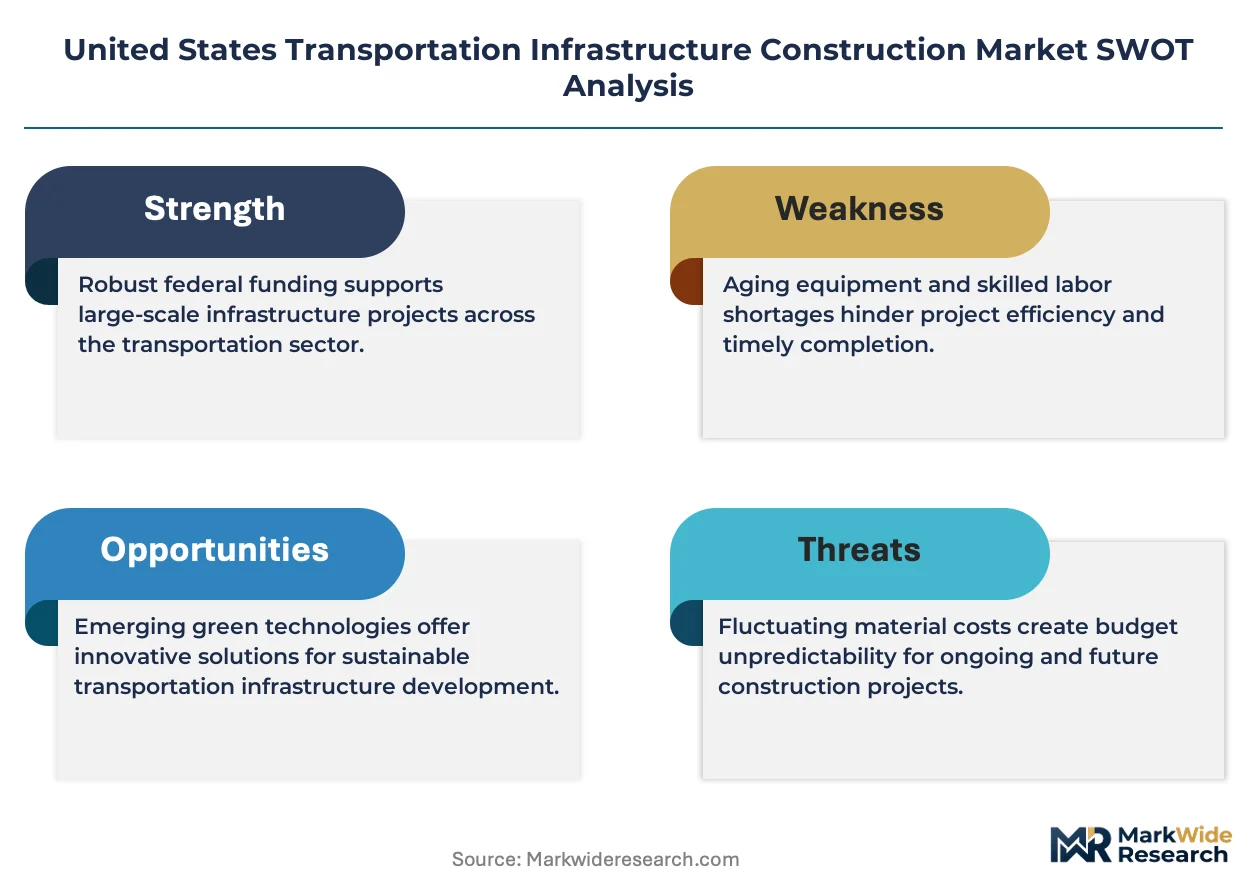
The Infrastructure Investment and Jobs Act has injected sustained federal capital into bridge replacement and electric vehicle corridor development, compressing project timelines while elevating contractor prequalification thresholds for resilient concrete specifications.
Growth Catalysts
- IIJA Formula Funding:Federal highway formula funds flow directly to state DOTs, accelerating procurement cycles for interstate rehabilitation programs in high-migration corridors.
- Texas-California-Florida Population Pressure:Interstate highway demand concentrates where inbound migration strains existing asphalt and concrete networks beyond original design capacity.
- Performance-Grade Asphalt Binder Standards:Advanced thermal cracking resistance specifications drive material upgrades on northern tier highway segments.
Market Restraints
- Domestic Steel and Cement Supply Concentration:Buy America provisions limit sourcing flexibility, exposing projects to regional production bottlenecks and price volatility.
- NEPA Review Duration:Environmental impact statement timelines routinely extend project initiation by 36-48 months, inflating carrying costs and design refresh cycles.
- Skilled Labor Pool Constraints:Operating engineers and ironworker apprenticeship pipelines fail to match project award velocity in Mountain and Southwest states.
Strategic Opportunities
- Public-Private Partnership Capital Formation:Availability payment and toll concession structures attract institutional investors to billion-dollar corridor projects where state pension obligations constrain pay-as-you-go financing.
- Electric Vehicle Charging Corridor Integration:Highway electrification mandates create bundled design-build opportunities combining pavement reconstruction with high-voltage infrastructure.
- Design-Build Contracting Expansion:Single-source liability transfer compresses delivery schedules and commands premium fee structures on complex tunnel and interchange projects.
Industry Challenges
- OSHA Trench Safety Compliance:Excavation protective system mandates add direct cost and schedule risk to utility relocation phases on urban reconstruction sites.
- Stormwater Management Retrofit Complexity:MS4 permit requirements force redesign of drainage systems on legacy interstate segments where right-of-way is fixed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Transportation Infrastructure Construction Market |
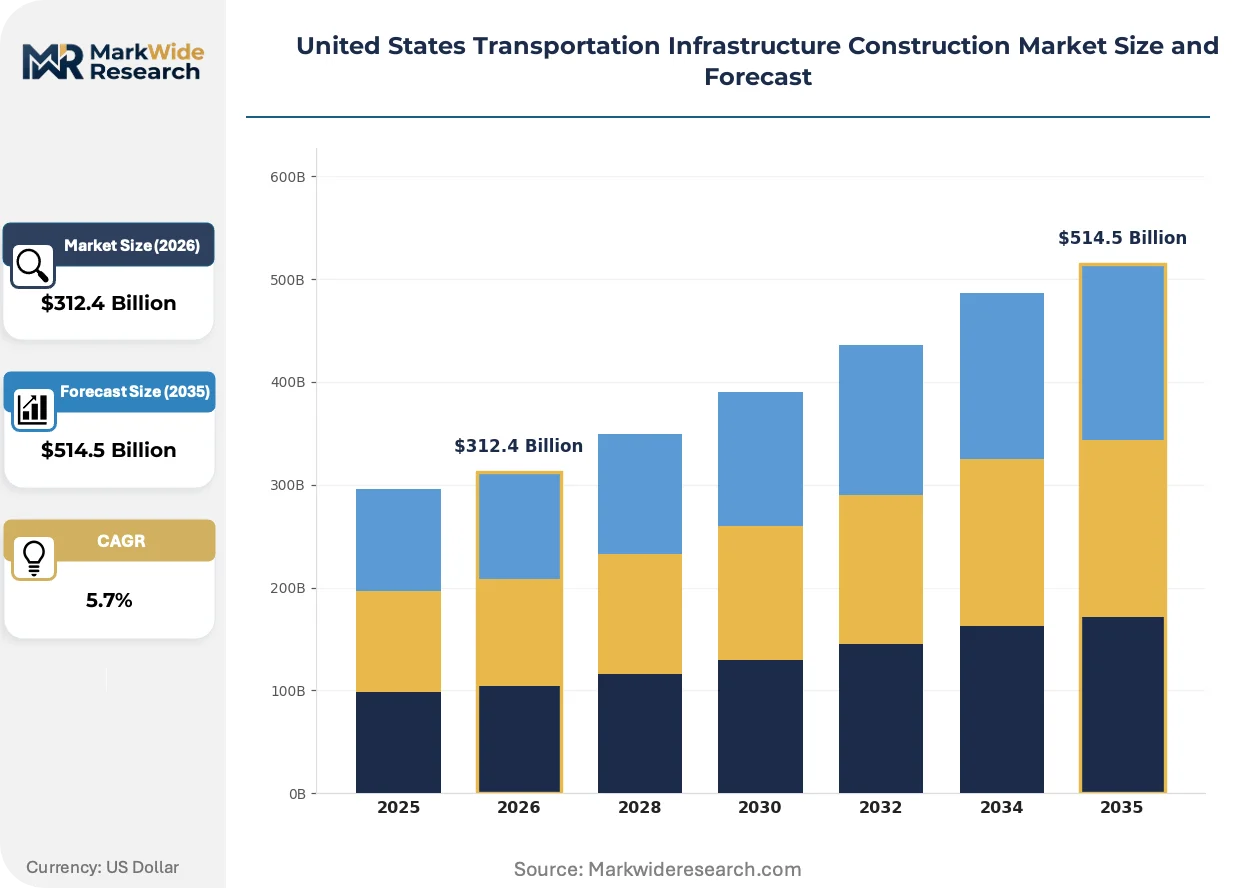
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $514.5 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Highway Construction, Bridge Construction, Tunnel Construction, Airport Development Material Used: Concrete, Steel, Asphalt, Composite Materials Funding Source: Federal Funding, State Funding, Private Investment, Public-Private Partnership Contracting Method: Design-Bid-Build, Design-Build, Construction Manager at Risk, Integrated Project Delivery |
| Companies Covered | Bechtel Corporation, Fluor Corporation, Kiewit Corporation, AECOM, Skanska USA, Turner Construction, Walsh Group, Clark Group, Jacobs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Transportation Infrastructure Construction Market Strategic Shifts
Material science advances and contracting method evolution are compressing project delivery while elevating durability expectations for concrete bridge decks and asphalt pavement systems.
Ultra-high-performance concrete is supplanting conventional deck overlays on major river crossings. State DOTs in coastal and freeze-thaw zones specify fiber-reinforced mixes for 75-year service life targets. The technology is supplanting traditional rehabilitation cycles by eliminating joint maintenance and reducing lane closure frequency.
FHWA Buy America waivers tightened domestic content thresholds for iron and steel products. Contractors now face accelerated sourcing verification requirements that delay submittal approvals. Bridge fabricators in Pennsylvania and Ohio have expanded in-house rolling capacity to maintain compliance without waiver dependency.
Asset owner procurement offices now mandate life-cycle cost analysis over lowest-bid award criteria. Design-build teams respond with alternative technical concepts that trade initial pavement thickness for extended maintenance intervals. This behavior shift is most visible on Texas and California corridor projects where traffic disruption penalties outweigh construction premium costs.
United States Transportation Infrastructure Construction Market Segmentation
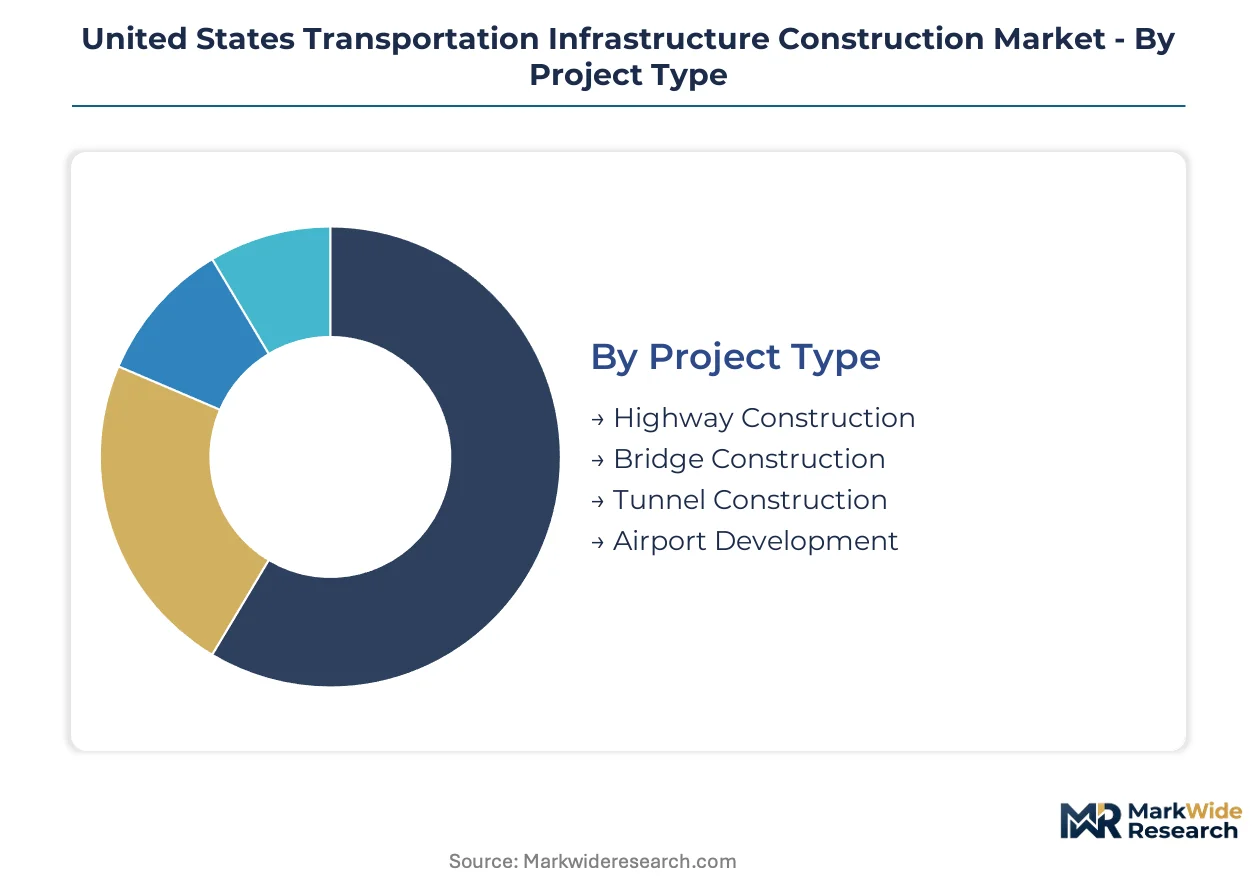
Segmentation reveals how IIJA capital allocation, material specification evolution, and contracting method innovation are fragmenting contractor capabilities across the United States transportation infrastructure construction market. Distinct procurement channels and technical requirements now demand specialized expertise rather than generalist execution.
Project Type:
Domestic demand dominates all project types, with federal formula funding anchoring interstate corridors and state DOT discretion directing bridge and tunnel awards.
- Highway Construction:Interstate rehabilitation and expansion programs specify Portland cement concrete with 4,000 psi minimum compressive strength and performance-grade asphalt binders for thermal cracking resistance. Texas, California, and Florida DOTs concentrate procurement where population migration strains existing networks beyond original design capacity.
- Bridge Construction:Ultra-high-performance concrete deck overlays with fiber-reinforced mixes target 75-year service life in coastal and freeze-thaw zones. FHWA Buy America waivers on steel products tightened domestic content verification, accelerating procurement cycles for major river crossings.
- Tunnel Construction:Mountain corridor projects in Colorado and Pennsylvania require specialized ground stabilization and ventilation system integration.
- Airport Development:Runway reconstruction and terminal expansion concentrates at hubs facing passenger volume recovery.
Highway Construction holds the largest share; momentum sits with Bridge Construction as IIJA prioritizes replacement over maintenance.
Material Used:
Cost tier stratification separates premium specification materials from commodity-grade alternatives, with durability premiums justified through life-cycle cost analysis mandates.
- Concrete:State DOTs specify enhanced durability mixes for bridge decks with fiber reinforcement and low-permeability formulations. Coastal zone agencies in Florida and Gulf states drive demand for corrosion-resistant specifications.
- Steel:Domestic mill capacity constraints under Buy America provisions limit sourcing flexibility for bridge girders and reinforcement. Pennsylvania and Ohio fabricators expanded in-house rolling to maintain compliance.
- Asphalt:Performance-grade binder standards for thermal cracking resistance upgrade northern tier highway specifications.
- Composite Materials:Fiber-reinforced polymer applications expand in bridge deck overlays and structural rehabilitation.
Concrete commands the dominant procurement volume; composite materials are climbing the fastest as agencies validate extended service life claims.
Funding Source:
Application-based segmentation separates entitlement programs from competitive discretionary awards and alternative capital formation structures.
- Federal Funding:IIJA formula funds flow directly to state DOTs through FHWA apportionment, accelerating procurement for interstate rehabilitation. Inflation-adjusted cost thresholds for major project classification determine oversight intensity.
- State Funding:Pay-as-you-go financing faces pressure from pension and healthcare obligations, constraining discretionary awards in Midwest and Northeast states.
- Private Investment:Institutional capital targets availability payment structures on billion-dollar corridor projects.
- Public-Private Partnership:Toll concession and availability payment models attract pension fund investment where state balance sheets face constraint.
Federal Funding maintains the largest commitment base; Public-Private Partnership shows the steepest expansion trajectory as pension capital seeks yield.
Contracting Method:
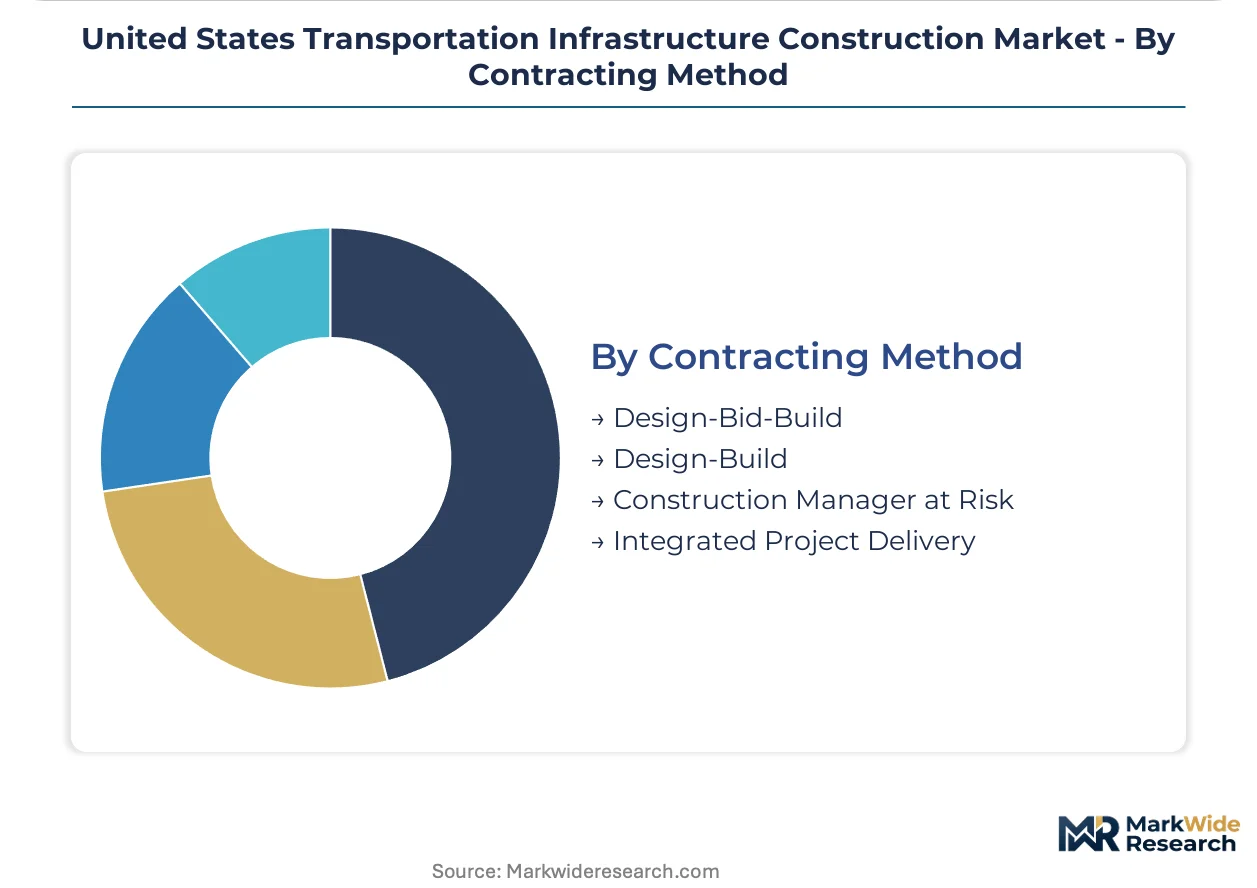
Customer type differentiation separates public agency risk tolerance levels, with progressive methods demanding enhanced contractor prequalification.
- Design-Bid-Build:Traditional sequential procurement remains prevalent for routine maintenance and small-bridge replacement where design complexity is limited.
- Design-Build:Single-source liability transfer compresses delivery schedules and commands premium fee structures on complex tunnel and interchange projects. Texas and California DOTs mandate this method for corridor reconstruction exceeding defined cost thresholds.
- Construction Manager at Risk:Guaranteed maximum price contracts with pre-construction services add cost certainty for urban reconstruction with utility conflict.
- Integrated Project Delivery:Multi-party risk-sharing agreements with shared savings clauses penetrate airport and major transit terminal programs.
Design-Bid-Build retains the largest project count; Design-Build is gaining share fastest as agencies prioritize schedule compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor capacity and material supply chains concentrate in corridors where IIJA formula funding intersects with population-driven demand pressure. State DOT procurement velocity varies sharply based on environmental review timelines and local labor market conditions.
Texas
Interstate expansion programs in the Dallas-Fort Worth and Houston metros absorb the largest share of federal highway formula funds. Texas DOT mandates design-build contracting for corridor projects exceeding defined cost thresholds, compressing traditional procurement cycles. San Antonio and Austin construction clusters face skilled labor constraints as project awards outpace operating engineer apprenticeship completions.
California
Caltrans directs capital toward seismic retrofit and corridor reconstruction in Los Angeles and the Bay Area, where traffic disruption penalties outweigh construction premiums. CEQA review timelines extend project initiation, though Senate Bill 1 gas tax revenues supplement federal dollars. Central Valley contractors specialize in high-volume concrete paving for agricultural freight corridors.
Florida
FDOT prioritizes coastal bridge replacement and hurricane-resilient specifications in the Tampa-Orlando-Miami triangle. Salt-air corrosion drives demand for low-permeability concrete formulations and cathodic protection systems. Northeast Florida fabricators expanded prestressed beam capacity to serve Georgia and South Carolina DOT programs.
Pennsylvania
PennDOT leverages Appalachian tunnel and mountain corridor expertise developed through Pennsylvania Turnpike legacy projects. Pittsburgh and Philadelphia construction clusters anchor steel bridge fabrication under tightened FHWA Buy America verification. Marcellus Shale energy sector competition strains skilled labor availability in the northern tier.
Colorado
CDOT procurement concentrates on Interstate 70 mountain corridor improvements requiring specialized ground stabilization and ventilation integration. Denver-based contractors self-perform rock excavation and shotcrete operations that out-of-state competitors subcontract. Altitude and weather windows compress construction seasons, elevating schedule risk pricing.
United States Transportation Infrastructure Construction Market Competitive Environment
Concentration sits with integrated engineering-procurement-construction operators capable of self-performing concrete and steel work on billion-dollar corridors. The vendor base separates into three tiers: national EPC firms with balance sheet capacity for surety bonding, regional heavy civil contractors with state-specific prequalification, and specialized tunnel or bridge fabricators with niche technical credentials. Consolidation pressure runs through acquisition of mid-tier state DOT prequalified entities and vertical integration into steel fabrication and concrete batching.
Among national EPC operators, Bechtel Corporation, Kiewit Corporation, and Fluor Corporation exemplify the integrated model that controls schedule risk through captive construction execution. Bechtel anchors complex tunnel projects in mountainous terrain where single-source liability transfer commands premium fee structures. Kiewit occupies a position defined by self-performing concrete and steel operations on interstate corridors. Fluor represents the engineering-led archetype with procurement systems designed for federal compliance verification. These three firms collectively illustrate how contractor prequalification thresholds under IIJA favor organizations with demonstrated surety capacity and resilient material specifications expertise.
| Leading Market Players |
|---|
| Bechtel Corporation |
| Fluor Corporation |
| Kiewit Corporation |
| AECOM |
| Skanska USA |
| Turner Construction |
| Walsh Group |
| Clark Group |
| Jacobs |
| Others |
Value Chain & Pricing Dynamics
Design-build contracting with guaranteed maximum price provisions locks in material cost visibility and labor access for multi-year corridor projects. This structure transfers escalation risk to contractors while state DOTs secure delivery certainty under IIJA funding cycles.
Pricing Analysis
FHWA Buy America provisions dictate the pricing tier structure for steel and cement procurement, separating compliant domestic sourcing from waiver-dependent alternatives. Price differentiation hinges on certification grade for ultra-high-performance concrete mixes and volume scale for asphalt binder contracts. Cost compression in standard-grade materials is intensifying because Pennsylvania and Ohio mill capacity constraints limit sourcing flexibility. Municipal buyers exhibit highest price sensitivity on routine maintenance contracts, while design-build teams absorb premium costs on billion-dollar interchanges where schedule penalties dwarf material differentials.
Supply Chain Analysis
Inland waterway congestion on the Mississippi River system elevates inbound logistics costs for bulk cement and aggregate shipments to Gulf Coast project sites. Geographic supply concentration centers on domestic Pennsylvania, Ohio, and Texas steel fabrication capacity alongside regional concrete batching networks. Raw material dependencies encompass Portland cement clinker, performance-grade asphalt binder, and domestic steel rebar. Single-source vulnerability runs through specialized ultra-high-performance concrete admixture suppliers serving coastal bridge programs. Distribution runs through state DOT prequalified contractor networks with captive batching and fabrication assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States transportation infrastructure construction is entering a cyclical upswing. IIJA formula funding anchors federal capital commitment through the mid-2030s.
For Market Incumbents: Secure prequalification status with Texas, California, and Florida DOTs before procurement velocity peaks. Backward integration into steel fabrication and concrete batching insulates margin pressure from Buy America supply bottlenecks. Self-performing operations on interstate corridors differentiates against subcontractor-dependent competitors facing labor shortages. For New Entrants and Emerging Players: State DOT minority contractor certification fast-tracks access to set-aside procurement pools in high-velocity markets. Target bridge deck rehabilitation segments where ultra-high-performance concrete expertise commands premium positioning over generalist highway contractors. Partner with established fabricators for steel component supply to bypass domestic mill queue constraints. For Investors and Strategic Acquirers: Heavy civil contractors with demonstrated surety bonding capacity above defined project thresholds represent the optimal acquisition archetype. Long-term viability rests on IIJA funding continuity and state pension obligation pressures sustaining public-private partnership formation. Monitor FHWA Buy America waiver approval velocity as inflection indicator for domestic steel pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Pennsylvania and Ohio fabricators expanded rolling capacity to eliminate waiver dependency under tightened FHWA verification. |
| Ultra-High-Performance Concrete Certification | State DOTs in coastal zones specify fiber-reinforced mixes for 75-year service life targets on major river crossings. |
| Design-Build Prequalification Investment | Texas and California DOTs mandate single-source liability transfer for corridor projects exceeding defined cost thresholds. |
| Apprenticeship Pipeline Expansion | Operating engineer and ironworker training programs in Mountain states fail to match project award velocity. |
| Public-Private Partnership Structuring | Availability payment models attract pension fund capital where state balance sheets face healthcare and pension constraints. |
Study Parameters
Cross-validation between state DOT procurement databases and FHWA apportionment records anchors the qualitative findings. Primary interviews with state transportation procurement officers, bridge program managers, EPC contractor estimating directors, and steel fabrication executives combined with secondary validation from FHWA obligation reports, state DOT capital improvement plans, and AGC workforce surveys. Bottom-up project pipeline aggregation and top-down federal funding allocation analysis triangulate market sizing.
Sensitivity analysis around IIJA funding reauthorization scenarios and material cost escalation bands stress-tests projection robustness across the analysis window. Segmentation dimensions encompass project type, material specification tier, funding source mechanism, and contracting method complexity. CAGRs derive from weighted average of historical award velocity and announced procurement pipelines. Forecast inputs include population migration patterns and environmental review timeline assumptions.
Decision-makers should treat outputs as directional under sustained federal formula funding and stable Buy America enforcement; material deviation would warrant model refresh. Forecasts reflect assumptions regarding skilled labor availability and domestic steel capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Thailand Data Center Construction Market