
 Loaded Container Handler Market | 2026-2036
Loaded Container Handler Market Size, Share, and Industry Trends Forecast 2026-2036
Loaded Container Handler Market Analytics
Multi-source procurement for critical drivetrain components is hardening across the supplier base. Konecranes Oyj leverages its crane technology heritage to anchor premium reach stacker positions in European ports. Cargotec Corporation sustains broad portfolio coverage across cargo handling equipment categories. Liebherr Group differentiates through in-house manufacturing of structural steel components and hydraulic cylinders.
A loaded container handler denotes heavy material handling equipment engineered to lift, transport, and stack ISO shipping containers, typically achieving lifting capacities between 10 and 50 tons with stacking heights reaching five to six containers high. Its primary industrial purpose centers on enabling efficient container throughput in marine terminals, inland depots, and intermodal rail yards where vessel sizes and cargo volumes demand rapid turnaround cycles. Reach stackers command the largest installed base among product types due to their operational flexibility across varied yard configurations. Electric drive systems represent the fastest-growing technology segment as terminal operators confront Scope 1 emissions targets and total cost of ownership advantages from battery architectures. Telemetry systems embedded in modern fleets generate operational data streams that reshape maintenance contracts and equipment utilization benchmarks.
EPA Tier 4 Final and Stage V emissions frameworks in North America and Europe compel engine re-enginerering and aftertreatment investments that elevate equipment price points and filter fleet renewal timelines. China's GB standards for non-road mobile machinery and SAMR certification requirements create parallel compliance pathways for manufacturers serving domestic and export markets. Stakeholders must monitor how port authority decarbonization mandates interact with equipment financing structures and residual value assumptions across multi-year lease arrangements.
Market Dynamics
EPA Tier 4 Final and Stage V emissions mandates are compressing fleet replacement cycles across marine terminals, forcing terminal operators to reconcile decarbonization timelines with residual value calculations on diesel assets.
Growth Catalysts
- Vessel upsizing:Ultra-large container carriers now dominate Asia-Europe routes, requiring terminals to deploy handlers with 50-ton lifting capacity and six-high stacking reach.
- GB standards compliance:China's SAMR certification pathway for non-road mobile machinery accelerates domestic equipment turnover at automated container terminals.
- Intermodal rail expansion:North American inland ports are adding handler capacity to manage transloading volumes from expanded port rail connections.
Market Restraints
- Aftertreatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add 15-20% to base equipment cost, stretching municipal port authority budgets.
- Battery supply concentration:Lithium-ion cell production clusters in China create procurement vulnerability for European and North American handler OEMs.
- Electric infrastructure gaps:Many legacy terminals lack grid capacity for megawatt-scale charging, delaying full-fleet electrification.
Strategic Opportunities
- Retrofit electrification kits:Aftermarket battery-electric conversion packages open addressable market among operators with young diesel fleets.
- Outcome-based maintenance:Telemetry-enabled uptime guarantees replace traditional parts-and-labor service contracts at automated terminals.
- India port privatization:Adani Ports and JSW Infrastructure expansion programs create demand for handlers at greenfield container terminals.
Industry Challenges
- Mechatronics technician scarcity:Electric drive systems require hybrid skill sets combining high-voltage electrical safety with hydraulic diagnostics.
- Software-hardware integration:Terminal operating system interfaces with handler telemetry demand custom API development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loaded Container Handler Market |
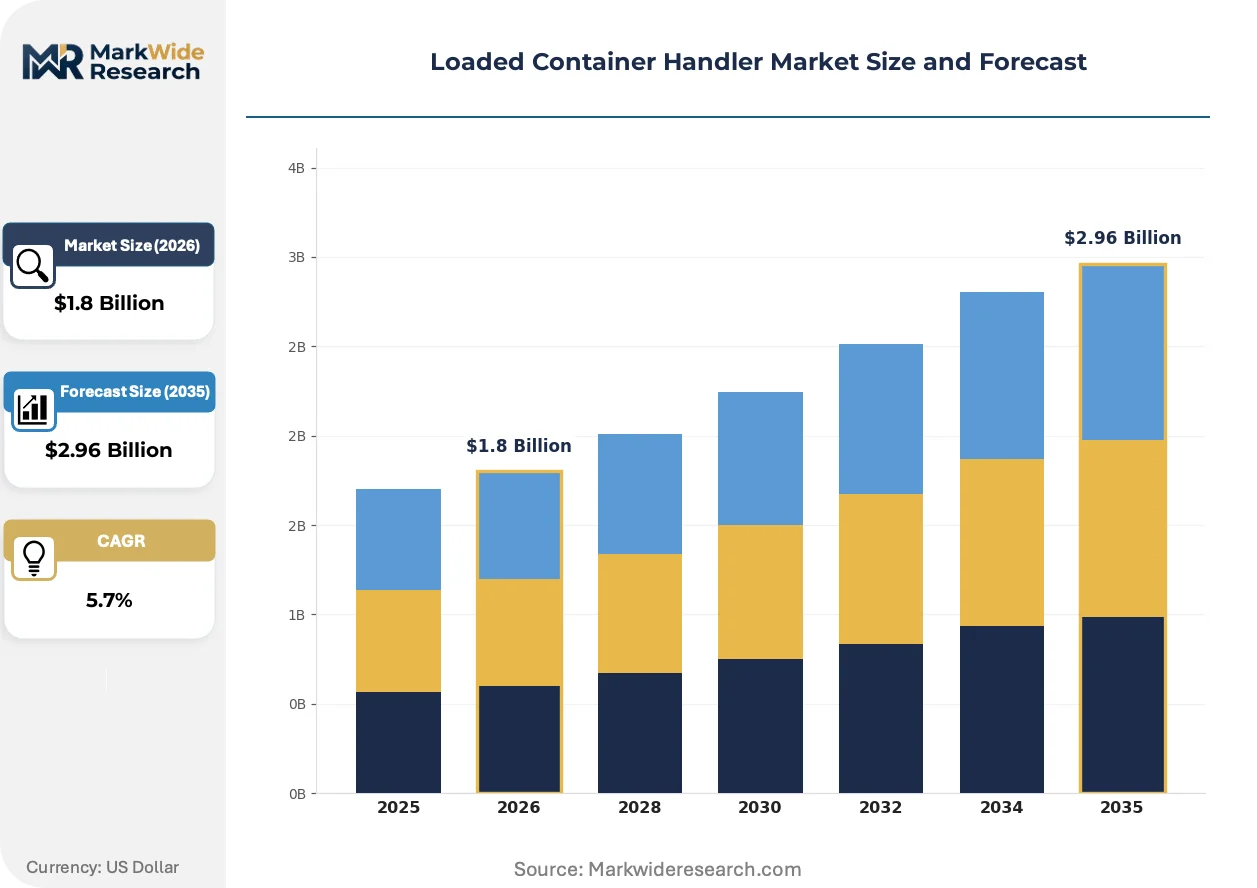
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Forklifts, Reach Stackers, Specialized Cranes, Automated Guided Vehicles Application: Port Operations, Warehouse Management, Intermodal Transport, Cargo Handling End User: Shipping Companies, Freight Forwarders, Logistics Providers, Terminal Operators Technology: Hydraulic Systems, Electric Drive Systems, Telemetry Systems, IoT Integration |
| Companies Covered | Konecranes Oyj, Taylor Group, Cargotec Corporation, PALFINGER AG, Shanghai Zhenhua Heavy Industries, Liebherr Group, Hyster-Yale Materials Handling, Mi-Jack, Sany Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loaded Container Handler Market Evolving Landscape
Battery-electric architectures are absorbing engineering resources across the supplier base, while regulatory deadlines harden and terminal operators seek operational data to justify capital deployment.
Lithium-iron-phosphate battery packs are absorbing the dominant share of new electric handler development. European port operators in Rotterdam and Hamburg are specifying these systems for their second-generation electric fleets. The technology is absorbing price premiums previously assigned to diesel-electric hybrids, compressing that intermediate category's market position.
EPA Tier 4 Final compliance deadlines in the United States and Stage V frameworks in the European Union are forcing engine re-engineering investments that elevate equipment price points. OEMs are passing aftertreatment costs to buyers while extending lease terms to maintain monthly payment affordability. The regulatory pressure is concentrating most acutely on North American independent terminal operators with limited access to green financing.
Telemetry-enabled utilization tracking is reshaping how terminal operators procure handler capacity. Marine terminals in Singapore and Los Angeles are unbundling equipment purchase from maintenance services, selecting vendors based on guaranteed uptime metrics. This shift is visible most clearly at automated container terminals where downtime costs exceed $100,000 per hour.
Loaded Container Handler Market Segmentation
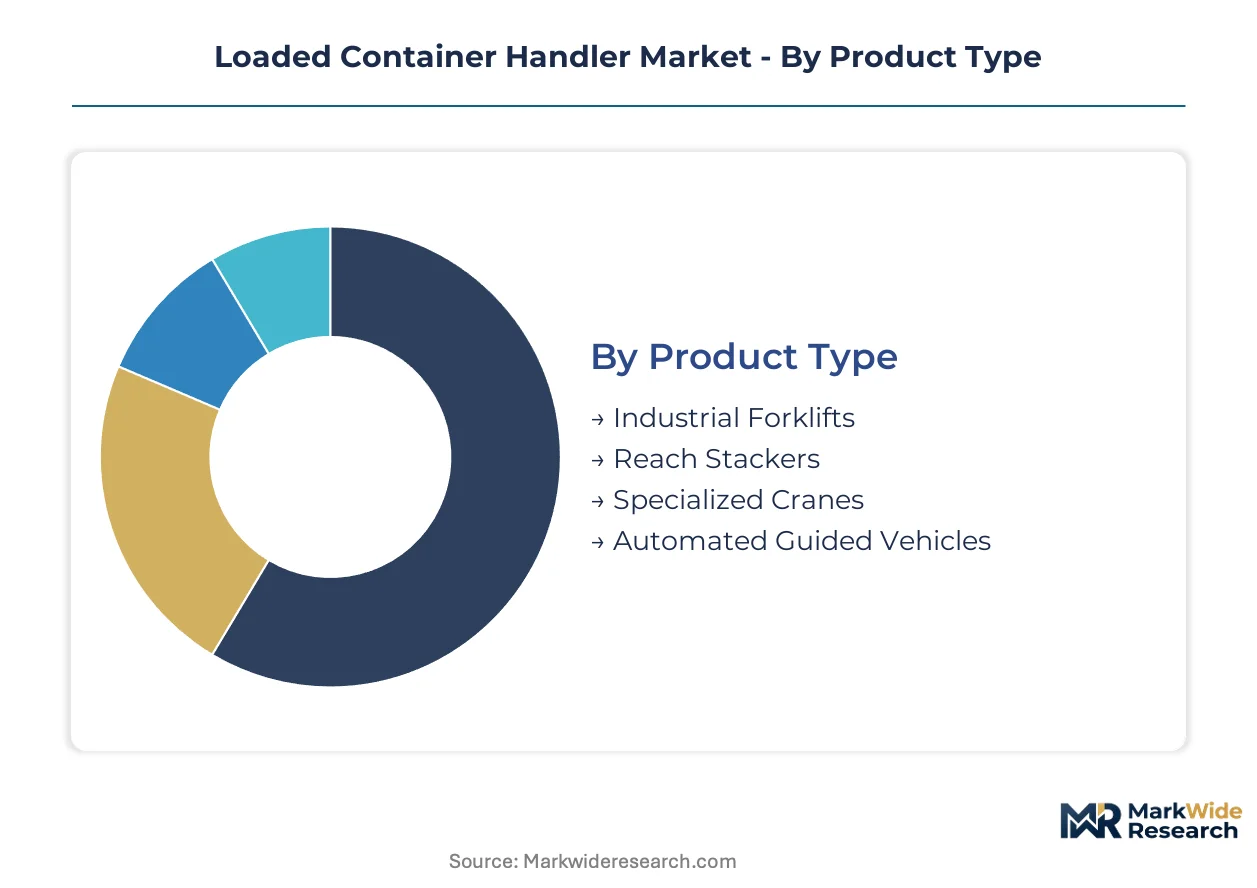
Equipment specification varies sharply across terminal configurations and cargo profiles. Buyers prioritize lifting capacity, stacking height, and powertrain architecture based on vessel call patterns and yard automation roadmaps.
Product Type:
Terminal layout density and vessel size distribution determine equipment selection more than purchase price.
- Reach Stackers:These machines combine front-loading container handling with road mobility, achieving stacking heights up to six containers and lifting capacities between 35 and 50 tons. Demand concentrates at medium-volume terminals in Germany and the Netherlands where yard flexibility outweighs pure throughput speed. Rotterdam's second-tier terminals favor reach stackers for their ability to reposition quickly between vessel berths.
- Automated Guided Vehicles:Battery-electric autonomous units operate within fenced terminal zones under central control system direction, eliminating operator cabs and enabling 24-hour continuous operation. Singapore's Tuas terminal and Los Angeles' automated berths are absorbing the largest deployments as labor cost arbitrage justifies infrastructure investment.
- Industrial Forklifts:Compact container handlers serve inland depots and rail yards with lower stacking requirements.
- Specialized Cranes:Rail-mounted and rubber-tired gantry systems dominate high-density Asian mega-terminals.
Reach stackers lead on installed base scale; automated guided vehicles lead on deployment momentum.
Application:
Operational intensity and vessel turnaround pressure create distinct equipment performance thresholds.
- Port Operations:Marine terminal applications demand handlers capable of 50-ton lifts and rapid container cycling to match ultra-large carrier discharge rates. China's automated terminals at Shanghai and Ningbo-Zhoushan are specifying electric drive systems exclusively for new quay-side equipment as SAMR certification timelines compress.
- Intermodal Transport:Rail yard and barge terminal operations require handlers with roading capability to bridge container movements between modes. North American inland ports along the Chicago-St. Louis corridor are adding capacity to manage transloading volumes from expanded port rail connections.
- Warehouse Management:Indoor container storage facilities prioritize compact turning radius and emission-free operation.
- Cargo Handling:General freight terminals utilize multi-purpose equipment for mixed container and breakbulk operations.
Port operations dominate capital deployment; intermodal transport is expanding most quickly.
End User:
Ownership structure and financing access shape procurement timing and technology risk tolerance.
- Terminal Operators:Dedicated marine terminal companies with long-term port concessions amortize equipment over 15-year depreciation schedules. PSA International and DP World are bundling handler procurement with terminal operating system upgrades to capture telemetry-enabled utilization data.
- Shipping Companies:Ocean carriers with dedicated terminal assets prioritize equipment standardization across their global port networks. Maersk's terminal operating unit is consolidating supplier relationships to simplify spare parts logistics and technician training.
- Freight Forwarders:Third-party logistics providers favor leased equipment with maintenance-inclusive contracts.
- Logistics Providers:Integrated supply chain operators select handlers based on intermodal connectivity requirements.
Terminal operators lead on fleet scale; shipping companies lead on standardization momentum.
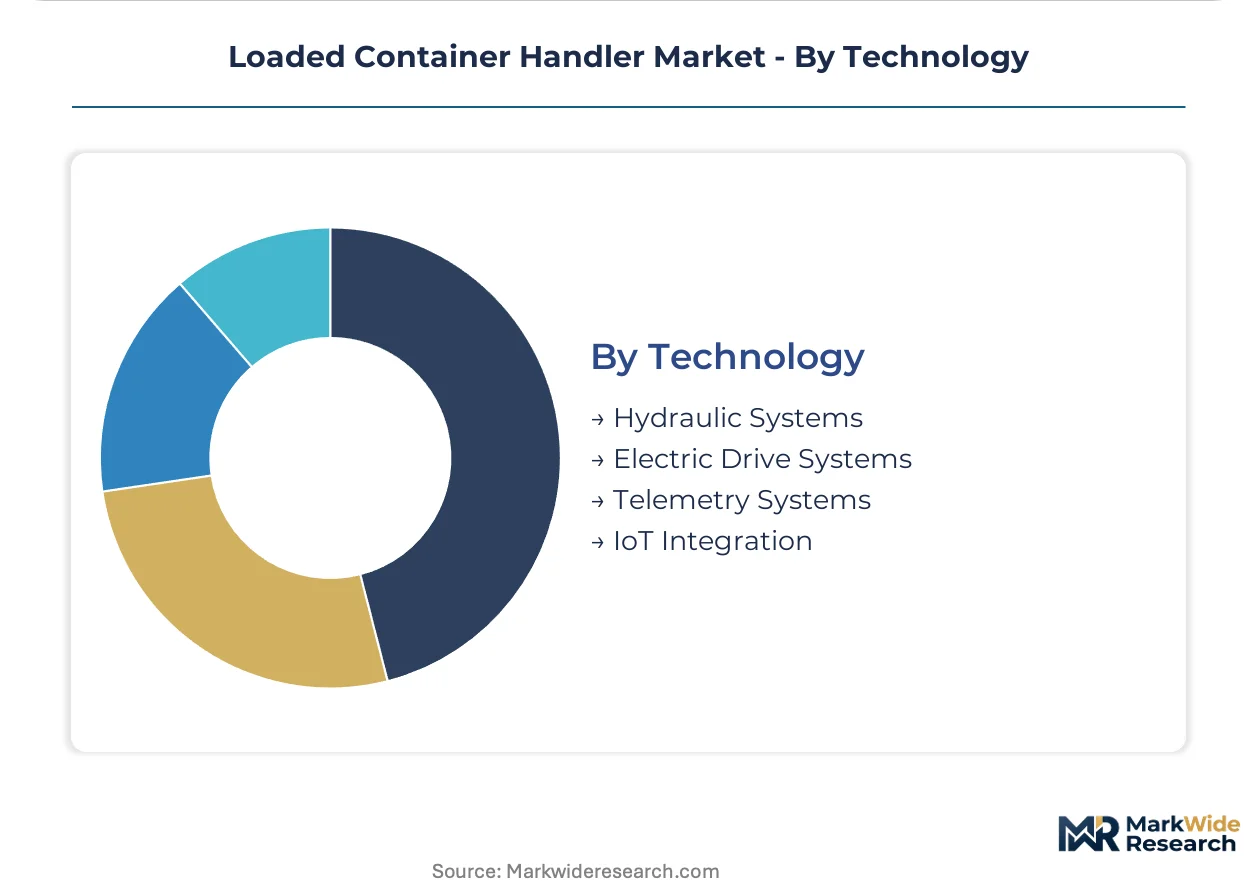
Technology:
Powertrain architecture and data connectivity now dominate total cost of ownership calculations.
- Electric Drive Systems:Battery-electric architectures eliminate diesel aftertreatment complexity while delivering torque characteristics suited to container lifting cycles. European port operators in Hamburg and Antwerp are specifying lithium-iron-phosphate packs for second-generation electric fleets as grid capacity expands.
- Telemetry Systems:Embedded sensors transmit operational data on fuel consumption, lift cycles, and component stress to enable predictive maintenance. Singapore's automated terminals are unbundling equipment purchase from uptime-guaranteed service contracts based on telemetry feeds.
- Hydraulic Systems:Conventional fluid power architectures persist in heavy-lift applications beyond current electric motor ratings.
- IoT Integration:Terminal operating system connectivity enables fleet-wide coordination and real-time positioning.
Hydraulic systems lead on current installed base; electric drive systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence on emissions compliance is redirecting procurement flows toward jurisdictions where green financing subsidizes equipment turnover. Terminal operators in low-subsidy environments delay fleet renewal, creating a cost-of-compliance arbitrage that advantages ports with concessional credit access.
China
Shanghai and Ningbo-Zhoushan terminals are absorbing the largest volumes of automated container handling equipment under SAMR certification timelines. GB standards for non-road mobile machinery are compressing domestic equipment replacement cycles. The Yangtze River Delta port cluster is specifying electric drive systems exclusively for new quay-side installations.
United States
EPA Tier 4 Final mandates are forcing independent terminal operators in Los Angeles and Long Beach to reconcile residual value calculations on diesel assets. The Port of Los Angeles is unbundling equipment procurement from uptime-guaranteed service contracts. Midwest inland ports along the Chicago-St. Louis corridor are adding handler capacity for transloading volumes.
Germany
Stage V emissions frameworks are elevating equipment price points at Hamburg and Bremerhaven terminals. Rotterdam's second-tier terminals favor reach stackers for flexibility between vessel berths. The country's port operators are specifying lithium-iron-phosphate battery packs for second-generation electric fleets.
Singapore
Tuas terminal is absorbing the largest deployments of battery-electric autonomous units under central control system direction. The Maritime and Port Authority's decarbonization mandates are reshaping equipment financing structures. PSA International is bundling handler procurement with terminal operating system upgrades.
India
Adani Ports and JSW Infrastructure expansion programs are creating demand at greenfield container terminals in Gujarat and Maharashtra. The country's national port regulator is privatizing terminal operations under long-term concession agreements. Jawaharlal Nehru Port Trust is modernizing yard equipment to handle larger vessel calls.
Loaded Container Handler Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and automation adjacencies. The supplier base concentrates around crane technology heritage and in-house manufacturing capabilities. Three archetypes dominate: diversified industrial conglomerates with captive steel production, specialized cargo handling equipment manufacturers, and port automation system integrators. Competitive moves center on strategic partnerships for battery supply and geographic expansion through terminal operator alliances.
Among European-based fabricators, Konecranes Oyj and Liebherr Group occupy positions anchored in crane technology heritage and in-house structural steel production. Cargotec Corporation represents the diversified cargo handling archetype with broad portfolio coverage. These three exemplify how engineering depth in adjacent heavy equipment categories translates into handler market positioning.
| Leading Market Players |
|---|
| Konecranes Oyj |
| Taylor Group |
| Cargotec Corporation |
| PALFINGER AG |
| Shanghai Zhenhua Heavy Industries |
| Liebherr Group |
| Hyster-Yale Materials Handling |
| Mi-Jack |
| Sany Group |
| Others |
Value Network & Pricing Analysis
Battery-electric powertrain transitions are simultaneously elevating upfront equipment costs and redistributing supplier power toward lithium-ion cell producers. This technology shift compresses margins for diesel-focused fabricators while concentrating procurement leverage among handlers of high-voltage battery systems and thermal management components.
Pricing Analysis
Distributor margins of 12-18% separate OEM factory gates from terminal operator acquisition costs across European and North American markets. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier 4 Final certification status, electric drive architecture, and telemetry integration depth. Cost compression in mid-tier diesel configurations is intensifying because aftertreatment systems now absorb 15-20% of base equipment cost. Municipal port authorities exhibit highest price sensitivity due to constrained capital budgets, while automated terminal operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese, South Korean, and Japanese producers, with CATL and BYD controlling cathode material refining capacity. Structural steel plate, high-pressure hydraulic cylinders, and permanent magnet motors constitute critical component inputs. Single-source vulnerability concentrates in rare earth magnet supply chains tethered to Chinese separation facilities. Distribution runs through OEM-direct sales teams at major terminal operators and specialized heavy equipment dealers serving mid-tier ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 4 Final and Stage V emissions deadlines force fleet turnover regardless of underlying cargo volume trends. Equipment procurement cycles are compressing as compliance timelines override residual value optimization.
For Market Incumbents: Anticipate battery supply allocation battles by securing long-term lithium-iron-phosphate cell offtake agreements with CATL or BYD before capacity constraints harden. Deepen in-house production of structural weldments and hydraulic cylinders to defend margin position against emerging electric-only entrants. Terminal operator consolidation into mega-ports threatens distributor networks, making direct service capability investment essential for equipment attach rates.
For New Entrants and Emerging Players: Enter via aftermarket retrofit electrification kits targeting young diesel fleets at independent North American terminals where full fleet replacement is capital-prohibitive. India's greenfield port privatization under Adani Ports and JSW Infrastructure expansion offers the most penetrable geography with limited incumbent service infrastructure. Position around telemetry-enabled uptime guarantees rather than equipment sales to bypass capital intensity barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among diversified industrial conglomerates with stranded diesel handler portfolios awaiting electrification transition costs. Long-term viability favors suppliers with captive battery partnerships and terminal operator alliance networks. Watch lithium-iron-phosphate price trajectories as the inflection signal determining electric handler total cost of ownership parity timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term lithium-iron-phosphate cell offtake secures production allocation against CATL capacity constraints. |
| Retrofit Electrification Kit Launch | Aftermarket battery-electric conversion opens addressable market among young diesel fleet operators. |
| Terminal Operator Alliance | PSA International and DP World bundling contracts reward vendors with telemetry integration capability. |
| In-House Structural Manufacturing | Liebherr Group's captive steel production model defends margin against commodity price volatility. |
| Outcome-Based Maintenance Contract | Singapore's automated terminals unbundle equipment purchase from uptime-guaranteed service agreements. |
Research Methodology
Bottom-up terminal operator procurement modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with marine terminal maintenance directors, port authority capital planning officers, heavy equipment procurement teams, and aftermarket service heads were validated against secondary sources including EPA compliance filings, SAMR certification databases, port authority capital expenditure disclosures, and customs trade records for container handler imports. This dual approach enables cross-verification of equipment deployment timelines against manufacturer order backlogs.
Historical trendline analysis of fleet replacement cycles, vessel size distributions, and emissions compliance deadlines established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type, powertrain architecture, terminal automation level, and regional regulatory framework. CAGRs were derived from equipment unit deployment trajectories and average selling price evolution across diesel, hybrid, and battery-electric configurations. Forecast inputs included port throughput projections, intermodal rail expansion plans, and grid capacity expansion timelines at major terminal clusters.
The model holds under stable emissions enforcement and battery cost decline trajectories; deviation in lithium supply disruptions or port privatization delays would shift replacement cycle timing. Forecasts reflect documented assumptions regarding SAMR certification timelines and EPA enforcement consistency. A small set of named triggers warrants ongoing watch: battery cell price volatility, terminal operator consolidation patterns, and grid infrastructure deployment at legacy port facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Global Precision Gearboxes Market