
 Roll Handling Machine Market | 2026-2036
Roll Handling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Roll Handling Machine Market Analytics
Market Context
Mid-sized packaging converters is rotating toward automated roll handling as labor costs and injury liability reshape procurement priorities. Schlumpf leverages its vertical integration into custom-engineered lifting mechanics to serve narrow-web converters with application-specific builds. R&D ERGO sustains technology leadership in ergonomic assist devices, anchoring its position in European tissue and hygiene markets where operator safety mandates command premium positioning. Packline competes on manufacturing scale across standard electric roll lifter platforms, while ASE Systems specializes in integrated vacuum and mechanical handling configurations for sensitive substrates.
Technical Definition and Segment Structure
Roll handling machines are industrial material handling systems engineered to lift, transport, rotate, and position cylindrical loads—typically paper, film, foil, or textile rolls—with load capacities spanning from light-duty manual units below 200 kg to ultra heavy capacity electric systems exceeding 5,000 kg, employing mechanical, hydraulic, pneumatic, or electric actuation to eliminate manual lifting injuries and accelerate changeover times in continuous production environments. Electric roll lifters capture expanding share as plant electrification initiatives and energy efficiency specifications displace legacy hydraulic units in plastics and textile verticals. Heavy capacity and ultra heavy capacity segments concentrate margin pools where engineering complexity and safety certification requirements limit vendor participation, while manual roll lifters occupy mature demand in small-batch manufacturing where capital constraints persist.
Regulatory Frame and Outlook
OSHA ergonomic standards in the United States, EU machinery directives with CE marking requirements, and ISO 3691 safety standards for industrial trucks collectively shape product design, mandating load stability controls, emergency lowering functions, and operator presence sensing that elevate engineering costs but bar uncertified imports. Germany's KBA-influenced industrial safety culture and the EU Green Deal's embodied carbon tracking for production equipment add compliance layers that favor regional manufacturers with established certification pathways. Stakeholders must monitor how machinery-as-a-service financing models and predictive maintenance integration reshape vendor-customer relationships beyond equipment transactions.
Market Dynamics
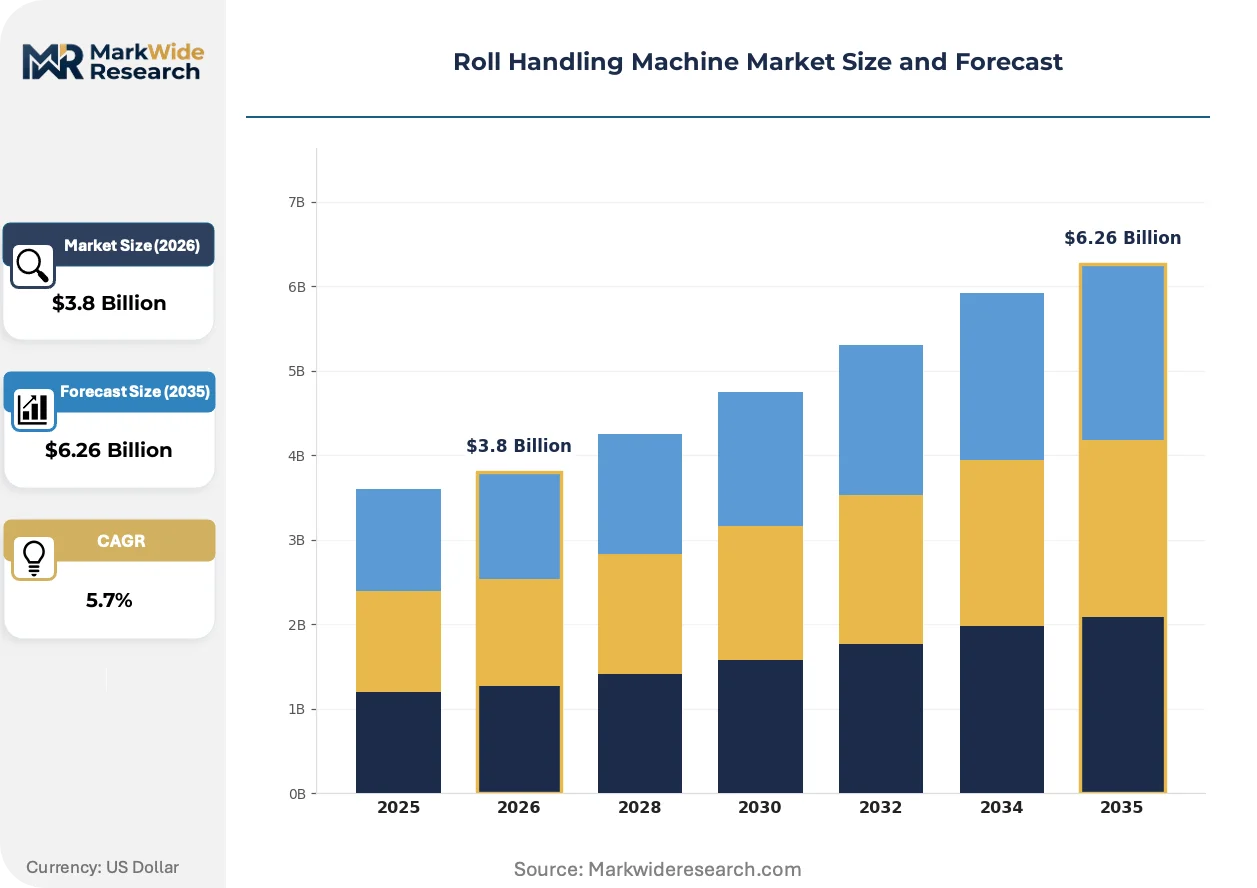
Plant electrification mandates and OSHA ergonomic enforcement are converging to accelerate displacement of hydraulic roll handling systems across North American and European converting operations.
Growth Catalysts
- EU Machinery Directives:CE marking requirements for emergency lowering functions and load stability controls are compelling packaging converters to upgrade legacy equipment, expanding replacement demand.
- Tissue manufacturing automation:Hygiene product lines are integrating electric roll lifters to achieve continuous production speeds while satisfying operator safety mandates.
- German converting machinery clusters:OEM specification intensity around integrated roll handling solutions is pulling advanced system adoption across European packaging supply chains.
Market Restraints
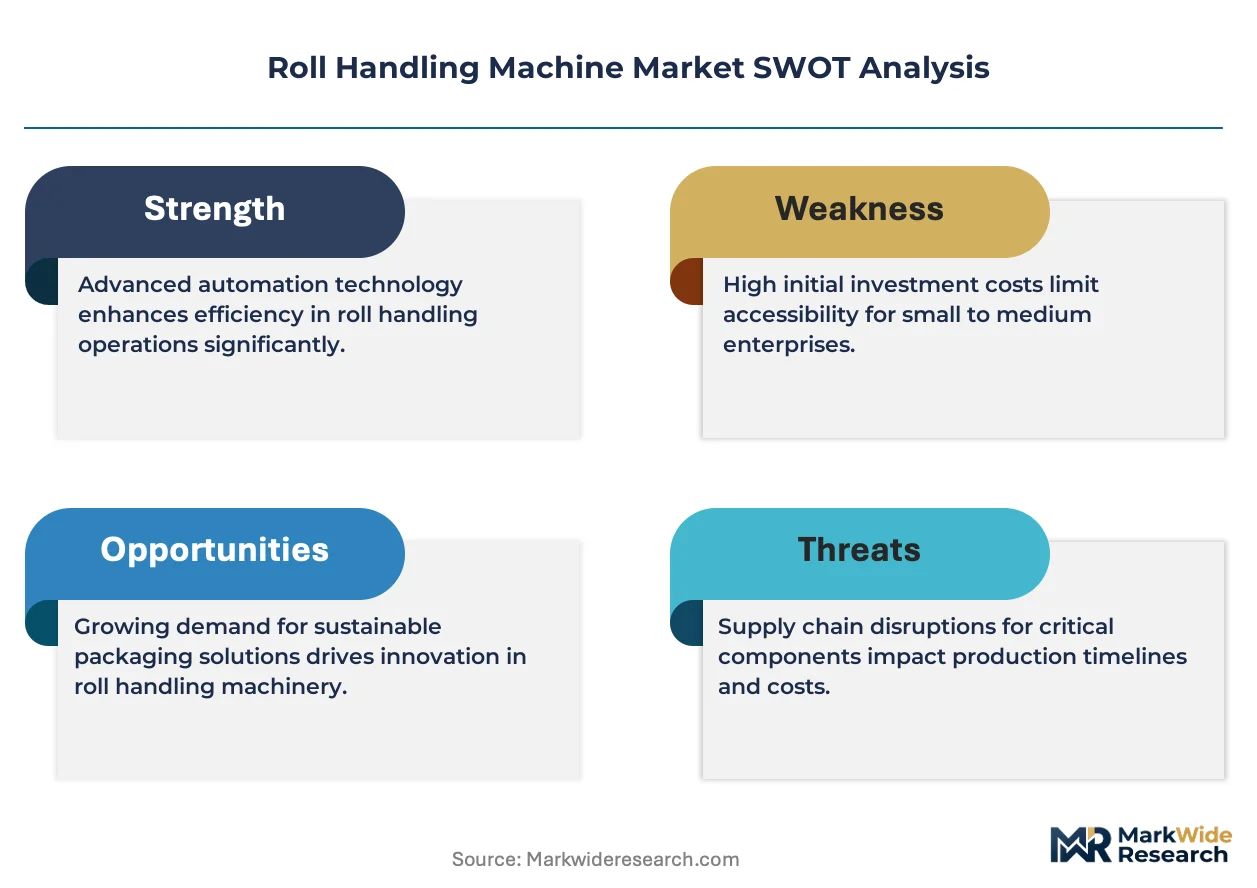
- Specialized steel alloy costs:Input price volatility for high-grade structural materials used in heavy capacity lifting frames compresses margin pools for standard equipment vendors.
- Certification timeline friction:ISO 3691 compliance documentation and third-party safety validation extend sales-to-revenue cycles by 4-8 months for non-European suppliers.
- Manual handling persistence:Small-batch manufacturers with capital constraints continue deploying basic mechanical lifters, capping premium equipment penetration in artisanal segments.
Strategic Opportunities
- India packaging expansion:BIS industrial safety standard adoption and PLI scheme incentives for paper converting are creating first-mover positioning for certified electric roll lifter suppliers.
- Predictive maintenance convergence:IoT sensor integration with existing fleet management platforms enables machinery-as-a-service financing models among mid-sized tissue producers.
- Sensitive substrate handling:Vacuum-mechanical hybrid configurations for optical film and battery separator rolls address emerging demand from electric vehicle supply chains.
Industry Challenges
- Mechatronics skill scarcity:Maintenance technician shortages for electric actuator systems and PLC-controlled safety interlocks constrain post-installation service scalability.
- Legacy hydraulic integration:Retrofit complexity with existing pneumatic infrastructure and plant floor layouts extends deployment timelines and inflates project engineering costs.
- CE marking documentation:Technical file assembly for EU market entry demands specialized regulatory expertise that smaller vendors struggle to resource internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll Handling Machine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Roll Lifters, Electric Roll Lifters, Specialized Roll Trucks, Roll Positioners Industry Vertical: Manufacturing, Paper & Pulp, Plastics, Textile Capacity: Light Capacity, Medium Capacity, Heavy Capacity, Ultra Heavy Capacity Technology: Hydraulic, Pneumatic, Mechanical, Electric |
| Companies Covered | Schlumpf, R&D ERGO, Tilt-Lock, Packline, ASE Systems, Torros, AZTECH Converting System, Easy Lift Equipment, Dotec B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll Handling Machine Market Evolving Landscape
Electrification, predictive connectivity, and service model restructuring are rewriting competitive requirements across roll handling equipment procurement.
Electric linear actuator systems are displacing hydraulic power units in heavy capacity roll lifters, delivering precision positioning and energy recovery that converters in Germany and the United States now specify as baseline requirements. Plastics extrusion and textile winding operations are accelerating adoption as plant electrification roadmaps eliminate fossil-fluid infrastructure. This transition is compressing aftermarket parts revenue for hydraulic component suppliers while elevating vendor R&D requirements for motor-drive integration.
REACH substance restrictions and EU Green Deal embodied carbon tracking are mandating material disclosure and lifecycle documentation for production equipment sold into European markets. Machinery OEMs must now certify steel sourcing, coating chemistries, and end-of-life recyclability to maintain specification eligibility with major converting groups. German tissue manufacturers are responding by embedding carbon accounting into capital equipment tenders, favoring regional suppliers with established environmental product declaration pathways.
Outcome-based service contracts are unbundling traditional equipment sales from maintenance obligations, with uptime guarantees and per-roll handling fees replacing outright purchase models among large packaging converters. Distributor and integrator channels in the United States are restructuring commission structures to capture recurring revenue streams. This behavioral shift is most pronounced in corrugated board and flexible packaging verticals where production continuity commands premium positioning.
Roll Handling Machine Market Segmentation
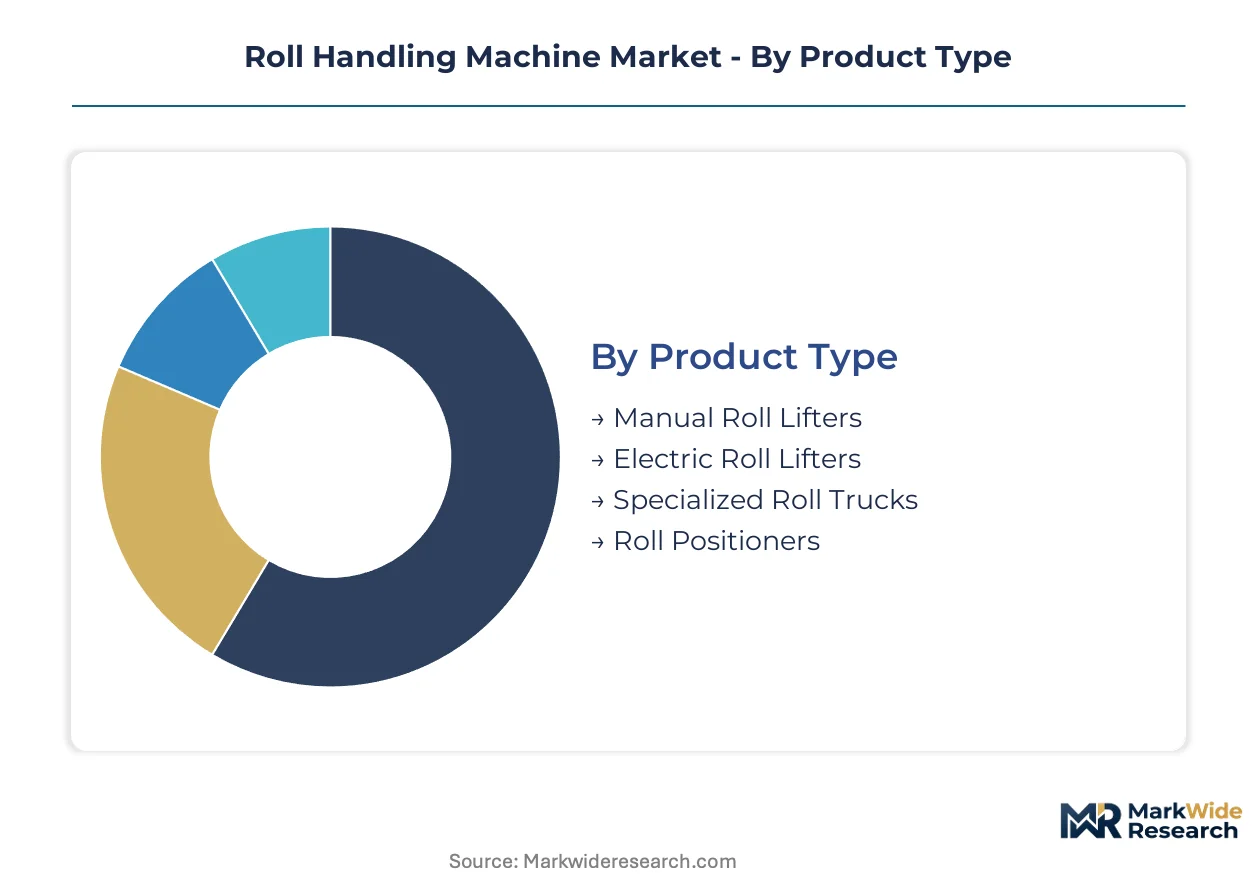
Roll handling equipment procurement diverges sharply by operational scale and substrate sensitivity, with automation intensity and safety mandates fragmenting vendor addressable markets across converting verticals. Segment boundaries increasingly blur as electric actuation platforms absorb functions previously served by distinct mechanical and hydraulic categories.
Product Type:
Electric roll lifters face the most acute substitution pressure from integrated robotic handling systems in high-volume tissue plants, while manual units confront ergonomic compliance phase-outs across OECD jurisdictions.
- Manual Roll Lifters:Lever-operated and hand-cranked units under 500 kg capacity serve small-batch converters and artisanal textile operations where capital constraints override automation roadmaps. Demand concentrates in India and Southeast Asian packaging clusters where BIS safety standards remain partially enforced and labor cost arbitrage sustains mechanical handling economics.
- Electric Roll Lifters:Precision motor-drive systems with programmable positioning and energy recovery dominate German and United States converting specifications, displacing hydraulic alternatives as plant electrification mandates harden. Tissue manufacturers in the EU specify these units to satisfy CE marking requirements for emergency lowering and operator presence sensing.
- Specialized Roll Trucks:Self-propelled transporters for cleanroom and food-contact environments serve pharmaceutical film and flexible packaging converters requiring washdown-rated construction.
- Roll Positioners:Turntable and upender configurations for unwind/rewind line integration address narrow-web label and battery separator producers.
Manual roll lifters retain volume leadership in unit shipments; electric roll lifters hold the steepest expansion curve.
Industry Vertical:
Cost tier stratification separates capital-intensive continuous producers from batch-oriented converters, with paper and pulp commanding premium engineered systems while plastics tolerates standardized platforms.
- Paper & Pulp:Tissue and hygiene manufacturers in Germany and the United States deploy heavy capacity electric systems with IoT-enabled predictive maintenance to sustain 24/7 production continuity. OSHA ergonomic enforcement and EU machinery directives mandate load stability controls that elevate specification intensity beyond other verticals.
- Manufacturing:General industrial applications span automotive interior textiles and appliance insulation rolls where handling precision matters less than throughput economics.
- Plastics:Film and sheet extruders in North American packaging corridors favor standardized electric lifters as hydraulic infrastructure retirement accelerates under corporate decarbonization commitments.
- Textile:Winding and weaving operations in regional clusters demand specialized positioners for delicate yarn and fabric rolls where surface damage rejection rates drive equipment selection.
Paper and pulp commands the highest average selling prices; plastics generates the largest installed base volume.
Capacity:
Margin concentration intensifies at load extremes, with ultra heavy capacity units capturing engineering premiums while light capacity segments suffer commoditization from Asian metal fabrication imports.
- Heavy Capacity:Electric systems rated 2,000-5,000 kg serve parent roll handling in integrated pulp-to-tissue mills where single-roll value exceeds equipment capital cost. German OEM specification networks and KBA-influenced safety culture sustain regional vendor preference in European installations.
- Ultra Heavy Capacity:Custom-engineered platforms exceeding 5,000 kg address specialty paper and metalized film rolls where structural steel alloy selection and finite element analysis certification limit qualified supplier pools to vertically integrated lifting specialists.
- Light Capacity:Units below 500 kg occupy mature demand in job shop converting and prototype film development labs.
- Medium Capacity:500-2,000 kg electric platforms dominate mid-tier packaging converter upgrade cycles as OSHA enforcement tightens.
Heavy capacity retains the deepest margin pool; ultra heavy capacity is climbing the fastest as battery separator and optical film rolls densify.
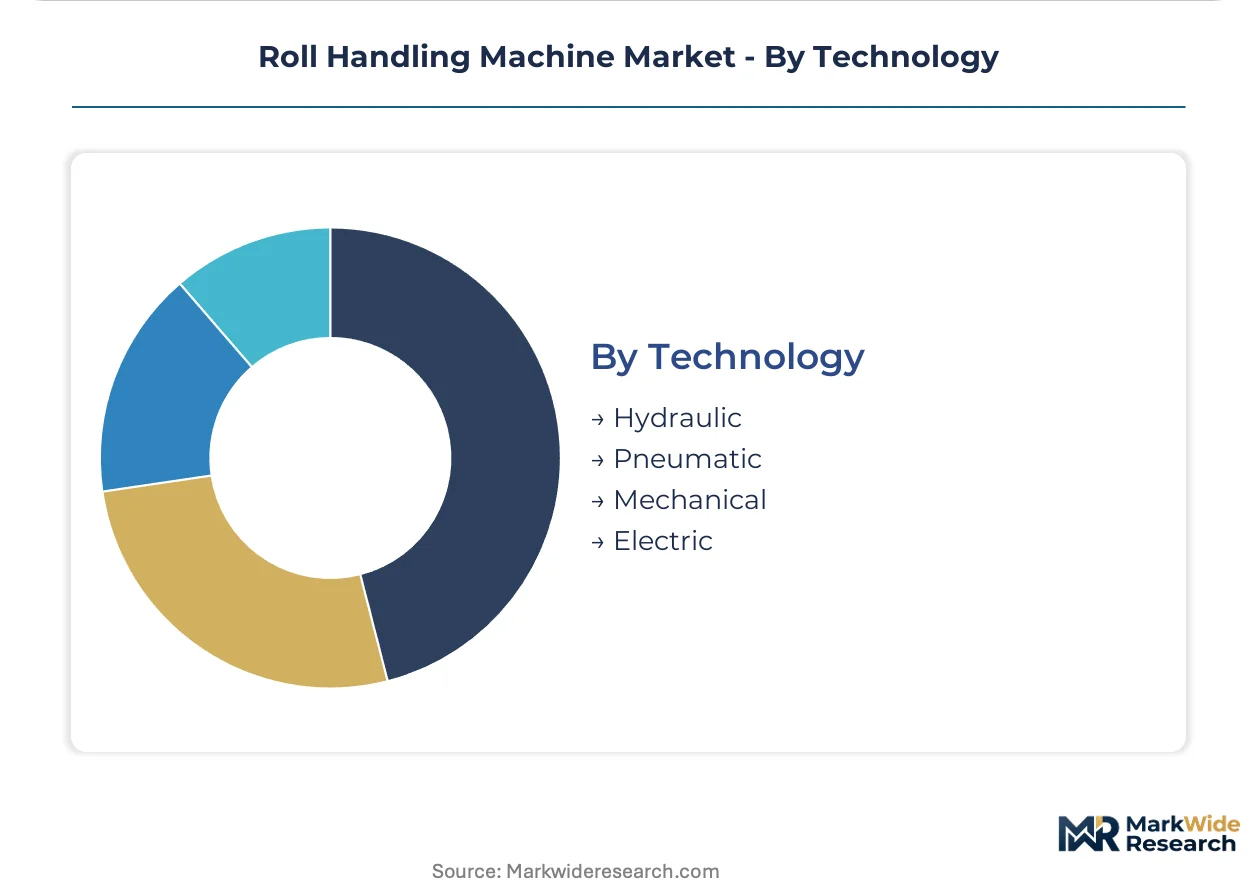
Technology:
Application requirements dictate actuation selection, with cleanroom and food-contact environments excluding hydraulic fluids while explosive atmosphere codes constrain electric motor options.
- Electric:Linear actuator and servo-motor systems deliver precision positioning with regenerative braking, specified by German and United States converters as baseline for new capital projects. Plant electrification roadmaps and REACH substance restrictions on hydraulic fluids accelerate displacement across plastics and textile verticals.
- Hydraulic:Legacy power units persist in heavy capacity applications where existing infrastructure amortization delays replacement, though maintenance cost escalation and energy efficiency penalties erode competitiveness.
- Pneumatic:Compressed-air systems serve explosion-sensitive chemical film and solvent-based coating operations where electric spark risk commands process safety priority.
- Mechanical:Hand-crank and ratchet mechanisms occupy residual demand in capital-constrained small-batch manufacturing and developing economy installations.
Electric technology commands specification momentum; pneumatic retains defensive positioning in hazardous environment niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites Europe's converting machinery import corridor, while Germany's Rhine-Ruhr rail network distributes capital equipment inland to tissue and packaging clusters.
United States
OSHA ergonomic enforcement and corrugated packaging automation drive electric roll lifter procurement across Midwest converting corridors. The Infrastructure Investment and Jobs Act channels federal investment into domestic manufacturing reshoring. Wisconsin and Ohio paper converting clusters are upgrading legacy hydraulic systems to satisfy injury liability mitigation mandates.
Germany
EU Machinery Directive CE marking requirements and KBA-influenced industrial safety culture elevate specification intensity for integrated roll handling solutions. The EU Green Deal's embodied carbon tracking mandates material disclosure for production equipment tenders. Baden-Württemberg and North Rhine-Westphalia converting machinery OEM clusters pull advanced system adoption across European supply chains.
China
Dual carbon goals and MIIT industrial equipment electrification directives accelerate displacement of hydraulic handling systems in Yangtze River Delta packaging zones. GB standards for industrial machinery safety are tightening lift-assist requirements. Shanghai and Jiangsu province film extrusion clusters are specifying electric actuation platforms to satisfy corporate decarbonization commitments.
India
BIS industrial safety standard adoption and PLI scheme incentives for paper converting create first-mover positioning for certified electric roll lifter suppliers. The central government's production-linked incentive framework subsidizes automation capital expenditure. Maharashtra and Gujarat packaging corridors are integrating automated handling to reduce manual lifting injuries amid tightening state factory inspectorate enforcement.
Japan
METI energy efficiency regulations and JIS machinery safety standards favor precision electric actuator systems in Kanto region tissue manufacturing. Aging workforce demographics intensify ergonomic compliance pressure. Chubu and Kansai industrial belt converters are deploying predictive maintenance-enabled roll handling to sustain 24/7 production continuity.
Roll Handling Machine Market Competitive Landscape
Concentration sits with vertically integrated lifting specialists and regional ergonomic equipment fabricators. The vendor base stratifies across custom-engineered heavy capacity providers, standardized electric platform manufacturers, and application-specific integrators. Two dominant competitive moves are reshaping positioning: machinery-as-a-service financing model adoption and predictive maintenance IoT integration into existing fleet management platforms.
Among European ergonomic equipment specialists, R&D ERGO and ASE Systems exemplify the premium-tier archetype anchored in CE certification pathways and operator safety mandates. Schlumpf occupies a position within the custom-engineered segment, representing German industrial machinery clusters where specification intensity demands application-specific builds. Packline sits within the scale-driven standardized platform tier, competing across electric roll lifter manufacturing volume.
| Leading Market Players |
|---|
| Schlumpf |
| R&D ERGO |
| Tilt-Lock |
| Packline |
| ASE Systems |
| Torros |
| AZTECH Converting System |
| Easy Lift Equipment |
| Dotec B.V. |
| Others |
Value Network & Pricing Analysis
Electric actuator substitution for hydraulic power units is redrawing supply geography toward motor-drive manufacturing clusters in Germany and Japan while compressing aftermarket pricing power for legacy fluid-power component suppliers. This displacement simultaneously elevates specification premiums for integrated electromechanical platforms and erodes margins for standardized hydraulic equipment across North American and European converting corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement patterns, with CE-certified electric systems commanding specification premiums from EU tissue manufacturers while manual units face commoditization from Asian metal fabrication imports. Price differentiation hinges on ISO 3691 safety validation depth and aftermarket service bundling intensity. Pricing pressure stems from specialized steel alloy cost volatility in heavy capacity lifting frames. Small-batch packaging converters exhibit acute price sensitivity; integrated pulp-to-tissue mills prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Inventory lead times for high-grade structural steel alloys and precision linear actuators have extended procurement cycles for custom-engineered heavy capacity platforms. Supply concentrates in Germany, China, and Japan, with Baden-Württemberg OEM clusters anchoring European specification networks. Component dependencies include rare-earth permanent magnets for servo motors, high-tensile steel forgings for lifting frames, and PLC control modules. Single-source vulnerability in rare-earth magnet processing creates exposure to export restriction shocks. Distribution runs through converting machinery OEM specification channels and certified integrator networks serving regional packaging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts and machinery-as-a-service financing layers are expanding faster than hardware unit sales, creating recurring revenue pools that reshape vendor-customer relationships beyond equipment transactions.
For Market Incumbents: Fortify aftermarket service attach rates by embedding IoT sensor diagnostics into existing fleet management platforms, countering margin compression from Asian electric actuator imports. Deepen backward integration into custom lifting mechanics to defend specification positioning with German converting machinery OEMs. Prioritize CE marking documentation capabilities to accelerate sales-to-revenue cycles against non-European competitors. For New Entrants and Emerging Players: Predictive maintenance integration gaps among mid-sized tissue producers present white-space entry points where incumbents under-serve with legacy break-fix models. Target India's Maharashtra and Gujarat packaging corridors where BIS safety standard enforcement creates first-mover certification advantages. Pursue machinery-as-a-service financing partnerships with regional distributors to bypass capital-constrained buyer resistance. For Investors and Strategic Acquirers: The market sits at an electrification transition phase that favors vertically integrated lifting specialists with captive motor-drive engineering capabilities. Five-to-ten year viability hinges on service revenue mix expansion and decarbonization compliance positioning. Monitor PLI scheme implementation velocity in India as an inflection indicator for emerging market automation penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | IoT sensor deployment with tissue manufacturers enables per-roll handling fee structures replacing outright equipment sales. |
| CE Marking Certification Investment | Technical file assembly capabilities accelerate EU market entry timelines for emergency lowering and load stability controls. |
| Backward Integration into Linear Actuators | In-house motor-drive production defends margin pools against commodity electric component imports from Asian suppliers. |
| Machinery-as-a-Service Financing Launch | Uptime guarantee contracts capture recurring revenue from corrugated board converters prioritizing production continuity. |
| India Market Certification First-Mover Positioning | BIS industrial safety standard compliance creates specification advantages in Maharashtra and Gujarat packaging corridors. |
Research Methodology
A spread of perspectives from plant engineers at packaging converters, procurement leads at tissue manufacturers, aftermarket service heads at lifting equipment OEMs, and regulatory compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from EU machinery directive documentation, OSHA enforcement databases, SEC filings by listed industrial equipment suppliers, and trade flow data from German converting machinery export records. Bottom-up unit shipment estimates triangulated against top-down capital expenditure patterns across paper and pulp verticals.
Segmentation dimensions modeled span product type, industry vertical, load capacity tier, actuation technology, and regional regulatory cluster across the projection horizon. CAGRs derived from trend extrapolation of electrification substitution rates, ergonomic compliance enforcement trajectories, and plant automation capital allocation patterns. Industry-specific forecast inputs include MIIT industrial equipment electrification directives in China and PLI scheme incentive uptake velocity in India.
Forecasts assume regulatory continuity in EU machinery directives, OSHA ergonomic standards, and BIS industrial safety regimes; material policy shifts would require re-modeling of replacement demand curves and certification timeline assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
High-Precision Gear Reducer Market