
 Automotive Surface Heat Treatment Furnaces Market | 2026-2036
Automotive Surface Heat Treatment Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Surface Heat Treatment Furnaces Market Insights
China is fragmenting as domestic furnace builders scale capacity for EV-dedicated heat treatment lines. SECO/WARWICK S.A. leverages its vacuum furnace portfolio to anchor European OEM supply chains for transmission components. Ipsen International GmbH competes through atmosphere furnace specialization serving Tier-1 suppliers across North America and Asia. ALD Vacuum Technologies GmbH differentiates via plasma nitriding systems for precision engine parts.
Automotive surface heat treatment furnaces are industrial thermal processing systems operating at controlled temperatures between 500°C and 1,050°C to alter the metallurgical properties of steel and cast iron components through processes such as carburizing, nitriding, and quenching. Vacuum furnaces command premium positioning due to minimal oxidation and tight distortion control required for EV transmission gears. Continuous furnaces sustain volume economics for brake disc and chassis component producers supplying high-output vehicle assembly plants.
EPA emissions enforcement and Euro 7 standards from the European Commission are tightening allowable surface finish tolerances and energy intensity benchmarks for automotive component manufacturing. NHTSA vehicle safety regulations in the United States reinforce metallurgical consistency requirements for brake discs and drive shafts. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal reshape furnace energy sourcing and carbon border adjustment exposure for imported treated components.
Market Dynamics
Electric vehicle powertrain manufacturing is compressing heat treatment cycle times while demanding tighter metallurgical tolerances, forcing furnace operators to retool continuous lines for vacuum-batch hybrid configurations that can handle hardened gears without distortion.
Growth Catalysts
- Euro 7 Emissions Standards:The European Commission's tightening surface finish tolerances mandate precision-controlled atmosphere heat treatment, accelerating furnace upgrades across German and Czech component plants supplying OEM transmission programs.
- EV Powertrain Expansion:Electric vehicle manufacturers require hardened gears and shafts with minimal distortion, pulling vacuum furnace capacity into dedicated lines for e-axle and reduction gear production.
- China Dual Carbon Goals:Beijing's carbon intensity targets are redirecting domestic furnace procurement toward energy-efficient vacuum and plasma nitriding systems for engine component manufacturing.
Market Restraints
- Natural Gas Price Volatility:Atmosphere furnaces depend on consistent natural gas supply for controlled carbon potential, exposing European operators to input cost swings that compress margin on fixed-price component contracts.
- Specialized Refractory Supply Concentration:High-purity alumina and silicon carbide heating elements concentrate sourcing from limited Chinese and Ukrainian suppliers, creating vulnerability for furnace builders facing extended lead times.
- Technical Limitation in Thin-Wall Components:Conventional carburizing processes risk dimensional instability in lightweight transmission housings below 4mm wall thickness, restricting application scope for continuous furnace economics.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced automotive parts manufacturing are attracting vacuum furnace deployments to Pune and Chennai clusters serving export-oriented Tier-1 suppliers.
- Regulatory Tailwind from EU Green Deal:Carbon border adjustment mechanisms will favor domestic European heat treatment capacity over imported treated components, incentivizing furnace investment in Poland and Hungary.
- Technology Convergence of Predictive Maintenance and IoT:Sensor-integrated furnace systems enabling real-time atmosphere monitoring and predictive refractory failure detection command premium positioning against conventional control architectures.
Industry Challenges
- Metallurgical Engineer Shortage:Vacuum furnace operation and atmosphere process optimization require specialized expertise that outpaces vocational training output in Midwestern US and Eastern European manufacturing regions.
- Legacy System Integration Complexity:Retrofitting continuous pusher furnaces with modern SCADA and emissions monitoring interfaces demands extended downtime that conflicts with just-in-time component delivery commitments to OEM assembly plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Surface Heat Treatment Furnaces Market |
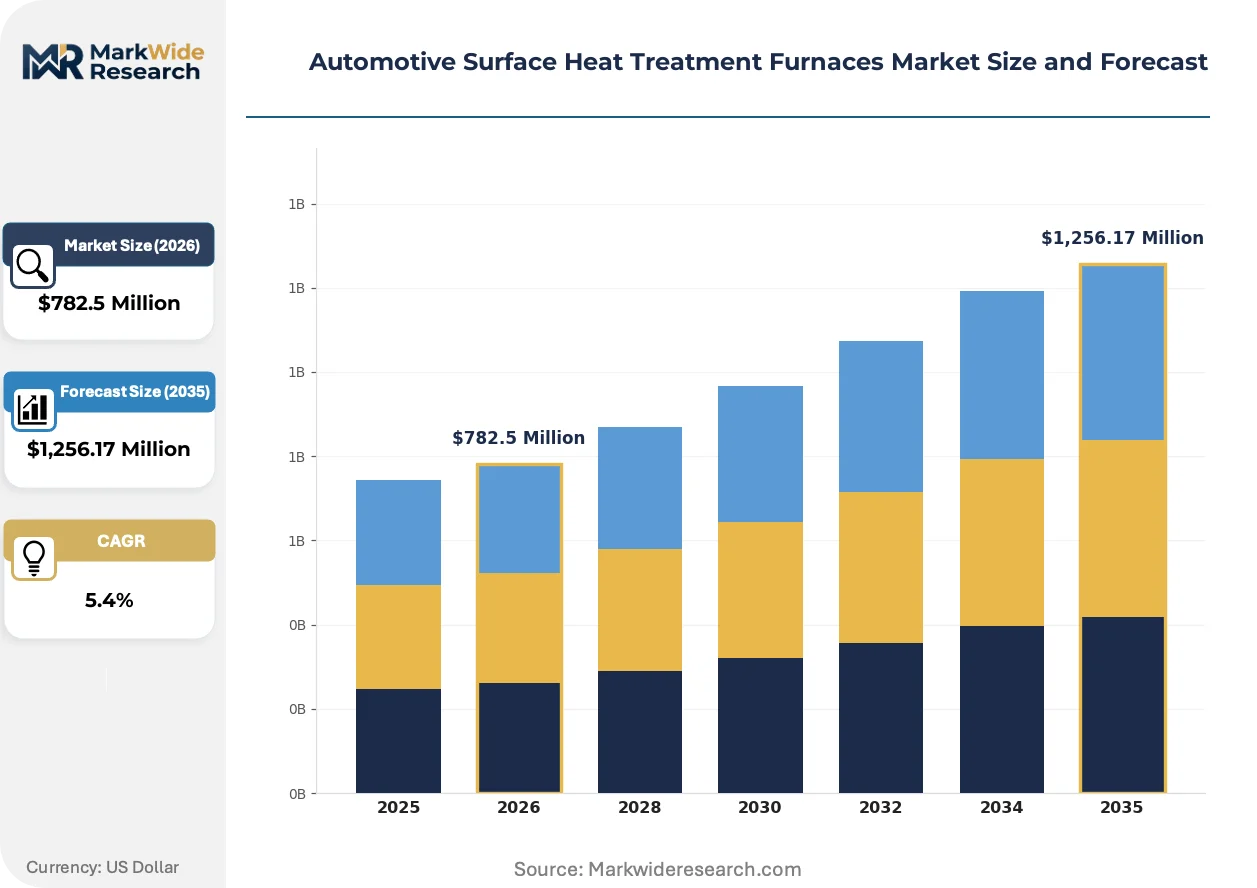
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,256.17 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Furnaces, Continuous Furnaces, Atmosphere Furnaces, Vacuum Furnaces, Induction Furnaces Technology: Gas Quenching, Oil Quenching, Salt Bath, Plasma Nitriding, Carburizing Application: Engine Components, Transmission Parts, Chassis Systems, Drive Shafts, Brake Discs End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Component Manufacturers |
| Companies Covered | Ipsen International GmbH, SECO/WARWICK S.A., ALD Vacuum Technologies GmbH, Tenova S.p.A., Surface Combustion, Inc., Lindberg/MPH, Nitrex Thermal Group, AFC-Holcroft, ECM Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Surface Heat Treatment Furnaces Market Trends and Innovations
Heat treatment furnace architecture is bifurcating between high-throughput continuous systems for commodity brake discs and precision vacuum platforms for EV transmission components, with control software emerging as the primary differentiation layer.
Low-pressure carburizing technology is collapsing the cycle time gap between vacuum batch processing and continuous atmosphere lines while eliminating intergranular oxidation. BMW and Mercedes-Benz powertrain suppliers in Bavaria are adopting these systems for e-axle gear production. The technology is collapsing the historical volume-premium tradeoff that forced component manufacturers to choose between distortion control and unit economics.
EPA emissions enforcement is tightening allowable volatile organic compound releases from atmosphere furnace quench oil systems, compelling US-based brake disc manufacturers to install thermal oxidizers or switch to polymer quenchants. The regulation is most acute in Michigan and Ohio foundries supplying Detroit Three assembly plants, where operators face capital decisions between abatement equipment and vacuum furnace conversion.
Component buyers are consolidating approved heat treatment supplier lists from regional multi-source models to single-site certification programs with full process traceability. Tier-1 transmission suppliers now require furnace-level data logging and metallurgical certificate integration directly into their ERP systems. This concentration is most visible in Germany's Mittelland supplier belt, where Volkswagen and BMW have reduced qualified heat treatment partners by forty percent over three years.
Automotive Surface Heat Treatment Furnaces Market Segmentation
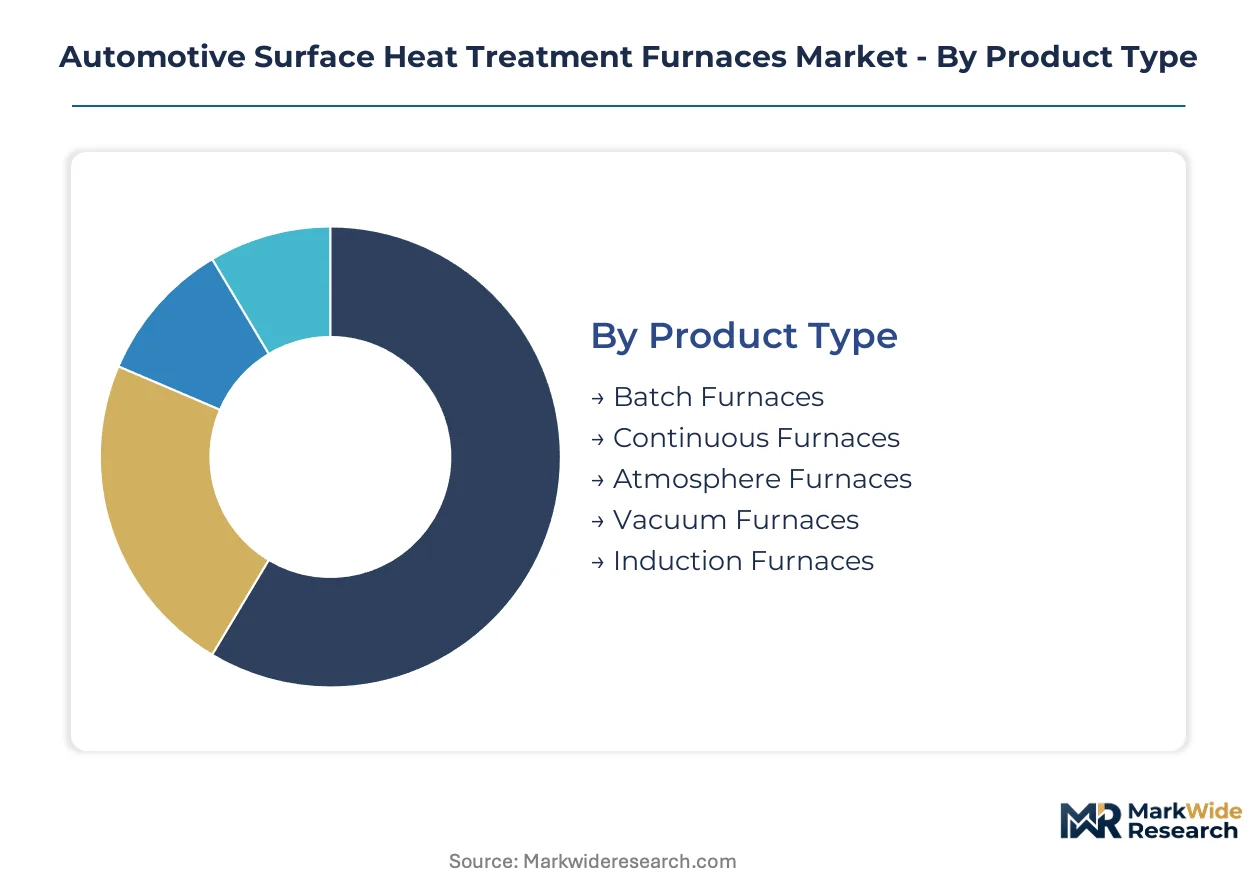
Heat treatment furnace procurement splits sharply between high-volume continuous lines serving commodity brake disc producers and precision vacuum systems dedicated to EV powertrain gears. Component buyers now mandate furnace-level data integration into ERP systems, compressing vendor qualification cycles and reshaping how each segment competes on traceability.
Product Type:
Continuous furnaces turn over fastest with cycle times measured in hours for brake disc batches, while vacuum systems run extended thermal profiles demanding 12-24 hour cycles for distortion-critical gears.
- Batch Furnaces:These systems process discrete loads in sealed chambers, enabling flexible atmosphere control for mixed component runs. Demand concentrates among German Mittelstand suppliers serving BMW and Volkswagen transmission programs, where small-lot hardened gears require rapid changeover between carburizing and nitriding cycles.
- Continuous Furnaces:Pusher and roller-hearth configurations sustain 24/7 operation for high-output brake disc and chassis component manufacturing. Michigan and Ohio foundries supplying Detroit Three assembly plants dominate installed capacity, though EPA quench oil emissions rules now force costly abatement retrofits or vacuum conversion decisions.
- Atmosphere Furnaces:Controlled carbon-potential systems remain the workhorse for conventional transmission gear hardening.
- Vacuum Furnaces:Low-pressure carburizing variants are collapsing the cycle-time gap with continuous lines while eliminating intergranular oxidation.
- Induction Furnaces:Electromagnetic heating delivers localized surface hardening for crankshaft journals and camshaft lobes.
Continuous furnaces dominate installed base. Vacuum furnaces are where expansion concentrates.
Technology:
Cost tiers separate commodity quenching methods from premium plasma and controlled atmosphere processes that command 3-4x capital investment per ton of throughput.
- Gas Quenching:High-pressure nitrogen or helium cooling within vacuum chambers delivers distortion control impossible with liquid media. Bavarian e-axle gear suppliers for Mercedes-Benz have standardized this approach, accepting slower cycle times to meet sub-50 micron flatness tolerances.
- Plasma Nitriding:Ionized gas surface hardening operates below 600°C, preserving core mechanical properties in precision engine components. ALD Vacuum Technologies anchors European supply for this technology, targeting turbocharger shafts and fuel injection systems where dimensional stability overrides speed.
- Oil Quenching:Conventional polymer and mineral oil baths remain prevalent for cost-sensitive brake disc production.
- Salt Bath:Liquid salt media enable rapid uniform heating for tool steel and specialty alloy components.
- Carburizing:Diffusion of carbon into low-carbon steel surfaces creates hard wear-resistant cases.
Oil quenching dominates legacy installed base. Gas quenching is where expansion concentrates.
Application:
Volume concentration tracks vehicle electrification patterns—transmission part demand is accelerating while engine component volumes face compression.
- Transmission Parts:E-axle reduction gears and shafts require vacuum heat treatment to achieve 58-62 HRC surface hardness without grinding distortion. Tier-1 suppliers in Stuttgart and Munich have dedicated furnace lines for this application, with cycle time optimization now the primary competitive battleground.
- Brake Discs:Gray cast iron rotors sustain the highest furnace throughput volumes globally. Continuous pusher lines in Shandong and Hebei provinces process millions of units monthly, though China's dual carbon goals are forcing efficiency upgrades and fuel switching.
- Engine Components:Camshafts, crankshafts, and valve train parts face demand pressure from powertrain electrification.
- Chassis Systems:Suspension control arms and steering knuckles require through-hardening for fatigue resistance.
- Drive Shafts:Hollow and solid propeller shafts for internal combustion and hybrid vehicles need balanced induction hardening.
Brake discs dominate installed base. Transmission parts are where expansion concentrates.
End User:
Customer type determines furnace specification rigor—OEM captive shops demand full SCADA integration while aftermarket providers prioritize equipment flexibility.
- Tier-1 Suppliers:These component specialists face the most intense furnace qualification pressure. Volkswagen and BMW have reduced approved heat treatment partners by forty percent, mandating furnace-level data logging and metallurgical certificate integration directly into ERP systems.
- OEMs:Captive heat treatment operations at BMW, Mercedes-Benz, and Volkswagen anchor precision vacuum furnace demand in Germany.
- Vehicle Assemblers:Final assembly plants rarely operate captive heat treatment, instead sourcing treated components from qualified supplier networks.
- Aftermarket Providers:Independent remanufacturers of transmission and engine components require flexible batch furnace configurations.
- Component Manufacturers:Specialized producers of bearings, gears, and shafts serve multiple automotive and industrial end markets.
Tier-1 suppliers dominate qualified furnace deployments. OEM captive operations are where precision capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in manufacturing corridors where automotive OEMs anchor component supply chains. Furnace builders align capacity with electrification timelines and emissions enforcement patterns across major production zones.
Germany
Volkswagen, BMW, and Mercedes-Benz captive operations drive vacuum furnace demand for e-axle gear production. The EU Green Deal and carbon border adjustment mechanisms incentivize domestic heat treatment capacity over imported components. Bavarian suppliers around Munich and Stuttgart have reduced qualified heat treatment partners by forty percent while mandating furnace-level ERP integration.
China
Domestic furnace builders scale capacity for EV-dedicated heat treatment lines serving BYD, NIO, and Tesla Shanghai. Beijing's dual carbon goals redirect procurement toward energy-efficient vacuum and plasma nitriding systems. Shandong and Hebei provinces host the highest continuous furnace throughput for brake disc production, though fuel switching pressures mount under carbon intensity targets.
United States
Detroit Three assembly plants in Michigan and Ohio sustain demand for brake disc heat treatment, though EPA quench oil emissions rules force abatement retrofits or vacuum conversion decisions. NHTSA vehicle safety regulations reinforce metallurgical consistency requirements for drive shafts. Midwestern foundries face technical workforce shortages for vacuum furnace operation and atmosphere process optimization.
India
Production-linked incentives for advanced automotive parts attract vacuum furnace deployments to Pune and Chennai clusters. The PLI scheme targets export-oriented Tier-1 suppliers serving European and North American OEM programs. Domestic component manufacturers upgrade from batch to continuous configurations to meet volume qualification thresholds for global supply chain integration.
Japan
Precision automotive component exports sustain demand for plasma nitriding and low-pressure carburizing systems. METI industrial efficiency standards push furnace operators toward predictive maintenance and IoT-enabled atmosphere monitoring. Toyota and Honda supplier networks in Aichi Prefecture prioritize distortion control for transmission gears over cycle time economics.
Automotive Surface Heat Treatment Furnaces Market Competitive Landscape
Vacuum specialists and atmosphere furnace builders split the market along precision-versus-volume fault lines. European vendors anchor premium positioning through low-pressure carburizing technology, while North American and Asian competitors compete on continuous line throughput and retrofit flexibility. Three archetypes dominate: integrated thermal processing system houses, specialized vacuum equipment builders, and regional batch furnace fabricators serving aftermarket remanufacturers. Capacity expansion and technology licensing represent the dominant competitive moves, with vendors partnering to bridge vacuum and continuous furnace capability gaps.
Among European integrated system houses, SECO/WARWICK S.A., Ipsen International GmbH, and ALD Vacuum Technologies GmbH occupy positions across the vacuum-atmosphere spectrum. SECO/WARWICK anchors European OEM supply chains through vacuum furnace portfolios. Ipsen International exemplifies atmosphere furnace specialization with Tier-1 supplier relationships spanning multiple continents. ALD Vacuum Technologies represents the precision-engineering tier through plasma nitriding system differentiation. These three GmbH and S.A. structured entities collectively illustrate how geographic origin and corporate form signal capability positioning in furnace procurement decisions.
| Leading Market Players |
|---|
| Ipsen International GmbH |
| SECO/WARWICK S.A. |
| ALD Vacuum Technologies GmbH |
| Tenova S.p.A. |
| Surface Combustion, Inc. |
| Lindberg/MPH |
| Nitrex Thermal Group |
| AFC-Holcroft |
| ECM Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine freight corridors linking German Mittelstand suppliers to OEM assembly plants concentrate logistics cost exposure for furnace-dependent component flows, compressing margins on fixed-price transmission gear contracts while amplifying price differentiation between vacuum-batch precision suppliers and continuous-line commodity producers.
Pricing Analysis
Euro 7 emissions standards dictate the pricing tier structure across automotive heat treatment services, separating vacuum furnace operators serving BMW and Mercedes-Benz e-axle programs from atmosphere furnace competitors tied to brake disc volume economics. Certification grade and furnace-level ERP integration capability drive price differentiation, with Tier-1 qualified suppliers commanding substantial premiums over unqualified batch operators. Cost compression in continuous furnace segments is intensifying because EPA quench oil abatement requirements force capital diversion from productivity investments. Aftermarket remanufacturers exhibit highest price sensitivity, while OEM captive operations prioritize metallurgical consistency over unit cost.
Supply Chain Analysis
High-purity alumina heating elements and silicon carbide refractories anchor upstream feedstock vulnerability for furnace builders, with sourcing concentrating in China and Ukraine. Natural gas for controlled atmosphere processing and specialized alloy steel for furnace construction represent critical input dependencies. Single-source vulnerability in Ukrainian refractory supply creates extended lead time exposure for European furnace operators. Distribution runs through qualified supplier networks with full process traceability, where Volkswagen and BMW have consolidated approved heat treatment partners by forty percent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive surface heat treatment furnaces constitute a defensive-moat market where regulatory entrenchment through Euro 7 and EPA emissions certification creates structural barriers that protect incumbent positioning against price competition.
For Market Incumbents: Build switching cost moats through furnace-level ERP integration and metallurgical certificate automation that locks Tier-1 suppliers into long-term qualification cycles. Deepen backward integration into specialized refractory supply to mitigate Ukrainian sourcing concentration. Expand vacuum-batch hybrid capacity in Bavaria and Stuttgart clusters to capture EV powertrain gear demand before emerging entrants secure OEM validation slots. For New Entrants and Emerging Players: India's PLI scheme auto component clusters present the most penetrable geographic underpenetration for vacuum furnace deployment, with Pune and Chennai offering export-oriented qualification pathways. Target Tier-2 transmission suppliers in Eastern Europe seeking dual sourcing alternatives to German Mittelstand concentration. Pursue technology licensing partnerships with established vacuum equipment builders to bypass metallurgical engineer shortage barriers in Midwestern US markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized heat treatment divisions lacking furnace-level data integration capabilities. Five-to-ten year viability hinges on vacuum technology exposure and EV powertrain supplier relationships rather than legacy engine component volumes. Monitor carbon border adjustment mechanism implementation timing as inflection indicator for European domestic capacity valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Batch Hybrid Line Deployment | SECO/WARWICK and Ipsen anchor European OEM supply chains through low-pressure carburizing technology adoption. |
| Backward Integration into Refractory Supply | Furnace builders mitigate Ukrainian alumina concentration through captive sourcing partnerships with Chinese suppliers. |
| ERP Integration and Traceability Investment | Tier-1 suppliers mandate furnace-level data logging to qualify for Volkswagen and BMW reduced partner lists. |
| Geographic Expansion to India PLI Clusters | Vacuum furnace deployments target Pune and Chennai export-oriented component manufacturing zones. |
| Predictive Maintenance and IoT Platform Development | Sensor-integrated systems enable real-time atmosphere monitoring for premium positioning against conventional architectures. |
Research Methodology
Cross-validation between furnace operator interviews and customs trade data anchors the qualitative findings on regional capacity expansion patterns. Primary discussions with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket service heads, and furnace builder technical directors combined with secondary analysis of SEC filings, vehicle production databases, and EPA enforcement records. Bottom-up installed base modeling and top-down OEM procurement spend estimates triangulate market sizing.
Calibration against historical furnace shipment data and OEM electrification timelines refines projection parameters across the analysis window. Segmentation dimensions include furnace type, quenching technology, component application, and end-user category. CAGRs derive from regression analysis of equipment procurement cycles against EV powertrain ramp schedules and emissions regulatory phase-ins. Forecast inputs incorporate natural gas price volatility scenarios and refractory supply lead time assumptions.
Practitioners should monitor carbon border adjustment mechanism implementation schedules and dual carbon goal enforcement intensity in China for early signals of demand migration. Forecasts reflect assumptions regarding EV penetration rates and regulatory compliance timelines. Cross-checking against IHS Markit vehicle production forecasts and OEM capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Snow Removal Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Cement and Mortar Testing Equipment Market