
 Japan Transportation Infrastructure Construction Market | 2026-2036
Japan Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Transportation Infrastructure Construction Market Foresight
Ultra-high-performance concrete is expanding its share in bridge deck applications across Japan, displacing conventional reinforced concrete on seismic-critical spans. Taisei Corporation leverages proprietary UHPC batching technology to anchor its position in Honshu-Shikoku corridor projects. Obayashi Corporation sustains competitive positioning through captive supply of precast segments at its Kansai manufacturing complex. Shimizu Corporation differentiates via integrated design-build contracts for Tokyo metropolitan rail extensions.
Japan transportation infrastructure construction encompasses the engineering, fabrication, and assembly of civil works including roadbeds, bridge superstructures, tunnel linings, and rail track systems, typically specified to JIS A 5308 for ready-mixed concrete and 490 N/mm² tensile strength rebar for seismic zones. Its primary purpose is to sustain passenger and freight mobility across Japan's archipelagic geography while meeting 200-year design life thresholds for coastal exposure. Road construction occupies the largest value share among service types, driven by expressway widening and intercity connector programs. Rail infrastructure represents the fastest-expanding segment, fed by maglev corridor preparation and legacy Shinkansen station upgrades. Mega projects concentrate margin pools through bundled civil, electrical, and systems contracting that locks out smaller regional bidders.
METI sets industrial policy direction for infrastructure investment cycles, while Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces technical standards for structure durability and construction quality. PMDA oversight intersects where medical transport infrastructure integrates into hospital-adjacent transit nodes. MLIT's progressive tightening of carbon-intensity benchmarks for cement and steel procurement is reshaping supplier qualification requirements. Stakeholders must monitor whether METI's next Basic Plan on Infrastructure Maintenance accelerates asset replacement timelines or extends existing structure service lives through retrofit mandates.
Market Dynamics
METI's progressive tightening of carbon-intensity benchmarks for cement and steel procurement is compressing contractor margins while forcing material substitution across Japan's bridge and tunnel portfolios. This regulatory pressure cascades through supply chains, reshaping qualification requirements and locking out suppliers unable to meet embodied-carbon thresholds.
Growth Catalysts
- Maglev corridor preparation:Central Japan Railway Company's linear Chuo Shinkansen route is generating bundled civil-electrical-systems contracts across Yamanashi and Shizuoka prefectures.
- MLIT durability mandates:The Ministry of Land, Infrastructure, Transport and Tourism's 200-year design life thresholds for coastal exposure are accelerating ultra-high-performance concrete adoption on seismic-critical spans.
- Tohoku reconstruction stimulus:Prefecture-level funding corridors in northern Honshu are concentrating bidding activity among contractors with proven earthquake-resistance retrofit capabilities.
Market Restraints
- Domestic cement supply concentration:Three integrated producers control bulk clinker supply, limiting price negotiation leverage for mid-tier contractors on fixed-price public tenders.
- Specialized rebar fabrication bottleneck:490 N/mm² tensile strength seismic-grade rebar requires accredited rolling mills, creating procurement delays for projects outside Kanto and Kansai manufacturing clusters.
- Labor mobility restrictions:Japan's technical intern training program reforms have constrained skilled tunnelling crew availability, extending project timelines on remote Honshu-Shikoku corridor segments.
Strategic Opportunities
- Hokkaido freight rail modernization:Underpenetrated northern island infrastructure presents white space for integrated design-build contractors capable of permafrost-adapted foundation engineering.
- Digital twin convergence:Integration of BIM models with IoT structural health monitoring is enabling predictive maintenance contracts that extend contractor revenue streams beyond construction completion.
- Osaka-Kansai Expo 2025 legacy conversion:Temporary transport infrastructure on Yumeshima Island offers conversion pathways to permanent metropolitan rail extensions post-event.
Industry Challenges
- Geotechnical specialist scarcity:Deep-bored tunnelling expertise concentrates among aging engineer cohorts, complicating knowledge transfer for Nagoya metropolitan rail extensions.
- JIS A 5308 compliance timelines:Ready-mixed concrete certification delays for new UHPC formulations are extending pre-qualification periods, freezing contractor eligibility for time-sensitive municipal tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Transportation Infrastructure Construction Market |
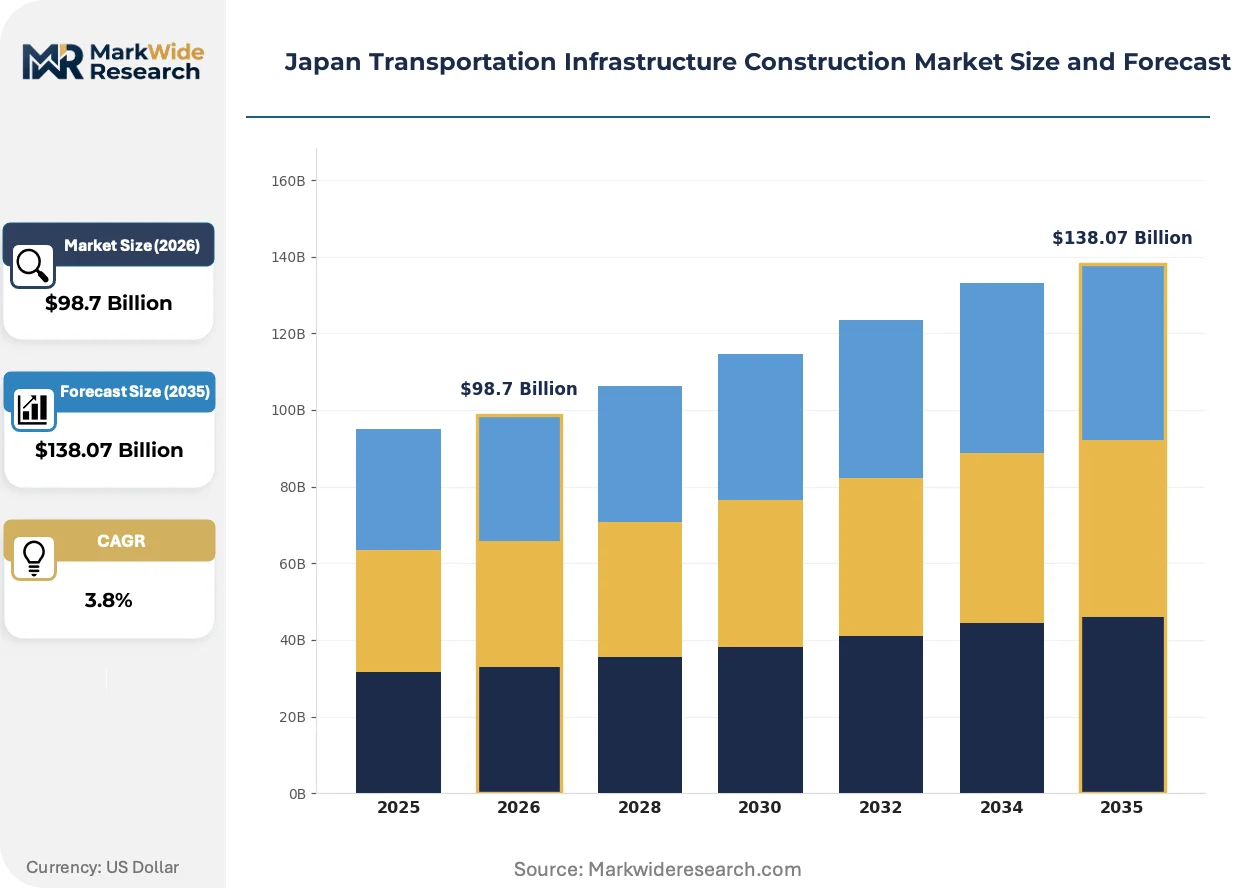
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $138.07 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Construction, Bridge Engineering, Tunnel Construction, Rail Infrastructure Material Type: Cement, Steel, Asphalt, Concrete Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Client Type: Government Agencies, Private Investors, Public-Private Partnerships, Contractors |
| Companies Covered | Takenaka Corporation, Wakachiku Construction, Obayashi Corporation, Penta-Ocean Construction, TOA Corporation, Shimizu Corporation, Tekken Corporation, Yahagi Construction, Taisei Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Transportation Infrastructure Construction Market Shifts & Advancements
Material science advances and digital construction methods are compressing project delivery timelines while elevating performance specifications for seismic resilience. These shifts favor contractors with captive manufacturing assets and integrated engineering capabilities.
Ultra-high-performance concrete is overtaking conventional reinforced concrete on bridge deck applications across Japan's seismic zones. Municipal transit authorities in Osaka and Nagoya specify UHPC for critical spans requiring reduced maintenance intervals. This material transition is compressing the competitive set to contractors with proprietary batching technology or captive supply agreements.
METI's carbon-intensity benchmarking framework is reshaping steel and cement procurement qualification requirements for public infrastructure tenders. Contractors must now document embodied-carbon footprints across supply chains to maintain eligibility for MLIT-administered contracts. Coastal expressway and intercity connector programs face the steepest compliance adjustments, driving consolidation among qualified material suppliers.
Prefecture-level transit authorities are consolidating design-build procurement for urban rail extensions, unbundling traditional civil-electrical-systems separations. Tokyo metropolitan rail projects now specify single-contractor accountability across trackbed, signalling, and station integration. This bundling concentrates margin pools among integrated contractors while marginalizing specialized regional bidders in Kansai and Chubu corridors.
Japan Transportation Infrastructure Construction Market Segmentation
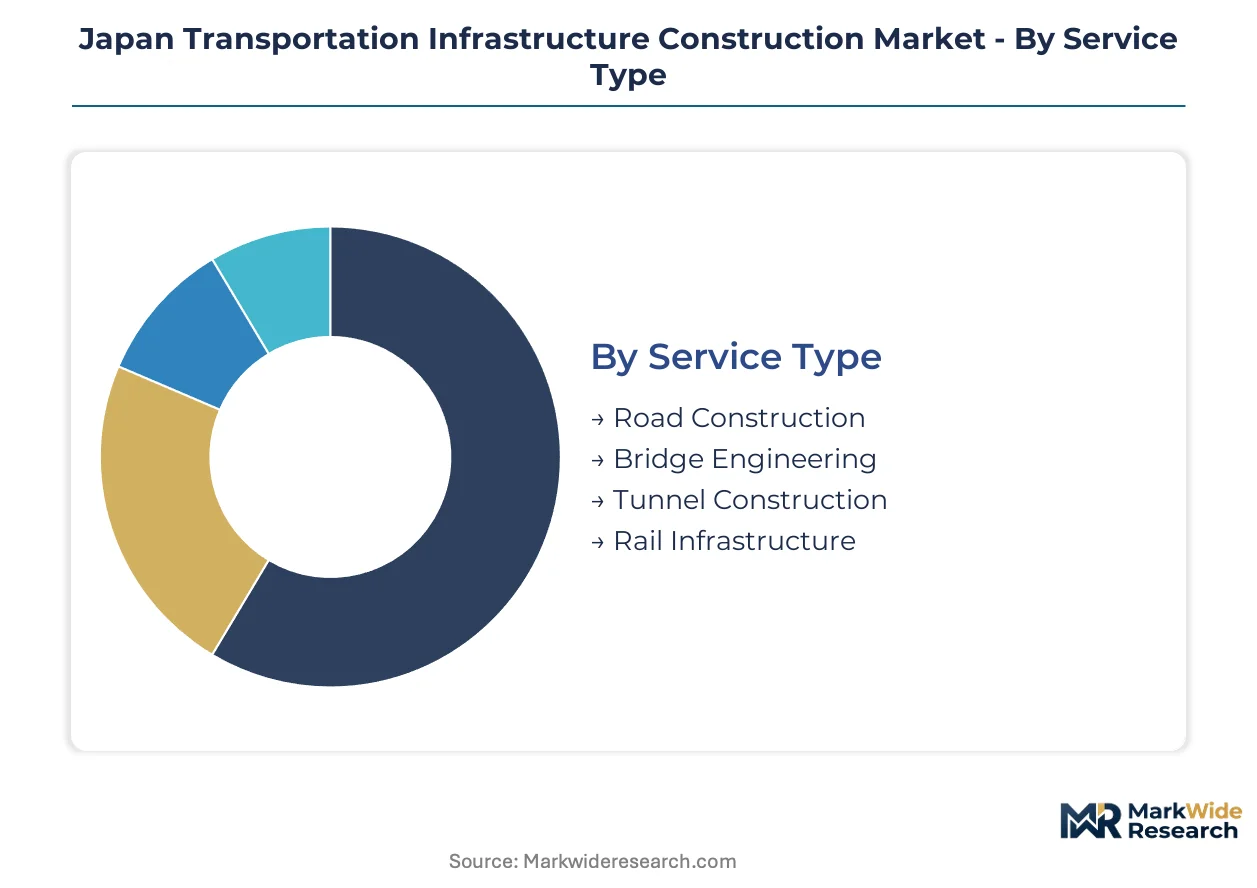
Segmentation in Japan's transportation infrastructure construction market reveals how regulatory pressure and procurement bundling reshape competitive positioning across service lines. Understanding these divides exposes where contractor capabilities align with METI's carbon-intensity mandates and MLIT's durability thresholds.
Service Type:
Road construction commands the largest contractor workforce concentration, while rail infrastructure attracts the most integrated engineering bids.
- Road Construction:Expressway widening and intercity connector programs dominate municipal procurement in Osaka and Nagoya metropolitan rings. MLIT-administered coastal exposure projects specify 200-year design life thresholds, compressing the qualified contractor pool to firms with UHPC batching capabilities.
- Rail Infrastructure:Maglev corridor preparation across Yamanashi and Shizuoka prefectures generates bundled civil-electrical-systems contracts that exclude regional specialists. Tokyo metropolitan extensions concentrate margin pools among design-build contractors capable of station integration.
- Bridge Engineering:Seismic-critical spans drive ultra-high-performance concrete adoption under updated earthquake-resistance standards.
- Tunnel Construction:Deep-bored expertise concentrates among aging engineer cohorts, complicating knowledge transfer for Nagoya extensions.
Today's leader: Road Construction. Tomorrow's challenger: Rail Infrastructure.
Material Type:
Procurement qualification requirements now hinge on documented embodied-carbon footprints across supply chains.
- Cement:Three integrated producers control bulk clinker supply, limiting price negotiation leverage for mid-tier contractors on fixed-price public tenders. METI's progressive tightening of carbon-intensity benchmarks is reshaping supplier qualification requirements for MLIT-administered contracts.
- Concrete:Ultra-high-performance formulations displace conventional reinforced concrete on seismic-critical bridge decks. JIS A 5308 certification delays for new UHPC grades extend pre-qualification periods, freezing contractor eligibility for time-sensitive municipal tenders.
- Steel:490 N/mm² tensile strength seismic-grade rebar requires accredited rolling mills, creating procurement delays outside Kanto and Kansai manufacturing clusters.
- Asphalt:Expressway surface specifications favor polymer-modified binders from captive refinery agreements.
Cement and concrete together anchor material procurement spend, with steel facing the steepest compliance adjustments under carbon benchmarking.
Project Size:
Mega projects concentrate margin pools through bundled contracting that locks out smaller regional bidders.
- Mega Projects:Central Japan Railway Company's linear Chuo Shinkansen route exemplifies bundled civil-electrical-systems procurement. Single-contractor accountability across trackbed, signalling, and station integration marginalizes specialized regional bidders in Kansai and Chubu corridors.
- Large Scale:Honshu-Shikoku corridor segments and Tohoku reconstruction corridors concentrate bidding activity among contractors with proven earthquake-resistance retrofit capabilities.
- Medium Scale:Prefecture-level transit authorities consolidate design-build procurement for urban rail extensions.
- Small Scale:Municipal maintenance contracts face compressed margins due to limited bundling opportunities.
Mega Projects capture premium margins through integration complexity; Medium Scale projects offer the most accessible entry point for specialized regional contractors.
Client Type:
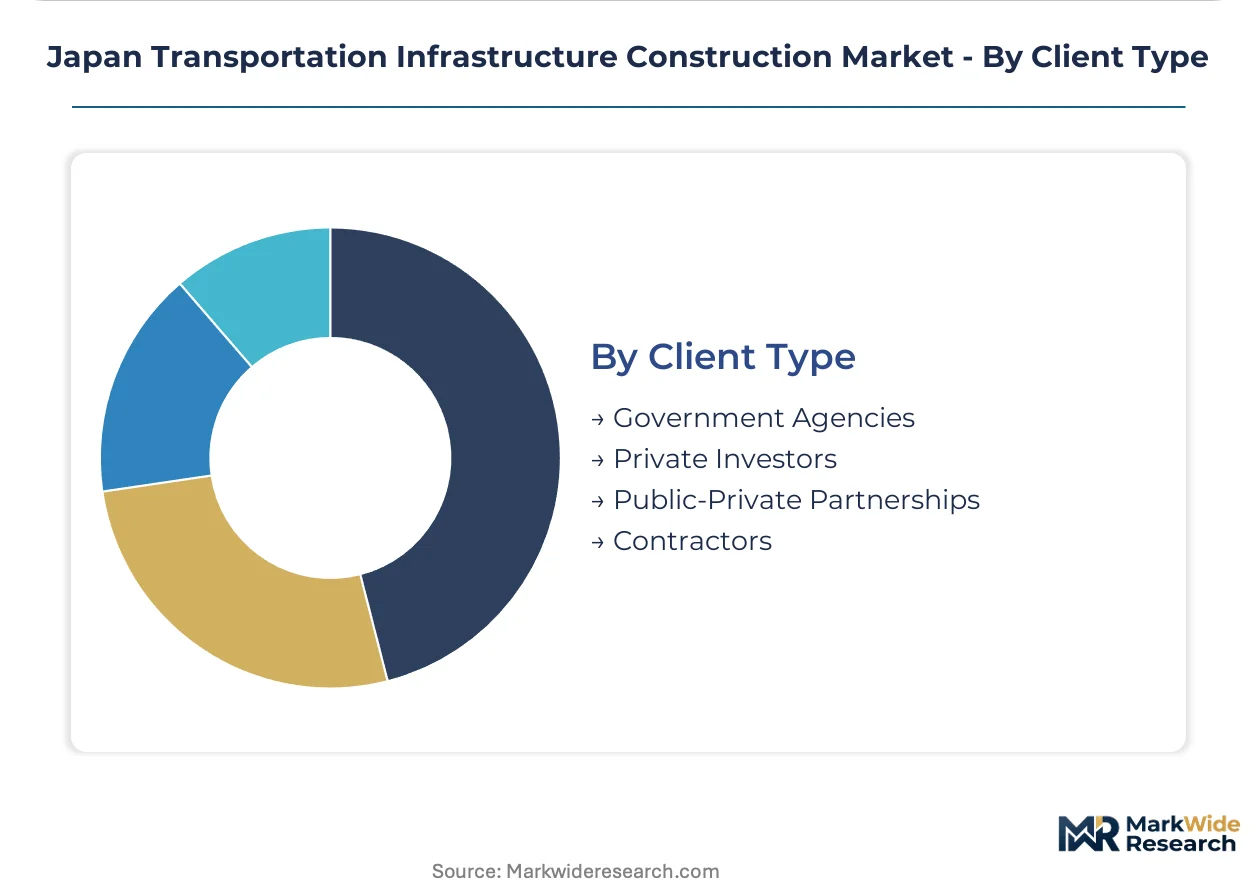
Government agencies dominate procurement volume, while public-private partnerships concentrate risk-transfer innovation.
- Government Agencies:MLIT and prefecture-level authorities administer the majority of expressway and rail extension tenders. Progressive tightening of carbon-intensity benchmarks for cement and steel procurement is compressing contractor margins while forcing material substitution.
- Public-Private Partnerships:Osaka-Kansai Expo 2025 legacy conversion pathways on Yumeshima Island demonstrate how temporary transport infrastructure transitions to permanent metropolitan rail extensions.
- Private Investors:Freight rail modernization in Hokkaido attracts integrated design-build contractors capable of permafrost-adapted foundation engineering.
- Contractors:Self-directed investment in captive manufacturing assets differentiates competitive positioning for UHPC and precast segment supply.
Government Agencies set qualification standards that cascade through all client types; Public-Private Partnerships offer the most flexible procurement innovation pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto's metropolitan rail density anchors Japan's transportation infrastructure investment gravity, with prefecture-level procurement concentrating contractor deployment across Honshu's eastern seaboard. Regional divergence reflects seismic retrofit urgency, maglev corridor preparation, and northern reconstruction stimulus corridors.
Kanto/Tokyo
Tokyo metropolitan rail extensions and Shinkansen station upgrades absorb the majority of MLIT-administered design-build contracts. METI's carbon-intensity benchmarks for steel procurement reshape qualification requirements for Chuo Shinkansen terminal works. The Greater Tokyo Area concentrates integrated contractors capable of bundled civil-electrical-systems accountability across trackbed and signalling integration.
Kansai/Osaka
Urban rail expansion in Osaka and Yumeshima Island's Expo 2025 legacy conversion drive municipal transit authority procurement. UHPC batching capabilities differentiate competitive positioning for bridge deck applications on seismic-critical spans. The Osaka metropolitan ring attracts contractors with captive precast segment supply from integrated Kansai manufacturing complexes.
Chubu/Nagoya
Nagoya metropolitan rail extensions face geotechnical specialist scarcity among aging engineer cohorts. Deep-bored tunnelling expertise concentrates bidding activity among contractors with proven earthquake-resistance retrofit capabilities. Aichi Prefecture's transit authorities consolidate single-contractor procurement across station integration and trackbed works.
Tohoku
Prefecture-level stimulus corridors concentrate reconstruction bidding in northern Honshu earthquake-damaged zones. MLIT's updated 200-year design life thresholds for coastal exposure accelerate material upgrades across bridge portfolios. Iwate and Miyagi prefectures attract contractors with documented UHPC formulation certification under JIS A 5308 compliance timelines.
Hokkaido
Freight rail modernization presents white space for integrated design-build contractors capable of permafrost-adapted foundation engineering. Underpenetrated northern island infrastructure lacks the specialized rebar fabrication clusters concentrated in Kanto and Kansai. Sapporo-based procurement faces procurement delays for 490 N/mm² tensile strength seismic-grade rebar from accredited rolling mills.
Japan Transportation Infrastructure Construction Market Competitive Landscape
Captive manufacturing asset acquisition dominates the current landscape as contractors secure UHPC batching technology and precast segment supply chains. The market structures around three tiers: integrated giants with bundled civil-electrical-systems capabilities, mid-tier regional specialists with proven retrofit expertise, and material-science innovators with proprietary formulation certification. Strategic differentiation hinges on backward integration into concrete supply and upstream control over accredited rebar sourcing. Competitive intensity concentrates in design-build procurement for maglev corridor segments and metropolitan rail extensions.
Within the integrated contractor tier, Taisei Corporation, Obayashi Corporation, and Shimizu Corporation exemplify archetypes of competitive positioning. Taisei anchors proprietary UHPC technology deployment across Honshu-Shikoku corridor projects. Obayashi occupies a position tied to captive precast manufacturing scale in the Kansai industrial basin. Shimizu represents the design-build integration model for Tokyo metropolitan rail extensions. These three Japanese construction entities sit within a market where METI carbon benchmarks and MLIT durability mandates reshape qualification requirements, compressing margins for contractors lacking verified supply chain documentation.
| Leading Market Players |
|---|
| Takenaka Corporation |
| Wakachiku Construction |
| Obayashi Corporation |
| Penta-Ocean Construction |
| TOA Corporation |
| Shimizu Corporation |
| Tekken Corporation |
| Yahagi Construction |
| Taisei Corporation |
| Others |
Supply & Pricing Matrix
Prefecture-level transit authorities concentrate procurement volume across MLIT-administered tenders, locking contractors into fixed-price public contracts with limited renegotiation clauses. This buyer concentration amplifies margin compression when METI carbon-intensity benchmarks force material substitution without price adjustment mechanisms.
Pricing Analysis
Input-cost pass-through operates partially across Japan's infrastructure contracting tiers, with bulk cement and seismic-grade rebar fluctuations absorbed differently by integrated giants versus mid-tier regional players. Three-tier pricing structure across premium UHPC-certified, standard JIS-compliant, and economy-grade concrete tiers separates contractors by formulation certification status. Pricing pressure stems from METI's embodied-carbon documentation requirements, which disqualify uncertified suppliers from public tenders. Municipal transit authorities in Osaka and Nagoya exhibit highest price sensitivity on maintenance-interval contracts, while maglev corridor bundling commands premium tolerance from Central Japan Railway Company procurement.
Supply Chain Analysis
JIS A 5308 certification and MLIT durability qualification gates filter concrete supplier eligibility, freezing pre-qualification timelines for new UHPC formulations. Bulk clinker supply concentrates among three integrated Japanese producers, with specialized 490 N/mm² rebar fabrication anchored in Kanto and Kansai manufacturing clusters. Raw material dependencies span low-carbon cement formulations, seismic-grade steel, and polymer-modified asphalt binders. Single-source vulnerability concentrates in accredited rolling mill capacity for northern Honshu and Hokkaido projects. Distribution runs through contractor captive manufacturing complexes and prefecture-level material depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's transportation infrastructure construction market compounds steadily through earthquake-resistance retrofit cycles and metropolitan rail densification, with METI policy continuity supporting predictable procurement pipelines.
For Market Incumbents: Extend proprietary UHPC batching technology deployment across Tohoku reconstruction corridors to anchor position in seismic-critical span markets. Deepen backward integration into low-carbon cement supply chains before METI tightens embodied-carbon thresholds further. Consolidate design-build capabilities around maglev corridor station integration to exclude regional specialists from margin pools. For New Entrants and Emerging Players: Digital twin convergence for predictive maintenance contracts offers technology-first wedge into post-construction revenue streams underserved by traditional EPC contractors. Target Hokkaido freight rail modernization as the most penetrable geography, where permafrost engineering scarcity limits incumbent presence. Pursue municipal maintenance contracts in secondary cities as entry pathway before qualifying for bundled mega-project procurement. For Investors and Strategic Acquirers: Integrated contractors with captive precast manufacturing assets are the most active acquirer in this space, consolidating regional specialists to secure JIS A 5308 certification portfolios. Five-to-ten-year viability hinges on carbon-intensity compliance infrastructure rather than pure construction volume. Watch METI's next Basic Plan on Infrastructure Maintenance as the signal for whether asset replacement timelines accelerate or retrofit mandates extend service lives.| Strategic Initiative | Industry Significance |
|---|---|
| UHPC Formulation Certification | JIS A 5308 compliance unlocks eligibility for MLIT-administered seismic-critical bridge tenders. |
| Backward Integration into Low-Carbon Cement | Captive supply chains satisfy METI embodied-carbon benchmarks for public infrastructure procurement. |
| Design-Build Capability Consolidation | Single-contractor accountability across civil-electrical-systems excludes fragmented regional competitors. |
| Digital Twin Platform Development | BIM-IoT integration enables predictive maintenance contracts extending revenue beyond construction completion. |
| Permafrost Engineering Competency Buildup | Hokkaido freight modernization demand outpaces specialized contractor supply in northern island markets. |
Research Methodology
Multiple input streams — structured interviews with construction project directors, procurement officers at prefecture-level transit authorities, and MLIT policy specialists — were reconciled against secondary validation from Japan Ministry of Land, Infrastructure, Transport and Tourism construction statistics, METI industrial policy white papers, and contractor financial disclosures. Bottom-up project pipeline aggregation across maglev corridor segments, Tohoku reconstruction zones, and metropolitan rail extensions was cross-checked against top-down market sizing from cement consumption data and steel procurement volumes.
Historical bid-award patterns were cross-referenced against panel input from engineering procurement leads to calibrate segment growth trajectories across the projection horizon. Segmentation dimensions modeled include service type, material certification tier, project scale bundling, and client procurement structure. CAGRs were derived from trend extrapolation of prefecture-level capital expenditure commitments and METI infrastructure maintenance cycle assumptions, with maglev corridor phasing and Expo 2025 legacy conversion timelines as industry-specific forecast inputs.
The model holds under continued METI carbon-intensity benchmarking enforcement and MLIT 200-year durability mandate maintenance; deviation in stimulus allocation priorities or JIS certification timeline acceleration would shift contractor qualification dynamics and regional bidding concentration patterns. A model refresh is warranted upon material change in METI Basic Plan policy direction or significant earthquake event triggering emergency reconstruction appropriations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Denmark Data Center Construction Market