
 North America Freestanding Canopy Market | 2026-2036
North America Freestanding Canopy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Freestanding Canopy Market Insights
ASTM F2374-17 is unwinding the competitive landscape by disqualifying uncertified imports from Mexico and Asia from commercial procurement channels across the United States. ShelterLogic leverages its vertically integrated steel-frame production in Illinois to sustain price competitiveness against offshore alternatives. Caravan Canopy anchors its position through dominant retail distribution at big-box chains throughout the Midwest and Southeast. E-Z UP differentiates via rapid-deployment engineering that targets event-production professionals requiring sub-two-minute setup protocols.
North America freestanding canopy denotes a self-supporting temporary shelter structure utilizing aluminum or steel framing with tensioned fabric membranes, engineered to withstand wind loads between 35-70 mph depending on anchoring configuration and roof geometry. These structures serve commercial and recreational users requiring rapid-deploy weather protection for outdoor commerce, social functions, and emergency response operations. Commercial grade canopies command the thickest margin pools due to fire-retardant certification requirements and custom-engineering services that residential segments rarely demand. Pop-up canopies represent the fastest-expanding product type as food vendors and weekend-market operators prioritize portability over permanence. Polyester dominates material selection for entry-level units, while vinyl and canvas concentrate in premium tiers where UV degradation resistance justifies higher unit economics.
FAA guidelines for temporary structures at airport-adjacent events, combined with NFPA 701 fire-resistance standards and provincial building codes in Ontario and Quebec, collectively elevate compliance costs for manufacturers serving cross-border demand. The EPA's evolving stance on PFAS-treated water-repellent fabrics is pressuring suppliers to reformulate coating chemistries before enforcement timelines solidify. Stakeholders must monitor certification reciprocity negotiations between Canadian Standards Association and Underwriters Laboratories, as diverging test protocols threaten to fragment product lines and inflate inventory carrying costs for brands serving both national markets.
Market Dynamics
ASTM F2374-17 certification mandates are compressing the supplier base by disqualifying uncertified imports from commercial procurement channels across the United States and Canada, forcing domestic manufacturers to absorb compliance costs while offshore competitors retreat to residential segments.
Growth Catalysts
- Commercial Event Expansion:Event planners across California and Texas are expanding canopy deployments for outdoor weddings and corporate gatherings, sustaining replacement cycles and premium upgrades.
- FAA Temporary Structure Guidelines:Airport-adjacent event regulations are creating compliant product demand from rental companies serving aviation-adjacent venues.
- Steel-Frame Vertical Integration:Domestic manufacturers with captive Illinois-based steel production are sustaining price competitiveness against offshore alternatives.
Market Restraints
- PFAS Coating Reformulation Costs:The EPA's evolving stance on PFAS-treated water-repellent fabrics is pressuring suppliers to reformulate chemistries before enforcement timelines solidify.
- Cross-Border Certification Fragmentation:Diverging test protocols between Canadian Standards Association and Underwriters Laboratories threaten to inflate inventory carrying costs for brands serving both national markets.
- Polyester Input Volatility:Entry-level canopy margins compress when petroleum-derived polyester feedstock prices spike, forcing manufacturers to absorb costs or sacrifice volume.
Strategic Opportunities
- Emergency Response Vertical:Municipal emergency management agencies in hurricane-prone Gulf Coast states represent underpenetrated demand for rapid-deploy shelter systems.
- NFPB 701 Fire-Resistance Premium Tier:Fire-retardant certification requirements open margin pools in commercial segments that residential buyers rarely demand.
- Weekend-Market Operator Channel:Food vendors and pop-up retailers are prioritizing sub-two-minute setup protocols, creating pull for engineered rapid-deployment systems.
Industry Challenges
- CSA-UL Reciprocity Negotiations:Brands serving both US and Canadian markets face timeline uncertainty as certification reciprocity talks stall, complicating product line planning.
- Anchoring Engineering Talent:Wind-load engineering expertise for 35-70 mph rated structures is scarce, slowing R&D cycles for next-generation frame geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Freestanding Canopy Market |
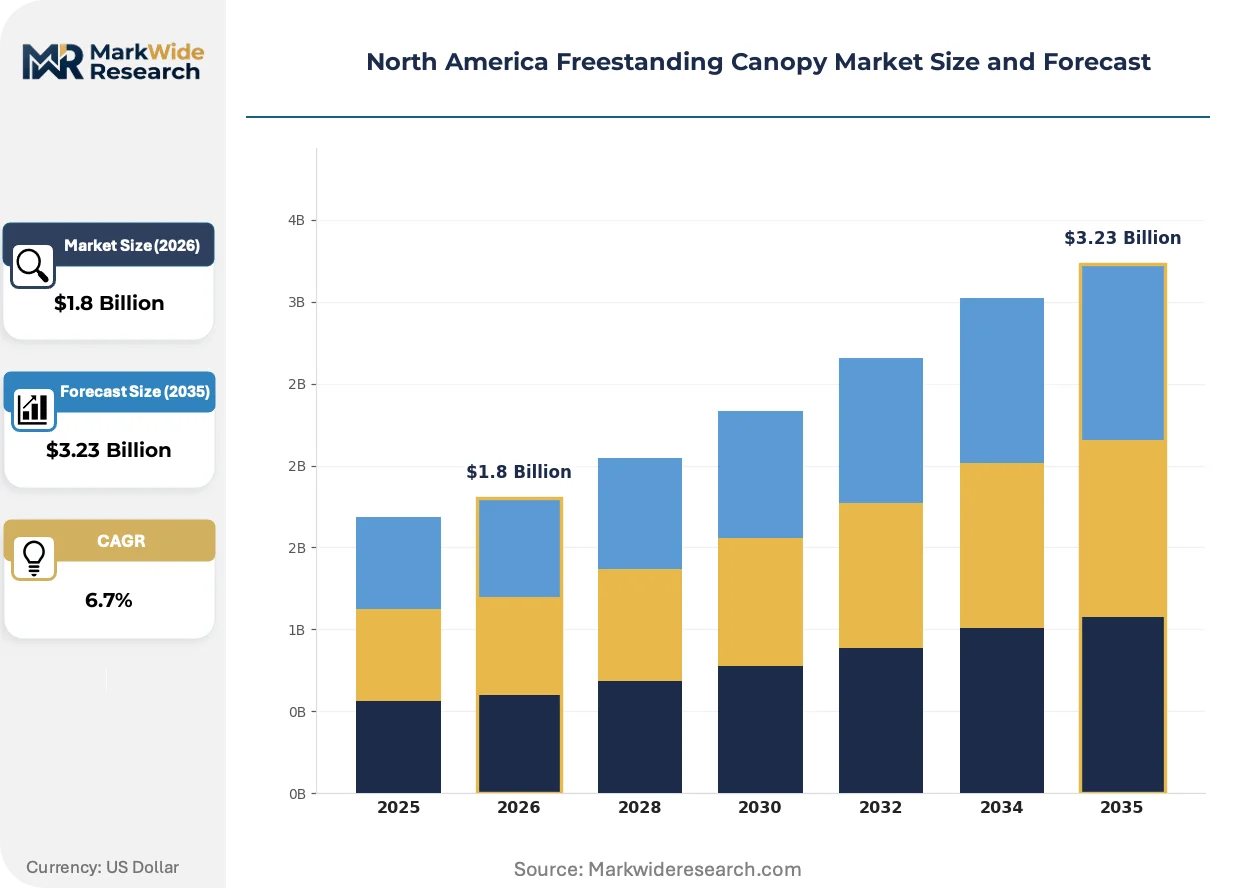
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Canopies, Pop-Up Canopies, Commercial Grade Canopies, Custom Canopies Material: Polyester, Vinyl, Canvas, HDPE End User: Residential, Commercial, Event Planners, Outdoor Sports Application: Picnics, Outdoor Events, Trade Shows, Emergency Shelters |
| Companies Covered | ShelterLogic, Caravan Canopy, E-Z UP, Abba Patio, Poggesi, ShadeFX, Quik Shade, King Canopy, Tentsile, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Freestanding Canopy Market Trends and Innovations
Modular aluminum framing systems and advanced fabric coatings are actively reshaping product architecture, while regulatory pressure on chemical treatments and buyer expectations for deployment speed are compressing traditional manufacturing timelines.
Modular aluminum extrusion systems with tool-free connection nodes are decomposing the traditional welded-steel frame paradigm. Food vendors and weekend-market operators across Texas and Florida are adopting these systems at accelerating rates. The technology is decomposing incumbent supplier relationships by enabling end-users to self-service repairs and expand footprint without manufacturer dependency.
NFPA 701 fire-resistance standards are tightening enforcement timelines across Ontario and Quebec provincial building codes. Commercial-grade canopy manufacturers serving cross-border demand must now dual-certify fabric treatments, adding 8-12 weeks to production schedules. Event-production professionals in Toronto and Montreal are responding by consolidating procurement with vendors holding pre-certified inventory.
Rental-to-retail channel migration is accelerating as big-box chains capture weekend-market operators previously served by specialty dealers. The Midwest and Southeast are seeing the fastest displacement of independent canopy retailers. California event planners remain the exception, maintaining direct manufacturer relationships for custom-engineered corporate installations.
North America Freestanding Canopy Market Segmentation
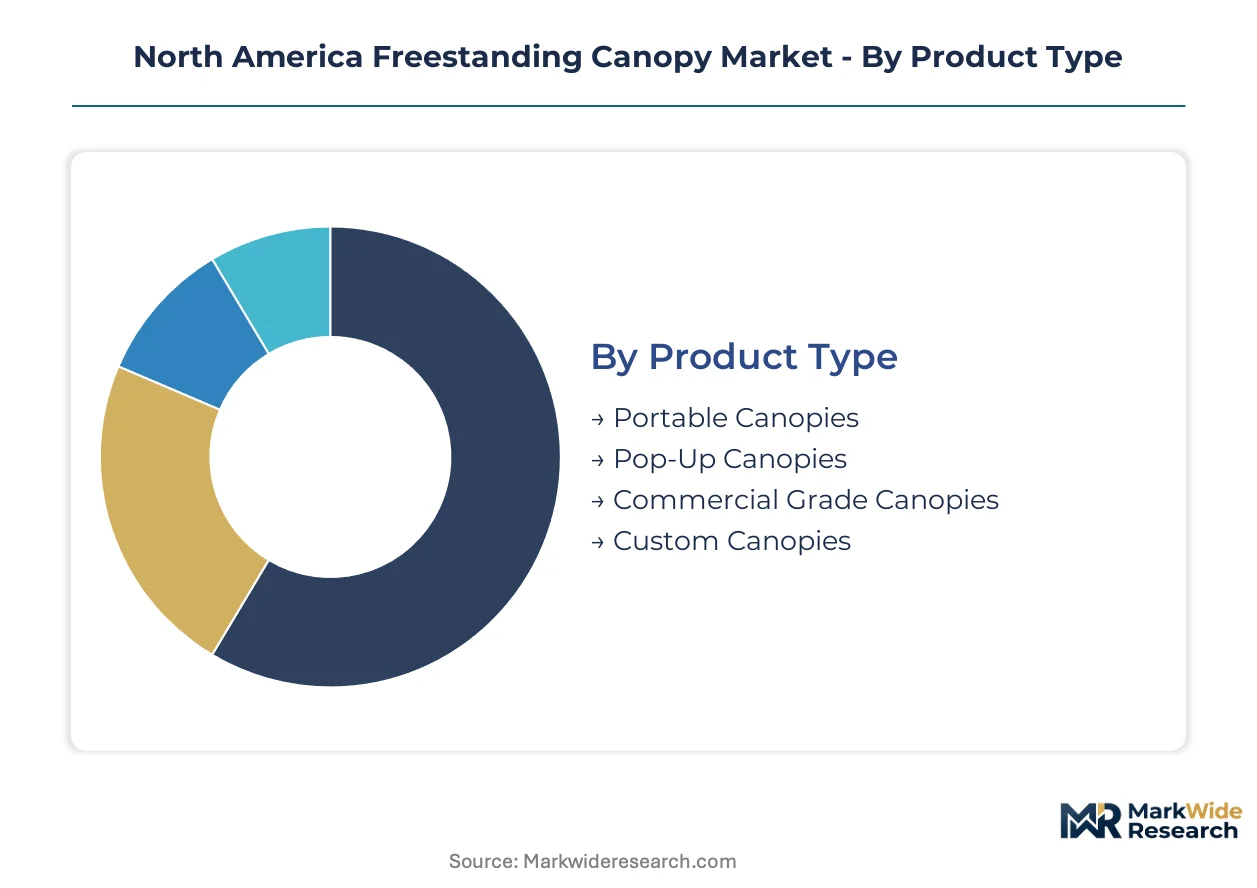
ASTM F2374-17 certification requirements fragment procurement patterns across the North America freestanding canopy market. Regulatory tiering creates distinct margin pools that reshape manufacturer prioritization and channel investment.
Product Type:
Certification mandates from the FAA and NFPA 701 split commercial viability across frame engineering approaches, with wind-load ratings and fire-resistance compliance determining channel access.
- Portable Canopies:Lightweight aluminum or steel framing with polyester membranes dominates weekend-market operators in Texas and Florida. Food vendors prioritize sub-two-minute deployment protocols over structural permanence.
- Pop-Up Canopies:Tensioned fabric systems with scissor-lift mechanisms serve event-production professionals requiring rapid field deployment. California wedding planners and corporate event coordinators sustain replacement cycles through premium-grade purchases.
- Commercial Grade Canopies:Engineered steel-frame structures with NFPA 701-certified fabrics command rental company procurement at airport-adjacent venues.
- Custom Canopies:Bespoke engineered solutions with proprietary anchoring systems address municipal emergency management specifications in hurricane-prone Gulf Coast states.
Established volume favors portable canopies; emerging adoption favors commercial grade systems.
Material:
EPA pressure on PFAS-treated water-repellent coatings is forcing chemistry reformulation across fabric tiers, with compliance timelines compressing supplier R&D cycles.
- Polyester:Petroleum-derived synthetic dominates entry-level unit production. Price volatility in feedstock markets squeezes manufacturer margins during crude oil spikes.
- Vinyl:PVC-coated polyester laminates deliver UV degradation resistance for premium outdoor commerce installations in California and Texas.
- Canvas:Cotton-polyester blends with fire-retardant treatments serve heritage aesthetic requirements at upscale outdoor weddings.
- HDPE:High-density polyethylene mesh fabrics penetrate agricultural and semi-permanent shade applications with extended service life specifications.
Polyester anchors current production volume; vinyl climbs fastest on durability premiums.
End User:
Procurement sophistication varies sharply across buyer categories, with commercial entities demanding certified documentation that residential purchasers rarely request.
- Residential:Backyard recreation and seasonal shade drive seasonal purchasing concentrated through big-box retail channels in the Midwest and Southeast.
- Commercial:Corporate campus installations and permanent outdoor dining structures in California sustain custom-engineering relationships with domestic manufacturers.
- Event Planners:Toronto and Montreal coordinators consolidate vendor relationships around pre-certified NFPA 701 inventory to circumvent cross-border compliance delays.
- Outdoor Sports:Tournament operators and youth league organizers prioritize rapid-deploy systems with standardized footprint configurations.
Commercial buyers concentrate margin extraction; event planners drive specification escalation fastest.
Application:
Wind-load engineering requirements and occupancy density regulations create divergent product performance thresholds across use scenarios.
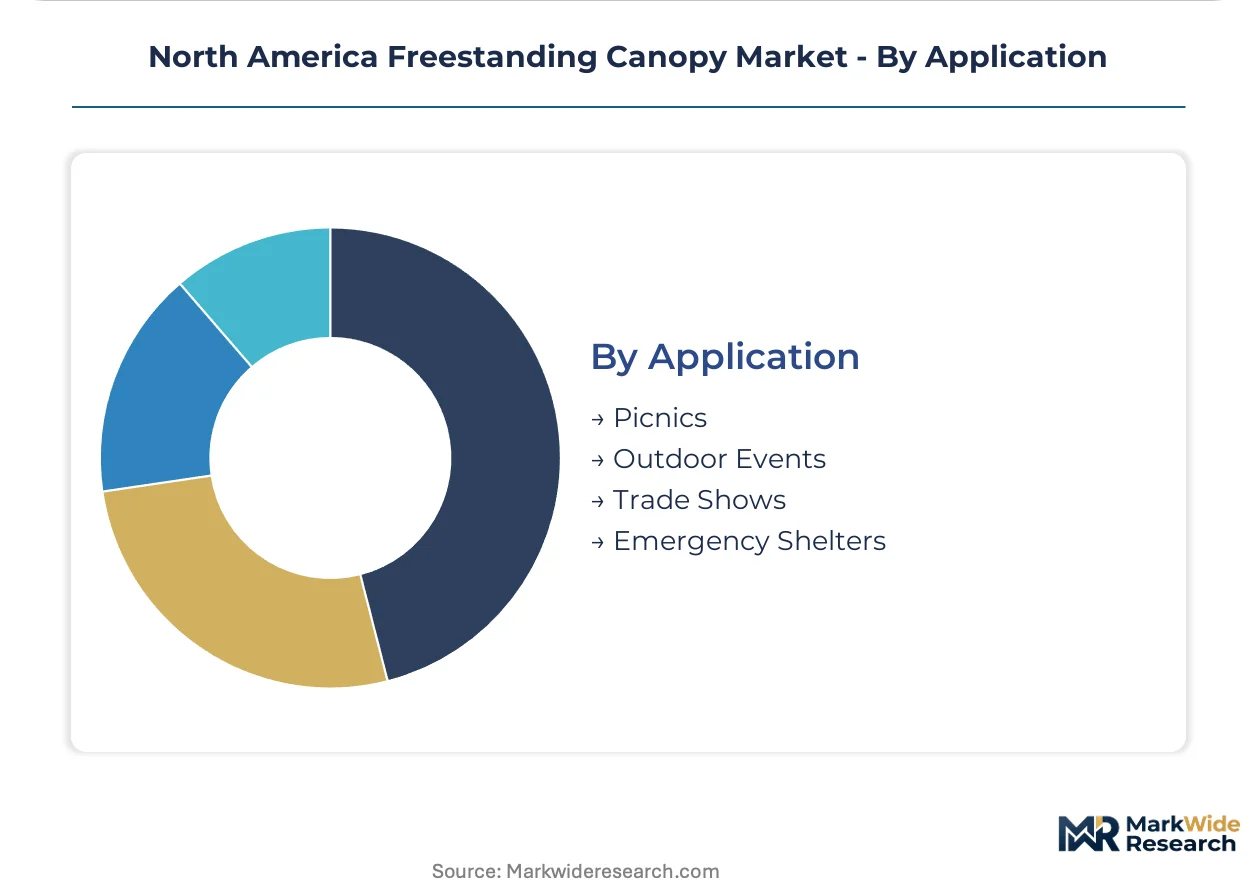
- Picnics:Casual recreational deployment favors lightweight pop-up systems with minimal anchoring complexity for consumer-grade purchasers.
- Outdoor Events:Wedding and festival applications in California and Texas sustain premium pricing for fire-retardant certified custom installations.
- Trade Shows:Exhibition hall adjacent deployments require FAA-compliant temporary structures with engineered ballast or staking protocols.
- Emergency Shelters:Municipal procurement in Gulf Coast states represents underpenetrated demand for rapid-deploy systems with 35-70 mph wind ratings.
Outdoor events dominate current revenue; emergency shelters present steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Event planners and commercial buyers concentrate procurement in coastal states and cross-border corridors where outdoor commerce operates year-round. ASTM F2374-17 certification requirements reshape supplier access across national boundaries.
United States
California wedding planners and Texas food vendors sustain replacement cycles for premium-grade systems. FAA temporary structure guidelines at airport-adjacent venues in Florida and Georgia create compliant product demand from rental operators. Chicago-area steel fabricators leverage captive production to defend price positions against offshore alternatives.
Canada
Toronto and Montreal event coordinators consolidate vendor relationships around pre-certified NFPA 701 inventory. Provincial building codes in Ontario and Quebec tighten enforcement timelines, compressing procurement windows. Vancouver's outdoor hospitality sector drives custom-engineering relationships with cross-border manufacturers.
Mexico
Weekend-market operators in Mexico City Metro and Guadalajara prioritize portable systems for informal commerce. Uncertified imports face disqualification from commercial procurement channels under harmonizing ASTM standards. Baja California suppliers serve California buyers seeking rapid fulfillment for emergency response applications.
North America Freestanding Canopy Market Competitive Landscape
Player mix skews toward vertically integrated domestic manufacturers and import-dependent assemblers competing on deployment speed. The supplier base compresses under certification mandates that disqualify uncertified offshore competitors from commercial channels. Two strategic archetypes dominate: Illinois-based steel-frame producers with captive fabrication, and rapid-deployment specialists targeting sub-two-minute setup protocols. Competitive moves center on certification pre-positioning and retail channel consolidation.
Among domestic manufacturers with Midwest production footprints, ShelterLogic and Caravan Canopy exemplify the integrated fabrication archetype. E-Z UP occupies a position within the rapid-deployment tier, representing engineering-focused differentiation for event-production professionals. These three anchors illustrate how certification compliance and channel access separate sustainable competitors from retreating import-dependent suppliers.
| Leading Market Players |
|---|
| ShelterLogic |
| Caravan Canopy |
| E-Z UP |
| Abba Patio |
| Poggesi |
| ShadeFX |
| Quik Shade |
| King Canopy |
| Tentsile |
| Others |
Pricing and Supply Chain Analysis
ASTM F2374-17 certification gates both supplier qualification and price differentiation across the North America freestanding canopy market, compressing the vendor base while concentrating margin extraction among pre-certified domestic manufacturers serving commercial procurement channels.
Pricing Analysis
Cost-plus contracts with steel indexation dominate commercial-grade canopy procurement, tying frame pricing to Chicago-area commodity benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates NFPA 701-certified commercial systems from residential pop-ups and entry-level polyester units. Cost compression in the entry tier intensifies because petroleum-derived feedstock volatility squeezes manufacturer margins during crude oil spikes. Weekend-market operators in Texas and Florida exhibit highest price sensitivity, while California event planners purchasing custom-engineered installations show lowest elasticity.
Supply Chain Analysis
Port congestion along the Los Angeles-Long Beach corridor and container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for offshore fabric and component shipments. Steel frame production concentrates in Illinois and Ohio, with fabric membrane sourcing drawing from South Carolina textile mills and selected Asian coating facilities. Raw material dependencies rest on cold-rolled steel, PVC-coated polyester laminates, and fire-retardant chemical treatments. Single-source vulnerability in PFAS-free coating formulations threatens supply continuity as EPA enforcement timelines approach. Distribution runs through big-box retail chains in the Midwest and Southeast, alongside direct manufacturer relationships with California commercial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind-load engineering expertise for 35-70 mph rated structures sits in short supply, constraining R&D velocity for next-generation frame geometries and compressing competitive differentiation to certification pre-positioning and captive production assets.
For Market Incumbents: Consolidate certification holdings by accelerating NFPA 701 pre-certification of fabric inventory ahead of Ontario and Quebec enforcement timelines. Deepen backward integration into Illinois-based steel galvanizing to defend price positions against offshore alternatives retreating to residential segments. Anchor channel control through exclusive supply agreements with big-box chains displacing independent retailers across the Midwest. For New Entrants and Emerging Players: Lead with rapid-deployment engineering protocols targeting food vendors and weekend-market operators prioritizing sub-two-minute setup speeds. Municipal emergency management agencies in Gulf Coast states represent the most penetrable demand cluster, with hurricane-preparedness procurement cycles creating pull for engineered shelter systems. Pursue direct sales relationships with Toronto and Montreal event coordinators circumventing cross-border compliance delays through pre-certified inventory positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across commercial-grade canopy manufacturing as dual-certification requirements for CSA and UL testing fragment product lines and inflate inventory carrying costs. Viable acquisition targets combine captive steel-frame fabrication with established NFPA 701-certified fabric treatment capabilities, serving both US and Canadian procurement channels. Watch for reciprocity negotiations between Canadian Standards Association and Underwriters Laboratories as the signal indicating timeline certainty for cross-border inventory rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | NFPA 701 pre-certified inventory secures access to Toronto and Montreal event procurement channels ahead of enforcement. |
| Backward Integration into Steel | Captive Illinois galvanizing capacity defends margin structure against offshore frame imports disqualified by ASTM F2374-17. |
| Rapid-Deployment Engineering | Sub-two-minute setup protocols capture food vendor demand in Texas and Florida weekend markets. |
| Emergency Response Vertical Entry | Municipal Gulf Coast procurement for hurricane-rated shelters opens underpenetrated demand with 35-70 mph specifications. |
| Cross-Border Inventory Rationalization | CSA-UL reciprocity alignment would compress carrying costs for manufacturers serving both US and Canadian markets. |
Research Methodology
A spread of perspectives from canopy manufacturing plant managers, event rental company procurement directors, big-box retail category buyers, steel fabrication specialists, and municipal emergency management officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA temporary structure guidelines, EPA PFAS regulatory filings, ASTM certification databases, and provincial building code amendments in Ontario and Quebec. Bottom-up unit economics triangulated against top-down market sizing across product type, material grade, end-user category, and application scenario.
Segmentation dimensions modeled include frame engineering approach, fabric membrane chemistry, wind-load rating tier, fire-resistance certification status, buyer procurement sophistication, and geographic regulatory cluster across the projection horizon. CAGRs were derived from fitted growth curves calibrated to replacement cycle frequencies in California and Texas, cross-referenced with commercial event expansion rates and certification mandate compliance timelines. Industry-specific forecast inputs incorporated steel price index trajectories and polyester feedstock volatility assumptions.
The analysis sits within stated boundaries; outcomes outside sustained commercial event expansion, stable ASTM-CSA reciprocity negotiations, or manageable PFAS reformulation timelines would require recalibration. Forecasts reflect documented assumptions regarding certification enforcement schedules and raw material input trajectories. Recalibration cycles align with material shifts in regulatory enforcement timelines, commodity price inflections, and cross-border certification reciprocity developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Silos Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Global Steel Pipe Piles Market