
 Technical Insulation Market | 2026-2036
Technical Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Insulation Market Intelligence
The skilled installer labor pool for industrial insulation systems is collapsing across mature economies, tightening project timelines and elevating contractor premiums. Armacell International leverages its global fabrication network to pre-engineer insulation kits that reduce field labor hours. Rockwool SA anchors its position through dense production assets in Northern Europe that sustain specification-grade mineral wool supply. Owens Corning competes by extending its fiberglass formulation expertise into higher-temperature industrial envelopes previously served by mineral wool.
Technical insulation comprises engineered materials designed to control thermal energy transfer, limit fire propagation, and attenuate mechanical vibration in industrial process equipment, typically specified by conductivity values measured in W/m·K and maximum service temperature thresholds. Mineral wool dominates volume in high-temperature power generation and petrochemical applications where thermal stability above 700°C is mandatory, while foam products capture margin in offshore marine and cryogenic LNG infrastructure where low-density, low-conductivity envelopes reduce structural load. Fiberglass occupies a mature position in commercial and light industrial HVAC ducting, whereas calcium silicate specializes in load-bearing pipe support and block insulation where compressive strength requirements exclude softer alternatives.
The EPA enforces emissions and workplace exposure limits that shape material selection and removal protocols in US industrial facilities, while REACH and the EU F-Gas Regulation restrict chemical constituents in foam blowing agents sold across European member states. China's GB standards and MEE oversight impose parallel constraints on domestic production and import certification, fragmenting compliance pathways for multinational suppliers. Buyers must monitor divergence between regional chemical registries and thermal performance test methods when qualifying products for cross-border project portfolios.
Market Dynamics
The EU F-Gas Regulation is compressing foam blowing agent chemistries across European supply chains while simultaneously pulling demand toward mineral wool alternatives in high-temperature process envelopes.
Growth Catalysts
- Offshore LNG infrastructure buildout:Cryogenic storage and transport systems require ultra-low conductivity foam systems that reduce structural load on floating platforms.
- REACH chemical restrictions:The European framework is accelerating substitution of legacy blowing agents with next-generation low-GWP formulations in polyurethane foams.
- Aging refinery retrofit cycles:North American and European petrochemical operators are replacing degraded thermal barriers to meet tightened energy efficiency mandates.
Market Restraints
- Blowing agent input volatility:Hydrofluoroolefin and hydrocarbon feedstock prices fluctuate with energy markets, compressing foam manufacturer margins unpredictably.
- Mineral wool supply concentration:Dense production assets in Northern Europe create geographic vulnerability to energy cost spikes and logistics disruptions.
- Technical limitation in cryogenic range:Fiberglass formulations cannot achieve the thermal performance thresholds required for LNG minus 162 degree Celsius service, excluding the material from the fastest-growing application segment.
Strategic Opportunities
- India industrial corridor expansion:The country's PLI scheme and domestic manufacturing push are generating greenfield specification opportunities in chemicals and power generation.
- Pre-engineered insulation kits:Modular fabrication models reduce field labor hours and address the collapsing skilled installer pool across mature economies.
- EU Green Deal building renovation wave:Industrial facility energy audits are mandating thermal envelope upgrades that expand addressable market for high-performance materials.
Industry Challenges
- Certified installer scarcity:Industrial insulation systems require specialized application techniques; the shrinking qualified labor pool extends project timelines and elevates contractor premiums.
- Cross-border compliance fragmentation:Divergence between EPA workplace exposure limits, REACH chemical registries, and China's GB standards forces manufacturers to maintain parallel product portfolios.
- Legacy system integration complexity:Retrofit projects must interface with aged pipe support structures and irregular equipment geometries that resist standardized insulation geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Insulation Market |
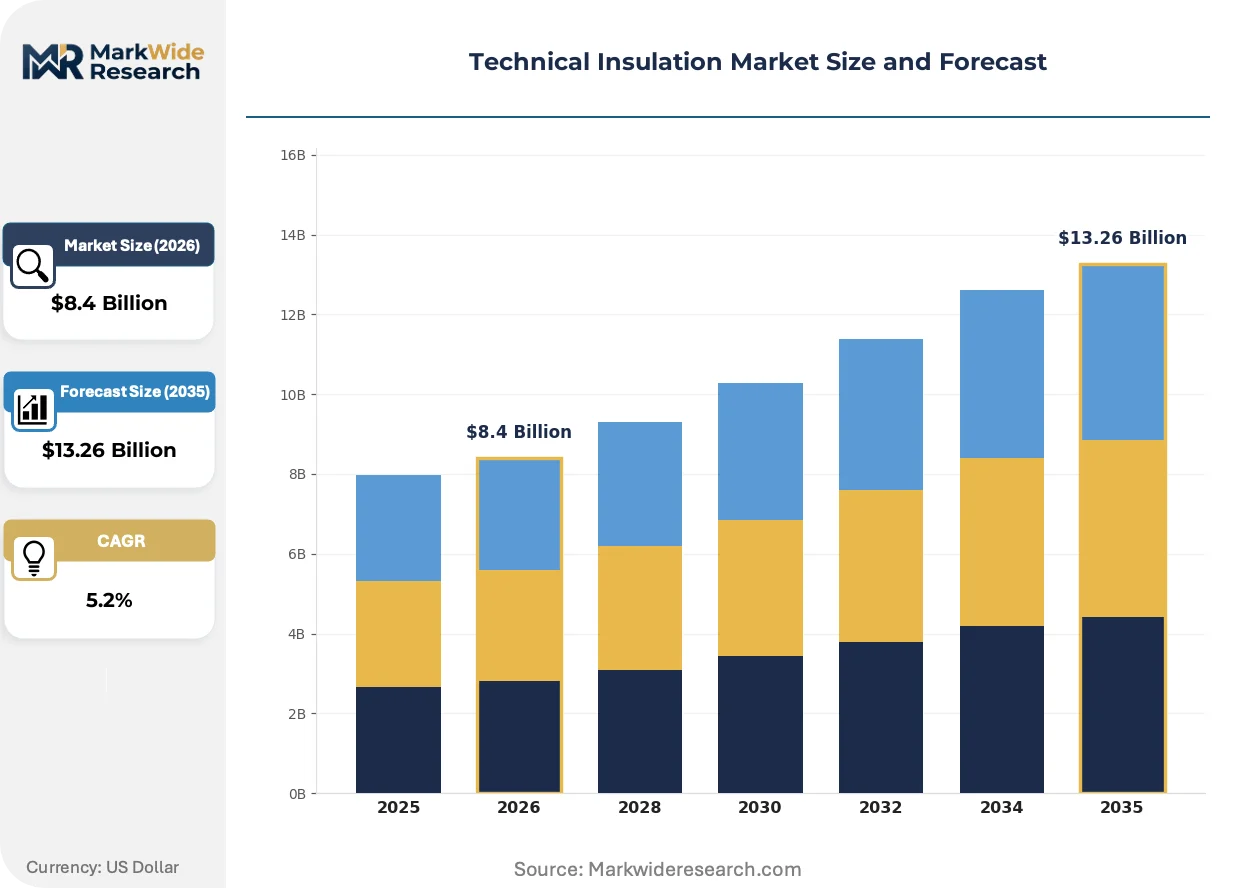
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Mineral Wool, Fiberglass, Calcium Silicate End User: Oil & Gas, Chemicals, Power Generation, Marine Installation Type: Onshore, Offshore, Industrial, Comercial Thermal Conductivity: Low Thermal Conductivity, Medium Thermal Conductivity, High Thermal Conductivity, Ultra-Low Thermal Conductivity |
| Companies Covered | Knauf Insulation, Armacell International, Rockwool SA, Morgan Advanced Materials, L’ISOLANTE K-FLEX, Saint-Gobain Isover, Kingspan Group, ETEX, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Insulation Market Strategic Shifts & Innovations
Aerogel composites and bio-based blowing agents are disrupting established material hierarchies while digital specification tools compress procurement cycles for complex industrial envelopes.
Aerogel blanket systems are supplanting traditional multi-layer insulation in space-constrained high-temperature applications. Petrochemical and power generation engineers specify these silica-based materials where thermal performance must fit within tight clearance envelopes. The technology is compressing insulation thickness requirements by fifty to seventy percent versus mineral wool equivalents, enabling equipment layouts previously impossible.
The EU F-Gas Regulation is forcing wholesale reformulation of polyurethane foam blowing agent portfolios. Manufacturers must phase down hydrofluorocarbon chemistries with global warming potentials above 150, redirecting R&D expenditure toward hydrocarbon and hydrofluoroolefin alternatives. European foam producers are accelerating qualification timelines for next-generation formulations to maintain specification eligibility in marine and cryogenic segments.
Engineering-procurement-construction firms are consolidating supplier relationships around full-service insulation system providers. Single-source accountability for material supply, fabrication, and installation supervision is displacing fragmented multi-vendor procurement models. This concentration is most visible in German and US Gulf Coast petrochemical projects where schedule risk transfer has become a primary contractor selection criterion.
Technical Insulation Market Segmentation
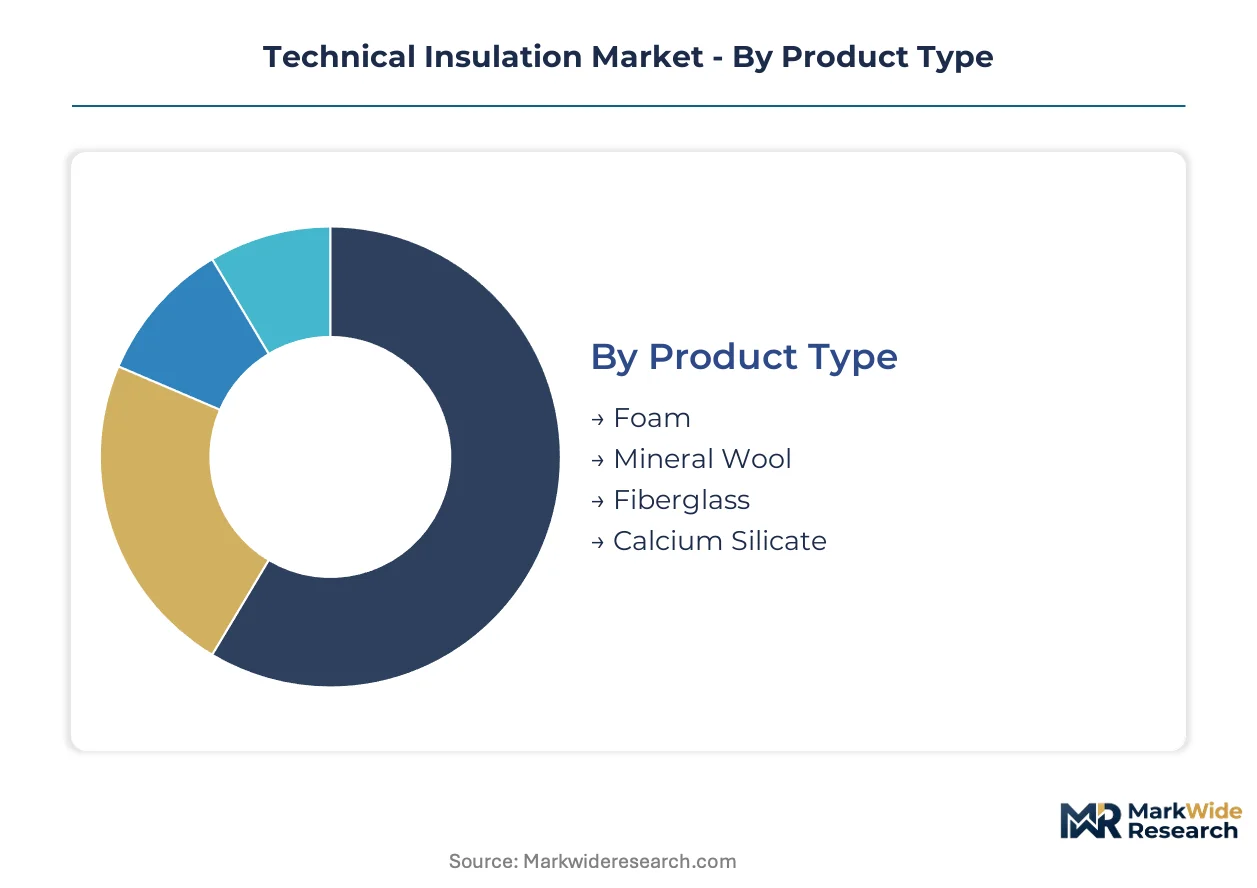
Technical insulation procurement follows distinct specification pathways where material chemistry, thermal performance thresholds, and installation environment dictate vendor selection and pricing tiers.
Product Type:
Margin pools concentrate in low-density foam formulations where cryogenic LNG applications command premium pricing against standardized mineral wool specifications.
- Foam:Polyurethane and polyisocyanurate systems deliver ultra-low thermal conductivity through hydrocarbon or hydrofluoroolefin blowing agents. Offshore LNG infrastructure in the United States and Qatar specifies these materials to minimize structural load on floating platforms while maintaining minus 162°C service integrity.
- Mineral Wool:Basalt and slag-based fibers withstand continuous exposure above 700°C without thermal degradation. German and Chinese power generation operators specify these materials for boiler insulation and exhaust ducting where fire resistance ratings are mandatory.
- Fiberglass:Glass fiber batts and rigid boards serve commercial HVAC and light industrial applications with moderate temperature requirements.
- Calcium Silicate:Hydrous calcium silicate blocks provide compressive strength for pipe support insulation and load-bearing industrial envelopes.
The dominant share belongs to mineral wool, while foam is closing the gap fastest.
End User:
Application intensity varies sharply by sector, with hydrocarbon processing and marine transport imposing the most stringent thermal performance specifications.
- Oil & Gas:Upstream, midstream, and downstream operators retrofit aging refineries and construct greenfield LNG export terminals. North American and Middle Eastern project pipelines specify multi-layer insulation systems for cryogenic storage and high-temperature process vessels.
- Marine:Shipbuilders and offshore platform fabricators require lightweight, low-conductivity materials that reduce fuel consumption and structural steel requirements. South Korean and Japanese shipyards are expanding specification activity for LNG carriers and floating production units.
- Chemicals:Petrochemical complexes demand thermal stability across reactor vessels, distillation columns, and storage tanks.
- Power Generation:Combined cycle gas turbines and coal-fired units require high-temperature insulation for boilers, steam lines, and exhaust systems.
Oil & Gas commands the largest procurement volumes, though marine applications are expanding most quickly.
Installation Type:
Project location and environment dictate material selection, with offshore and cryogenic settings requiring specialized fabrication and application protocols.
- Offshore:Platform and vessel insulation must withstand salt spray, vibration, and space constraints while maintaining thermal performance under dynamic loading conditions.
- Onshore:Refinery, chemical plant, and power station installations allow conventional application methods with standard weatherproofing systems.
- Industrial:Manufacturing facilities and process plants require insulation for rotating equipment, piping networks, and pressure vessels.
- Commercial:Building services and light industrial applications use standardized insulation products with lower performance thresholds.
Onshore installations retain the largest share, while offshore projects are gaining share fastest.
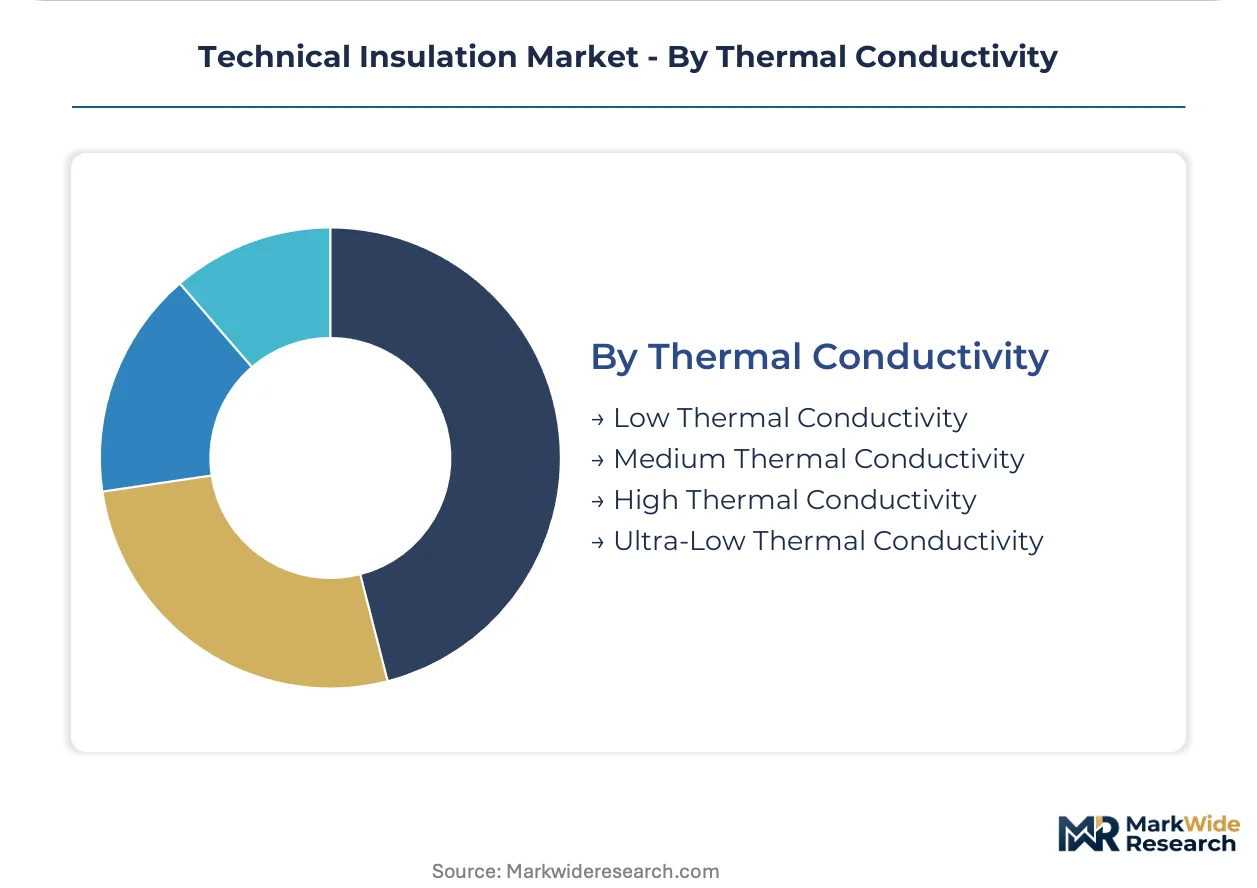
Thermal Conductivity:
Specification-grade differentiation separates commodity insulation from engineered systems, with ultra-low conductivity materials capturing disproportionate margin.
- Ultra-Low Thermal Conductivity:Aerogel composites and advanced foam systems achieve thermal resistance values below 0.020 W/m·K. Petrochemical engineers in Germany and the United States specify these materials where equipment clearances are constrained and heat loss minimization is critical.
- Low Thermal Conductivity:Polyurethane and phenolic foams serve cryogenic and refrigeration applications with conductivity ranging 0.020–0.030 W/m·K.
- Medium Thermal Conductivity:Mineral wool and fiberglass products occupy the broad industrial middle market.
- High Thermal Conductivity:Dense refractory materials and specialized cements serve extreme temperature applications above 1000°C.
Low thermal conductivity materials dominate procurement value, while ultra-low conductivity grades are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical insulation consumption patterns diverge sharply by geography. German engineers prioritize mineral wool for high-temperature power envelopes, while US Gulf Coast operators favor foam systems for cryogenic LNG infrastructure, and Chinese procurement emphasizes cost-optimized fiberglass for industrial HVAC scale deployment.
United States
Petrochemical retrofit cycles and offshore LNG export terminal construction dominate demand. EPA emissions enforcement and OSHA workplace exposure protocols shape material removal and specification protocols. The Texas-Louisiana Gulf Coast corridor concentrates greenfield insulation procurement for cryogenic storage and process vessel applications.
Germany
Power generation boiler insulation and industrial exhaust ducting drive mineral wool volumes. EU F-Gas Regulation mandates accelerate transitions away from high-GWP foam blowing agents. The Ruhr industrial cluster and Bavarian chemical corridors sustain dense specification activity for high-temperature process envelopes.
China
Industrial HVAC scale deployment and chemical plant construction absorb standardized fiberglass and mineral wool volumes. GB standards and MEE oversight impose domestic certification requirements on imported foam systems. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate procurement for process equipment insulation.
India
Greenfield power generation and petrochemical complex buildouts generate specification opportunities. PLI scheme incentives and domestic manufacturing mandates reshape local supply chain configurations. The Gujarat Industrial Corridor and Maharashtra chemical clusters anchor emerging demand for high-performance thermal barriers.
Saudi Arabia
Downstream refinery expansion and petrochemical integration projects sustain premium insulation procurement. The country's national industrial regulator enforces thermal performance standards for process safety compliance. The Eastern Province industrial cities of Jubail and Yanbu concentrate large-project specification activity for high-temperature applications.
Technical Insulation Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in technical insulation supply. The upper tier commands specification relationships with EPC firms and maintains captive fabrication networks. The specialist tier competes on regional proximity and application-specific expertise. Two dominant competitive moves reshape positioning: backward integration into raw material production to secure blowing agent supply, and pre-engineered kit fabrication to capture collapsing field labor pools.
Within the integrated multinational tier, Armacell International and Rockwool SA exemplify divergent strategic anchors. Armacell occupies a position associated with global fabrication networks and pre-engineered system delivery. Rockwool sits within the mineral wool specialization vector, leveraging dense Northern European production assets. Owens Corning represents the fiberglass formulation extension archetype, competing for industrial envelope share previously served by mineral wool alternatives. These three entities illustrate how material chemistry specialization and geographic production concentration define competitive positioning.
| Leading Market Players |
|---|
| Knauf Insulation |
| Armacell International |
| Rockwool SA |
| Morgan Advanced Materials |
| L'ISOLANTE K-FLEX |
| Saint-Gobain Isover |
| Kingspan Group |
| ETEX |
| Owens Corning |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between EPC contractors and foam manufacturers lock in blowing agent supply access while providing price visibility across volatile hydrocarbon feedstock cycles. German petrochemical operators and US Gulf Coast LNG developers favor these structures to hedge against hydrofluoroolefin cost spikes triggered by EU F-Gas Regulation phase-down schedules.
Pricing Analysis
Project-based contracting dominates procurement for large industrial envelopes, with pricing stratifying across premium, standard, and economy tiers based on thermal conductivity certification and installation complexity. Armacell International and Rockwool SA command premiums for pre-engineered kits and specification-grade mineral wool respectively, while commodity fiberglass faces price erosion from Chinese import competition. Cost compression in standard-grade mineral wool is intensifying because Northern European energy costs feed directly into slag fiber production economics. Downstream chemical operators exhibit highest price sensitivity, whereas marine and offshore buyers prioritize performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of hydrofluoroolefin blowing agents has become standard practice among European foam producers navigating REACH-mandated formulation transitions. Raw material supply draws from Germany, China, and the United States for specialized blowing agent chemistries, basalt fiber feedstock, and glass cullet respectively. Single-source vulnerability concentrates in hydrofluoroolefin supply chains where patent-protected formulations limit qualified suppliers. Distribution runs through EPC contractor networks that consolidate material procurement, fabrication, and installation supervision into single-source accountability structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around engineering-procurement-construction firms that consolidate supplier relationships and transfer schedule risk to insulation system providers. This consolidation fragments procurement decisions across fewer decision-makers with expanded technical qualification requirements.
For Market Incumbents: Secure captive supply of next-generation low-GWP blowing agents through backward integration or exclusive offtake agreements before EU F-Gas Regulation phase-down deadlines eliminate legacy formulations. Expand pre-engineered kit fabrication capacity in the United States and Germany to capture collapsing skilled installer pools and defend margin position against labor cost inflation. For New Entrants and Emerging Players: Anchor in India's Gujarat Industrial Corridor and Maharashtra chemical clusters where PLI scheme incentives and greenfield project pipelines create specification opportunities without entrenched incumbent relationships. Target cryogenic LNG applications in South Korean and Japanese shipyards with aerogel composite offerings that bypass mineral wool and fiberglass thermal performance limitations. For Investors and Strategic Acquirers: Capital is best deployed toward fabrication-network specialists with captive pre-engineering capabilities and established EPC contractor relationships that sustain recurring specification flow. The inflection signal to watch is qualified installer wage inflation crossing thresholds that accelerate modular kit adoption versus field-fabricated alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agents | Captures supply security for EU F-Gas Regulation compliance and hedges hydrocarbon feedstock volatility. |
| Pre-Engineered Kit Fabrication Expansion | Addresses certified installer scarcity in Germany and the United States while compressing project timelines. |
| Aerogel Composite Qualification | Enables penetration of space-constrained petrochemical applications previously served by multi-layer mineral wool. |
| India Manufacturing Footprint Establishment | Aligns with PLI scheme incentives and domestic content requirements in Gujarat and Maharashtra corridors. |
| EPC Contractor Partnership Consolidation | Captures single-source accountability demand from US Gulf Coast and German petrochemical project developers. |
Research Approach
Initial hypotheses were tested against primary input from EPC procurement directors, plant engineers at petrochemical facilities, insulation contractor operations managers, and regulatory affairs specialists, then refined through secondary validation against SEC filings, customs trade data, EU F-Gas Regulation implementation reports, and REACH chemical registry updates. Bottom-up volume estimates derived from project pipeline databases were triangulated with top-down market sizing from industry association reports.
Variance decomposition across product type, end-use sector, installation environment, and thermal conductivity grade shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate distributions calibrated to historical retrofit cycle timing and greenfield project announcement flows. Forecast inputs incorporated LNG infrastructure buildout schedules, refinery energy efficiency mandate compliance deadlines, and aerogel manufacturing capacity expansion announcements.
Underlying assumptions cover regulatory phase-down timelines, skilled labor availability trajectories, and blowing agent feedstock price stability, with deviation risk concentrated in EU F-Gas Regulation enforcement intensity and India PLI scheme implementation pace. Revision becomes warranted when certified installer wage inflation or hydrofluoroolefin supply disruption crosses thresholds that materially alter modular kit adoption economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Railing Market
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
GCC Ceramic Tiles Market