
 North America and Europe Snow Blowers Market | 2026-2036
North America and Europe Snow Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Snow Blowers Market Analysis
Market Context
The capital-intensity divergence between foundry-capable incumbents and asset-light assemblers is unwinding competitive stability across the North America and Europe Snow Blowers Market. Honda Power Equipment leverages captive engine manufacturing to control cost volatility and supply continuity through Midwest winters. Ariens sustains domestic forging and fabrication in Wisconsin, insulating its two-stage lineup from trans-Atlantic logistics friction. Husqvarna AB anchors European distribution through Scandinavian retail networks while competing on battery platform interoperability.
Technical Definition and Segment Structure
North America and Europe Snow Blowers are self-propelled or tractor-mounted machines using auger-and-impeller systems to collect and discharge snow, with clearing widths spanning 18 to 45 inches and engine outputs from 5 to 25 horsepower for residential through municipal applications. Two-stage gas models dominate contractor and municipal fleets where wet, heavy snow demands throwing distances exceeding 40 feet, while battery units are displacing single-stage gas in residential driveways under 1,000 square feet. Riding snow blowers command premium positioning in rural estate and commercial campus segments where attachment versatility offsets capital outlay. The 25-30 inch capacity tier captures the fastest structural expansion as hybrid power trains bridge runtime anxiety and emissions compliance.
Regulatory Framework
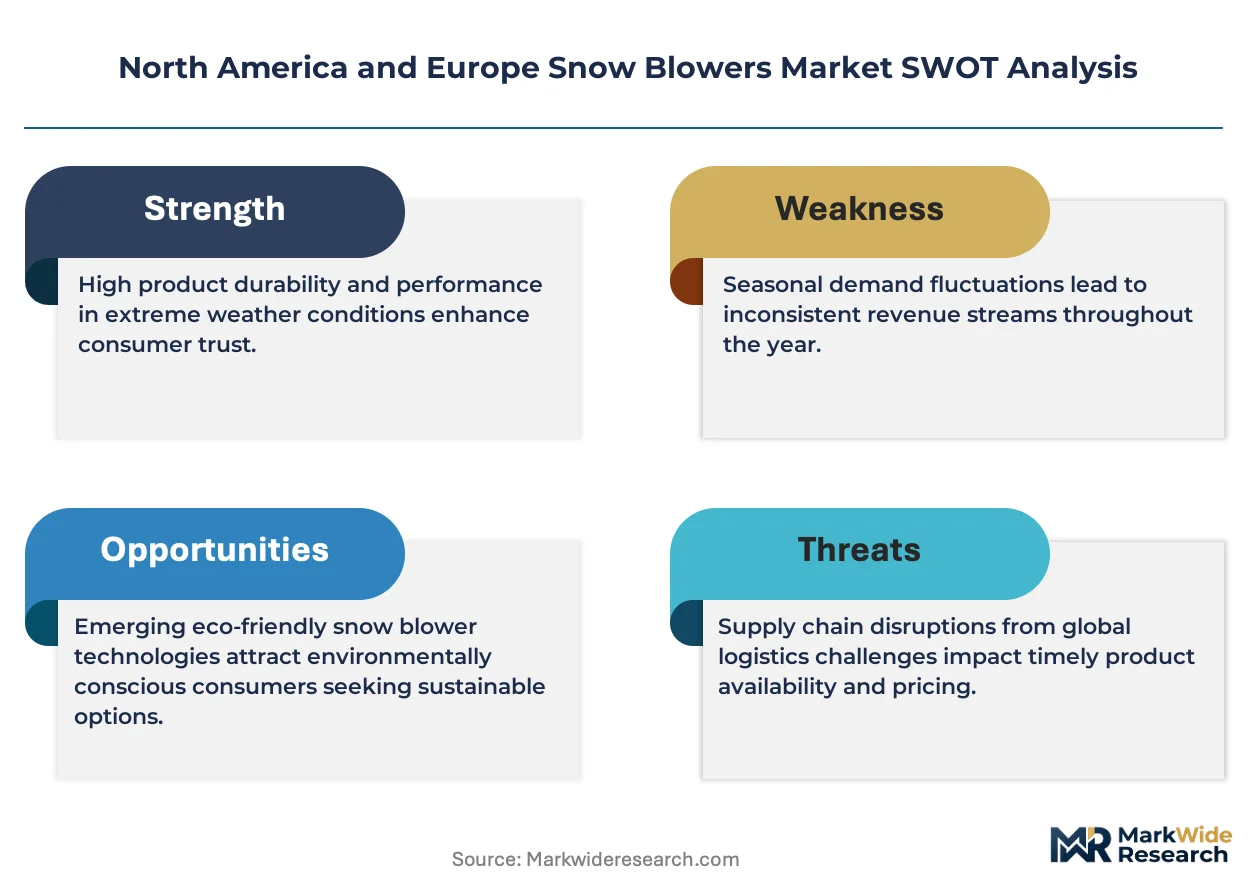
EPA Phase 3 standards and the EU F-Gas Regulation are forcing engine redesigns and refrigerant exclusions that elevate R&D burn rates for gas-powered portfolios. CARB zero-emission mandates in California and New York's Climate Leadership and Community Protection Act are accelerating battery-electric qualification timelines for municipal procurement pools. Stakeholders must monitor state-level buyback incentives and EU Ecodesign preparatory studies that will determine which power source architectures secure long-term fleet certification.
Market Dynamics
The collision of EPA Phase 3 small spark-ignition engine standards with EU F-Gas refrigerant phase-downs is forcing simultaneous powertrain redesigns across gas and battery portfolios, compressing R&D timelines while elevating compliance costs for foundry-dependent manufacturers.
Growth Catalysts
- CARB zero-emission mandates:California and New York procurement pools now require battery-electric qualification for municipal fleet contracts, accelerating OEM qualification investments.
- Grid-hardened residential zones:Minnesota, Ontario, and Bavaria exhibit elevated battery unit penetration where winter severity meets reliable electricity infrastructure.
- Dual-stage auger-impeller innovation:Hybrid powertrains in the 25-30 inch clearing-width tier bridge runtime anxiety with emissions compliance, opening contractor upgrade cycles.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack economics remain sensitive to cathode material pricing, constraining margin expansion for electric-first portfolios.
- Scandinavian forging concentration:Critical auger and impeller steel supply clusters in Swedish and Finnish foundries create trans-Atlantic logistics exposure.
- Runtime physics in wet snow:Battery energy density limitations prevent full displacement of gas units in municipal applications requiring continuous 8-hour operation.
Strategic Opportunities
- Eastern European municipal fleets:Poland and Czech Republic snow removal authorities lag Nordic electrification rates, presenting first-mover positioning for battery platform suppliers.
- Attachment ecosystem convergence:Riding snow blower compatibility with mid-mount mower decks and front-loaders expands rural estate value propositions.
- EU Ecodesign preparatory studies:Anticipated 2027-2028 ecodesign requirements for outdoor power equipment will favor architectures already compliant with F-Gas and noise directives.
Industry Challenges
- Power electronics talent scarcity:Battery management system firmware engineers and motor control specialists command premium compensation in Midwest manufacturing zones.
- Dual-certification timeline compression:Simultaneous EPA and EU type-approval processes for new engine families extend product launch windows by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Snow Blowers Market |
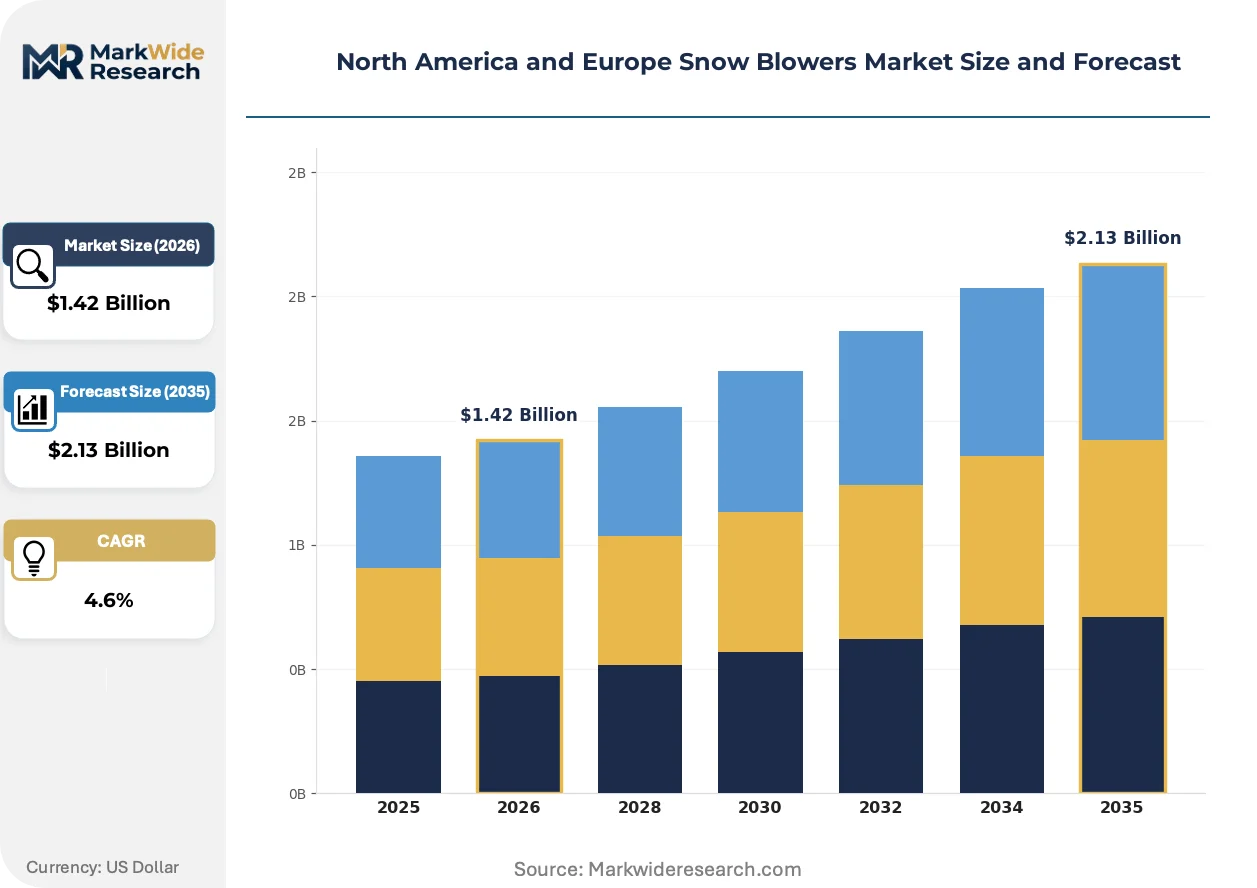
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
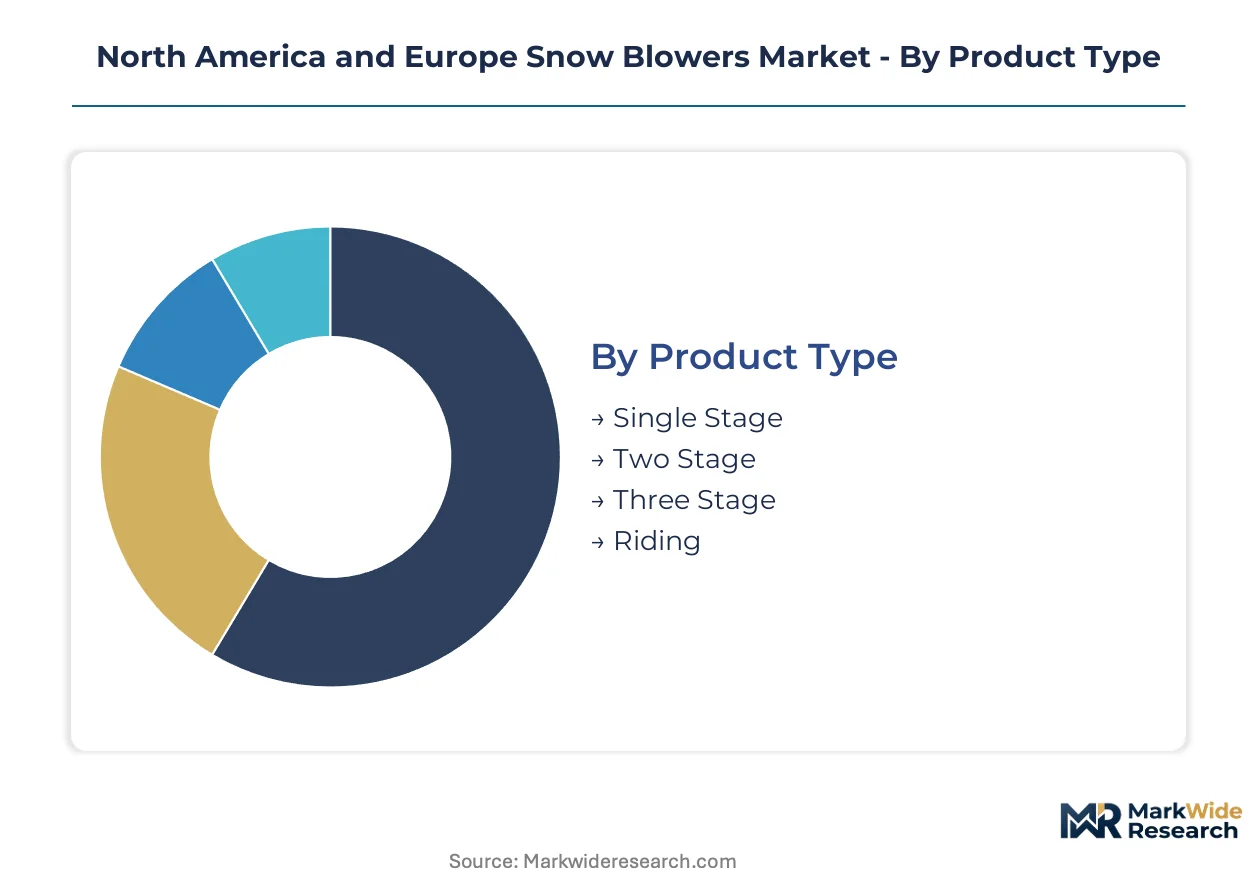
| Segmentation | Product Type: Single Stage, Two Stage, Three Stage, Riding End User: Residential, Commercial, Municipal, Contractors Power Source: Gas, Electric, Battery, Hybrid Capacity: Under 20 Inches, 20-24 Inches, 25-30 Inches, Over 30 Inches |
| Companies Covered | Honda Power Equipment, Deere & Company, Ariens, Briggs & Stratton, Snow Joe, Husqvarna AB, MTD Products, Stanley Black & Decker, Toro Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Snow Blowers Market Emerging Trajectories
Powertrain electrification is advancing faster than supporting infrastructure, creating a capability gap between battery hardware availability and the service networks, charging protocols, and technician training required to sustain fielded fleets.
Lithium iron phosphate (LiFePO4) battery packs with active thermal management are displacing nickel manganese cobalt chemistries in commercial snow blower applications. Municipal fleet operators in Germany and Minnesota prioritize these configurations for cold-weather reliability and reduced thermal runaway risk. The chemistry shift is compressing incumbent supplier relationships while opening procurement to automotive-tier cell manufacturers.
EPA Phase 3 small spark-ignition engine standards and the EU F-Gas Regulation are forcing parallel compliance investments that strain mid-tier engineering budgets. Gas-powered portfolio managers must redesign combustion chambers and aftertreatment while eliminating refrigerants in hydrostatic transmission cooling loops. Two-stage contractor units face the steepest cost escalation as they must satisfy both power density requirements and emissions ceilings.
Direct-to-contractor digital sales channels are fragmenting traditional dealer-distributor hierarchies in North American commercial segments. Independent landscaping operators in Michigan and Wisconsin now configure specifications online and arrange port-direct delivery, bypassing inventory-carrying dealerships. Equipment financiers are responding with digital credit decisioning tailored to seasonal cash flow patterns in snow-belt states.
North America and Europe Snow Blowers Market Segmentation
Snow blower procurement patterns diverge sharply across residential, commercial, and municipal channels, with each end-use imposing distinct performance thresholds, runtime requirements, and compliance burdens. Product positioning must align with these channel-specific demand profiles to capture replacement cycles and electrification incentives.
Product Type:
Dealer networks dominate two-stage and three-stage sales where installation complexity and service bundling justify margin premiums, while single-stage units flow increasingly through mass retail and direct-to-consumer channels.
- Single Stage:Auger-assisted discharge systems without impeller stages suit dry, powdery snow under 8 inches depth. Residential driveways in Minnesota and Ontario exhibit accelerating battery displacement here as grid reliability supports electric transition.
- Two Stage:Separate auger and impeller mechanisms throw wet, heavy snow beyond 40 feet. Municipal fleets across Wisconsin and Bavaria anchor replacement demand where EPA Phase 3 compliance deadlines compress upgrade timelines.
- Three Stage:Accelerator augers pre-crush ice and compacted snow for maximum throughput. Commercial campus operators in Michigan prioritize these units for parking lot clearing efficiency during lake-effect events.
- Riding:Tractor-mounted or zero-turn attachments serve rural estates and commercial campuses exceeding 5 acres. Attachment versatility with mid-mount mower decks expands value propositions in Pennsylvania and Ohio farm-country segments.
By volume, Two Stage leads. By growth pace, Battery-equipped Single Stage is climbing the fastest.
End User:
Cost tier stratification separates premium municipal procurement from price-sensitive residential replacement, with commercial contractors occupying a mid-tier where financing terms and uptime guarantees drive selection.
- Residential:Driveway clearing under 1,000 square feet dominates unit volume. Battery penetration concentrates in Germany, Minnesota, and Ontario where winter severity intersects with reliable electricity infrastructure and state-level buyback incentives.
- Commercial:Property management firms and retail chains demand 4-6 hour continuous runtime. Wet-snow physics and energy density limitations sustain gas dominance in this tier despite CARB zero-emission mandates in California and New York.
- Municipal:Fleet operators in the Upper Midwest and Nordic regions manage 8-hour shift requirements with redundant equipment. EPA Phase 3 and EU F-Gas Regulation compliance costs are accelerating hybrid qualification timelines for procurement pools.
- Contractors:Independent snow removal operators prioritize throwing distance and clearing width over emissions compliance. Digital sales channels in Michigan and Wisconsin now bypass traditional dealer hierarchies for specification-direct procurement.
Residential commands unit volume leadership. Municipal segments show steepest expansion trajectory as electrification mandates reshape fleet replacement schedules.
Power Source:
Application requirements dictate power source selection, with runtime physics and infrastructure availability creating hard boundaries between viable architectures.
- Gas:Small spark-ignition engines from 5 to 25 horsepower retain municipal and contractor dominance where continuous 8-hour operation is mandatory. EPA Phase 3 redesigns and aftertreatment additions are elevating cost structures for foundry-dependent manufacturers.
- Electric:Corded units remain niche for small residential applications with guaranteed outlet proximity. Grid-hardened zones in Bavaria and southern Ontario sustain limited demand despite mobility constraints.
- Battery:Lithium iron phosphate packs with active thermal management are displacing nickel manganese cobalt in commercial applications. Municipal operators in Germany and Minnesota prioritize these configurations for cold-weather reliability and reduced thermal runaway risk.
- Hybrid:Range-extender architectures bridge runtime anxiety with emissions compliance in the 25-30 inch capacity tier. Contractor upgrade cycles in Wisconsin and Michigan are opening as hybrid platforms qualify for fleet incentives.
Gas retains volume dominance. Battery configurations are gaining share fastest as cell chemistry advances and charging infrastructure hardens.
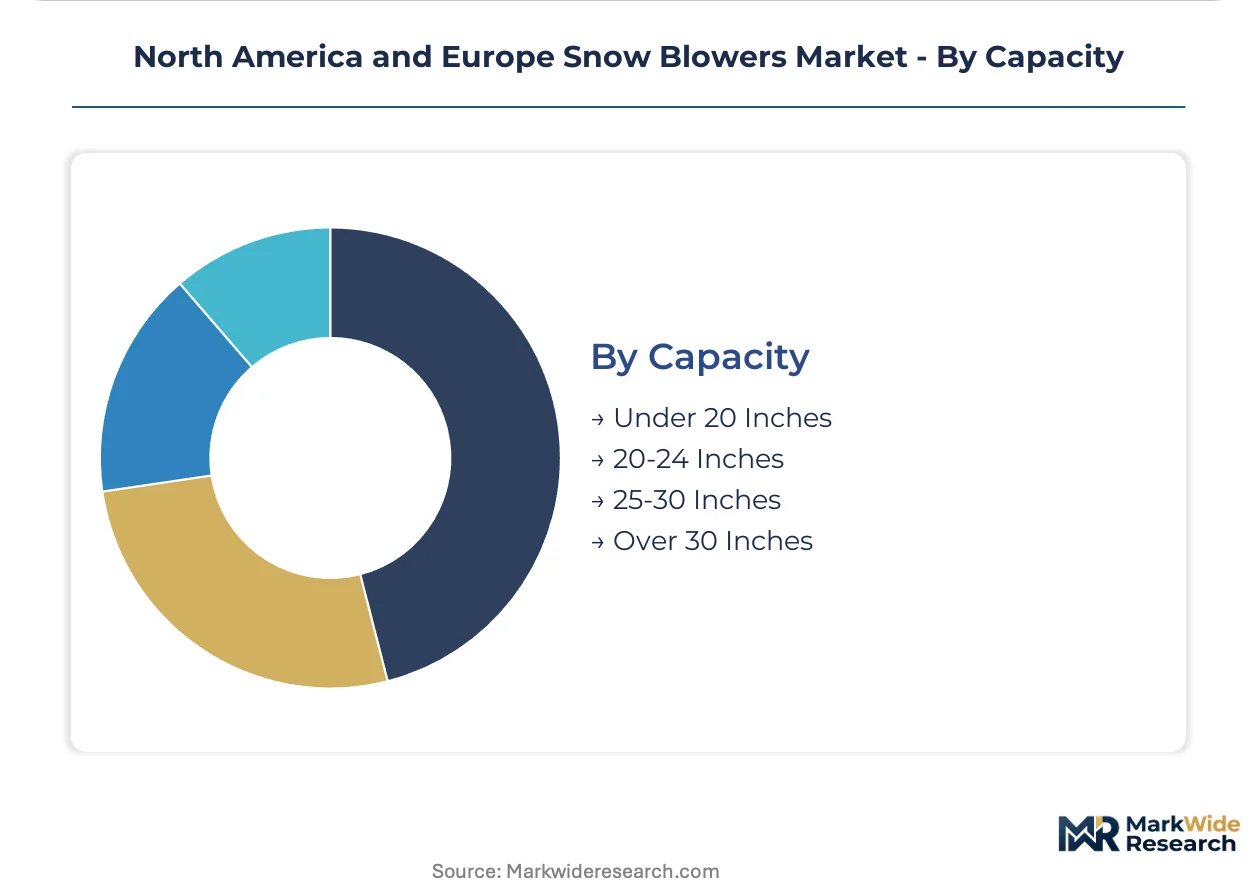
Capacity:
Clearing width directly correlates with capital intensity and replacement cycle length, with mid-tier capacities capturing technology transition investment.
- Under 20 Inches:Walk-behind units for urban driveways and narrow walkways. Battery displacement is most advanced here due to manageable power demands and shorter clearing durations.
- 20-24 Inches:Standard residential capacity tier where single-stage gas units face direct battery competition. Price-sensitive segments in Ohio and Pennsylvania drive volume.
- 25-30 Inches:Hybrid powertrain introduction is concentrating in this tier as manufacturers bridge contractor runtime requirements with emissions compliance. Municipal pilot programs in Minnesota and Bavaria target this capacity range for electrification trials.
- Over 30 Inches:Municipal and commercial fleet dominance with premium pricing attached to durability guarantees. Wet-snow performance requirements sustain gas and hybrid architectures despite regulatory pressure.
20-24 Inches leads by volume. 25-30 Inches shows the steepest expansion trajectory as hybrid platforms capture contractor upgrade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Upper Midwest manufacturing clusters where captive forging capacity and EPA Phase 3 engine redesigns elevate cost structures, while Scandinavian foundry dependencies create trans-Atlantic logistics exposure that compresses margins for asset-light assemblers.
United States
Municipal fleet operators in Minnesota and Wisconsin drive two-stage replacement cycles as EPA Phase 3 deadlines compress upgrade timelines. CARB zero-emission mandates in California and New York accelerate battery-electric qualification for procurement pools. Ariens anchors domestic fabrication in Wisconsin, insulating commercial lineups from overseas supply friction.
Germany
Bavarian grid-hardened zones exhibit elevated battery unit penetration where winter severity meets reliable electricity infrastructure. EU F-Gas Regulation compliance costs force refrigerant exclusions in hydrostatic transmission cooling loops. Municipal operators in Munich prioritize lithium iron phosphate configurations for cold-weather reliability.
Canada
Ontario residential segments show accelerating battery displacement in single-stage units under 1,000 square feet clearing requirements. Provincial buyback incentives align with federal emissions benchmarks for outdoor power equipment. Toronto-area contractors pilot hybrid platforms in the 25-30 inch capacity tier.
Sweden
Critical auger and impeller steel supply clusters in Swedish foundries create trans-Atlantic logistics exposure for North American OEMs. Nordic electrification rates exceed Eastern European benchmarks, tightening battery platform competition. Husqvarna AB anchors European distribution through Scandinavian retail networks.
Poland
Eastern European municipal fleets lag Nordic electrification rates, presenting first-mover positioning for battery platform suppliers. EU Ecodesign preparatory studies for outdoor power equipment shape anticipated 2027-2028 requirements. Warsaw-area procurement authorities evaluate hybrid qualification timelines against gas fleet replacement schedules.
North America and Europe Snow Blowers Market Vendor Landscape
Concentration sits with foundry-capable incumbents and asset-light assemblers competing across divergent capital-intensity models. Honda Power Equipment leverages captive engine manufacturing to control cost volatility through Midwest winters. Three archetypes define positioning: vertically integrated engine producers, domestic fabricators with forging capacity, and battery-platform specialists competing on interoperability. Dominant competitive moves include EPA Phase 3 compliance redesigns and hybrid powertrain introductions in the 25-30 inch tier.
Among engine-integrated manufacturers, Honda Power Equipment exemplifies captive supply chain control, while Ariens occupies a position within the domestic fabrication tier. Husqvarna AB represents the European battery-platform specialist archetype, competing through Scandinavian distribution density and cross-category power tool interoperability.
| Leading Market Players |
|---|
| Honda Power Equipment |
| Deere & Company |
| Ariens |
| Briggs & Stratton |
| Snow Joe |
| Husqvarna AB |
| MTD Products |
| Stanley Black & Decker |
| Toro Company |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Swedish and Finnish foundries lock in auger and impeller steel access while fixing cost visibility for North American OEMs facing EPA Phase 3 redesign timelines. These arrangements insulate vertically integrated manufacturers from spot volatility in specialty alloy markets while compressing margin flexibility for asset-light assemblers dependent on spot procurement.
Pricing Analysis
Configured-to-order pricing for municipal fleet contracts commands substantial premiums over standard residential SKUs. Three-tier pricing structure across premium, standard, and economy levels separates CARB-compliant battery platforms from EPA Phase 3 gas redesigns and legacy inventory clearances. Pricing pressure stems from lithium-ion cell cost volatility and cathode material swings, with residential segments exhibiting highest price sensitivity and municipal procurement pools showing lowest due to total-cost-of-ownership framing.
Supply Chain Analysis
Inventory buffers for critical auger castings now stretch across two winter seasons as lead times from Scandinavian foundries extend. Supply concentrates in Sweden, Finland, and Wisconsin for forged steel components, while lithium iron phosphate cells draw from automotive-tier manufacturers in South Korea and China. Single-source vulnerability sits with Swedish specialty steel suppliers for high-wear impeller alloys. Distribution runs through dealer networks for commercial tiers and mass retail for residential single-stage units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery powertrain disruption accelerates as EPA Phase 3 and EU F-Gas Regulation compress gas-powered redesign windows, forcing simultaneous compliance investments across incompatible architectures.
For Market Incumbents: Fortify captive forging capacity in Wisconsin and Upper Midwest clusters to insulate two-stage lineups from trans-Atlantic logistics friction. Deepen backward integration into lithium iron phosphate pack assembly to capture cell chemistry transitions and reduce supplier concentration risk. Prioritize hybrid qualification timelines in the 25-30 inch tier where contractor upgrade cycles concentrate. For New Entrants and Emerging Players: Aftermarket battery retrofit services for legacy gas fleets represent an underserved layer where incumbent OEMs under-invest. Eastern European municipal fleets in Poland and Czech Republic offer penetrable procurement pools with lagging electrification rates. Pursue direct digital sales channels to bypass established dealer hierarchies in Michigan and Wisconsin contractor segments. For Investors and Strategic Acquirers: Capital is best deployed toward foundry-capable mid-tier manufacturers with EPA Phase 3 redesign momentum and battery platform interoperability. Five-to-ten year viability hinges on dual-certification capability across US and EU regulatory regimes. Watch for EU Ecodesign preparatory study publications as inflection signals for architecture lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Introduction | Bridges contractor runtime requirements with CARB zero-emission mandates in California and New York procurement pools. |
| LiFePO4 Battery Platform Migration | Captures municipal cold-weather reliability demand in Minnesota and Bavaria while reducing thermal runaway risk. |
| Direct-to-Contractor Digital Channel | Bypasses inventory-carrying dealerships in Michigan and Wisconsin where independent operators seek specification-direct procurement. |
| Scandinavian Foundry Capacity Reservation | Locks in auger and impeller steel supply continuity through Midwest winters despite trans-Atlantic logistics exposure. |
| Attachment Ecosystem Expansion | Extends riding snow blower value propositions in Pennsylvania and Ohio through mid-mount mower deck compatibility. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA certification databases, EU F-Gas Regulation filings, and municipal procurement records. Primary interviews engaged fleet managers at Upper Midwest and Nordic municipal authorities, commercial contractors in Michigan and Wisconsin, and aftermarket service heads at dealer networks. Secondary validation drew from customs trade data, foundry production disclosures, and battery supply chain filings. Bottom-up unit shipment analysis triangulates against top-down equipment replacement cycle modeling.
Segmentation dimensions modeled include product type, end user channel, power source architecture, and clearing width capacity tier across the analysis window. CAGRs derive from replacement cycle compression, electrification incentive trajectories, and powertrain mix shift assumptions. Industry-specific forecast inputs incorporate EPA Phase 3 compliance deadlines and EU Ecodesign preparatory study timelines.
Forecasts assume regulatory continuity in EPA Phase 3 and EU F-Gas regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Spray Washer Market