
 Asia-Pacific Completion Equipment Market | 2026-2036
Asia-Pacific Completion Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Completion Equipment Market Outlook
The gap between premium intelligent completions and commodity land-based equipment is broadening across the Asia-Pacific basin. Schlumberger Ltd anchors high-margin subsea portfolios through proprietary electric actuation systems. Halliburton Company leverages integrated well-construction platforms to compete in Australia's LNG-driven offshore sector. Baker Hughes Company differentiates through permanent monitoring hardware that sustains pricing power in mature fields.
Completion equipment encompasses the mechanical assemblies, control systems, and pressure-containing devices installed after drilling to enable hydrocarbon flow from reservoir to surface, typically rated for pressures exceeding 10,000 psi and temperatures above 150°C in deepwater applications. Its primary purpose is to optimize production rates while maintaining well integrity across variable reservoir conditions. Packers and sand control equipment command the largest share of product-type revenue, reflecting heavy deployment in unconsolidated sandstone formations across Southeast Asian basins. Electronic control systems represent the fastest-expanding technology segment, as operators prioritize real-time reservoir management over conventional hydraulic actuation.
China's MIIT enforces GB standards for subsea equipment certification, while Australia's NOPSEMA mandates well-integrity management systems for offshore installations. These frameworks elevate compliance costs for imported systems but create preferential access for suppliers with in-country testing facilities. Stakeholders must weigh localization requirements against scale economies when configuring regional supply networks.
Market Dynamics
Deepwater operators across Southeast Asian basins are accelerating adoption of electric actuation systems, forcing suppliers to reconfigure product portfolios around real-time reservoir management capabilities rather than conventional hydraulic architectures.
Growth Catalysts
- China's dual carbon goals:MIIT-mandated efficiency standards for subsea equipment are pulling intelligent completion systems into Bohai Bay developments, rewarding suppliers with certified low-carbon manufacturing processes.
- Electronic control systems:Downhole monitoring arrays with fiber-optic telemetry are replacing hydraulic control lines in Australia's Northwest Shelf, enabling multi-zone production optimization without well intervention.
- India's Krishna-Godavari Basin:Reliance Industries and ONGC are commissioning high-pressure high-temperature completions for ultra-deepwater gas fields, creating concentrated demand for premium metallurgy and sealing technologies.
Market Restraints
- Specialized alloy supply concentration:Super duplex stainless steel and Inconel 718 forgings for subsea wellheads concentrate among Japanese and South Korean metallurgical suppliers, exposing procurement to capacity constraints.
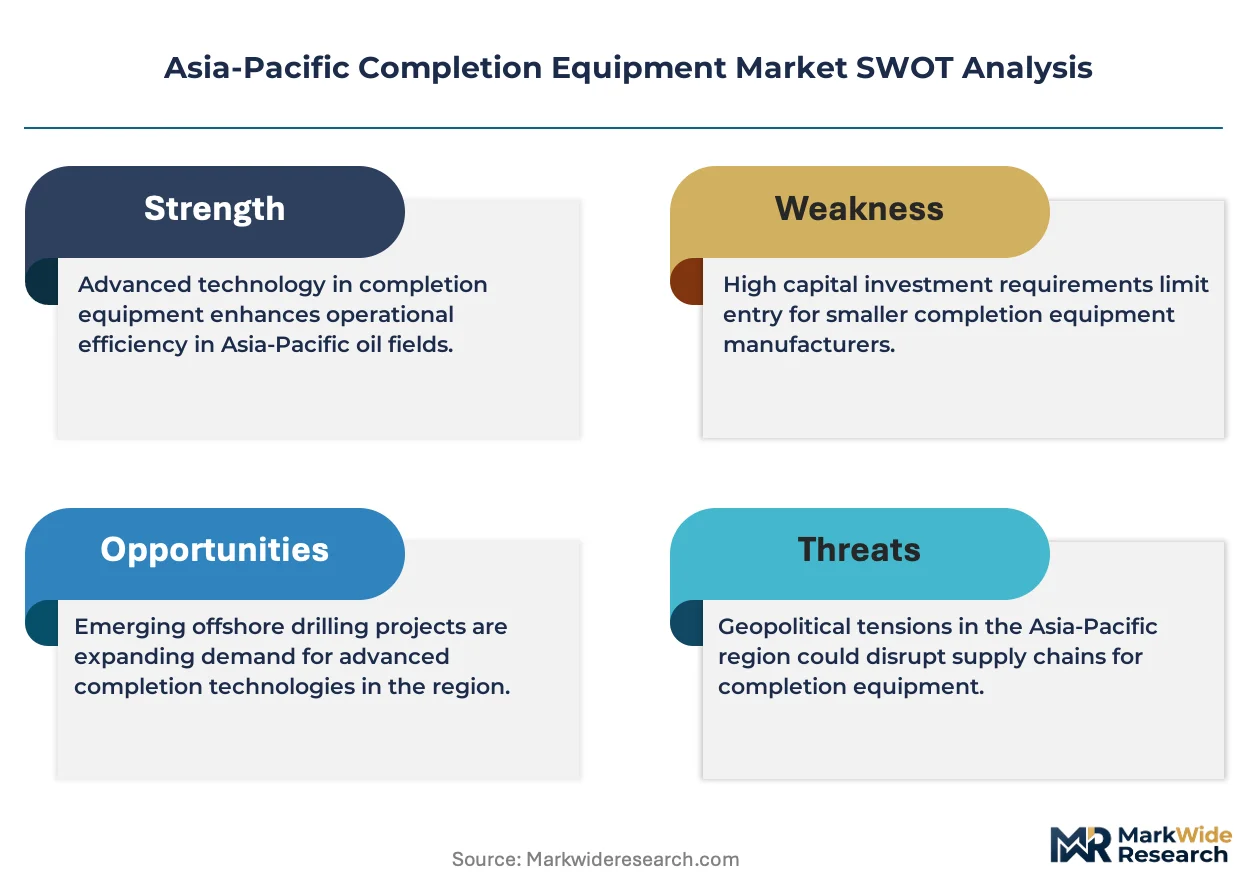
- NOPSEMA well-integrity mandates:Australia's offshore regulator requires continuous barrier verification and documented maintenance intervals, elevating lifecycle compliance costs above comparable Southeast Asian jurisdictions.
- Extended project sanctioning cycles:Final investment decisions for Australian LNG developments now average 18-24 months longer than pre-2020 baselines, compressing equipment order visibility.
Strategic Opportunities
- Vietnam's Ca Voi Xanh development:ExxonMobil's pending sanction of this 10 Tcf gas field will require subsea production systems with integrated sand control and artificial lift, opening a new equipment demand center.
- Retrofit of mature Australian fields:Brownfield installations on the Northwest Shelf are upgrading to permanent downhole gauges and remotely operated sliding sleeves, creating aftermarket revenue streams independent of drilling activity.
- Japan's METI hydrogen roadmap:Pilot projects for offshore blue hydrogen production are testing adapted completion hardware for CO2 injection and hydrogen extraction, positioning early movers for technology transfer.
Industry Challenges
- Subsea systems engineering talent:Specialized expertise in multiphase flow modeling and subsea controls architecture remains concentrated among a narrow cohort of engineers in Perth and Singapore, constraining execution capacity.
- GB standard certification timelines:China's MIIT requires in-country pressure testing and third-party verification for subsea Christmas trees, extending product qualification cycles by 8-12 months versus international equivalents.
- Integration with legacy hydraulic infrastructure:Hybrid architectures combining new electric actuation with existing hydraulic umbilicals introduce interface complexity and failure-mode uncertainties during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Completion Equipment Market |
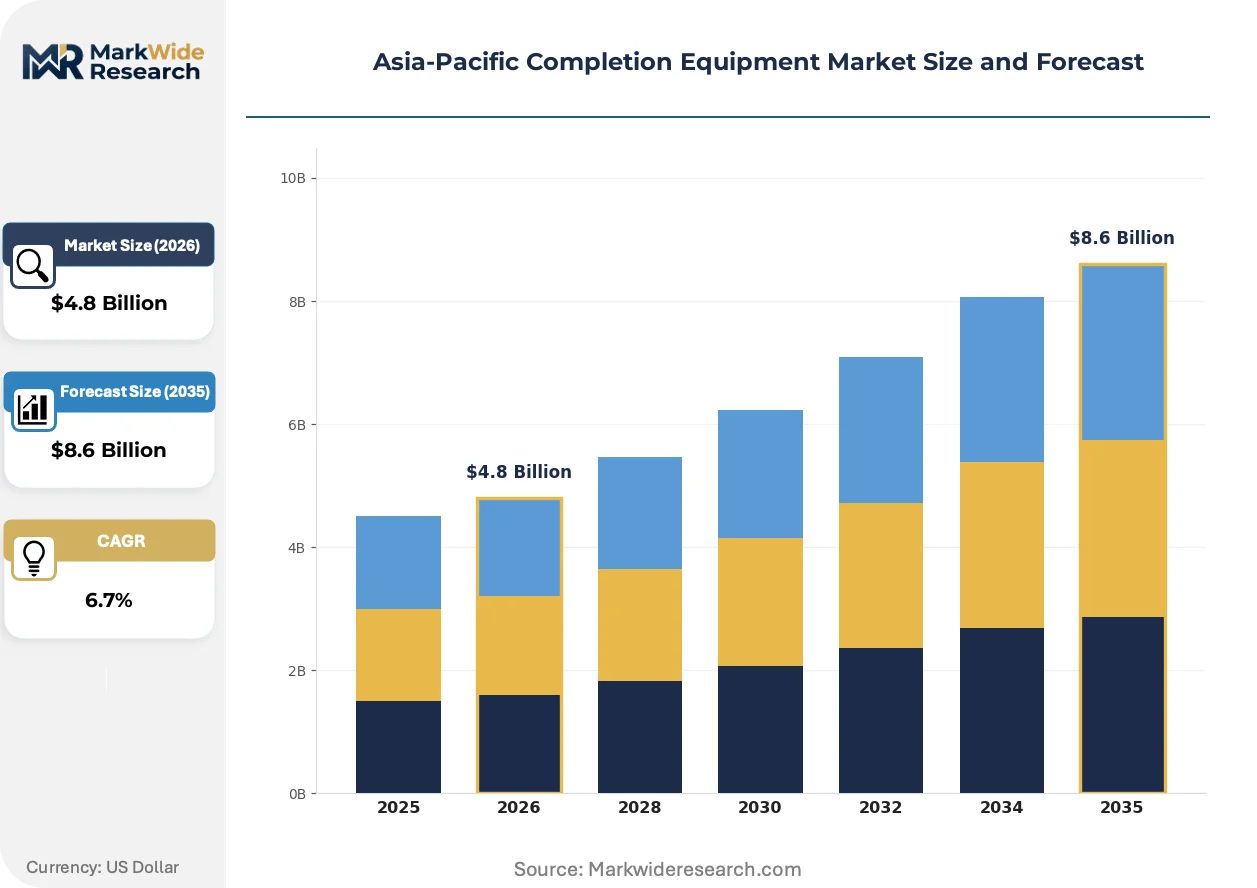
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packers, Sand Control Equipment, Wellhead Equipment, Pipe Systems Technology: Hydraulic Completion, Membrane Technology, Slickline Technology, Electronic Control Systems End User: Oil Producers, Natural Gas Producers, Offshore Operators, Onshore Operators Installation: Subsea Installation, Land Installation, Platform Installation, Surface Installation |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International plc, China Oilfield Services Ltd, National Oilwell Varco, NOV, Forum Energy Technologies, Nine Energy Service, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Completion Equipment Market Strategic Shifts
Digitalization of downhole operations is collapsing the distinction between completion hardware and reservoir surveillance platforms, with operators now specifying integrated systems rather than discrete mechanical components.
All-electric intelligent completion systems are converging with permanent fiber-optic distributed temperature and acoustic sensing. Offshore operators in Australia's Ichthys and Prelude fields are deploying these integrated packages to eliminate hydraulic control lines and enable real-time zonal isolation decisions. This convergence is compressing the addressable market for conventional hydraulic packers and sliding sleeves in deepwater applications.
NOPSEMA's updated offshore facility safety case requirements mandate documented barrier management systems with independent verification of well integrity throughout field life. Australian operators must now demonstrate continuous monitoring capabilities and predictive maintenance protocols for subsea production systems. The regulation most affects mature field operators retrofitting legacy completions, who are accelerating procurement of permanent monitoring hardware to satisfy audit requirements.
Integrated service contracting is displacing discrete equipment purchasing for major offshore developments. Operators in China's Bohai Bay and Australia's Scarborough project are awarding single-source contracts encompassing well construction, completion design, and subsea production system installation. This consolidation most visibly affects procurement departments at CNOOC and Woodside, who are reducing qualified vendor lists and prioritizing suppliers with integrated platform capabilities over specialized equipment manufacturers.
Asia-Pacific Completion Equipment Market Segmentation
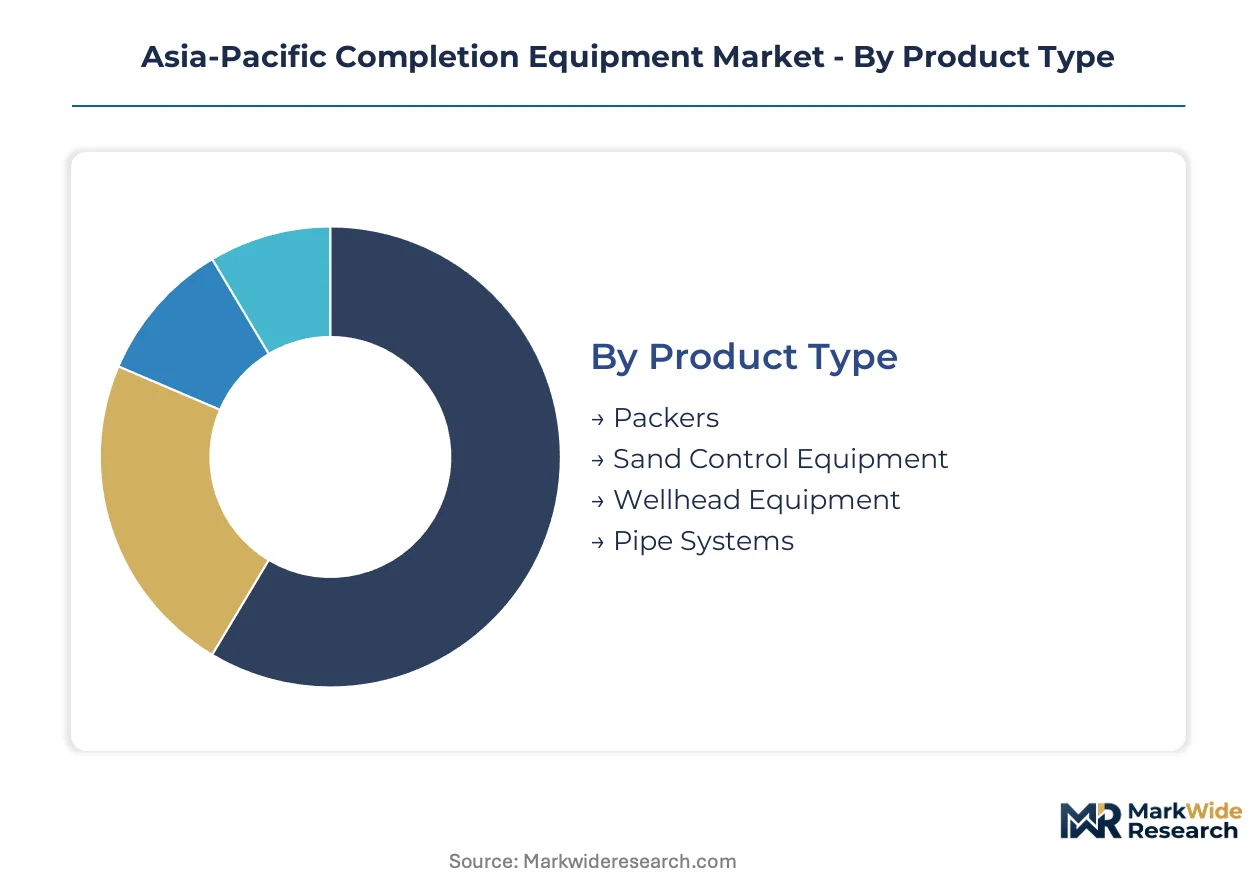
Completion equipment procurement in the Asia-Pacific basin follows distinct technical and commercial logics. Operators segment purchasing decisions by reservoir characteristics, regulatory environment, and integration complexity rather than unit cost alone.
Product Type:
Buyers prioritize pressure containment reliability and sand management effectiveness when selecting mechanical assemblies.
- Packers:These annular sealing devices isolate production zones and withstand differential pressures exceeding 10,000 psi in deepwater applications. Demand concentrates in Australia's Northwest Shelf, where Ichthys and Prelude operators require multi-set packers for zonal isolation in high-pressure gas wells.
- Sand Control Equipment:Screens, gravel packs, and frac packs prevent formation sand migration into wellbores. Operators in Southeast Asian basins with unconsolidated sandstone formations deploy these systems most intensively, with Vietnam's Ca Voi Xanh development specifying integrated sand control for its subsea production systems.
- Wellhead Equipment:Casing heads, tubing heads, and Christmas trees provide pressure control at the surface or seabed.
- Pipe Systems:Production tubing, casing, and liners form the conduit from reservoir to surface facilities.
Packers lead on scale; Sand Control Equipment leads on momentum.
Technology:
Technology selection reflects the trade-off between proven hydraulic architectures and emerging electric capabilities.
- Hydraulic Completion:Conventional systems using pressurized control lines dominate installed base across mature Asia-Pacific fields. Australia's Northwest Shelf retains extensive hydraulic infrastructure, though brownfield retrofits face integration complexity when adding electric monitoring layers.
- Electronic Control Systems:Downhole sensors with fiber-optic telemetry enable real-time reservoir management without well intervention. China's MIIT efficiency standards are pulling these systems into Bohai Bay developments, rewarding suppliers with certified low-carbon manufacturing processes.
- Membrane Technology:Advanced filtration systems separate multiphase flows at the completion level.
- Slickline Technology:Wireline-based intervention methods maintain and adjust completions without full workover rigs.
Hydraulic Completion retains the largest installed base; Electronic Control Systems are gaining share fastest.
End User:
Customer type determines specification stringency and procurement cycle length.
- Offshore Operators:Deepwater developers in Australia's Northwest Shelf and India's Krishna-Godavari Basin require premium metallurgy and sealing technologies. Reliance Industries and ONGC commission high-pressure high-temperature completions for ultra-deepwater gas fields, creating concentrated demand for specialized alloys.
- Oil Producers:Onshore and offshore crude-focused operators prioritize artificial lift integration and water shutoff capabilities.
- Natural Gas Producers:Gas-focused developments emphasize hydrate management and high-rate flow assurance.
- Onshore Operators:Land-based developers in China and India face different cost structures and regulatory requirements than their offshore counterparts.
Offshore Operators command the highest specification tier; Oil Producers represent the broadest volume base.
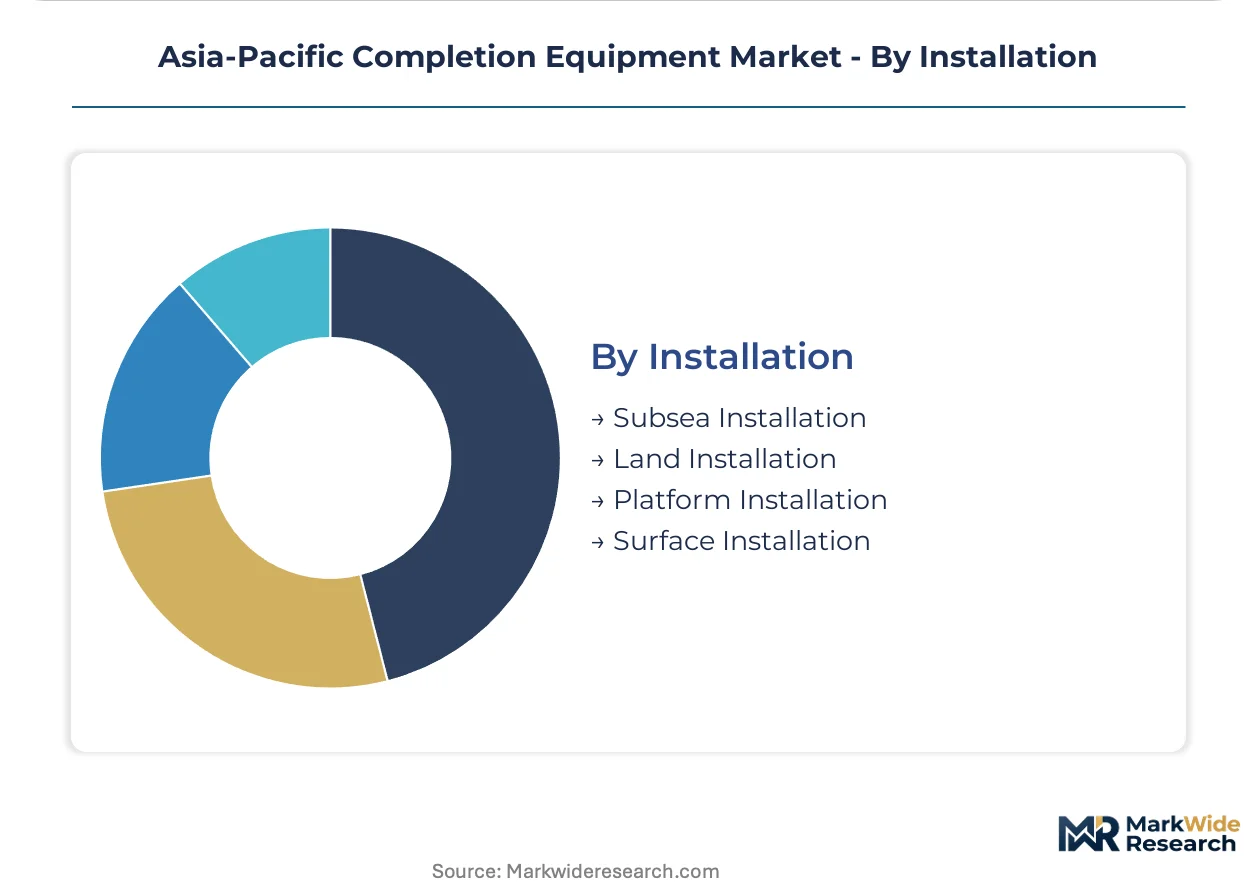
Installation:
Installation environment dictates pressure rating, corrosion allowance, and maintenance access design.
- Subsea Installation:Seabed-mounted wellheads and production trees operate without surface platform support. Australia's NOPSEMA mandates continuous barrier verification and documented maintenance intervals for these systems, elevating lifecycle compliance costs above comparable Southeast Asian jurisdictions.
- Platform Installation:Fixed-structure completions integrate with offshore production facilities.
- Land Installation:Surface wellheads and onshore completion assemblies face simpler logistics but variable terrain challenges.
- Surface Installation:Coastal and near-shore configurations blend subsea and land design elements.
Subsea Installation leads on engineering complexity; Platform Installation leads on near-term project visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized subsea systems engineers cluster in Perth and Singapore, anchoring execution capacity for deepwater developments across Southeast Asian basins. This talent concentration shapes procurement patterns and vendor qualification timelines throughout the region.
Australia
Northwest Shelf LNG operators drive premium completion demand through Ichthys and Prelude field developments. NOPSEMA mandates continuous barrier verification and predictive maintenance protocols for subsea production systems. Brownfield retrofits in the Carnarvon Basin accelerate procurement of permanent downhole monitoring hardware to satisfy audit requirements.
China
CNOOC commissions intelligent completion systems for Bohai Bay ultra-deepwater gas fields under MIIT-mandated efficiency standards. GB certification requirements for subsea Christmas trees extend product qualification cycles by 8-12 months versus international equivalents. Manufacturing clusters in Tianjin and Shenzhen prioritize suppliers with certified low-carbon production processes.
India
Reliance Industries and ONGC anchor demand for high-pressure high-temperature completions in the Krishna-Godavari Basin. The country's national petroleum regulator enforces well-integrity documentation for ultra-deepwater gas developments. Fabrication yards in Visakhapatnam concentrate procurement of specialized metallurgy for premium wellhead assemblies.
Vietnam
ExxonMobil's pending sanction of the Ca Voi Xanh gas field creates concentrated demand for integrated sand control and artificial lift systems. The country's national energy regulator applies offshore facility safety standards adapted from regional benchmarks. Equipment specification work concentrates in Ho Chi Minh City engineering offices ahead of final investment decisions.
Japan
METI's hydrogen roadmap pilots adapted completion hardware for offshore CO2 injection and hydrogen extraction applications. JIS standards govern pressure-containing equipment certification for domestic suppliers. Yokohama-based engineering groups test technology transfer protocols for early-mover positioning in blue hydrogen infrastructure.
Asia-Pacific Completion Equipment Market Competitive Environment
Top-tier vendors anchor premium subsea portfolios, while mid-tier fabricators compete on localization compliance and aftermarket service density. The market structures around three distinct competitive tiers: integrated service contractors commanding single-source awards, specialized equipment manufacturers defending niche metallurgy positions, and national oilfield services companies leveraging domestic certification advantages. Consolidation pressures favor vendors with in-country testing facilities capable of satisfying MIIT and NOPSEMA requirements simultaneously. Strategic moves concentrate on portfolio diversification into permanent monitoring hardware and backward integration into specialized alloy supply chains.
Within the integrated service tier, Schlumberger Ltd, Halliburton Company, and Baker Hughes Company occupy positions exemplifying the shift toward real-time reservoir management platforms. Schlumberger anchors high-margin electric actuation capabilities through proprietary subsea control architectures. Halliburton exemplifies integrated well-construction contracting models now prevailing in Australian LNG developments. Baker Hughes represents the permanent monitoring hardware specialization sustaining pricing power in mature field retrofits. These three entities collectively illustrate how vendor consolidation around intelligent completion systems is displacing discrete equipment procurement patterns across the region.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| China Oilfield Services Ltd |
| National Oilwell Varco |
| NOV |
| Forum Energy Technologies |
| Nine Energy Service |
| Others |
Value Chain & Pricing Dynamics
Electric actuation technology migration simultaneously compresses hydraulic component margins and concentrates procurement leverage among suppliers with certified subsea control architectures. This dual shift elevates cost structures for conventional packer systems while rewarding integrated service contractors capable of bundling real-time reservoir management capabilities.
Pricing Analysis
Bundled single-source contracts for well construction and completion design now command premium positioning over discrete equipment purchasing. Three-tier pricing structure across premium intelligent completions, standard hydraulic systems, and economy land-based equipment reflects certification grade differentiation and after-sales service density. Cost compression in commodity packer segments is intensifying because Australia's NOPSEMA mandates elevate compliance documentation requirements. National oilfield services companies exhibit highest price sensitivity due to localization requirements, while integrated operators in Australia's Northwest Shelf prioritize performance guarantees over unit cost.
Supply Chain Analysis
Super duplex stainless steel and Inconel 718 forgings for subsea wellheads rest on Japanese and South Korean metallurgical suppliers, with secondary sourcing from German specialty steel producers. Raw material dependencies center on nickel-based superalloys, high-pressure sealing elastomers, and fiber-optic telemetry components. Single-source vulnerability concentrates in forged subsea connectors where capacity constraints limit alternative qualification. Distribution runs through Singapore warehousing hubs serving Australian offshore developments and Tianjin manufacturing clusters supplying China's Bohai Bay operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as operators prioritize intelligent completion specifications over conventional hydraulic architectures. The shift toward real-time reservoir management platforms favors suppliers with integrated electric actuation capabilities and in-country certification facilities.
For Market Incumbents: Acquire permanent downhole monitoring hardware specialists to anchor aftermarket revenue streams in Australia's mature Northwest Shelf fields. Consolidate backward integration into specialized alloy supply chains to mitigate Japanese and South Korean forging capacity constraints. Defend against emerging integrated service contractors by accelerating GB standard certification timelines for subsea Christmas trees in China. For New Entrants and Emerging Players: The price-point gap between premium intelligent completions and economy land-based equipment creates entry space for mid-tier suppliers with localized manufacturing capabilities. Target Vietnam's Ca Voi Xanh development ahead of final investment decisions, where integrated sand control and artificial lift specifications remain unsettled. Establish Ho Chi Minh City engineering presence to capture specification influence before procurement finalization. For Investors and Strategic Acquirers: Valuations sit cheapest among national oilfield services companies with dormant GB certification capabilities and underutilized Tianjin fabrication assets. Five-to-ten year viability hinges on successful technology transfer from hydraulic to electric architectures. Watch Japan's METI hydrogen roadmap pilot projects as inflection indicator for adapted completion hardware demand in CO2 injection applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Mitigates Japanese forging capacity constraints affecting subsea wellhead procurement timelines. |
| GB Standard Certification Investment | Unlocks preferential access to CNOOC's Bohai Bay intelligent completion procurement under MIIT mandates. |
| Permanent Monitoring Hardware Acquisition | Captures brownfield retrofit demand from Australia's NOPSEMA-mandated barrier verification requirements. |
| Singapore Engineering Talent Cluster Expansion | Addresses concentrated expertise scarcity in multiphase flow modeling across Southeast Asian basins. |
| Vietnam Market Entry Positioning | Secures specification influence ahead of ExxonMobil's Ca Voi Xanh subsea production system procurement. |
Study Parameters
Direct dialogue with subsea systems engineers, procurement directors at national oil companies, NOPSEMA compliance officers, and metallurgical forging specialists grounded qualitative findings. Secondary validation drew from MIIT equipment certification databases, Australian offshore facility safety case filings, SEC 10-K disclosures from integrated service contractors, and customs records for super duplex stainless steel imports. Bottom-up project sanctioning timelines and top-down regional expenditure forecasts were triangulated to anchor volume estimates.
Bottom-up modeling segmented demand across packers, sand control equipment, wellhead assemblies, and electronic control systems, further disaggregated by hydraulic versus electric technology architectures and subsea versus platform installation environments. CAGRs were derived from project visibility pipelines in Australia's Northwest Shelf, China's Bohai Bay, and India's Krishna-Godavari Basin, cross-referenced against operator capital guidance and regulatory sanctioning velocity.
Caveats apply where extended Australian LNG project sanctioning cycles or Chinese GB certification timeline extensions could materially shift equipment order visibility. Forecasts reflect assumptions regarding Reliance Industries and ONGC ultra-deepwater gas field development pacing. A small set of named triggers warrants ongoing watch: Vietnam's Ca Voi Xanh final investment decision, Japan's METI hydrogen pilot project conversion rates, and NOPSEMA audit enforcement intensity for mature field operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Mini Excavators Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Metal Rollforming System Market