
 Snow Clearing Vehicles Market | 2026-2036
Snow Clearing Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Clearing Vehicles Market Analytics
Electrification of heavy-duty powertrains is narrowing the performance gap between diesel and battery-electric snow clearing platforms for urban and airport deployments. Oshkosh Corporation leverages its defense-derived all-wheel-drive architecture to sustain technical credibility in severe-duty segments. PRINOTH AG anchors its position through specialized mountain and grooming applications where slope-grade capability commands premium positioning.
Snow clearing vehicles are purpose-built machines engineered with blade widths spanning 2.5 to 7.5 meters, operating weights from 3,500 kg to over 30,000 kg, and power outputs calibrated for continuous low-speed traction in sub-zero conditions; their primary function is restoring safe surface transit across roadways, runways, and pedestrian corridors following snowfall or ice events. Municipal application fleets represent the deepest installed base, though electric and hybrid technology segments attract disproportionate capital allocation as total cost of ownership equations shift. Mechanical systems still dominate volume shipments, but hydraulic precision controls command stronger margin pools in commercial and infrastructure contracts where damage liability thresholds are highest.
EPA Tier 4 Final and Euro Stage V emissions frameworks have elevated engine certification costs, while EU Green Deal implementation timelines and FAA airport surface equipment directives are redirecting procurement specifications toward lower-carbon alternatives. NHTSA vehicle classification rules and OSHA winter workplace safety standards further constrain equipment design parameters for contractor-operated fleets. Stakeholders must weigh powertrain transition capital requirements against regulatory compliance deadlines and residual value risk in secondary markets.
Market Dynamics
Electric powertrain maturation is compressing the total cost of ownership differential against diesel platforms, forcing incumbent manufacturers to reconfigure R&D allocation and supplier relationships across municipal and airport procurement channels.
Growth Catalysts
- EU Green Deal decarbonization mandates:Airport authorities in Norway, Sweden, and Finland face binding emission reduction timelines that accelerate fleet replacement cycles for ground support equipment.
- Avinor infrastructure investment:Norway's state-owned airport operator maintains sustained capital deployment for winter preparedness, creating predictable demand visibility for severe-duty platform suppliers.
- Battery thermal management advances:Solid-state heating systems now sustain operational performance in sub-zero conditions previously exclusive to combustion engines.
Market Restraints
- Lithium supply concentration:Cathode material processing dependency on Chinese refining infrastructure exposes battery pack cost volatility for European and North American OEMs.
- EPA Tier 4 Final certification costs:Small-volume diesel engine suppliers face disproportionate compliance burden, consolidating powertrain sourcing options for mid-tier equipment builders.
- Runway friction measurement substitution:Fixed sensor networks reduce reliance on mobile friction testing vehicles in major hub airports.
Strategic Opportunities
- Polish municipal fleet modernization:EU cohesion fund access enables accelerated replacement of Soviet-era equipment in secondary cities with limited historical electrification.
- Swiss alpine grooming convergence:Slope maintenance contracts increasingly specify combined snow clearing and terrain preparation capability, opening integrated platform demand.
- OSHA winter workplace safety standard expansion:Private contractor liability thresholds are tightening across US commercial property management, expanding insured equipment requirements.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack certified personnel for battery-electric powertrain diagnostics and repair.
- FAA airport surface equipment directive compliance timelines:Certification documentation requirements for electric GSE are extending procurement cycles beyond traditional equipment replacement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Clearing Vehicles Market |
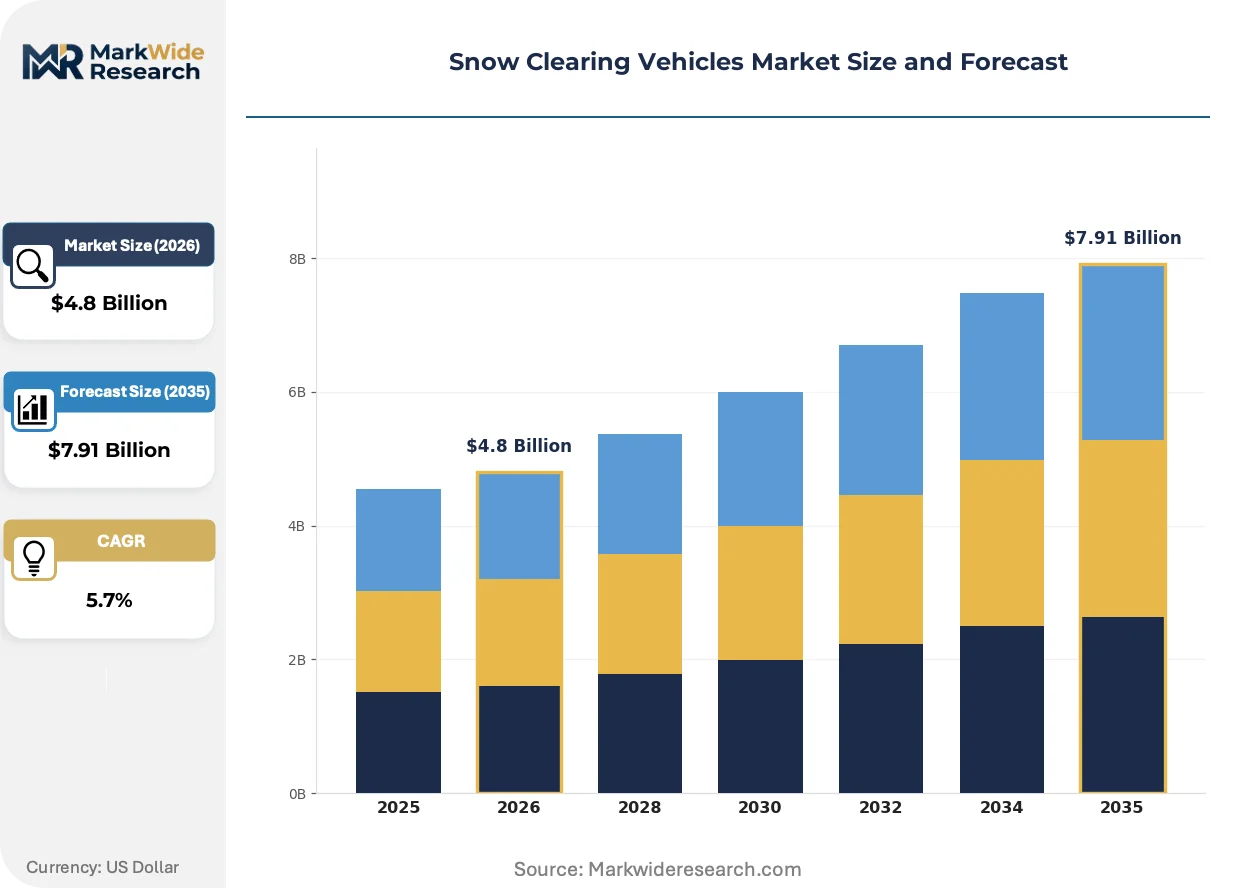
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plows, Spreaders, Snow Blowers, Ice Resolvers Application: Municipal, Residential, Commercial, Infrastructure Technology: Mechanical, Hydraulic, Electric, Hybrid End User: Government Agencies, Contractors, Homeowners, Maintenance Providers |
| Companies Covered | Alamo Group Inc., Oshkosh Corporation, M-B Companies, Inc., Team Eagle Ltd., Kodiak America, Marcel Boschung AG, PRINOTH AG, Bobcat Company, Wausau Equipment Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Clearing Vehicles Market Evolving Landscape
Autonomous blade positioning and predictive surface condition monitoring are converging to reduce operator skill requirements while improving clearing consistency across variable terrain and pavement types.
Autonomous blade control systems utilizing LiDAR terrain mapping and real-time friction sensing are rendering obsolete manual operator adjustment protocols for variable-depth snow removal. Municipal fleets in Edmonton and Calgary are piloting retrofitted platforms with compressed deployment timelines. The technology is compressing training requirements and expanding the addressable labor pool for seasonal hiring.
EPA emissions enforcement is tightening defect reporting obligations for imported diesel engines used in commercial snow clearing equipment. Non-compliant powertrain shipments face expanded detention authority at US ports. Airport contractors operating under FAA grant assurances are prioritizing pre-certified electric alternatives to avoid procurement delays.
Swiss and Austrian alpine municipalities are consolidating equipment purchasing through inter-municipal cooperative frameworks that standardize specifications across contiguous territories. Traditional dealer networks are losing specification-setting influence to procurement consortia. This concentration is most visible in Graubünden and Vorarlberg regional tendering.
Snow Clearing Vehicles Market Segmentation
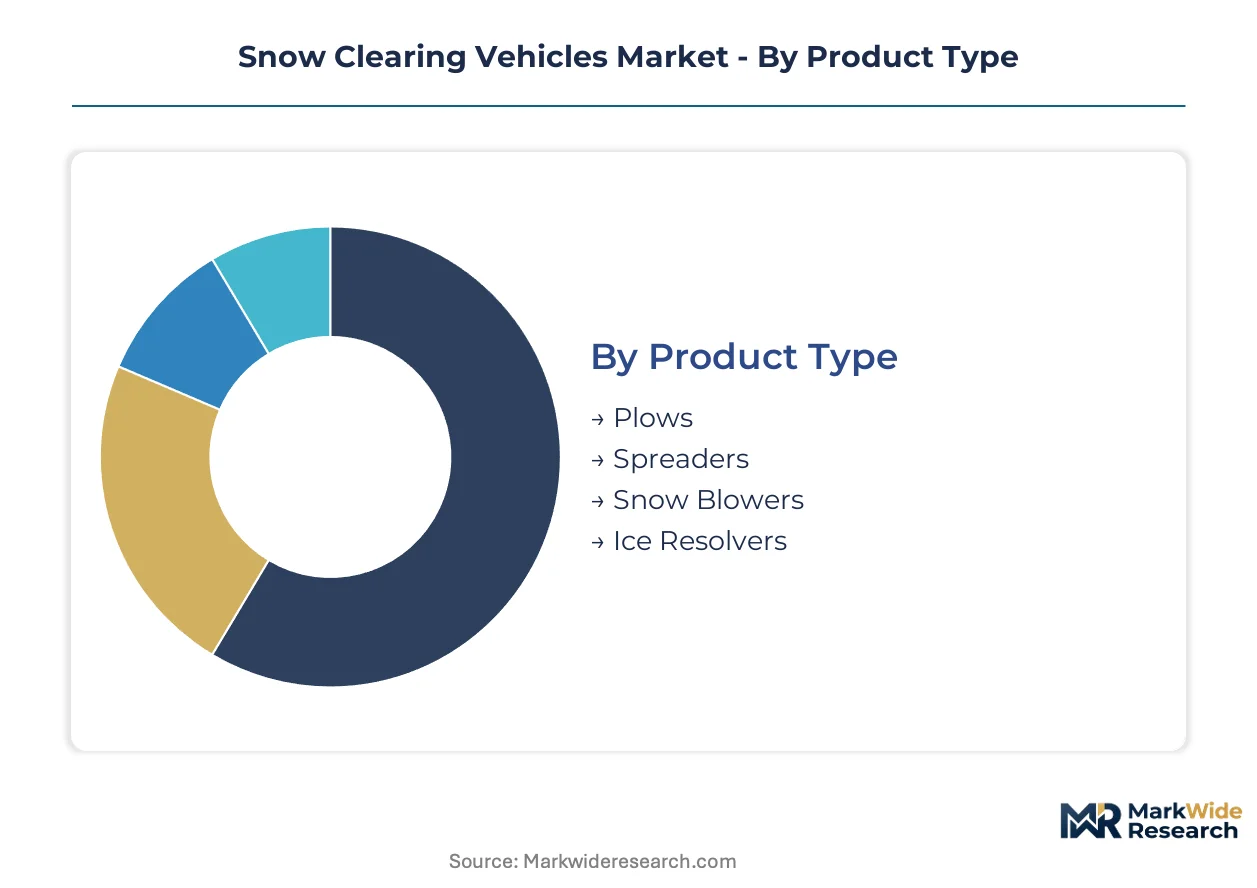
Snow clearing vehicles serve divergent duty cycles across product categories, from seasonal municipal deployments to continuous airport operations. Understanding replacement velocity and specification intensity by segment reveals where procurement budgets concentrate and where technology transitions face friction.
Product Type:
Plows and spreaders turn over fastest in municipal fleets, while snow blowers and ice resolvers cycle slower due to lower utilization hours and specialized deployment patterns.
- Plows:Front-mounted and underbody configurations with blade widths from 2.5 to 7.5 meters dominate high-frequency clearing operations. Norwegian municipal authorities in Oslo and Bergen drive specification intensity here, where EU Green Deal timelines accelerate electric retrofit programs ahead of diesel phase-out deadlines.
- Spreaders:Hopper-mounted salt and brine distribution systems integrate liquid pre-wetting and solid material metering. Demand clusters with airport authorities under FAA grant assurance compliance, where surface friction certification requirements tighten material application precision standards.
- Snow Blowers:Rotary and auger-fed discharge systems handle deep accumulation events exceeding plow capacity. Alpine municipalities in Graubünden specify these for mountain pass accessibility.
- Ice Resolvers:Chemical applicators and thermal melting systems target bonded ice layers on critical infrastructure surfaces. Swedish Transport Administration procurement emphasizes these for bridge deck maintenance.
Plows dominate installed base. Electric and hybrid configurations are where expansion concentrates.
Application:
Cost tier differentiation separates specification-heavy infrastructure contracts from price-sensitive residential deployments, with municipal and commercial segments occupying intermediate positions.
- Municipal:City and county fleets operate the deepest installed base of severe-duty platforms with standardized blade widths and interoperability requirements. Polish secondary cities accessing EU cohesion funds are replacing Soviet-era equipment with modern specifications.
- Residential:Compact utility vehicles and attachment systems serve driveway and small-lot clearing. Homeowner demand in Calgary and Edmonton is shifting toward autonomous blade positioning retrofits that reduce operator training burdens.
- Commercial:Property management contractors face tightening OSHA winter workplace safety standards that expand insured equipment requirements across US retail and logistics campuses.
- Infrastructure:Highway authorities and airport operators specify the highest damage liability thresholds, commanding hydraulic precision controls and real-time friction monitoring. Avinor's sustained capital deployment in Norway anchors premium platform demand here.
Municipal fleets represent the deepest installed base. Infrastructure contracts are where margin expansion concentrates.
Technology:
Volume concentration still favors mechanical systems, though margin pools and capital allocation increasingly favor electrified alternatives as total cost of ownership equations shift.
- Mechanical:Direct-drive linkages and cable-actuated controls persist in price-sensitive segments and legacy fleet maintenance. These systems dominate shipment volumes in Eastern European municipal markets with constrained modernization budgets.
- Hydraulic:Precision pressure and flow controls enable variable blade positioning and attachment modulation. Swiss alpine grooming contracts increasingly specify hydraulic platforms for combined slope maintenance and terrain preparation capability.
- Electric:Battery-electric powertrains with solid-state thermal management now sustain sub-zero operational performance previously exclusive to combustion engines. Edmonton and Calgary pilot programs are validating compressed deployment timelines.
- Hybrid:Range-extended and parallel architectures bridge infrastructure gaps where charging deployment lags fleet electrification targets. Finnish airport contractors evaluate these under EU Green Deal implementation timelines.
Mechanical systems dominate installed base. Battery-electric platforms are where expansion concentrates.
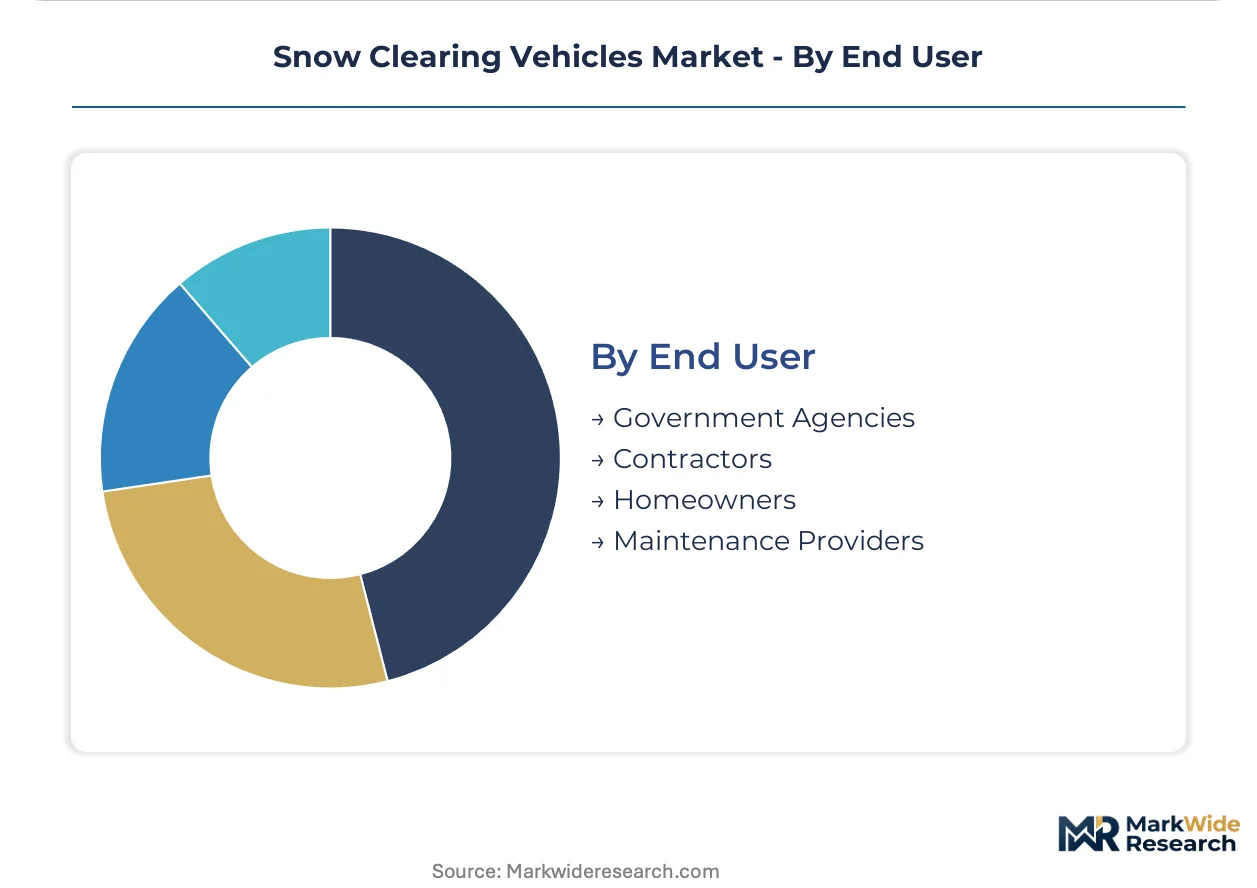
End User:
Customer type determines procurement channel structure, with government agencies and contractors facing divergent compliance frameworks and financing constraints.
- Government Agencies:State and municipal procurement offices operate through formal tender processes with multi-year fleet replacement cycles. Norwegian county authorities coordinate standardization across contiguous territories, consolidating specification-setting influence.
- Contractors:Private operators face tightening liability thresholds and insurance requirements that expand certified equipment mandates. US commercial property management contractors prioritize pre-certified electric alternatives to avoid FAA and EPA procurement delays.
- Homeowners:Individual purchasers drive compact equipment demand with seasonal utilization patterns and storage constraints. Attachment compatibility with existing utility vehicles influences purchase decisions.
- Maintenance Providers:Specialized service firms operate mixed fleets serving multiple client types with divergent specification requirements. These intermediaries face high-voltage technician scarcity as electrification accelerates.
Government agencies dominate installed base. Contractor fleets are where specification intensity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized chassis and hydraulic systems to Scandinavian municipal fleets, while US manufacturers supply airport ground support equipment to Canadian and Middle Eastern buyers.
Norway
Avinor's sustained capital deployment for winter preparedness anchors premium platform demand across Oslo, Bergen, and Tromsø airports. EU Green Deal decarbonization mandates bind state-owned operators to emission reduction timelines that accelerate electric fleet replacement. Tromsø's Arctic climate testing facilities validate solid-state thermal management systems for sub-zero battery performance.
Sweden
Swedish Transport Administration procurement emphasizes ice resolvers and bridge deck maintenance systems for critical infrastructure resilience. REACH chemical regulations constrain de-icing material formulations, redirecting specification toward precision application equipment. Northern county authorities in Norrbotten coordinate inter-municipal fleet standardization across contiguous territories.
Canada
Edmonton and Calgary municipal fleets pilot autonomous blade positioning retrofits that compress operator training requirements for seasonal hiring. Transport Canada winter road maintenance standards tighten surface friction certification requirements. Alberta's oil sands logistics corridors drive severe-duty platform demand for haul road accessibility.
Switzerland
Graubünden and Vorarlberg regional tendering consolidates alpine grooming and slope maintenance contracts through inter-municipal cooperative frameworks. F-Gas Regulation compliance elevates specification intensity for combined snow clearing and terrain preparation platforms. Zürich-based procurement consortia increasingly standardize equipment specifications across contiguous cantonal territories.
Poland
EU cohesion fund access enables secondary cities to replace Soviet-era equipment with modern specifications ahead of diesel phase-out deadlines. Polish municipal fleet modernization concentrates in Kraków, Wrocław, and Łódź procurement offices. The country's national environmental regulator implements Euro Stage V transition timelines that constrain small-volume diesel engine sourcing.
Snow Clearing Vehicles Market Competitive Landscape
On the supply side, the industry is tiered between defense-derived severe-duty specialists and regional fabrication houses serving price-sensitive municipal segments. Tier-one players leverage all-wheel-drive architectures and precision hydraulic controls to command premium positioning in airport and infrastructure contracts. Mid-tier builders compete on attachment compatibility and fleet interoperability for seasonal municipal deployments. Dominant competitive moves include strategic partnerships for battery-electric powertrain integration and geographic expansion through inter-municipal procurement consortia.
Among US-based severe-duty specialists, Oshkosh Corporation and Alamo Group Inc. occupy positions anchored by defense-contractor heritage and municipal equipment diversification. Swiss-incorporated PRINOTH AG exemplifies the alpine-specialist archetype, with slope-grade capability commanding premium positioning in mountain grooming applications. These three entities represent distinct competitive vectors: multi-segment industrial conglomeration, regional municipal fleet penetration, and terrain-specific technical specialization.
| Leading Market Players |
|---|
| Alamo Group Inc. |
| Oshkosh Corporation |
| M-B Companies, Inc. |
| Team Eagle Ltd. |
| Kodiak America |
| Marcel Boschung AG |
| PRINOTH AG |
| Bobcat Company |
| Wausau Equipment Company, Inc. |
| Others |
Value Network & Pricing Analysis
Chinese cathode material processing infrastructure concentrates upstream cost leverage for battery-electric powertrains, compressing margin pools for European and North American OEMs while redirecting procurement budgets toward thermal management and solid-state heating subsystems where technical differentiation commands premium positioning.
Pricing Analysis
Current-generation battery-electric platforms carry 35-50% capital cost premiums over prior-generation diesel equivalents, though next-generation solid-state thermal systems are narrowing this differential through operational efficiency gains. Three-tier pricing structure across premium, standard, and economy levels separates airport infrastructure contracts with FAA friction certification requirements from municipal fleet replacements and seasonal contractor equipment. Pricing pressure stems from lithium supply volatility and EPA Tier 4 Final certification cost absorption, with Polish secondary cities and Eastern European municipalities exhibiting highest price sensitivity due to EU cohesion fund dependency and Soviet-era fleet replacement urgency.
Supply Chain Analysis
Export control regimes restricting high-voltage battery management system technology flows between jurisdictions are fragmenting supplier qualification pathways for OEMs serving multiple regulatory domains. Manufacturing concentration in Germany, China, and South Korea anchors chassis and hydraulic system sourcing, while lithium carbonate, nickel sulfate, and rare-earth permanent magnet materials draw from concentrated extraction geographies. Single-source vulnerability in solid-state thermal management componentry elevates supply chain risk for sub-zero operational platforms. Distribution runs through municipal procurement consortia and airport authority tender processes that consolidate specification-setting influence away from traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on interoperability standardization across Norwegian county fleet coordination and Graubünden-Vorarlberg inter-municipal frameworks, where consolidated procurement consortia are displacing fragmented dealer specification influence.
For Market Incumbents: Pre-empt powertrain transition margin compression by securing captive lithium supply agreements and accelerating solid-state thermal management in-house production before export control regimes tighten technology transfer pathways. Defend airport infrastructure positioning through FAA pre-certification investment that compresses procurement cycle advantages over mid-tier competitors facing documentation delays. For New Entrants and Emerging Players: Build out aftermarket service capabilities targeting high-voltage technician scarcity in maintenance provider fleets, where electrification skill gaps create addressable white space independent of manufacturing scale requirements. Polish municipal modernization programs offer most penetrable entry geography given EU cohesion fund visibility and Soviet-era replacement urgency, with attachment compatibility and fleet interoperability as primary go-to-market angles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed alpine grooming specialists possessing terrain-grade technical credibility but lacking electric powertrain integration capabilities for EU Green Deal compliance. Five-to-ten year viability hinges on regulatory timeline execution rather than demand cyclicality. Watch Avinor procurement specification releases as inflection indicator for premium platform demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Electrification Partnership | Battery-electric integration with solid-state thermal management addresses EU Green Deal mandates and FAA grant assurance compliance. |
| Inter-Municipal Procurement Consortium Formation | Standardized specifications across contiguous territories consolidate demand influence and compress dealer network margins in Switzerland and Poland. |
| High-Voltage Technician Certification Program | Addressed skill scarcity in maintenance provider fleets unlocks aftermarket service revenue as electrification accelerates. |
| Autonomous Blade Positioning Retrofit Launch | LiDAR terrain mapping integration reduces operator training burdens for Edmonton and Calgary seasonal hiring pools. |
| Captive Lithium Supply Agreement | Upstream cathode material access insulates OEM margins from Chinese refining infrastructure volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal fleet managers, airport ground support equipment procurement officers, alpine grooming contract administrators, and high-voltage maintenance technicians; and secondary validation through customs trade databases, EPA certification filings, EU tender documentation, and F-Gas Regulation compliance registries. Bottom-up equipment shipment triangulation against top-down procurement budget analysis anchored volume and value estimates.
Forecast inputs span powertrain technology generation, application duty cycle intensity, regulatory compliance tier, and regional procurement consolidation patterns across the projection horizon. Segmentation dimensions modeled include product type, application severity, technology architecture, and end-user procurement channel. CAGRs derived from replacement cycle velocity analysis and capital allocation trajectory assessment, with battery thermal management performance validation and friction certification requirement tightening as industry-specific demand drivers.
Stress conditions across lithium price volatility bands, EPA enforcement intensity scenarios, and EU cohesion fund disbursement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding powertrain transition pacing and regulatory deadline adherence. Material shifts in export control regime stringency or solid-state battery commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Snow Removal Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
India Crane Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Cement Consistometer Market