
 Wire Mesh Welding Machines Market | 2026-2036
Wire Mesh Welding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Mesh Welding Machines Market Insights
Software-defined weld parameter control is pivoting how machine builders monetize equipment, shifting revenue from hardware-only sales to recurring firmware subscriptions and predictive maintenance contracts. Schlatter Group AG leverages its Swiss engineering heritage to dominate precision mesh applications for medical and filtration end uses. Lincoln Electric Holdings, Inc. sustains technology leadership through deep R&D in resistance welding power sources. WAFIOS AG differentiates by occupying the high-speed automated segment with integrated coil-to-mesh lines that reduce labor content.
Wire mesh welding machines are electromechanical systems that fuse intersecting metal wires at programmed intervals using controlled electrical current, typically handling wire diameters from 2 mm to 16 mm and producing grids at speeds exceeding 120 cross-wires per minute for concrete reinforcement, fencing, and industrial screening. Resistance welding technology anchors the installed base due to its reliability with carbon steel, though laser welding is gaining traction for stainless architectural mesh where heat-affected zone control determines product quality. Automatic systems command the premium tier as construction contractors prioritize throughput and labor reduction over capital cost. Industrial mesh applications lead volume demand while security mesh generates higher per-unit margins through specialized alloy requirements and tighter tolerance specifications.
FDA oversight of surgical mesh implants creates downstream quality mandates that propagate to welding equipment specifications, particularly for medical-grade stainless mesh producers supplying US device manufacturers. China's SAMR enforces GB standards for welded reinforcement mesh used in state infrastructure projects, compelling domestic and foreign equipment makers to certify compliance for market access. The EU Construction Products Regulation and CE marking requirements shape export competitiveness for European machine builders. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving steel decarbonization rules reshape raw material costs and equipment specification priorities across major manufacturing clusters.
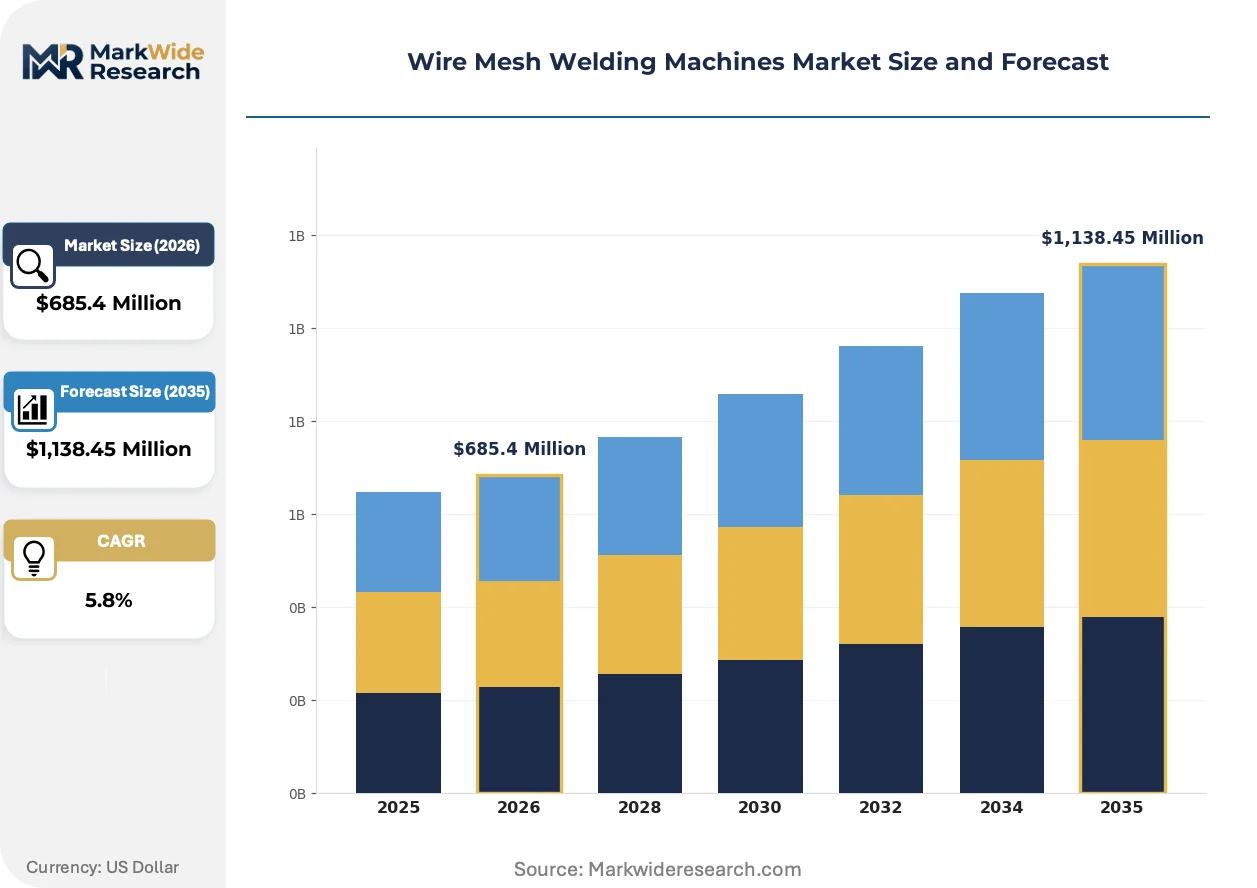
Market Dynamics
Software-defined weld parameter control is consolidating machine builder revenue models away from hardware-only sales toward recurring firmware subscriptions and predictive maintenance contracts, reshaping competitive positioning in automated mesh production.
Growth Catalysts
- India's northern industrial corridor expansion:Precast concrete plants in Haryana, Uttar Pradesh, and Punjab are commissioning high-throughput welding lines to meet infrastructure build-out timelines under the National Infrastructure Pipeline.
- China's GB standard tightening:SAMR enforcement of stricter welded steel reinforcement mesh quality requirements for export-bound equipment is forcing equipment upgrades across Southeast Asian manufacturing bases supplying Chinese contractors.
- Laser welding penetration:Stainless architectural mesh producers are adopting fiber laser systems for heat-affected zone control in premium facade applications, displacing resistance welding in tolerance-critical segments.
Market Restraints
- Copper and silicon steel input volatility:Transformer core materials and welding electrode alloys face price swings that compress equipment margins during contract manufacturing cycles.
- European machine builder supply concentration:Swiss and German precision welding system manufacturers control critical servo-drive and power-source IP, creating import dependency for Asian fabricators.
- Resistance welding technical ceiling:Carbon steel mesh production speed plateaus at approximately 120 cross-wires per minute, limiting throughput gains without capital-intensive line duplication.
Strategic Opportunities
- Vietnam's underpenetrated fabrication base:Construction contractors in Ho Chi Minh City and Hanoi are retrofitting manual mesh shops with semi-automatic systems to serve Japanese and Korean contractor specifications.
- EU Green Deal carbon-border adjustment:European importers of welded mesh will face embodied carbon reporting requirements, creating demand for energy-efficient welding equipment with verified carbon footprints.
- Medical-filtration convergence:Surgical mesh and industrial filtration producers are converging on identical austenitic stainless grades, enabling equipment makers to serve dual end-use markets with single platform architectures.
Industry Challenges
- Certification timeline compression:FDA 510(k) pathways for surgical mesh welding equipment require extensive validation documentation that extends sales cycles for medical-grade system variants.
- Legacy PLC integration friction:Brownfield concrete plants in India's industrial corridor operate Siemens S7-300 and Allen-Bradley ControlLogix architectures that resist seamless integration with modern Ethernet/IP welding controllers.
- Skilled electrode maintenance scarcity:Resistance welding electrode dressing and alignment expertise is retiring from European and North American workforces faster than training programs replenish capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Mesh Welding Machines Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customized Technology: Resistance Welding, Laser Welding, Ultrasonic Welding, MIG Welding End User: Construction, Automotive, Agriculture, Fencing Application: Industrial Mesh, Decorative Mesh, Security Mesh, Filter Mesh |
| Companies Covered | Schlatter Group AG, Lincoln Electric Holdings, Inc., KUKA AG, EVG - Elektronik Vertriebs Gesellschaft mbH, WAFIOS AG, Schnell S.p.A., DAPU Machinery, JWELL Machinery, Yizhou Machinery Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Mesh Welding Machines Market Trends and Innovations
Digital thread integration across coil handling, welding, and mesh cutting is compressing changeover times and enabling lot-size-one production for specialized reinforcement patterns.
Servo-electric weld force actuation is consolidating mechanical pneumatic systems out of precision mesh applications. Medical device manufacturers in Minnesota and North Carolina are specifying electric press systems for FDA-regulated surgical mesh production. The technology is consolidating quality documentation capabilities by embedding force-displacement curves directly into batch records.
China's GB/T 1499.3 standard revision for welded reinforcement mesh is mandating tighter dimensional tolerances and weld shear strength minimums. Domestic equipment makers in Jiangsu and Shandong provinces are retrofitting hydraulic weld stations with closed-loop force monitoring to certify compliance. Export-oriented Chinese fabricators are demanding CE-marked European welding controllers to preempt technical barriers in Southeast Asian project tenders.
Contractors in Indonesia and the Philippines are unbundling after-sales service from equipment purchase, procuring welding lines on capital leases while purchasing maintenance and spare parts through separate annual contracts. Equipment distributors in Jakarta and Manila are responding by building captive service organizations. The shift is most visible in precast concrete verticals where plant uptime guarantees determine project milestone payments.
Wire Mesh Welding Machines Market Segmentation
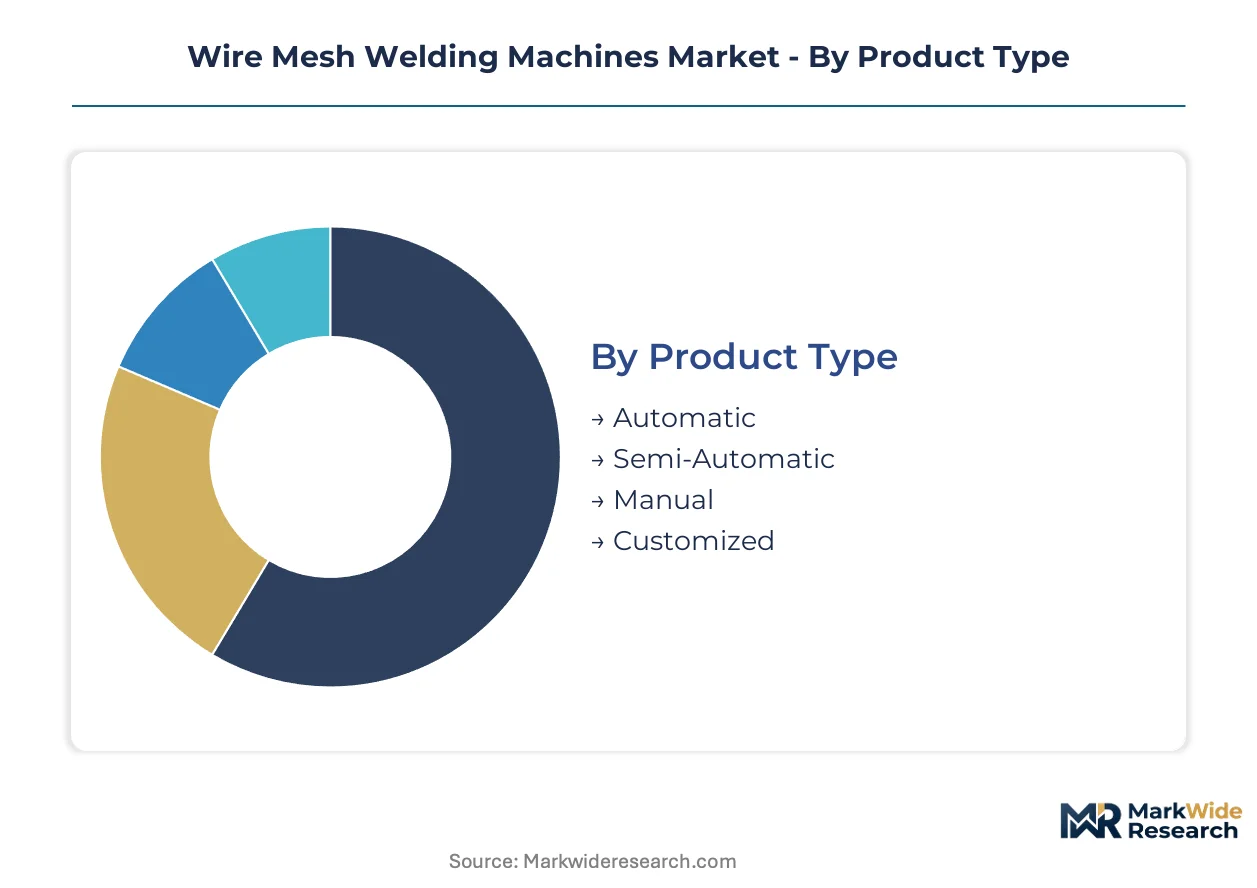
Wire mesh welding equipment varies dramatically in capital intensity and operational complexity. Buyers select configurations based on throughput requirements, material specifications, and regulatory compliance obligations for their target end-use markets.
Product Type:
Capital intensity escalates sharply from manual stations to fully automated coil-to-mesh lines. Automatic systems demand the highest upfront investment but deliver labor substitution and quality consistency at scale.
- Automatic:Integrated coil handling, servo-electric weld force actuation, and digital parameter control enable speeds exceeding 120 cross-wires per minute. Precast concrete plants in India's northern industrial corridor commission these lines to meet National Infrastructure Pipeline timelines. FDA-regulated surgical mesh producers specify electric press variants for embedded quality documentation.
- Semi-Automatic:Hybrid configurations blend operator-fed wire positioning with automated welding cycles. Construction contractors in Vietnam's Ho Chi Minh City and Hanoi retrofit manual shops with these systems to satisfy Japanese and Korean contractor specifications.
- Manual:Operator-controlled spot welding stations serve low-volume custom fabrication and prototype development.
- Customized:Purpose-built architectures address specialized mesh geometries or alloy combinations outside standard product ranges.
Most installed capacity flows through Automatic systems. Expansion is steepest in Semi-Automatic configurations as emerging market fabricators modernize without full automation investment.
Technology:
Process selection hinges on material compatibility, heat-affected zone requirements, and speed-to-quality tradeoffs. Each technology occupies distinct positions in the performance-cost spectrum.
- Resistance Welding:Electromechanical fusion using controlled current through overlapping wire junctions. Carbon steel reinforcement mesh production relies on this established base due to reliability and electrode longevity.
- Laser Welding:Fiber laser systems deliver precise heat-affected zone control for stainless architectural mesh. Premium facade applications in developed markets displace resistance welding where tolerance criticality justifies capital premium.
- Ultrasonic Welding:High-frequency mechanical vibration bonding suits non-ferrous and coated wire applications where thermal distortion must be eliminated.
- MIG Welding:Gas-metal arc processes handle heavier wire diameters and structural mesh requiring deeper penetration than resistance methods achieve.
Resistance Welding retains the largest installed base. Laser Welding is gaining share fastest in medical and architectural segments where surface integrity commands priority.
End User:
Demand concentration varies by sector maturity, infrastructure spending cycles, and regulatory intensity. Each vertical imposes distinct equipment specifications and service requirements.
- Construction:Reinforcement mesh for concrete infrastructure dominates volume demand. China's GB standard tightening for welded steel reinforcement mesh forces equipment upgrades across Southeast Asian manufacturing bases supplying Chinese contractors.
- Automotive:Lightweight structural mesh and battery enclosure screening require precision tolerance and lot traceability.
- Agriculture:Livestock fencing and greenhouse structures utilize standard carbon steel mesh with moderate specification stringency.
- Fencing:Security perimeter applications generate higher per-unit margins through specialized alloy requirements and anti-climb geometry complexity.
Construction absorbs the majority of annual equipment shipments. Fencing delivers the highest margin contribution per machine sold.
Application:
End-use functionality determines mesh specification, which propagates backward to welding equipment requirements. Applications split between high-volume commodity production and precision-tolerance specialty manufacturing.
- Industrial Mesh:Heavy-gauge carbon steel grids for material handling, mining screens, and structural reinforcement. Standard resistance welding configurations serve this high-volume, price-sensitive segment.
- Decorative Mesh:Architectural facades and interior features demand aesthetic surface quality. Stainless grades and controlled heat input distinguish equipment specifications.
- Security Mesh:Anti-intrusion and ballistic-rated applications require tight geometric tolerances and high-strength alloy fusion.
- Filter Mesh:Surgical implants and industrial filtration converge on identical austenitic stainless grades. FDA 510(k) pathways for surgical mesh welding equipment extend sales cycles but lock in premium pricing.
Industrial Mesh represents the largest addressable equipment base. Filter Mesh is expanding most quickly as medical-filtration grade convergence enables dual-market platform architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement is migrating toward jurisdictions where GB standard alignment costs less than CE marking overhead, compressing European machine builder margins in price-sensitive segments while opening Southeast Asian fabrication hubs.
China
GB/T 1499.3 standard revisions for welded reinforcement mesh are forcing domestic equipment retrofits across Jiangsu and Shandong provinces. SAMR enforcement creates compliance cost gaps that favor local manufacturers over European imports. Export-oriented fabricators in Yangzhou industrial clusters are demanding CE-marked controllers to preempt technical barriers in Vietnamese and Indonesian project tenders.
India
Precast concrete plants in Haryana, Uttar Pradesh, and Punjab are commissioning high-throughput welding lines under National Infrastructure Pipeline timelines. BIS certification requirements for construction-grade mesh equipment are tightening quality mandates. Faridabad and Ludhiana industrial corridors concentrate demand where Japanese contractor specifications override domestic standards.
Vietnam
Construction contractors in Ho Chi Minh City and Hanoi are retrofitting manual mesh shops with semi-automatic systems to serve Japanese and Korean contractor specifications. The country's national standards body is aligning welding equipment norms with ASEAN harmonization protocols. Binh Duong province fabrication zones are absorbing decommissioned Chinese capacity as labor cost arbitrage shifts southward.
Indonesia
Precast concrete verticals in Jakarta and Surabaya are unbundling equipment purchase from after-sales service through capital leases. The national infrastructure regulator is mandating welded mesh traceability for state-funded bridge and highway projects. Bekasi industrial estates host the densest concentration of retrofit activity as contractors chase Japanese project milestone payments.
Germany
Precision welding system manufacturers in Baden-Württemberg and Bavaria control critical servo-drive and power-source IP that Asian fabricators import. EU Green Deal carbon-border adjustment mechanisms are reshaping equipment specification priorities for export-bound mesh producers. Stuttgart and Munich engineering clusters are pivoting toward predictive maintenance contracts to offset hardware margin compression.
Wire Mesh Welding Machines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision medical applications favoring Swiss and German engineering heritage while commodity reinforcement mesh tilts toward Chinese and Italian volume producers. The vendor base organizes around three archetypes: integrated coil-to-line specialists, component-focused power-source technologists, and regional fabrication-system integrators. Strategic moves concentrate on predictive maintenance contract bundling and firmware subscription layering atop hardware sales.
Within the precision-tier segment, Schlatter Group AG and WAFIOS AG exemplify engineering-origin specialists that anchor premium positioning through servo-electric actuation and embedded quality documentation. Lincoln Electric Holdings, Inc. occupies a distinct tier as a power-source technologist whose resistance welding R&D propagates across multiple equipment OEMs. Among Asia-Pacific fabricators, DAPU Machinery and Yizhou Machinery Technology represent the volume-oriented archetype serving cost-sensitive infrastructure markets with GB-standard compliance as the primary competitive filter.
| Leading Market Players |
|---|
| Schlatter Group AG |
| Lincoln Electric Holdings, Inc. |
| KUKA AG |
| EVG - Elektronik Vertriebs Gesellschaft mbH |
| WAFIOS AG |
| Schnell S.p.A. |
| DAPU Machinery |
| JWELL Machinery |
| Yizhou Machinery Technology |
| Others |
Pricing and Supply Chain Analysis
Precast concrete contractors in India's northern industrial corridor concentrate procurement power through National Infrastructure Pipeline tenders, compressing equipment pricing toward lifecycle-cost models that bundle predictive maintenance and firmware subscriptions.
Pricing Analysis
Capacity additions in Jiangsu and Shandong provinces are reshaping price floors for GB-standard compliant systems. Pricing stratifies across premium, standard, and economy tiers based on servo-electric actuation grade and CE-marking status. Price erosion runs through the manual and semi-automatic tiers as Chinese fabricators absorb surplus capacity. Construction contractors remain most price-sensitive, while FDA-regulated surgical mesh producers accept premium positioning for embedded quality documentation.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Mumbai coordinate hub-and-spoke patterns for servo-drive and power-source components. Manufacturing draws from Germany, Switzerland, and China for precision welding controllers, with copper transformer cores and silicon steel electrode alloys sourced from Chile and Australia. Single-source vulnerability concentrates in Swiss and German IP for closed-loop force monitoring systems. Distribution runs through captive service organizations that Jakarta and Manila distributors are building to unbundle equipment from aftermarket contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
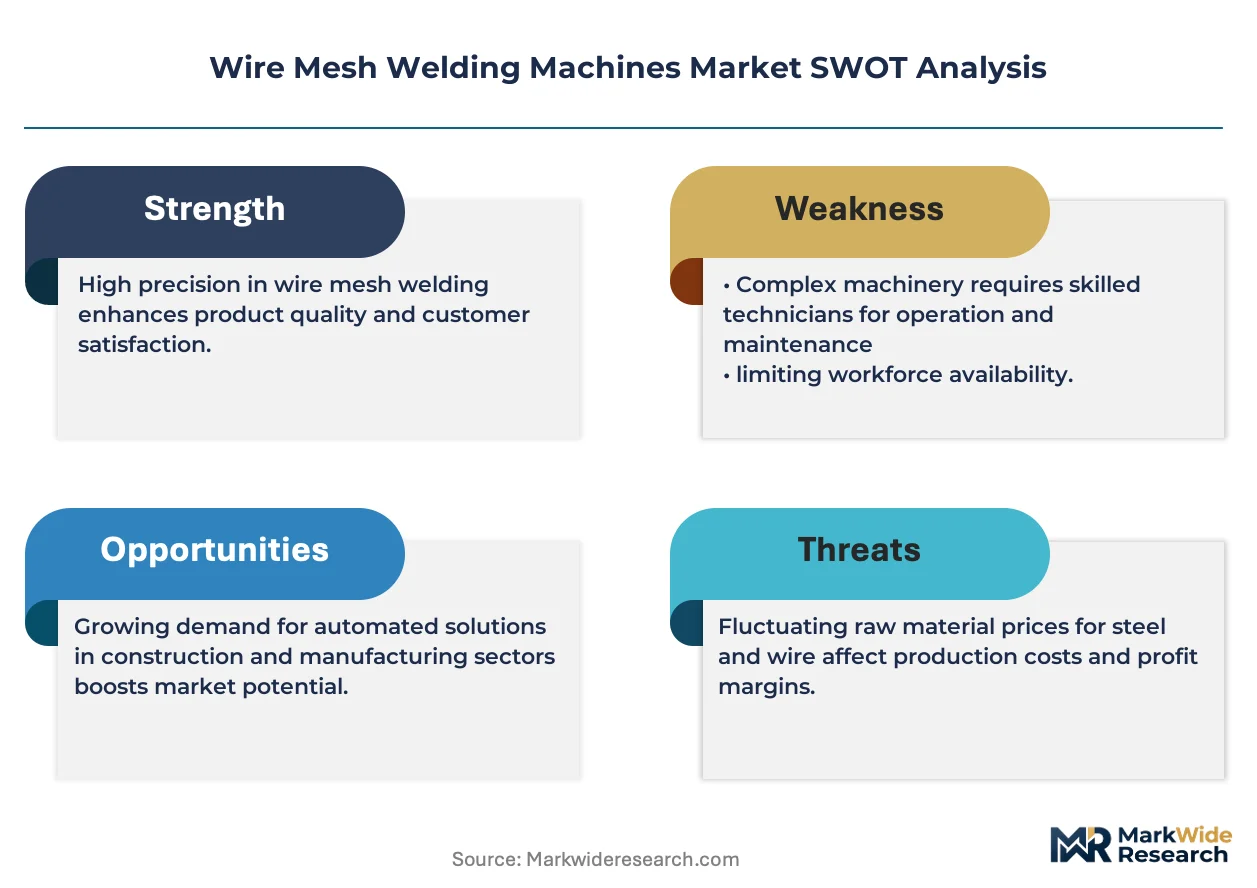
The wire mesh welding machines market reads as a late-cycle quality story, with downstream demand shifting toward FDA-validated surgical mesh and EU carbon-border-compliant architectural specifications that reward precision-tier equipment.
For Market Incumbents: Cement technology leadership through backward integration into servo-drive IP and predictive maintenance contract bundling. Laser welding systems for stainless architectural mesh threaten resistance welding incumbents in premium facade applications. Capacity additions in Vietnam's Binh Duong province demand preemptive channel control through local service partnerships. For New Entrants and Emerging Players: The price-point gap between CE-marked European systems and GB-standard Chinese equipment creates white-space for mid-tier ASEAN fabricators. Vietnam's semi-automatic retrofit wave offers the most penetrable entry, with Indonesian capital lease structures enabling service-revenue-first go-to-market positioning. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, targeting precision-tier specialists with FDA validation capabilities and embedded firmware architectures. Long-term viability hinges on software-defined revenue mix expansion. Watch laser welding penetration rates in medical-grade stainless mesh as the inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Bundling | Equipment distributors in Jakarta are building captive service organizations to capture recurring revenue streams. |
| Servo-Electric Actuation Migration | Medical device manufacturers in Minnesota specify electric press systems for FDA-regulated surgical mesh production. |
| GB Standard Compliance Certification | Domestic equipment makers in Jiangsu retrofit hydraulic stations with closed-loop force monitoring for SAMR enforcement. |
| Laser Welding Platform Expansion | Stainless architectural mesh producers adopt fiber laser systems for heat-affected zone control in premium facades. |
| Regional Distribution Center Establishment | Mumbai and Shanghai hubs coordinate component logistics for Indian precast concrete plant commissioning timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers with secondary validation through customs trade data, SEC filings, BIS certification records, and SAMR enforcement notices. Bottom-up equipment shipment modeling and top-down infrastructure spending triangulation anchored value estimates.
Segment-weighting applied product type, technology, end user, and application dimensions across the projection horizon, with CAGRs derived from regression analysis against construction output indices and medical device approval trajectories. Modeled inputs included National Infrastructure Pipeline project timelines, GB/T 1499.3 revision compliance costs, and FDA 510(k) pathway validation documentation burdens.
The model assumes a particular technology adoption path; alternative pathways for laser welding displacement of resistance welding would alter the outlook. Forecasts reflect documented assumptions on copper and silicon steel input cost trajectories, skilled electrode maintenance workforce availability, and ASEAN harmonization protocol alignment timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Robotic Mill Liner Market