
 Scaffold Technology Market | 2026-2036
Scaffold Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Scaffold Technology Market Analysis
REACH is expanding the cost-of-entry calculus for European scaffold manufacturers by mandating exhaustive substance safety documentation for novel biomaterials. Thermo Fisher Scientific Inc. leverages its analytical instrumentation portfolio to support client compliance with evolving chemical registration protocols. Merck KGaA anchors its position through high-purity reagent supply chains that feed directly into scaffold fabrication workflows. Corning Incorporated differentiates via decades of glass and ceramic material science translated into controlled-porosity substrates.
Scaffold technology encompasses three-dimensional porous structures engineered from biocompatible materials including collagen, PLGA, hydroxyapatite, and chitosan, fabricated through techniques such as electrospinning, freeze-drying, and selective laser sintering to provide mechanical support and biochemical cues for cell attachment, proliferation, and tissue formation in vitro and in vivo. Polymer scaffolds dominate current production volumes due to tunable degradation rates and established manufacturing scalability, while bio-scaffolds derived from decellularized extracellular matrix command premium positioning in regenerative medicine applications where immunogenicity minimization determines clinical outcomes. Tissue engineering absorbs the largest share of scaffold deployment as academic and commercial laboratories transition from two-dimensional culture platforms to organoid and organ-on-chip systems requiring biomimetic structural environments.
The FDA maintains stringent premarket notification pathways for scaffold-based combination products, while the EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on resorbable implants marketed across EU member states. ISO 10993 biocompatibility testing standards govern material qualification protocols that scaffold developers must satisfy before initiating human trials. Stakeholders must monitor how harmonization pressures between FDA breakthrough device designation criteria and EU MDR Article 117 drug-device interface rules reshape competitive access timelines for multinational product portfolios.
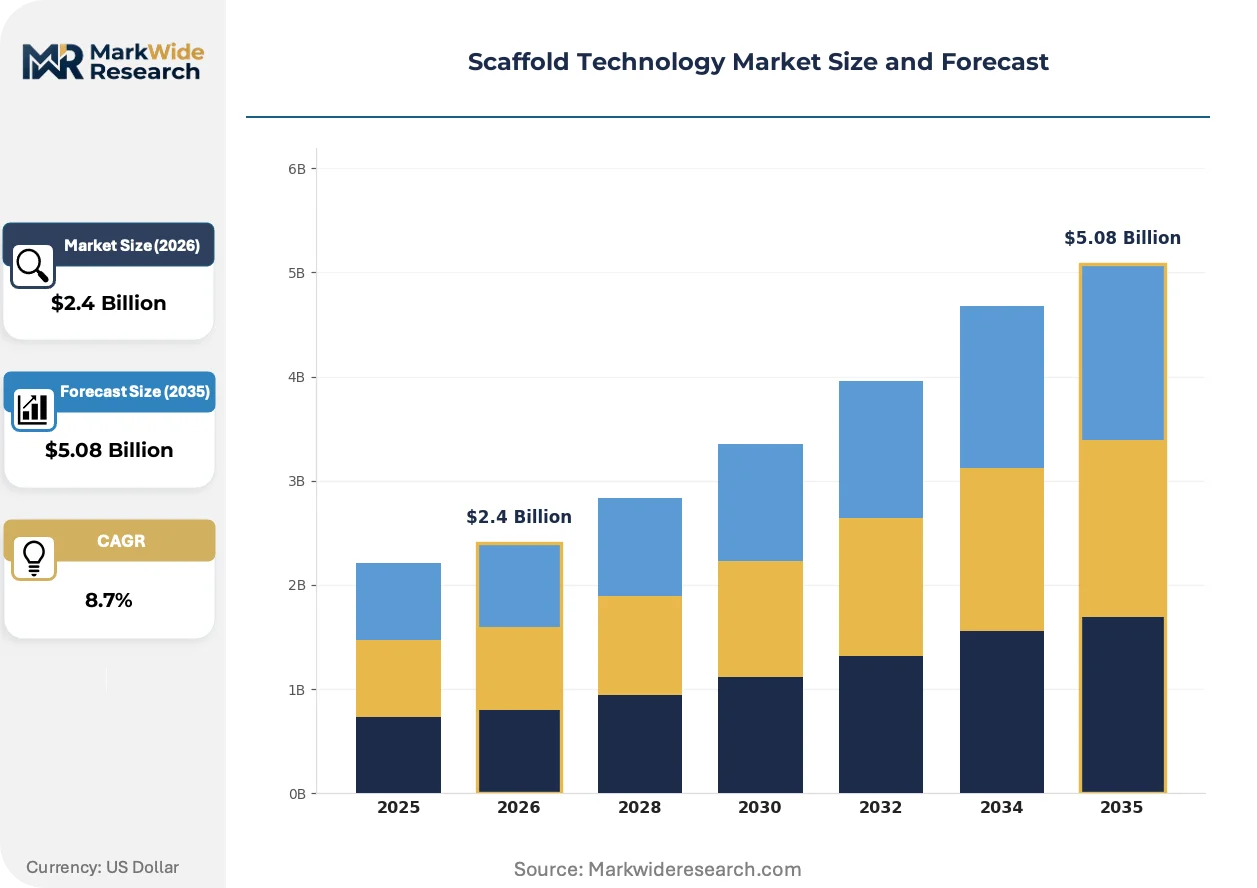
Market Dynamics
Bioresorbable scaffold validation timelines are compressing as FDA breakthrough device designation criteria converge with EU MDR Article 117 drug-device interface rules, forcing manufacturers to synchronize premarket evidence packages across jurisdictions.
Growth Catalysts
- FDA 3D-Printed Device Guidance:Accelerated validation pathways for patient-specific implants are shortening commercialization cycles for orthopedic applications.
- Electrospinning Scale-Up:Manufacturing throughput improvements for nanofiber scaffolds are reducing unit costs for tissue engineering laboratories.
- Academic Medical Center Procurement:United States teaching hospitals are consolidating vendor relationships through multi-year scaffold supply agreements.
Market Restraints
- PLGA Feedstock Volatility:Polymer precursor pricing swings are compressing gross margins for mid-tier scaffold fabricators.
- Decellularized ECM Supply Concentration:Porcine and bovine tissue sourcing clusters in specific agricultural regions create biological raw material vulnerability.
- ISO 10993 Testing Burden:Extended biocompatibility qualification timelines delay human trial initiation by 18-24 months for novel biomaterial formulations.
Strategic Opportunities
- Organ-on-Chip Integration:Convergence of microfluidics with 3D scaffold architecture is opening high-value contracts with pharmaceutical toxicology departments.
- India CDSCO Harmonization:Emerging regulatory alignment with ICH guidelines is simplifying market entry for Western scaffold manufacturers.
- Direct-to-Laboratory Distribution:E-commerce platforms serving academic researchers are bypassing traditional medical device distributor markups.
Industry Challenges
- Biofabrication Technician Scarcity:Cross-disciplinary expertise combining materials science with cell biology commands premium compensation and extends hiring timelines.
- Cleanroom Capex Requirements:GMP-compliant scaffold production facilities demand capital intensity that excludes emerging market entrants.
- Patent Thicket Navigation:Overlapping intellectual property claims covering electrospinning nozzle designs complicate freedom-to-operate analyses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scaffold Technology Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bio-scaffolds, Polymer Scaffolds, Ceramic Scaffolds, Metallic Scaffolds Application: Tissue Engineering, Drug Delivery, Regenerative Medicine, Wound Healing Material: Collagen, PLGA, Hydroxyapatite, Chitosan End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Corning Incorporated, Becton Dickinson and Company, Tecan Trading AG, 3D Biotek LLC, Molecular Matrix Inc., REPROCELL Inc., Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scaffold Technology Market Emerging Trajectories
Scaffold manufacturing is transitioning from standardized porous structures toward programmable architectures that encode spatial biochemical gradients, reshaping how researchers approach tissue mimicry.
4D bioprinting is unifying shape-memory polymers with live cell encapsulation to create scaffolds that self-assemble post-implantation. Reconstructive surgery departments at Cleveland Clinic and Massachusetts General Hospital are piloting these systems for cartilage defect repair. This capability is compressing the gap between in vitro scaffold characterization and in vivo remodeling outcomes.
REACH substance registration is forcing European manufacturers to disclose complete supply chain chemical compositions for novel hydroxyapatite composites. ECHA compliance costs are redirecting R&D investment toward known-material modifications rather than novel compound development. German orthopedic implant producers are responding by consolidating supplier audits under unified quality management systems.
Research procurement officers are unbundling scaffold purchases from integrated cell culture service contracts. Academic laboratories at Stanford, Johns Hopkins, and University of Tokyo are negotiating direct material sourcing agreements independent of traditional full-service distributors. This pattern is most pronounced in United States National Institutes of Health grant-funded projects where equipment and consumable budgets face separate audit scrutiny.
Scaffold Technology Market Segmentation
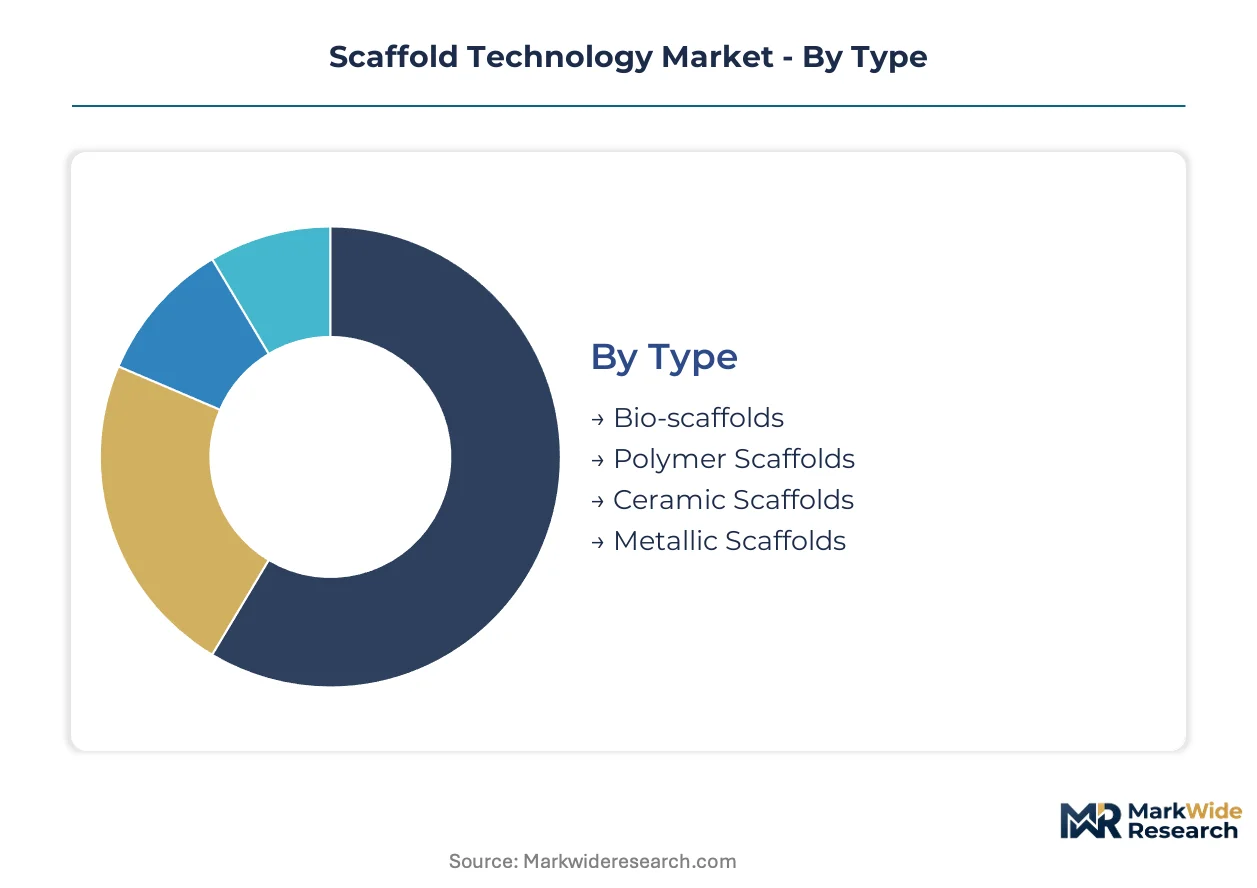
Scaffold technology markets fragment across four distinct axes that determine manufacturing economics and procurement patterns. Each segmentation layer carries implications for capital deployment, regulatory pathway selection, and customer relationship structure.
Type:
Capital intensity varies dramatically across scaffold categories, with cleanroom infrastructure and biocompatibility testing burdens creating divergent barriers to entry.
- Polymer Scaffolds:PLGA and PCL formulations dominate current production volumes due to tunable degradation kinetics and established electrospinning scale-up. United States tissue engineering laboratories at Stanford and Johns Hopkins absorb the majority of commercial shipments as academic procurement unbundles from full-service contracts.
- Bio-scaffolds:Decellularized extracellular matrix commands premium positioning where immunogenicity minimization determines clinical outcomes. Porcine and bovine tissue sourcing clusters in specific agricultural regions create biological raw material vulnerability that concentrates supply risk.
- Ceramic Scaffolds:Hydroxyapatite and tricalcium phosphate structures serve load-bearing orthopedic applications requiring compressive strength matching cancellous bone.
- Metallic Scaffolds:Titanium and magnesium alloys retain niche positioning for craniofacial reconstruction where radiopacity and mechanical integrity outweigh resorption requirements.
Polymer scaffolds absorb the bulk of installed capacity; bio-scaffolds are expanding most quickly.
Application:
Customer technical sophistication and purchasing authority shape demand patterns across clinical and research settings.
- Tissue Engineering:Organoid and organ-on-chip system deployment drives biomimetic structural environment requirements. Academic and commercial laboratories transition from two-dimensional culture platforms, compressing validation timelines for scaffold suppliers.
- Regenerative Medicine:Orthopedic surgeons and reconstructive specialists expand bioresorbable scaffold use for bone regeneration. Cleveland Clinic and Massachusetts General Hospital pilot 4D bioprinting systems for cartilage defect repair.
- Drug Delivery:Controlled-release kinetics integrate scaffold architecture with pharmaceutical formulation design.
- Wound Healing:Chronic wound clinics adopt collagen and chitosan matrices for diabetic ulcer management.
Tissue engineering commands the largest procurement volumes; regenerative medicine shows the steepest expansion trajectory.
Material:
Feedstock chemistry determines regulatory pathway complexity and supply chain geographic concentration.
- PLGA:Poly-lactic-co-glycolic acid offers degradation tunability from weeks to months through lactide:glycolide ratio adjustment. Polymer precursor pricing swings compress gross margins for mid-tier fabricators exposed to commodity chemical volatility.
- Collagen:Type I and III matrices derived from bovine and porcine sources provide native cell adhesion motifs. REACH substance registration forces European manufacturers to disclose complete supply chain chemical compositions.
- Hydroxyapatite:Calcium phosphate ceramic mimics bone mineral composition for orthopedic integration.
- Chitosan:Deacetylated chitin from crustacean shells offers antimicrobial properties for wound healing applications.
PLGA absorbs the bulk of installed capacity; collagen is climbing the fastest amid decellularized matrix demand.
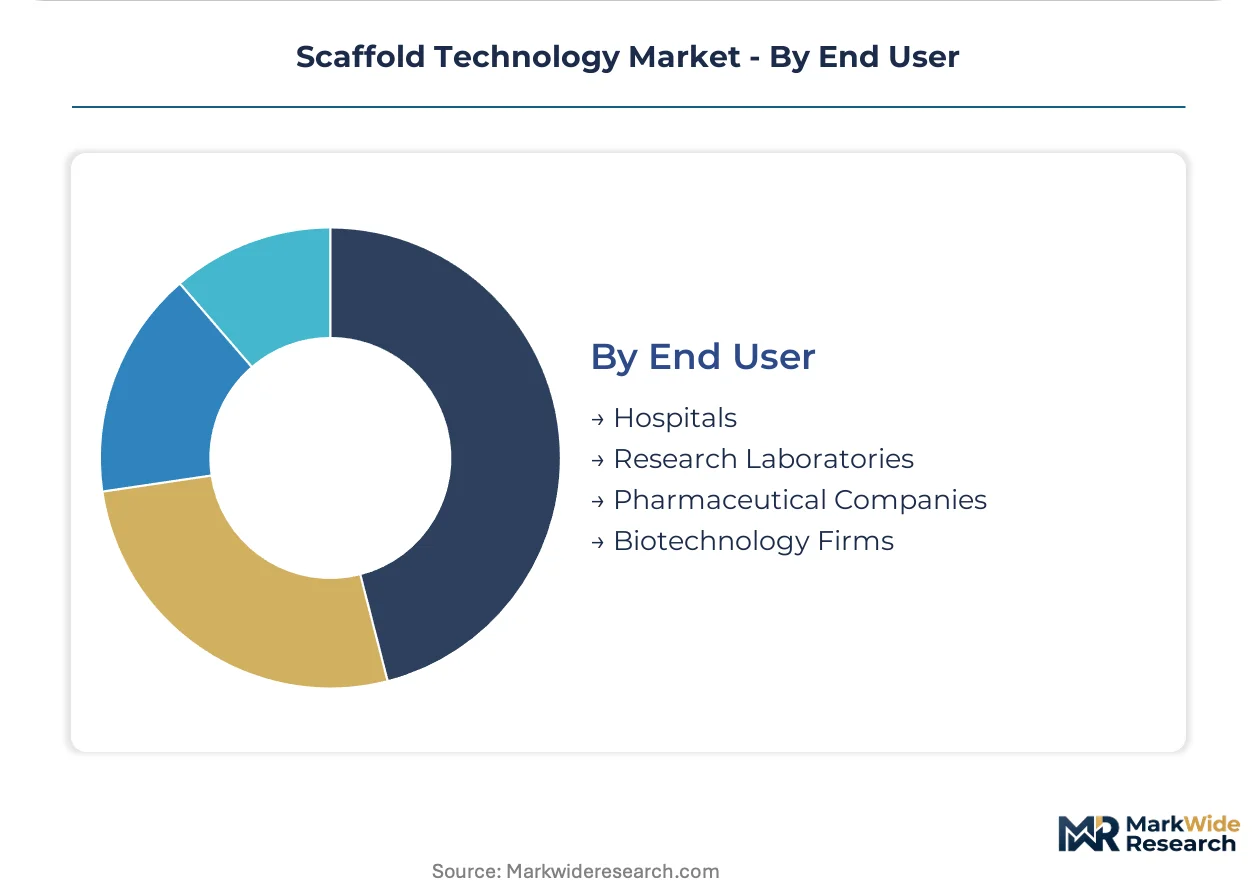
End User:
Procurement scale and specification authority fragment across institutional categories with divergent budget cycles.
- Research Laboratories:United States National Institutes of Health grant-funded projects drive direct material sourcing agreements independent of traditional distributors. Stanford, Johns Hopkins, and University of Tokyo negotiate separate equipment and consumable budgets.
- Hospitals:Academic medical centers consolidate vendor relationships through multi-year scaffold supply agreements. FDA breakthrough device designation criteria accelerate validation pathways for patient-specific implants.
- Pharmaceutical Companies:Toxicology departments contract for organ-on-chip integration with microfluidic scaffold architecture.
- Biotechnology Firms:Cell therapy developers procure GMP-compliant scaffolds for clinical manufacturing.
Research laboratories absorb the bulk of installed capacity; hospitals are gaining share fastest through orthopedic adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers and contract research organizations concentrate scaffold procurement volumes, while European REACH compliance costs redirect manufacturing investment toward known-material modifications.
United States
FDA breakthrough device designation criteria accelerate validation pathways for patient-specific orthopedic implants. Cleveland Clinic and Massachusetts General Hospital pilot 4D bioprinting systems for cartilage defect repair. Stanford and Johns Hopkins laboratories unbundle scaffold purchases from full-service cell culture contracts, negotiating direct material sourcing agreements.
Germany
EMA Medical Device Regulation Article 117 drug-device interface rules force synchronization of premarket evidence packages with FDA requirements. ECHA REACH substance registration mandates exhaustive supply chain chemical disclosure for novel hydroxyapatite composites. Bavarian orthopedic implant producers consolidate supplier audits under unified quality management systems.
Japan
PMDA harmonization with ICH guidelines simplifies scaffold market entry for Western manufacturers. METI funding supports organ-on-chip integration with microfluidic architecture for pharmaceutical toxicology applications. Tokyo and Osaka research clusters drive biomimetic structural environment requirements for organoid systems.
China
NMPA updated guidance on 3D-printed medical devices compresses commercialization timelines for domestic scaffold fabricators. MIIT industrial policy prioritizes bioresorbable polymer scale-up through electrospinning manufacturing improvements. Yangtze River Delta biotech parks attract cell therapy developers procuring GMP-compliant substrates.
India
CDSCO regulatory alignment with ICH guidelines reduces entry barriers for multinational scaffold suppliers. PLI scheme incentives target medical device component manufacturing including biocompatible polymer precursors. Maharashtra and Karnataka biotechnology corridors house emerging contract research organizations driving clinical adoption.
Scaffold Technology Market Vendor Landscape
United States producers anchor the premium instrumentation tier; European specialists hold dominant positions in high-purity reagent supply chains. The vendor base stratifies across analytical instrumentation conglomerates, diversified life science suppliers, and focused scaffold fabricators. Three archetypes prevail: diversified laboratory equipment providers leveraging cross-selling infrastructure; pure-play biomaterial specialists commanding technical depth; and contract manufacturers serving GMP clinical production requirements. Competitive dynamics center on strategic partnerships with academic medical centers and backward integration into polymer precursor supply.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. exemplifies the analytical infrastructure archetype supporting regulatory compliance workflows. Merck KGaA anchors the high-purity reagent supply chain position feeding scaffold fabrication processes. Corning Incorporated occupies the materials science translation niche, applying decades of glass and ceramic expertise to controlled-porosity substrate development.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Corning Incorporated |
| Becton Dickinson and Company |
| Tecan Trading AG |
| 3D Biotek LLC |
| Molecular Matrix Inc. |
| REPROCELL Inc. |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Cross-disciplinary biofabrication technician clusters in Massachusetts and Bavaria command premium compensation that widens pricing-tier spreads between GMP-certified clinical-grade scaffolds and research-use-only materials. Labor-cost differentials between these specialized workforce pools and emerging biotech corridors directly stratify end-product pricing.
Pricing Analysis
High-volume polymer scaffold transactions compress margins while decellularized ECM specialties sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated clinical implants from ISO 10993-compliant research substrates and basic electrospun mats. Pricing pressure stems from PLGA feedstock volatility eroding mid-tier fabricator margins. Academic laboratories exhibit highest price sensitivity through unbundled direct sourcing, while hospital procurement committees prioritize regulatory certification over unit cost.
Supply Chain Analysis
ISO 10993 and GMP qualification gating concentrates viable suppliers in the United States, Germany, and Japan where cleanroom infrastructure and regulatory expertise co-locate. Raw material flows draw from porcine tissue processing clusters in the United States Midwest, PLGA precursor manufacturing in China and South Korea, and high-purity reagent production in Switzerland. Single-source vulnerability pervades decellularized ECM sourcing where agricultural disease outbreaks threaten biological feedstock continuity. Distribution runs through academic laboratory e-commerce platforms and medical device distributor networks serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable 4D bioprinting architectures are displacing static porous scaffolds in cartilage defect repair applications, compressing validation-to-adoption timelines for legacy electrospun formats.
For Market Incumbents: Acquire electrospinning nozzle IP portfolios to secure freedom-to-operate in nanofiber manufacturing. Consolidate backward integration into PLGA precursor supply chains to buffer commodity volatility. Defensive positioning requires preemptive ISO 10993 testing investments before EMA-FDA harmonization tightens evidence requirements. For New Entrants and Emerging Players: Contract research organizations in India and Southeast Asia represent the most penetrable channel partner type for bypassing established distributor markups. White-space concentration sits with organ-on-chip microfluidic integration contracts from pharmaceutical toxicology departments. Direct-to-laboratory e-commerce platforms offer lowest customer acquisition friction versus hospital procurement committee navigation. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play biomaterial specialists possessing captive decellularized ECM supply given FDA breakthrough device designation acceleration. Long-term viability favors scaffold fabricators with GMP infrastructure and multi-jurisdictional regulatory dossiers. Monitor CDSCO harmonization progress as inflection signal for Indian market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursor Supply | Captive PLGA sourcing buffers mid-tier fabricators from commodity chemical volatility. |
| FDA Breakthrough Device Designation Pursuit | Accelerated validation pathways compress commercialization timelines for patient-specific orthopedic implants. |
| Academic Medical Center Partnership Consolidation | Multi-year supply agreements at Cleveland Clinic and Massachusetts General Hospital anchor revenue visibility. |
| Organ-on-Chip Microfluidic Integration Development | Pharmaceutical toxicology contracts from Stanford and Johns Hopkins open high-value application verticals. |
| ECHA REACH Compliance Infrastructure Investment | Exhaustive substance documentation capabilities defend European market access against regulatory exclusion. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance trajectories and EMA MDR Article 117 implementation timelines anchored the trend analysis, supplemented by interviews with scaffold fabrication executives, biomedical engineering professors at Johns Hopkins and Stanford, hospital purchasing committee members, GPO contracts managers, and CDSCO regulatory consultants. Secondary validation drew from FDA CDRH device databases, EMA public assessment reports, NIH RePORTER funding records, and ISO 10993 testing laboratory accreditation lists. Bottom-up vendor shipment estimates triangulated against top-down academic procurement budget allocations.
Segment-weighting across scaffold type, application, material chemistry, and end-user institution shaped the analytical framework throughout the forecast period. Modeled dimensions included polymer versus bio-scaffold degradation kinetics, tissue engineering versus regenerative medicine deployment settings, PLGA versus collagen versus hydroxyapatite feedstock categories, and research laboratory versus hospital versus pharmaceutical company procurement authority. CAGRs derived from installed capacity expansion rates, unbundled procurement trend velocity, and 4D bioprinting pilot adoption curves.
Caveats apply where FDA-EU MDR harmonization delays or PLGA feedstock supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding cleanroom capex deployment continuity and academic funding stability. A model refresh is warranted upon material change in CDSCO regulatory alignment progress or breakthrough device designation approval rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Construction Equipment Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Shield Machines Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Case Erectors Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Backhoe Bucket Market