
 Electric Power Tools Market | 2026-2036
Electric Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Power Tools Market Foresight
China is reshaping competitive dynamics in electric power tool manufacturing through expanded domestic capacity and supply chain localization. Robert Bosch GmbH leverages its German engineering heritage and brushless motor patents to sustain premium positioning across European and Asian channels. Makita Corporation anchors its market presence through deep cordless lithium-ion portfolios and professional-grade durability standards. Techtronic Industries Co. Ltd. competes aggressively on cost-engineered platforms while extending distribution reach through retail partnerships in North America and Australia.
Electric power tools are electromechanical devices converting electrical energy into rotational or reciprocating mechanical force, typically operating at voltages from 12V to 120V depending on application intensity and mobility requirements. These tools perform cutting, drilling, grinding, fastening, and surface preparation tasks across construction, manufacturing, and maintenance workflows where pneumatic or manual alternatives prove insufficient. The cordless power source segment commands the fastest expansion trajectory as lithium-ion energy density improvements enable performance parity with corded equivalents. Brushless technology dominates margin pools through reduced friction wear, higher efficiency conversion, and extended operational lifespan compared to conventional brushed architectures. Drill and saw product categories occupy the largest volume positions, though grinder adoption accelerates in metal fabrication and infrastructure refurbishment applications.
OSHA workplace safety mandates in the United States and CE marking requirements under EU machinery directives compel manufacturers to integrate vibration damping, kickback control, and electromagnetic compatibility safeguards into product designs. China's GB standards and MIIT energy efficiency regulations shape domestic certification pathways while influencing export specifications for tools manufactured in Shenzhen and Suzhou industrial clusters. India's BIS quality enforcement and construction sector labor protection rules are tightening market access for uncertified imports. Stakeholders must monitor battery chemistry substitution timelines, regional certification divergence, and professional versus DIY channel mix shifts to calibrate portfolio investments and geographic prioritization.
Market Dynamics
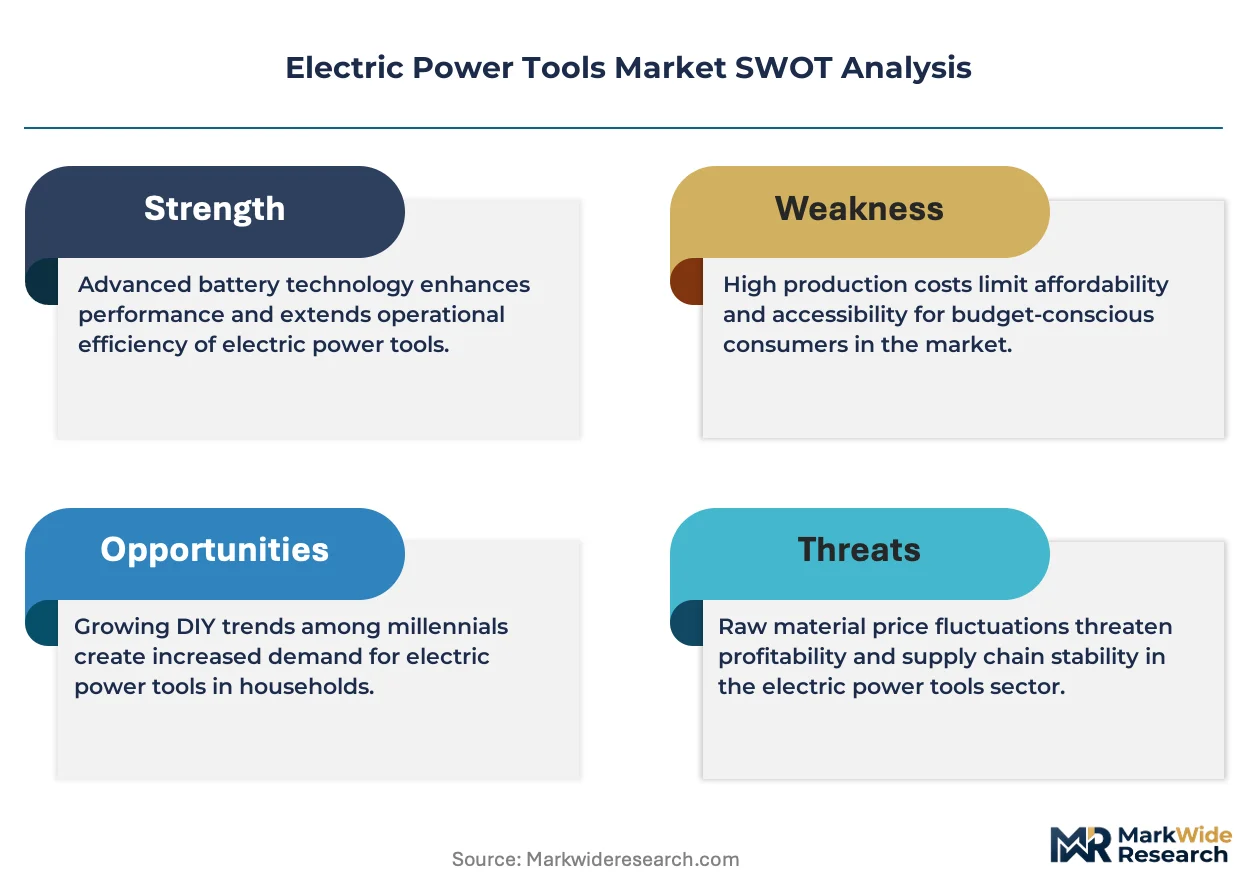
Cordless lithium-ion platforms are compressing replacement cycles and redistributing margin pools from motor manufacturers toward battery cell suppliers, while Chinese production scale forces pricing recalibration across mid-tier professional segments.
Growth Catalysts
- Brushless motor architectures:Professional construction crews in Germany and Japan specify brushless drives for reduced downtime, extending tool lifespan and compressing total cost of ownership calculations.
- OSHA silica exposure rules:Dust extraction mandates on US job sites are pulling integrated vacuum systems into grinder and rotary hammer specifications, expanding attachment revenue streams.
- Shenzhen-Suzhou manufacturing clusters:Domestic Chinese supply chain density enables 40% faster prototype-to-production cycles for cordless platforms targeting Southeast Asian infrastructure buildouts.
Market Restraints
- Cobalt and lithium carbonate volatility:Battery raw material price swings compress gross margins on cordless tool portfolios, forcing hedging costs onto manufacturers without captive mining contracts.
- Single-source cell dependency:Concentration of high-NCM cathode production in China's Fujian and Jiangsu provinces creates supply vulnerability for European and North American assemblers.
- Brushed motor obsolescence ceiling:Remaining corded tool demand in price-sensitive DIY channels limits full portfolio conversion, stranding R&D investments in legacy form factors.
Strategic Opportunities
- India's construction labor protection expansion:BIS enforcement of vibration exposure limits is opening certified professional-grade demand previously captured by informal grey-market imports.
- Battery-as-a-service models:Fleet operators in Australian mining and commercial facilities are piloting subscription-based cell replacement, decoupling capital expenditure from utilization rates.
- CE marking machinery directive updates:Stricter electromagnetic compatibility testing is fragmenting certification pathways, creating first-mover advantage for manufacturers with pre-validated component libraries.
Industry Challenges
- Power electronics engineering scarcity:Shortage of brushless motor control firmware specialists is delaying next-generation drive launches and inflating compensation costs in Shenzhen and Stuttgart R&D centers.
- Multi-jurisdiction certification parallelism:Divergent testing protocols between UL standards for North America and GB standards for China are extending product launch timelines and duplicating validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Power Tools Market |
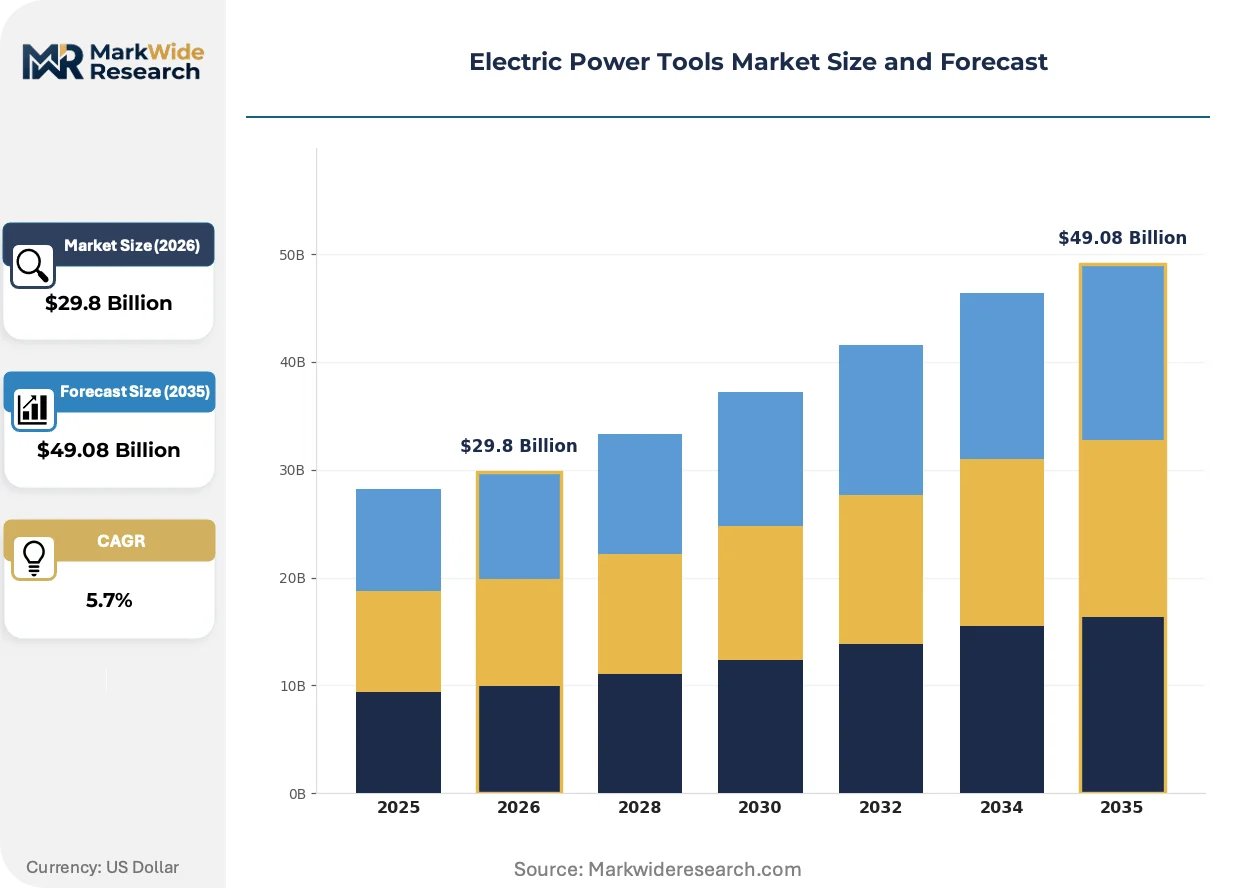
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $49.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Grinders, Sanders Power Source: Corded, Cordless, Hybrid, Electric End User: Industries, Construction, DIY Enthusiasts, Maintenance Technology: Brushless, Lithium-Ion, Brush, Standard |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Techtronic Industries Co. Ltd., Makita Corporation, Hilti Corporation, Apex Tool Group, Atlas Copco AB, Ingersoll Rand, Snap-on Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Power Tools Market Shifts & Advancements
Tool intelligence layers and energy management systems are redefining performance benchmarks and aftermarket revenue architecture across professional-grade portfolios.
Smart torque sensing and kickback mitigation algorithms are rendering obsolete manual clutch calibration and operator-dependent safety margins. Commercial contractors in Japan and Germany are specifying these intelligent drives for liability reduction on high-volume fastening operations. The technology is compressing training requirements while enabling usage-based warranty pricing models previously impractical at fleet scale.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon elimination from battery thermal management systems. Manufacturers serving European professional channels are redesigning pack enclosures around phase-change materials and liquid cooling loops. The compliance burden falls heaviest on high-discharge grinder and demolition tool categories where thermal runaway risk concentrates.
Rental and leasing channels are capturing share from direct equipment purchase among North American commercial construction fleets. Home Depot and United Rentals are expanding cordless tool subscription tiers with bundled maintenance and rapid cell exchange. The shift is most pronounced in commercial renovation verticals where project duration uncertainty favors operational expense treatment over capital deployment.
Electric Power Tools Market Segmentation
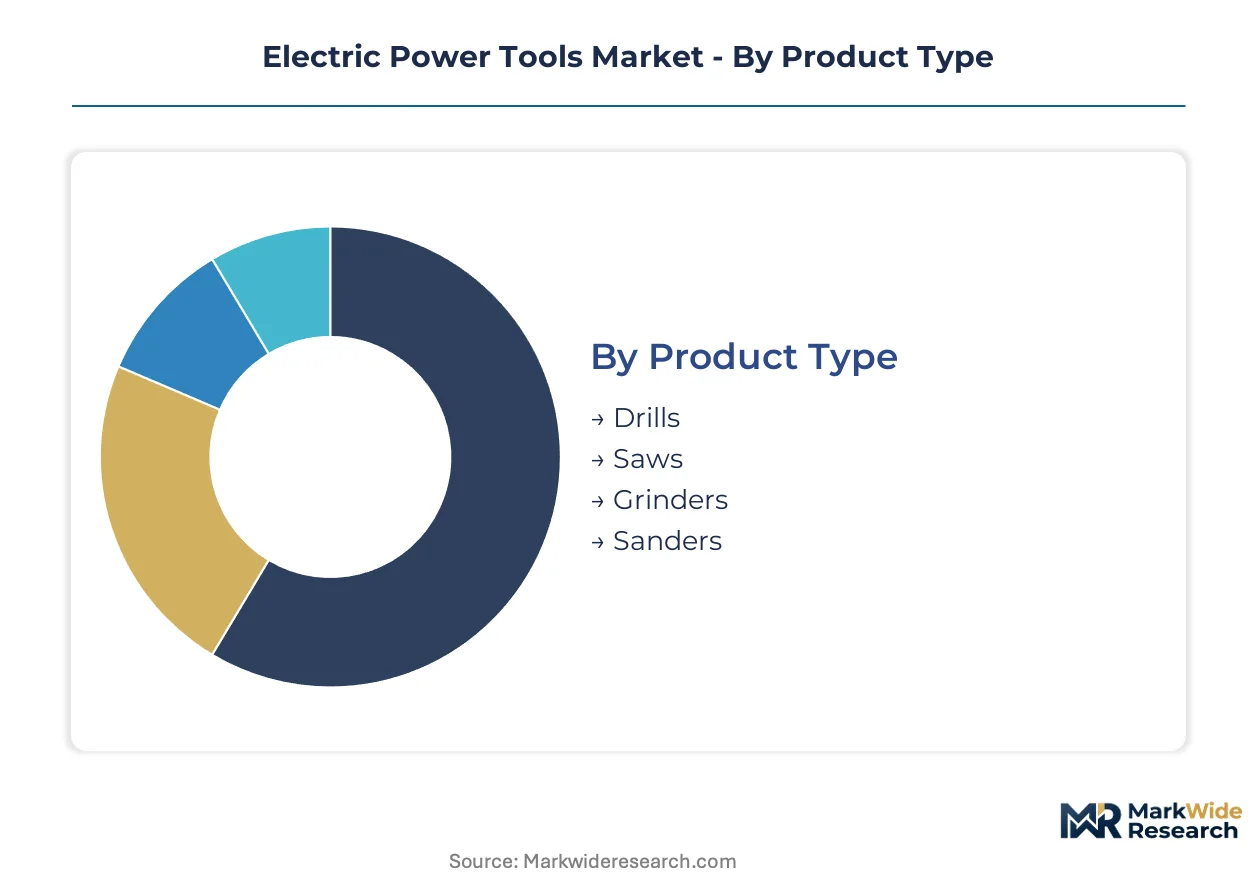
Electric power tools fragment across four structural dimensions that determine procurement patterns, margin architecture, and competitive positioning. Product type and power source capture the bulk of revenue concentration, while technology tier and end-user channel shape pricing power and replacement cycle velocity.
Product Type:
Mature categories dominate volume positions, though emerging applications in infrastructure refurbishment are redistributing growth trajectories across the portfolio.
- Drills:Rotary and hammer drill configurations serve fastening and masonry penetration tasks across residential construction and facility maintenance workflows. Demand concentrates in China's tier-one cities where high-rise residential development sustains fleet procurement from domestic manufacturers.
- Saws:Circular, reciprocating, and miter saw platforms execute dimensional lumber and metal stock cutting with blade-speed optimization for material-specific performance. German commercial contractors specify cordless circular saws for timber framing operations, prioritizing runtime consistency over upfront cost.
- Grinders:Angle grinder demand accelerates in metal fabrication and surface preparation applications.
- Sanders:Orbital and belt sander volumes concentrate in furniture manufacturing and finishing trades.
Drills retain volume leadership; grinders hold the steepest expansion curve.
Power Source:
Cost tier stratification separates capital-intensive cordless platforms from maintenance-heavy corded alternatives, with hybrid architectures occupying a narrowing transitional position.
- Cordless:Lithium-ion battery packs enable mobility-dependent operations on construction sites lacking reliable grid access. Japanese professional crews specify 18V and 36V platforms for infrastructure projects, where OSHA-compliant dust extraction integration drives attachment revenue.
- Corded:Continuous AC power delivery sustains high-torque applications in stationary workshops and manufacturing cells. China's Shenzhen-Suzhou industrial clusters produce cost-optimized corded grinders for Southeast Asian metalworking shops.
- Hybrid:Dual-power architectures accommodate grid-variable environments in emerging market construction.
- Electric:Dedicated electromechanical drives serve specialized industrial automation integrations.
Corded tools retain volume leadership in price-sensitive DIY channels; cordless platforms are climbing the fastest across professional segments.
End User:
Customer type determines specification intensity, with professional channels demanding durability certification and fleet interoperability that DIY purchasers disregard.
- Industries:Manufacturing and assembly line operations specify fixed-mount and robotic-integrated power tools with MTBF documentation and predictive maintenance telemetry. German automotive plants source brushless assembly drivers with torque-feedback logging for quality traceability.
- Construction:Commercial and residential building crews prioritize runtime, drop resistance, and multi-tool battery compatibility. Australian mining contractors pilot battery-as-a-service subscriptions to decouple capital expenditure from project duration uncertainty.
- DIY Enthusiasts:Home improvement purchasers prioritize purchase price over operational lifespan.
- Maintenance:Facility management operations demand reliability documentation for insurance and liability compliance.
Construction retains volume leadership; industries hold the steepest expansion curve as automation integration accelerates.
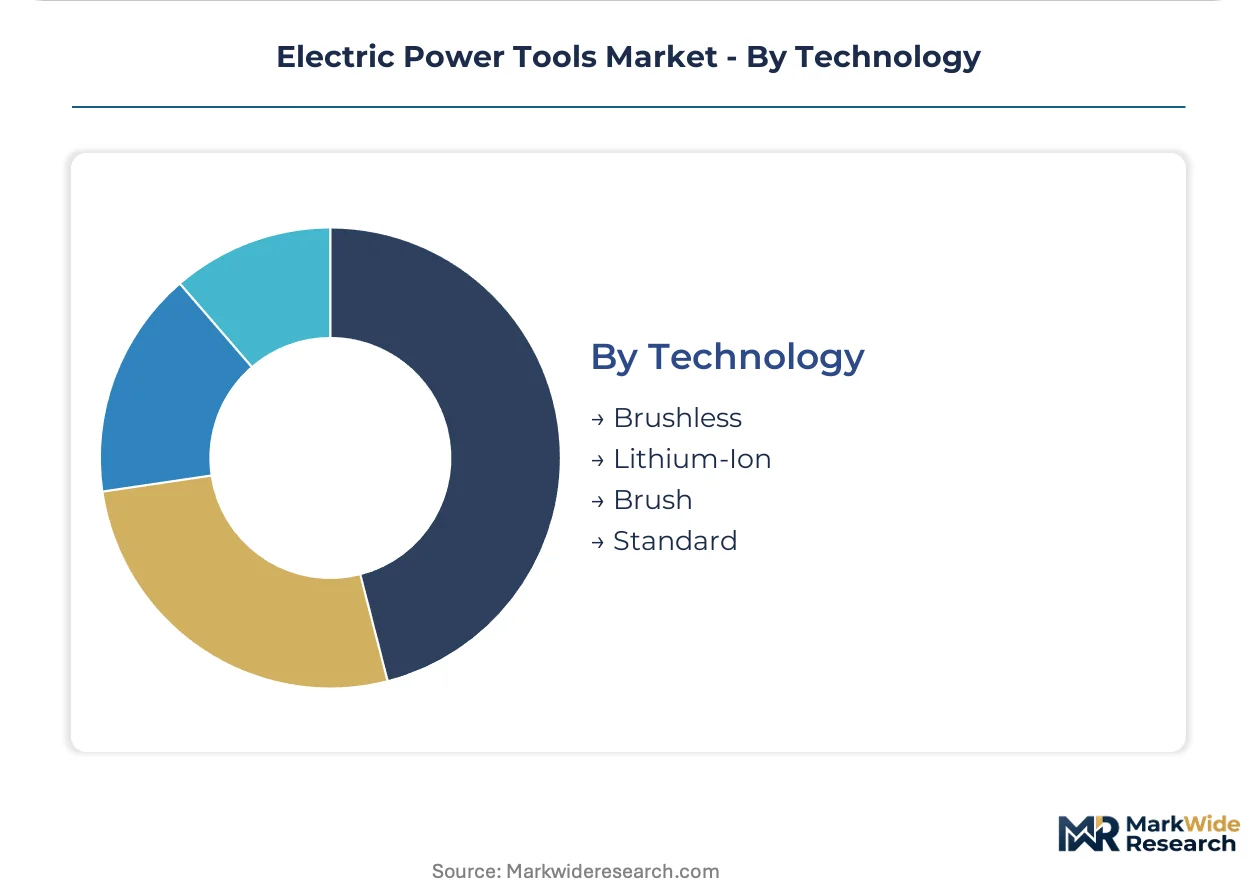
Technology:
Margin pools concentrate in advanced motor and battery architectures, with legacy platforms serving price-anchored market tiers.
- Brushless:Electronic commutation eliminates brush friction wear, extending operational lifespan and enabling compact form factors. Makita and Robert Bosch leverage German and Japanese engineering patents to sustain premium positioning in professional channels.
- Lithium-Ion:High energy-density cells deliver runtime parity with corded equivalents at reduced pack weight. China's MIIT energy efficiency regulations and GB standards shape domestic certification pathways while influencing export specifications.
- Brush:Mechanical commutation architectures persist in entry-tier corded tools.
- Standard:Baseline electromechanical configurations serve cost-minimized replacement demand.
Brush motors retain volume leadership in emerging market DIY channels; brushless architectures are gaining share fastest in professional-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters in Shenzhen and Suzhou supply over half of global cordless tool output, while German engineering centers and Japanese precision motor facilities anchor premium-tier production. Domestic infrastructure buildouts and localized certification regimes are redrawing procurement patterns across major economies.
United States
Commercial construction crews in Texas and Florida are upgrading cordless fleets to comply with OSHA silica exposure mandates on grinding and demolition tasks. The Department of Labor enforces dust extraction integration requirements that expand attachment revenue streams for grinder specifications. Milwaukee and Chicago industrial distributors serve as primary procurement channels for professional-grade brushless platforms.
Germany
Automotive assembly plants in Bavaria and Baden-Württemberg specify torque-feedback logging drivers for quality traceability in electric vehicle manufacturing. CE marking machinery directive updates under EU F-Gas Regulation are accelerating hydrofluorocarbon elimination from battery thermal management systems. Stuttgart engineering centers concentrate brushless motor control firmware development for next-generation professional tools.
China
High-rise residential development in Shanghai and Beijing sustains fleet procurement of domestically manufactured rotary and hammer drills. MIIT energy efficiency regulations and GB standards shape certification pathways for tools produced in Shenzhen-Suzhou industrial clusters. Domestic manufacturers compress prototype-to-production cycles to capture Southeast Asian infrastructure buildout demand.
Japan
Professional construction crews in Tokyo and Osaka specify 18V and 36V cordless platforms for infrastructure projects requiring OSHA-compliant dust extraction integration. METI industrial standards enforce electromagnetic compatibility safeguards that influence regional product design specifications. Nagoya manufacturing facilities concentrate precision motor assembly for premium-tier export markets.
India
BIS enforcement of vibration exposure limits in Maharashtra and Gujarat is opening certified professional-grade demand previously captured by informal grey-market imports. Construction labor protection expansion under central government directives tightens market access for uncertified equipment. Mumbai and Ahmedabad distribution hubs are pivoting toward compliant brushless inventory to serve commercial building sector procurement.
Electric Power Tools Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in motor control firmware and battery cell supply. The vendor base separates into three functional layers: diversified industrial conglomerates with captive distribution, pure-play power tool specialists with deep cordless portfolios, and contract manufacturers serving private-label retail channels. Consolidation pressure concentrates in the mid-tier professional segment where Chinese production scale forces pricing recalibration. Dominant competitive moves include backward integration into battery cell supply and geographic expansion through regional certification pre-validation.
Among diversified industrial conglomerates, Robert Bosch GmbH and Stanley Black & Decker occupy positions anchored by multi-decade brand equity and captive distribution networks. Makita Corporation exemplifies the pure-play specialist archetype with concentrated investment in professional-grade durability standards. Techtronic Industries Co. Ltd. represents the cost-engineered platform approach, competing through retail partnership density in North America and Australia.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Techtronic Industries Co. Ltd. |
| Makita Corporation |
| Hilti Corporation |
| Apex Tool Group |
| Atlas Copco AB |
| Ingersoll Rand |
| Snap-on Incorporated |
| Others |
Supply & Pricing Matrix
Shenzhen-Suzhou manufacturing clusters concentrate lithium-ion cell assembly and brushless motor production, compressing prototype-to-production cycles and forcing margin recalibration across mid-tier professional cordless platforms. This supply density enables Chinese domestic manufacturers to undercut European and North American assemblers on equivalent specifications, redistributing pricing power toward battery cell suppliers and away from tool integrators.
Pricing Analysis
OSHA silica exposure rules dictate the pricing tier structure by mandating dust extraction integration on grinder and rotary hammer specifications, bifurcating professional-grade procurement from uncertified grey-market alternatives. Three-tier pricing structure across premium, standard, and economy levels separates brushless cordless platforms with METI-compliant electromagnetic safeguards from brushed corded tools serving price-sensitive DIY channels. Cost compression in the mid-tier professional segment intensifies because Chinese production scale forces faster replacement cycles and bundled battery-as-a-service subscriptions. DIY enthusiasts exhibit highest price sensitivity, prioritizing upfront purchase cost over operational lifespan, while Australian mining contractors demonstrate lowest sensitivity through operational-expense treatment of fleet procurement.
Supply Chain Analysis
Export-control restrictions on high-NCM cathode production technology limit non-Chinese manufacturers' access to advanced cell chemistries, constraining European and North American assemblers' ability to replicate Shenzhen-Suzhou energy density improvements. Supply concentrates in China, South Korea, and Japan for lithium-ion cells, with brushless motor control firmware development anchored in Stuttgart and Nagoya engineering centers. Raw material dependencies on cobalt, lithium carbonate, and rare-earth magnets expose margins to commodity price volatility. Single-source cell vulnerability from Fujian and Jiangsu province concentration creates structural supply risk. Distribution runs through industrial distributors, rental-leasing channels, and retail partnerships serving professional construction fleets and DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery platform interoperability is emerging as the decisive ecosystem battleground, with multi-tool battery compatibility determining fleet procurement loyalty and aftermarket attachment revenue capture across professional construction segments.
For Market Incumbents: Build certification moats by pre-validating component libraries against CE marking machinery directive updates and OSHA silica compliance pathways, compressing rival launch timelines. Secure captive supply of high-NCM cathode cells through backward integration or long-term offtake agreements with Fujian and Jiangsu producers to insulate margins from raw material volatility. Defend against Chinese cost-engineered platforms by embedding predictive maintenance telemetry and usage-based warranty pricing that grey-market imports cannot replicate. For New Entrants and Emerging Players: India's BIS-certified professional-grade demand represents the most penetrable entry point, as vibration exposure enforcement displaces informal imports in Maharashtra and Gujarat commercial building markets. Southeast Asian infrastructure buildouts offer secondary white-space, with domestic Chinese manufacturers prioritizing higher-margin cordless platforms over cost-optimized corded grinders for metalworking shops. Partner with Mumbai and Ahmedabad distribution hubs pivoting toward compliant inventory to secure channel access without captive retail infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among battery-as-a-service fleet operators and rental-leasing channel partners, offering superior cash-flow quality against transactional tool sales. Acquisition targets should display vertical integration into brushless motor control firmware or pre-validated certification libraries that accelerate multi-jurisdiction launches. Monitor cobalt and lithium carbonate price trajectories as inflection indicators; sustained volatility would compress cordless platform margins and accelerate consolidation toward cell-captive assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Multi-tool battery compatibility locks fleet procurement loyalty and expands attachment revenue across grinder and saw categories. |
| Backward Integration into Cell Supply | Captive cathode sourcing from Fujian and Jiangsu insulates margins from cobalt and lithium carbonate price swings. |
| Certification Pre-Validation Investment | Pre-tested component libraries against CE marking and OSHA requirements compress rival product launch timelines. |
| Battery-as-a-Service Model Deployment | Subscription-based cell replacement converts capital expenditure to operational expense for Australian mining contractors. |
| Smart Torque Sensing Integration | Intelligent drive algorithms enable usage-based warranty pricing and liability reduction for Japanese commercial fastening operations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industrial cluster production disclosures to calibrate market size and growth trajectories. Primary interviews engaged product development executives at brushless motor engineering centers, procurement leads at commercial construction fleets, aftermarket service heads at industrial distributors, and regulatory affairs specialists navigating multi-jurisdiction certification. Secondary validation drew from OSHA enforcement records, MIIT energy efficiency disclosures, BIS quality enforcement bulletins, and SEC filings of publicly traded tool manufacturers. Bottom-up segment sizing triangulated against top-down industrial production indices and channel shipment estimates.
Forecast inputs incorporate cordless versus corded platform mix shifts, brushless motor penetration curves across professional and DIY channels, and regional certification divergence timelines across the analysis window. Segmentation dimensions modeled include product type, power source architecture, technology tier, and end-user channel, with cross-tabulation against geographic production cluster capacity and infrastructure investment cycles. CAGRs derived from fitted growth curves applied to validated base-year estimates, with sensitivity testing against battery chemistry substitution scenarios and raw material price trajectories.
Practitioners should monitor cobalt and lithium carbonate volatility, CE marking directive update implementation schedules, and BIS enforcement intensity for early signals of forecast deviation. Forecasts reflect assumptions regarding continued lithium-ion energy density improvement and sustained Chinese manufacturing cluster dominance. Material shifts in export-control regimes restricting cathode technology transfer, or abrupt regulatory divergence between UL and GB testing protocols, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Measuring Wheels Market
Tools
Global Swaging Machine Market
Tools
Global DC Torque Tool Market
Tools
Cutting Tools Market
Tools
Nut Runner Market
Tools
Global Metal Forming Machine Tools Market
Tools
End Milling Machine Market
Tools
Digital Laser Levels Market
Tools
Aluminum Folding Ladders Market
Tools
Drill Set Market
Tools
Forging Press Market
Tools
Digital Levels Market
Tools
Welding Products Market
Tools
Construction Nails Market
Tools
China Power Tools and Hand Tools Market
Tools
Fatigue Testing Machine Market