
 Construction Equipment Attachments Market | 2026-2036
Construction Equipment Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Equipment Attachments Market Insights
The capital-intensity divergence between full-line OEMs and specialized attachment manufacturers is rotating competitive advantage toward players with captive metallurgy and forging capacity. Caterpillar leverages in-house steel processing and global dealer networks to sustain attachment-to-machine bundling power. Komatsu anchors its position through integrated hydraulic system design that optimizes attachment-machine interface performance. Develon competes on agile manufacturing scale in compact utility attachments, particularly for Asian contractor fleets.
Construction equipment attachments are engineered steel assemblies—typically alloy or high-strength carbon steel with hardened cutting edges, wear plates, and hydraulic coupler systems—designed to extend base machine functionality across excavation, demolition, material handling, and grading tasks. Heat treatment processes including induction hardening and through-hardening determine service life under abrasive conditions, with Rockwell hardness ratings of 45-55 HRC common for ground-engaging components. Buckles and hammers dominate product-type revenue due to universal applicability across machine classes, while grapple attachments for material handling represent the fastest-growing product category driven by recycling and waste-stream recovery demand. Application segmentation shows excavation maintaining volume leadership, though demolition attachments command premium pricing through specialized metallurgy and reinforced structural designs.
EPA Tier 4 Final and EU Stage V emissions standards shape equipment replacement cycles, directly expanding attachment demand as contractors modernize fleets with quick-coupler-compatible machines. OSHA excavation safety regulations and ISO 13031 attachment interface standards influence product certification requirements and market access conditions in North America and Europe. Stakeholders must monitor quick-coupler standardization progress across OEM platforms, as interoperability investments will determine aftermarket attachment viability and rental fleet procurement decisions.
Market Dynamics
Quick-coupler standardization across OEM platforms is restructuring attachment procurement, as contractors demand interchangeability between machine brands to maximize fleet utilization and reduce downtime during tool changes.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Fleet turnover in the United States accelerates replacement of pre-emission machines with quick-coupler-compatible units, expanding the installed base for modern attachments.
- Urban densification:Infrastructure rehabilitation across aging metropolitan cores in Germany and Japan drives demolition and excavation attachment deployment for confined-space operations.
- Recycling mandates:EU waste-stream recovery regulations elevate grapple attachment demand for material sorting and construction debris processing facilities.
Market Restraints
- Alloy steel price volatility:Nickel and chromium input cost swings compress margin stability for forged component manufacturers dependent on spot market sourcing.
- Foundry capacity concentration:Specialized heat-treatment infrastructure clusters in China's industrial heartland, creating geographic supply vulnerability for Western attachment producers.
- Hydraulic interface incompatibility:Proprietary coupler designs from major OEMs fragment aftermarket attachment interoperability and limit rental fleet standardization.
Strategic Opportunities
- Indian infrastructure buildout:National highway and metro expansion projects create underpenetrated demand for compact excavator attachments among emerging contractor fleets.
- Electrification convergence:Battery-powered base machines and low-noise hydraulic systems open municipal and residential applications previously restricted by emissions and noise ordinances.
- Rental channel digitization:Equipment-as-a-service platforms enable attachment subscription models, reducing capital barriers for mid-tier contractors.
Industry Challenges
- ISO 13031 certification timelines:Attachment interface standardization delays prolong product validation cycles and postpone market entry for innovative coupling designs.
- Induction hardening technician scarcity:Specialized metallurgical expertise gaps constrain quality assurance throughput for heat-treated wear components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Equipment Attachments Market |
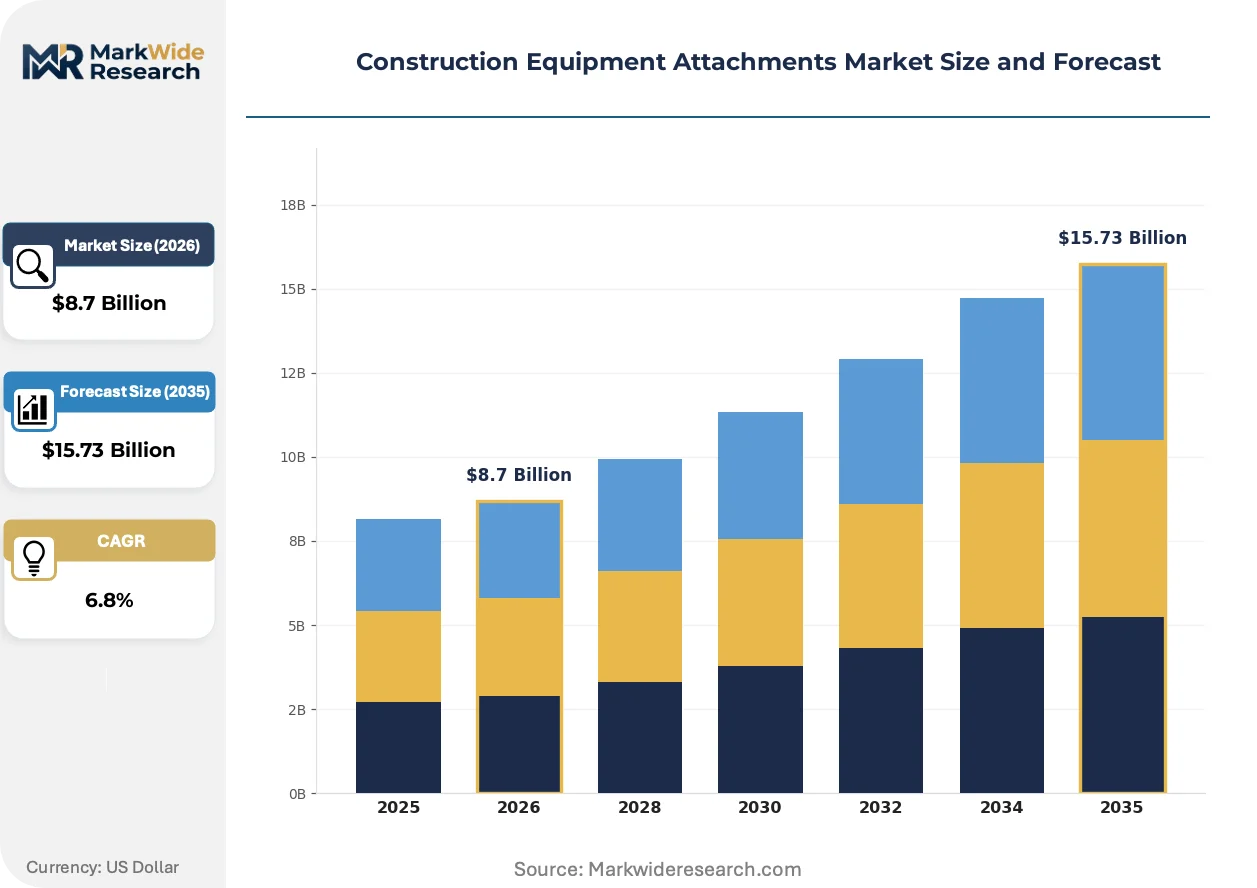
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket, Grapple, Auger, Blade, Hammer, Ripper Application: Excavation, Demolition, Material Handling, Landscaping, Utility, Drilling End User: Contractors, Rental Companies, Mining Operators, Municipal Agencies, Civil Engineers, Road Builders Distribution Channel: Direct Sales, Dealers, Online Platforms, OEMs, Distributors, Rental Providers |
| Companies Covered | Caterpillar, Komatsu, Volvo Construction Equipment, Hitachi Construction Machinery, JCB, Liebherr Group, Develon, CNH Industrial, Sany Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Equipment Attachments Market Trends and Innovations
Attachment intelligence and materials science are converging to extend service intervals and enable predictive maintenance, shifting value capture from hardware sales toward lifecycle performance guarantees.
Sensor-embedded ground-engaging tools are fragmenting traditional maintenance scheduling. Load-cell instrumentation and edge-wear monitoring transmit real-time abrasion data to fleet management systems. Large demolition contractors in Japan and Germany are adopting these systems fastest, compressing the replacement parts aftermarket by enabling condition-based rather than calendar-based service.
EU Stage V emissions enforcement is tightening hydraulic system specifications for attachment-machine interfaces. Auxiliary flow requirements for high-power tools now trigger engine derating protocols that reduce base machine productivity. European rental fleets are responding by segregating high-flow attachment inventory to dedicated machine pools, fragmenting fleet deployment flexibility.
Contractor buying committees are consolidating attachment procurement under centralized fleet managers, displacing decentralized site-level purchasing. Large infrastructure developers in the United States now mandate approved-vendor lists with interoperability certification requirements. This concentration shifts volume toward full-line OEM bundling and squeezes independent attachment specialists on specification compliance costs.
Construction Equipment Attachments Market Segmentation
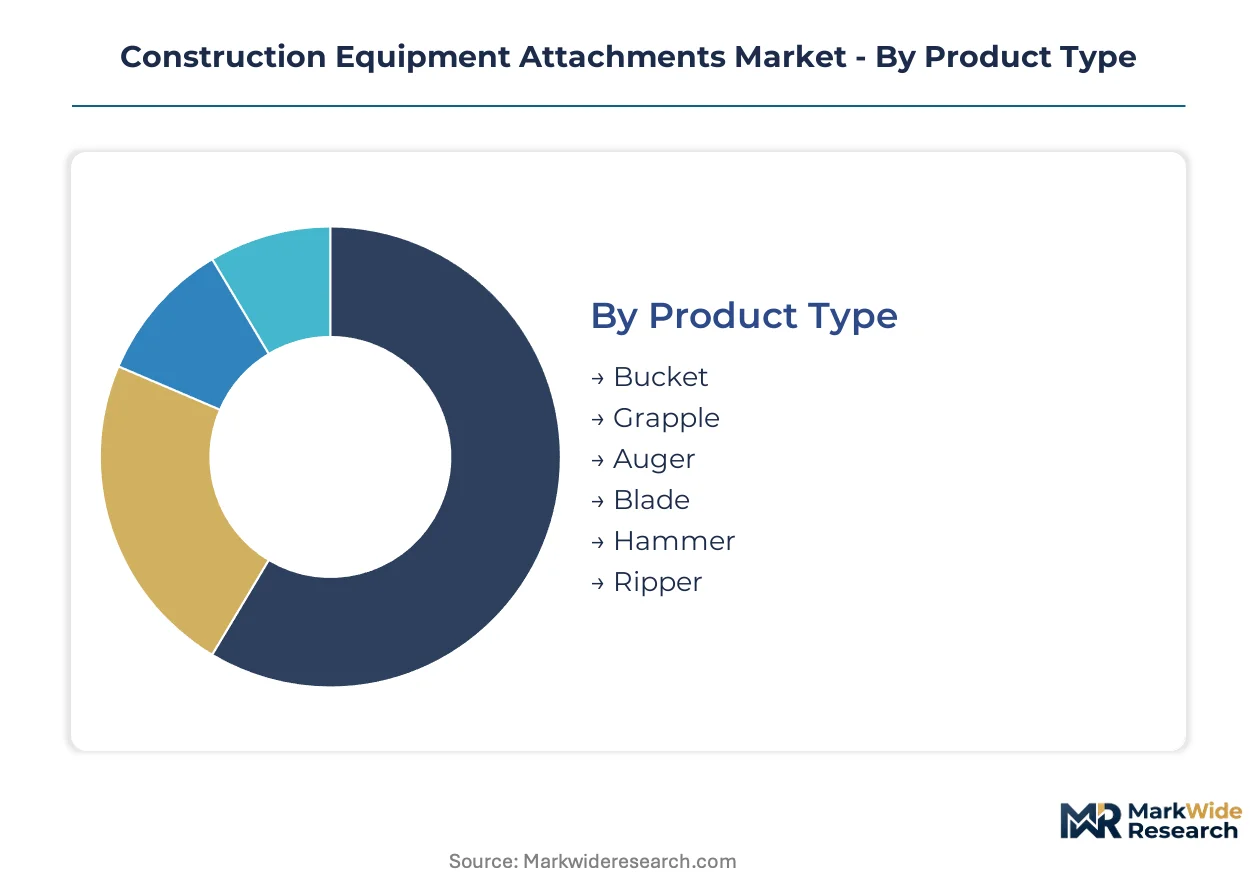
Attachment procurement patterns diverge sharply across product categories and buyer types, with rental channel consolidation and OEM bundling power reshaping how segments capture value. Understanding these flow dynamics exposes where specialized manufacturers retain pricing leverage versus where volume concentrates through integrated supply relationships.
Product Type:
Channel mix varies by attachment complexity—standardized buckets and blades flow heavily through dealer networks and rental fleets, while specialized demolition tools concentrate in direct OEM bundling and contractor-direct procurement.
- Bucket:Universal excavation and loading tool fabricated from high-strength carbon steel with hardened cutting edges rated 45-55 HRC. Demand clusters in United States highway rehabilitation and German urban densification projects where quick-coupler compatibility drives replacement cycles.
- Grapple:Hydraulic or mechanical material handling attachment with multiple tine configurations for waste recovery and sorting operations. Recycling mandates across EU member states and Japanese demolition contractors are accelerating adoption fastest among all product types.
- Auger:Spiral drilling attachment for utility pole setting and foundation work, common in compact excavator configurations.
- Blade:Grading and leveling attachment ranging from dozer blades to tilt-rotator units for precision finish work.
- Hammer:Hydraulic breaker for rock fragmentation and concrete demolition, requiring high-flow auxiliary circuits.
- Ripper:Ground-engaging tool for fracturing compacted substrates in mining and heavy civil applications.
By volume, Bucket leads. By growth pace, Grapple is expanding most quickly.
Application:
Cost tier stratification separates premium demolition and drilling attachments—where specialized metallurgy commands price premiums—from standard excavation and landscaping tools competing on manufacturing scale.
- Excavation:Foundation digging, trenching, and earthmoving operations using buckets and augers. United States infrastructure rehabilitation and Chinese metro expansion sustain the largest installed base of compatible machines.
- Demolition:Structural dismantling and debris processing employing hammers, grapples, and specialized cutting attachments. Japanese and German contractors pay premium pricing for reinforced designs meeting confined-space safety protocols.
- Material Handling:Loading, sorting, and transporting bulk materials across construction debris and recycling streams.
- Landscaping:Grading, soil preparation, and vegetation management using compact machine-mounted tools.
- Utility:Trenching, pole setting, and pipeline installation requiring precision auger and bucket configurations.
- Drilling:Rock and substrate penetration for foundation piling and geotechnical applications.
Excavation dominates machine-hour utilization. Demolition generates the highest attachment revenue per base machine deployed.
End User:
Customer type determines specification authority—large rental companies and mining operators centralize procurement with interoperability mandates, while fragmented contractors respond to site-level availability and financing terms.
- Contractors:General and specialty construction firms purchasing attachments for owned equipment fleets. United States infrastructure developers increasingly mandate approved-vendor lists with ISO 13031 certification requirements.
- Rental Companies:Equipment-as-a-service providers standardizing quick-coupler platforms across mixed-brand fleets. European rental consolidation is concentrating volume toward full-line OEM bundling agreements.
- Mining Operators:Surface and underground extraction firms requiring extreme-duty ground-engaging tools with extended service intervals.
- Municipal Agencies:City and county governments procuring compact utility attachments for road maintenance and public works.
- Civil Engineers:Infrastructure design-build firms specifying attachment performance requirements for project delivery.
- Road Builders:Highway and pavement contractors deploying specialized cold planing and grading attachments.
Rental companies capture the steepest procurement volume growth. Contractors retain the largest absolute attachment inventory.
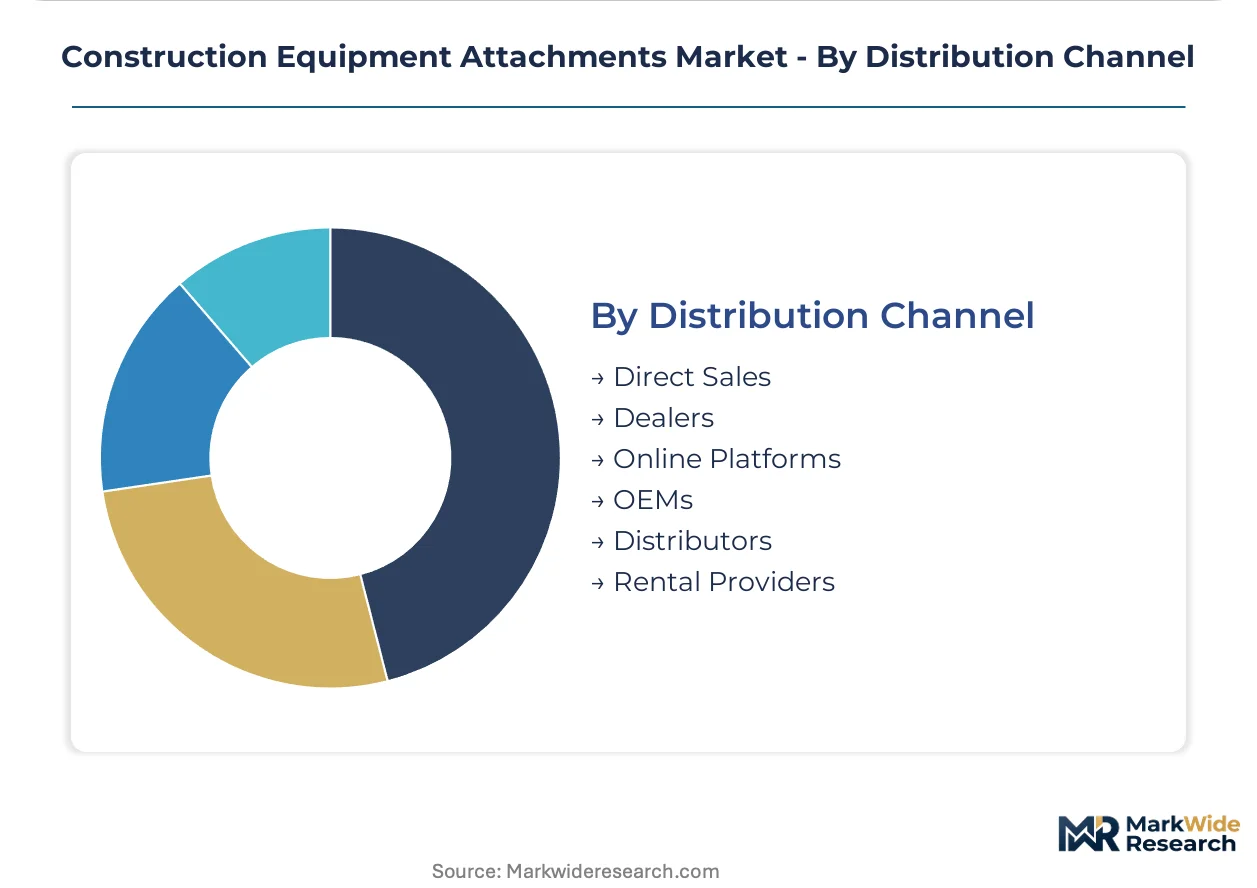
Distribution Channel:
Supply concentration in forged component manufacturing and heat-treatment infrastructure shapes channel economics, with OEM captive production and Chinese foundry clusters determining margin capture upstream.
- Direct Sales:Manufacturer-to-contractor transactions for large demolition and mining attachments. Caterpillar and Komatsu leverage in-house steel processing to sustain attachment-to-machine bundling power in direct channels.
- Dealers:Authorized distribution networks providing local inventory and service support. Quick-coupler standardization across OEM platforms is restructuring how dealers stock interchangeable attachment inventory.
- Online Platforms:Digital procurement channels for standardized compact attachments and replacement wear parts.
- OEMs:Original equipment manufacturers integrating attachments with new machine sales and certified pre-owned programs.
- Distributors:Independent wholesalers serving secondary markets and specialized regional demand.
- Rental Providers:Equipment rental firms offering attachments on short-term and subscription-based contracts.
Dealers move the highest attachment volume. Rental providers are gaining share fastest in compact utility categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premiums for reinforced demolition attachments, while Chinese manufacturers compete on forged component scale. This asymmetry shapes procurement patterns across contractor fleets and rental channels.
United States
Highway rehabilitation and urban core densification drive bucket and hammer attachment procurement. EPA Tier 4 Final compliance deadlines accelerate fleet turnover toward quick-coupler-compatible machines. Texas and California contractor markets concentrate demand for compact utility attachments among multi-purpose fleet operators.
Germany
Confined-space demolition protocols in aging metropolitan cores sustain premium pricing for reinforced grapple and hammer designs. EU Stage V emissions enforcement tightens hydraulic interface specifications for attachment-machine compatibility. Industrial clusters in North Rhine-Westphalia anchor heat-treatment capacity for hardened wear components.
China
Metro expansion and national infrastructure buildout expand the installed base of compact excavator attachments. GB standards and MIIT equipment certification requirements influence domestic attachment interface specifications. Foundry and forging capacity concentrates in the Yangtze River Delta, supplying alloy steel components to Western OEMs.
Japan
Demolition contractors adopt sensor-embedded ground-engaging tools fastest, enabling condition-based maintenance scheduling. METI industrial standards and JIS certification requirements shape attachment quality benchmarks. Osaka-based equipment lessors standardize quick-coupler platforms across mixed-brand fleets.
India
National highway and metro rail projects create underpenetrated demand for auger and bucket attachments among emerging contractor fleets. BIS equipment safety standards and central infrastructure allocation programs accelerate machine-hour utilization growth. Maharashtra and Gujarat industrial corridors concentrate rental fleet expansion for compact utility categories.
Construction Equipment Attachments Market Competitive Landscape
Concentration sits with full-line OEMs possessing captive metallurgy and integrated hydraulic system design. The vendor base stratifies across three tiers: integrated machinery manufacturers with in-house steel processing, specialized attachment fabricators with regional forging partnerships, and commodity producers competing on manufacturing scale. Strategic moves center on quick-coupler standardization alliances and backward integration into heat-treatment capacity.
Among integrated machinery manufacturers, Caterpillar, Komatsu, and Develon occupy positions reflecting distinct competitive anchors. Caterpillar exemplifies the captive metallurgy archetype through in-house steel processing capabilities. Komatsu represents hydraulic system integration, optimizing attachment-machine interface performance. Develon sits within agile manufacturing scale, particularly for compact utility attachments serving Asian contractor fleets.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| JCB |
| Liebherr Group |
| Develon |
| CNH Industrial |
| Sany Group |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week delivery windows for induction-hardened wear plates signal supply-chain rigidity that hands pricing leverage to Chinese foundry clusters and compresses margin recovery for Western attachment fabricators. Inventory buffers at German heat-treatment facilities have thinned to three days of forward cover, amplifying spot-market exposure when alloy steel inputs swing.
Pricing Analysis
Configured-to-order demolition grapples command 40-60% premiums over standard bucket configurations due to specialized metallurgy and reinforced tine geometries. Three-tier pricing structure across premium, standard, and economy levels stratifies by Rockwell hardness certification and quick-coupler interoperability grade. Cost compression in economy-tier buckets runs through spot-market alloy sourcing and offshore forging partnerships. Rental companies exhibit the sharpest price sensitivity due to fleet standardization mandates, while Japanese demolition contractors absorb premium pricing for sensor-embedded condition-monitoring systems.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam lane have extended inbound logistics costs for European attachment assemblers sourcing Yangtze River Delta forgings. Manufacturing gravity centers on China, Germany, and the United States, with alloy steel billet supply drawing from South Korean and Japanese mill capacity. Nickel and chromium price volatility creates single-source vulnerability for heat-treatment-dependent wear components. Distribution runs through OEM captive networks for bundled machine-attachment sales, while independent fabricators rely on dealer and rental channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery following EPA Tier 4 Final fleet turnover, with equipment replacement waves in the United States and Germany driving attachment demand acceleration.
For Market Incumbents: Shield margin position by deepening captive heat-treatment capacity in North Rhine-Westphalia and securing long-term alloy offtake from South Korean mills. Proprietary quick-coupler designs from Komatsu and Caterpillar threaten aftermarket interoperability for independent specialists, making ISO 13031 certification investment the priority defensive lever.
For New Entrants and Emerging Players: Anchor in India's underpenetrated compact excavator attachment segment, where national highway and metro buildout outpaces domestic forging capacity. Maharashtra contractor fleets represent the most penetrable demand pool, accessible through equipment-as-a-service platform partnerships that reduce capital barriers for emerging fleet operators.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because rental channel digitization and procurement centralization will displace fragmented independent fabricators. Target acquisition archetypes include regional attachment specialists with captive metallurgy and established dealer relationships. The signal to watch is quick-coupler standardization progress across OEM platforms, which would accelerate aftermarket attachment viability and trigger valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Capacity | Captive induction hardening insulates margin stability from Chinese foundry concentration risk. |
| Quick-Coupler Standardization Alliance | Interoperability certification with Caterpillar and Komatsu unlocks rental fleet procurement volume. |
| Sensor-Embedded Attachment Development | Condition-monitoring systems shift revenue from hardware sales toward lifecycle performance guarantees. |
| Indian Distribution Partnership | Maharashtra and Gujarat channel access captures metro rail and highway expansion demand. |
| Alloy Steel Mill offtake Agreement | Long-term South Korean billet supply hedges nickel and chromium spot volatility exposure. |
Research Methodology
A spread of perspectives from OEM procurement directors, rental fleet managers, heat-treatment facility operators, and demolition contractor equipment supervisors converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC equipment manufacturer filings, and EPA emissions compliance tracking databases. Bottom-up attachment shipment estimates triangulated against top-down construction equipment production data across the analysis window.
Segmentation dimensions modeled include product type complexity, application cost tier, end-user procurement centralization, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and fleet turnover velocity assumptions, cross-referenced with alloy steel input cost trajectories and quick-coupler adoption curves. Attachment-to-machine bundling rates and rental channel penetration served as industry-specific forecast inputs.
Underlying assumptions cover EPA Tier 4 Final compliance timelines and EU Stage V enforcement consistency, with deviation risk concentrated in alloy steel price volatility and ISO 13031 standardization delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Press Brakes Market
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Tower Crane Market
Construction Equipment
Compact Excavator Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Concrete Demolition Professional Equipment Market