
 Foundry Sand Cleaning Machine Market | 2026-2036
Foundry Sand Cleaning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Foundry Sand Cleaning Machine Market Analytics
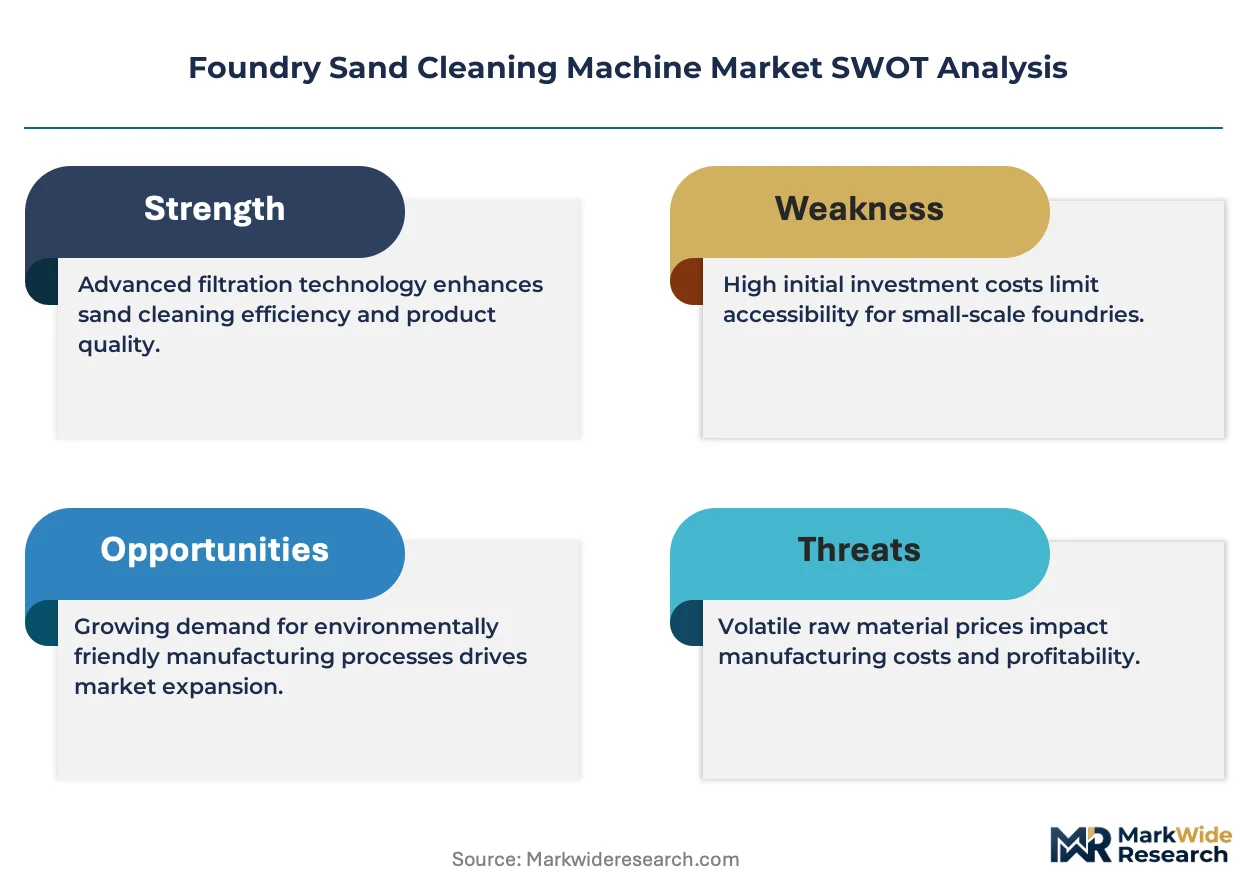
Asset-light leasing and pay-per-ton service contracts is narrowing the competitive field to suppliers with balance-sheet depth. General Kinematics Corporation leverages its North American installed base to bundle equipment with aftermarket service agreements. Sinto Group anchors its position through captive financing programs that lower capital barriers for mid-sized foundries. Qingdao Hezhi Machinery Group Co., Ltd. competes on manufacturing scale, offering shorter delivery timelines than European rivals.
Foundry sand cleaning machines remove binder residues, fines, and contaminants from spent molding sand through thermal, mechanical, or chemical processes, restoring grain size distribution and permeability for reuse in metal casting operations. Thermal cleaners typically operate at 600–800°C to combust organic binders while mechanical systems use attrition mills and pneumatic classification to strip surface coatings. Mechanical Cleaners dominate current installations due to lower energy intensity, though Hybrid Systems are gaining traction where foundries face mixed binder chemistries. Among End User segments, Automotive Manufacturers represent the deepest margin pool because their volume contracts justify dedicated on-site regeneration lines.
EPA silica standards and OSHA permissible exposure limits directly shape equipment specifications, compelling foundries to enclose cleaning processes and install dust collection. REACH restrictions on phenolic resin binders in Europe force adaptation in chemical cleaning chemistry. Stakeholders must monitor how binding technology shifts alter the technical requirements for sand regeneration equipment.
Market Dynamics
Automotive foundries in Germany, the United States, and Japan are consolidating sand regeneration into captive on-site facilities, compressing the addressable market for standalone equipment vendors while elevating service-contract intensity.
Growth Catalysts
- EPA Silica Standards:OSHA permissible exposure limits for respirable crystalline silica compel foundries to enclose mechanical cleaning processes and upgrade dust collection infrastructure.
- Automotive Casting Volumes:Precision powertrain component manufacturing in Stuttgart, Detroit, and Aichi prefecture requires thermally reclaimed sand with tight grain-size distribution tolerances.
- Hybrid System Adoption:Mixed phenolic-urethane binder chemistries in lost-foam and V-process casting lines favor dual-stage thermal-mechanical cleaning configurations.
Market Restraints
- Natural Gas Price Volatility:Thermal cleaners operating at 600–800°C face input cost instability that erodes payback calculations for capital-intensive installations.
- European Equipment Supply Concentration:Germany and Italy host dominant attrition mill and pneumatic classifier manufacturers, creating single-source vulnerability for Asian foundries.
- REACH Phenolic Restrictions:ECHA limitations on formaldehyde-releasing binders complicate chemical cleaning chemistry formulation and extend requalification timelines.
Strategic Opportunities
- Indian Foundry Modernization:BIS quality mandates and PLI scheme incentives for automotive component exports accelerate demand for automated mechanical cleaners in Rajkot and Coimbatore clusters.
- Pay-per-ton Service Contracts:Asset-light leasing models lower capital barriers for mid-tier ferrous foundries in Mexico and Turkey, expanding addressable volume beyond Tier 1 automotive suppliers.
- CE-MDR Convergence:Machinery Directive compliance requirements for enclosed dust-handling systems create specification premiums for integrated thermal-mechanical units.
Industry Challenges
- Refractory Lining Replacement Cycles:Thermal cleaner combustion chambers require scheduled rebuilds that disrupt foundry production scheduling and inflate total cost of ownership calculations.
- Legacy Mechanical System Integration:Pneumatic classification retrofits into existing shakeout and cooling lines demand custom ducting engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foundry Sand Cleaning Machine Market |
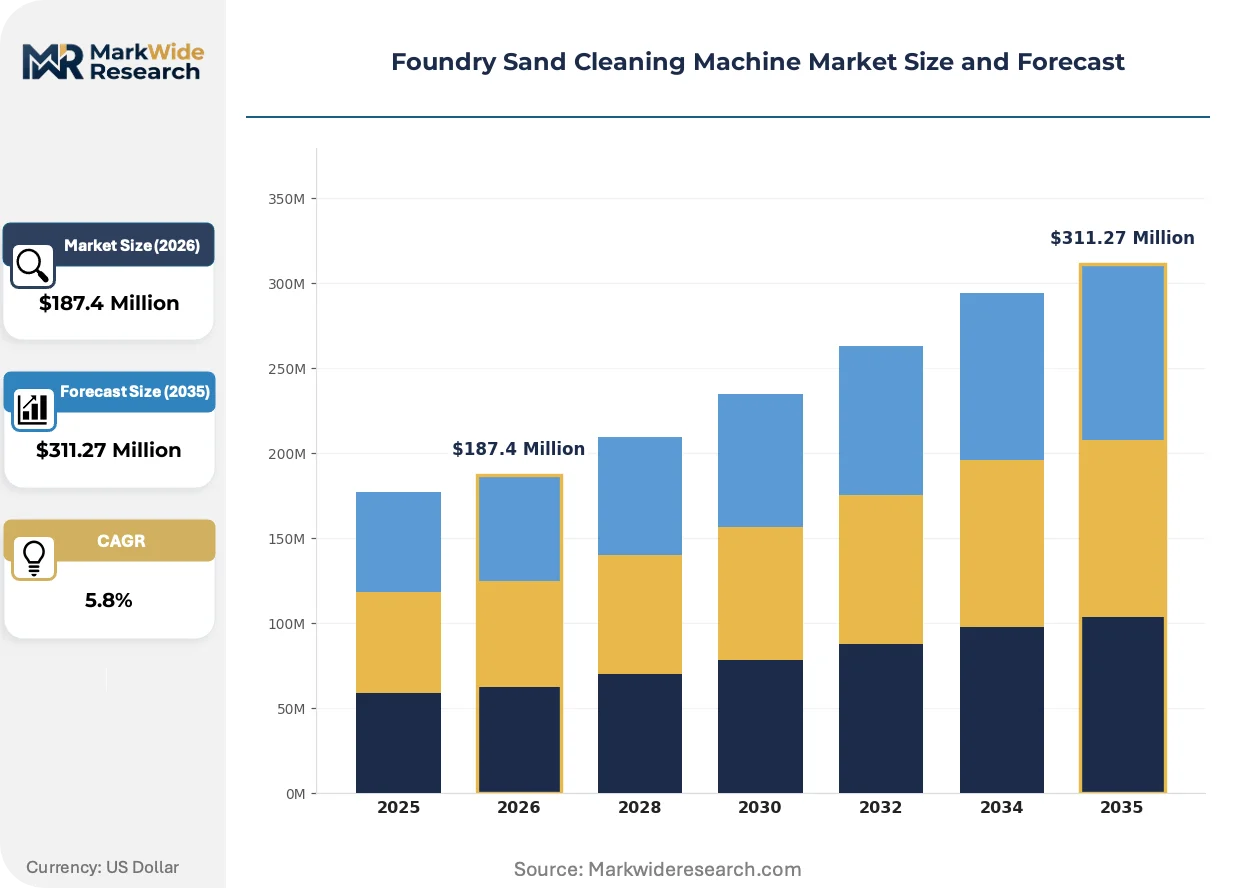
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Cleaners, Thermal Cleaners, Chemical Cleaners, Hybrid Systems Application: Metal Casting, Molding, Core Making, Recycling End User: Automotive Manufacturers, Aerospace Industries, Construction Firms, Foundries Technology: Mechanical Separation, Thermal Treatment, Chemical Processes, Innovative Techniques |
| Companies Covered | Metso Corporation, General Kinematics Corporation, Qingdao Hezhi Machinery Group Co., Ltd., EIRICH Machines, Inc., Loramendi S. Coop., Vulcan Engineering Co., Omega Foundry Machinery Ltd., Palmer Manufacturing & Supply, Inc., Sinto Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foundry Sand Cleaning Machine Market Evolving Landscape
Electrification of vehicle powertrains is fragmenting casting demand across aluminum structural components and reduced iron block volumes, altering sand chemistry requirements and regeneration intensity profiles.
Continuous thermal reclamation units with integrated heat recovery are rendering obsolete batch-operated crucible cleaners in high-volume automotive foundries. BMW, Toyota, and Ford casting operations in Leipzig, Tahara, and Cleveland have adopted these systems since 2022. The shift compresses energy consumption per ton of reclaimed sand and eliminates batch-to-batch quality variance that complicated just-in-time molding line supply.
REACH restrictions on phenolic resin binders are forcing adaptation in chemical cleaning additive formulations across European foundries. ECHA substance evaluation timelines have delayed approval of alternative furan and alkaline phenolic systems. German and Italian equipment suppliers are responding with modular chemical cleaning stages that permit rapid chemistry switching without full line reconfiguration.
Foundry procurement departments are unbundling aftermarket service agreements from initial equipment purchases. Tier 2 automotive suppliers in the US Midwest and Mexico's Querétaro corridor now source spare parts and technical support through independent distributors rather than captive OEM service networks. This channel fragmentation pressures original equipment margins while expanding third-party maintenance market entry points.
Foundry Sand Cleaning Machine Market Segmentation
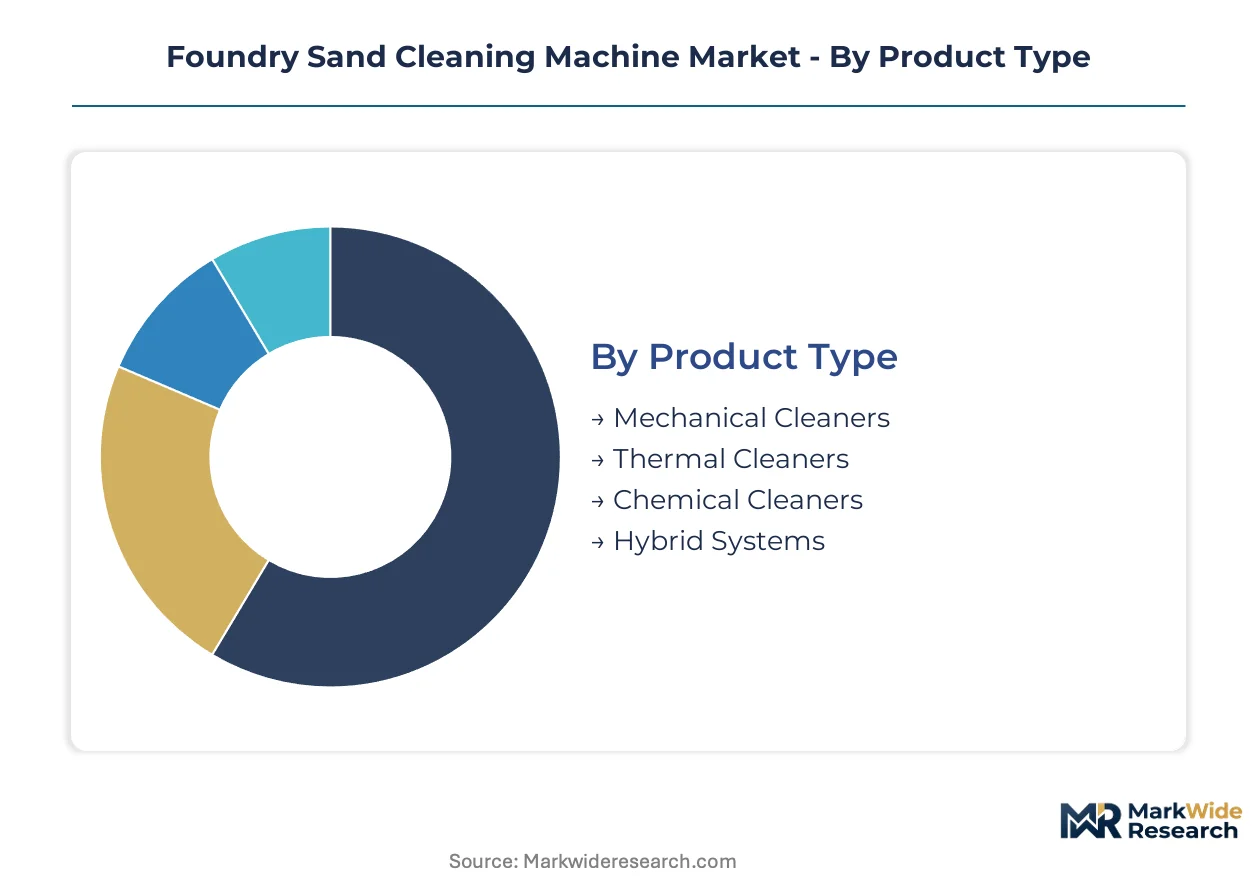
Segmentation in foundry sand cleaning machines tracks how binder chemistry, casting volume, and regulatory pressure reshape equipment specifications across different operational contexts. Understanding these divisions reveals where capital deployment concentrates and which technical configurations command pricing premiums.
Product Type:
Mechanical systems dominate low-to-mid volume operations while thermal configurations anchor high-throughput automotive lines; hybrid architectures are gaining ground where foundries process mixed binder streams.
- Mechanical Cleaners:Attrition mills and pneumatic classifiers strip surface coatings from spent sand at ambient temperatures, consuming 60-70% less energy than thermal alternatives. Demand concentrates in Germany's automotive foundry belt around Stuttgart and Munich, where continuous regeneration lines serve BMW and Porsche powertrain casting operations facing strict EPA silica enclosure mandates.
- Thermal Cleaners:Combustion chambers operating at 600–800°C incinerate organic binders to restore base sand grain structure. Foundries in Aichi prefecture, Japan deploy these systems for Toyota's just-in-time aluminum casting lines, where batch-to-batch consistency requirements justify natural gas input costs despite price volatility concerns.
- Chemical Cleaners:Solvent-based additive formulations dissolve specific binder chemistries without thermal stress. REACH phenolic restrictions in Europe are forcing reformulation cycles that extend equipment requalification timelines.
- Hybrid Systems:Dual-stage thermal-mechanical configurations handle mixed phenolic-urethane binder chemistries common in lost-foam casting. Adoption is climbing fastest among Tier 1 suppliers retooling for electrification-driven aluminum component demand.
The dominant share belongs to Mechanical Cleaners, while Hybrid Systems are closing the gap fastest as binder complexity increases across automotive casting operations.
Application:
Volume intensity varies sharply: metal casting consumes the most reclaimed sand tonnage, while core making demands the tightest grain-size tolerances.
- Metal Casting:Green sand and chemically bonded molding systems require continuous sand regeneration to maintain permeability and surface finish specifications. High-volume ferrous foundries in Rajkot, India are automating mechanical cleaning lines to meet BIS quality mandates for automotive export contracts.
- Molding:Precision molding lines for engine blocks and transmission housings demand thermally reclaimed sand with narrow grain distribution curves. Ford's Cleveland casting plant upgraded to continuous thermal reclamation with integrated heat recovery to eliminate batch quality variance.
- Core Making:Cold-box and hot-box core production uses virgin sand or premium reclaimed material with minimal binder residue. Aerospace suppliers in Querétaro, Mexico specify near-virgin quality for complex internal passage geometries.
- Core Making:Cold-box and hot-box core production uses virgin sand or premium reclaimed material with minimal binder residue. Aerospace suppliers in Querétaro, Mexico specify near-virgin quality for complex internal passage geometries.
- Recycling:Standalone reclamation facilities process sand from multiple foundries under pay-per-ton service contracts, concentrating in Turkey's organized industrial zones where mid-tier ferrous casters lack captive regeneration capacity.
Metal Casting commands the largest equipment installed base, though Recycling is expanding most quickly as asset-light service models penetrate fragmented foundry markets.
End User:
Capital intensity and technical sophistication separate captive automotive facilities from independent job shops serving construction and general industry.
- Automotive Manufacturers:Dedicated on-site regeneration lines justify premium thermal and hybrid systems with integrated dust collection and real-time quality monitoring. Toyota's Tahara plant represents the benchmark for continuous thermal reclamation deployment.
- Foundries:Independent casting operations serving multiple industries favor mechanical cleaners with lower capital barriers and flexible throughput. Coimbatore's cluster of mid-sized ferrous foundries is modernizing with automated attrition mills under PLI scheme incentives.
- Aerospace Industries:Titanium and superalloy investment casting requires ultra-low contaminant levels that often mandate virgin sand or specialized chemical cleaning stages.
- Construction Firms:Infrastructure casting for valves, fittings, and municipal hardware operates with lower reclamation intensity, often outsourcing sand processing to regional recycling facilities.
Automotive Manufacturers retain the deepest margin pool for equipment vendors, while Foundries are gaining share fastest as consolidation creates larger independent operations capable of captive regeneration investment.
Technology:
Process physics determines energy intensity, emission profiles, and compatibility with evolving binder chemistries across regulatory jurisdictions.
- Mechanical Separation:Kinetic attrition and air classification remove surface coatings without thermal degradation of base sand. German equipment suppliers in Bavaria dominate attrition mill engineering for European automotive foundries.
- Thermal Treatment:High-temperature combustion oxidizes organic binders and burns off carbon residues. OSHA silica exposure limits in the United States mandate enclosed combustion chambers with negative-pressure dust handling.
- Chemical Processes:Acid washing and solvent extraction target specific contaminant chemistries. ECHA substance evaluation timelines are delaying alternative furan system approvals, freezing some European investment decisions.
- Innovative Techniques:Microwave thermal treatment and plasma-based surface stripping are emerging for specialized applications. METI-funded research programs in Japan are piloting these approaches for next-generation aluminum casting sand regeneration.
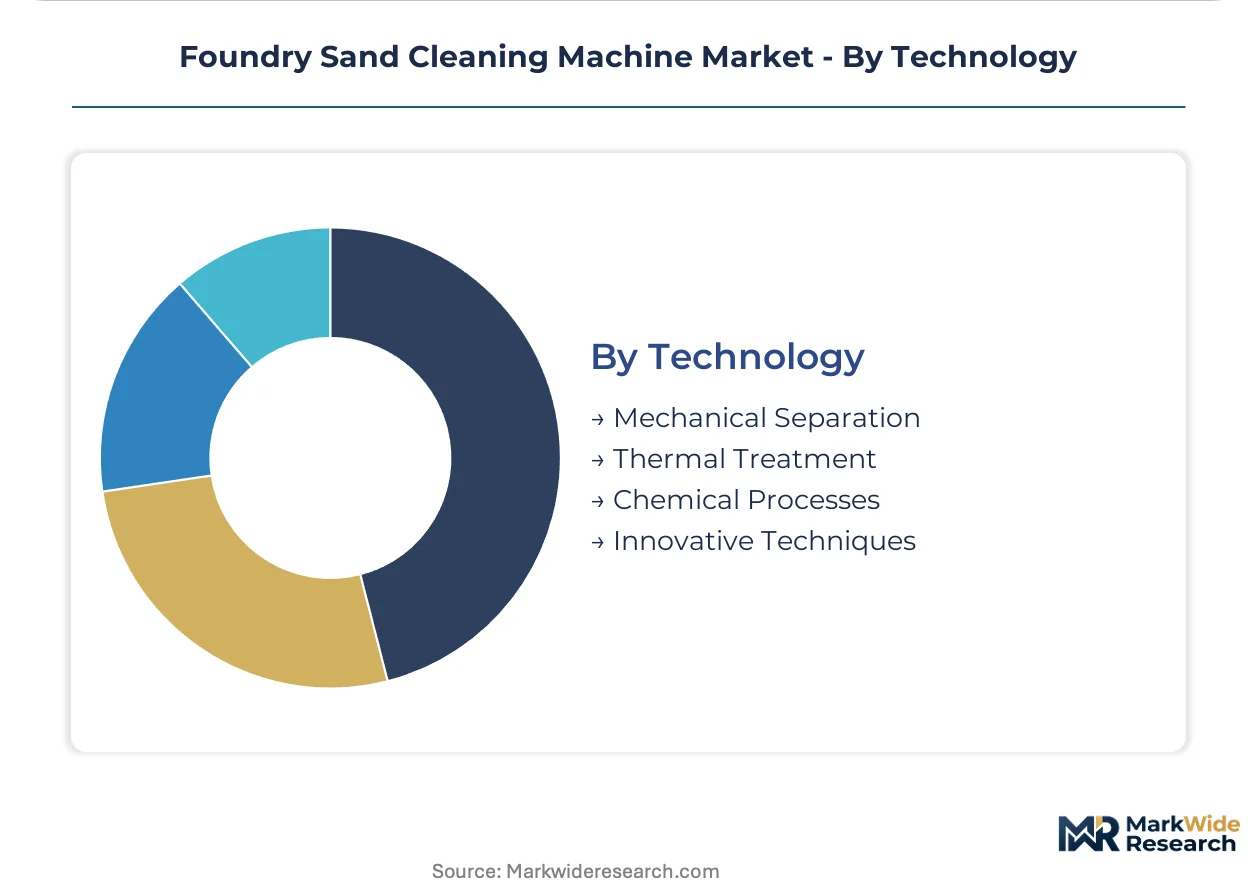
Mechanical Separation holds the dominant installed base, though Innovative Techniques are climbing the fastest as energy efficiency and emission reduction targets intensify across major manufacturing economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA silica exposure limits and EPA emissions rules in the United States, alongside REACH phenolic restrictions in Europe and BIS quality mandates in India, are reshaping capital deployment patterns for foundry sand regeneration equipment across major manufacturing economies.
United States
Automotive powertrain casting operations in Detroit and Cleveland drive demand for continuous thermal reclamation systems with integrated dust collection. OSHA permissible exposure limits for respirable crystalline silica compel foundries to enclose mechanical cleaning processes entirely. Ford's Cleveland casting plant upgraded to heat-recovery thermal units to eliminate batch quality variance in just-in-time molding line supply.
Germany
BMW and Porsche powertrain operations around Stuttgart and Munich anchor European demand for premium mechanical and hybrid cleaning configurations. REACH restrictions on formaldehyde-releasing phenolic binders force equipment suppliers to engineer modular chemical cleaning stages permitting rapid chemistry switching. Bavarian equipment manufacturers dominate attrition mill engineering for automotive foundry belt customers.
Japan
Toyota's aluminum casting lines in Aichi prefecture deploy high-temperature thermal cleaners operating at 600–800°C for just-in-time sand supply with tight grain-size tolerances. METI-funded research programs are piloting microwave thermal treatment and plasma-based surface stripping for next-generation regeneration. Tahara plant represents the benchmark for continuous thermal reclamation deployment in Asian automotive manufacturing.
India
BIS quality mandates and PLI scheme incentives for automotive component exports accelerate demand for automated mechanical cleaners in Rajkot and Coimbatore foundry clusters. Mid-sized ferrous foundries modernize with attrition mills to meet export contract specifications. Government production-linked incentive schemes lower capital barriers for captive regeneration investment.
Turkey
Organized industrial zones around Istanbul and Izmir concentrate pay-per-ton sand recycling service contracts serving mid-tier ferrous casters lacking captive regeneration capacity. Asset-light leasing models expand addressable volume beyond Tier 1 automotive suppliers. Regional recycling facilities process sand from multiple foundries under service contract arrangements.
Foundry Sand Cleaning Machine Market Competitive Landscape
On the supply side, the industry is tiered between premium thermal-mechanical system integrators, mid-market mechanical cleaner specialists, and scale-driven Asian fabricators. Strategic archetypes include captive financing providers lowering capital barriers, aftermarket service bundlers leveraging installed base density, and manufacturing-scale competitors compressing delivery timelines. Dominant competitive moves encompass geographic expansion through distribution partnerships and portfolio diversification into hybrid system configurations.
Among North American-based integrators, General Kinematics Corporation exemplifies the aftermarket service bundler archetype, while Japanese industrial conglomerates represented by Sinto Group anchor the captive financing tier. Chinese manufacturing-scale competitors including Qingdao Hezhi Machinery Group Co., Ltd. occupy positions emphasizing production throughput and compressed delivery schedules relative to European rivals.
| Leading Market Players |
|---|
| Metso Corporation |
| General Kinematics Corporation |
| Qingdao Hezhi Machinery Group Co., Ltd. |
| EIRICH Machines, Inc. |
| Loramendi S. Coop. |
| Vulcan Engineering Co. |
| Omega Foundry Machinery Ltd. |
| Palmer Manufacturing & Supply, Inc. |
| Sinto Group |
| Others |
Value Network & Pricing Analysis
German and Italian attrition mill manufacturers anchor upstream supply for pneumatic classification components, concentrating margin capture with equipment integrators serving BMW and Porsche operations around Stuttgart while compressing pricing power for mid-tier mechanical cleaner vendors.
Pricing Analysis
Certification level (CE-MDR and OSHA silica compliance) creates the primary spread between premium thermal-mechanical units and standard mechanical configurations. Three-tier pricing structure across premium, standard, and economy levels reflects enclosure sophistication and real-time quality monitoring integration. Pricing pressure stems from natural gas input cost volatility affecting thermal cleaner payback calculations. Tier 2 automotive suppliers in Mexico's Querétaro corridor exhibit highest price sensitivity, while captive automotive facilities in Germany and Japan absorb premium positioning for just-in-time reliability.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Bavarian attrition mill specialists, Aichi prefecture thermal chamber fabricators, and Qingdao-based scale producers serving Asian foundry demand. Component sourcing draws from German refractory lining suppliers, Japanese burner system manufacturers, and Chinese steel fabrication networks. Single-source vulnerability runs through European pneumatic classifier engineering. Distribution runs through OEM captive service networks and independent aftermarket distributors fragmenting channel control in the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from in-house sand regeneration consolidation at Toyota, BMW, and Ford casting operations, requiring defensive repositioning around service intensity rather than equipment shipment volumes.
For Market Incumbents: Build switching-cost moats through captive spare parts logistics and predictive maintenance software integration. Bundle thermal cleaner rebuild services with refractory lining replacement cycles to lock in Toyota and Ford automotive accounts. Counter vertical integration threats from Tier 1 suppliers by embedding field engineering teams directly at BMW Leipzig and Tahara plant operations. For New Entrants and Emerging Players: Build out pay-per-ton service contract capabilities targeting Rajkot and Coimbatore foundry clusters lacking captive regeneration investment. Penetrate Turkey's organized industrial zones where mid-tier ferrous casters outsource sand processing under asset-light arrangements. Lead with rapid chemical cleaning stage reconfiguration to exploit REACH-driven formulation uncertainty among European phenolic binder users. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mechanical cleaner specialists in Germany's automotive foundry belt holding dense installed base positions. Five-to-ten year viability hinges on hybrid system transition timing as electrification fragments casting demand toward aluminum components. Monitor METI-funded microwave thermal treatment pilots in Japan as inflection signal for next-generation technology displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Lining Production | Captive supply of combustion chamber rebuild materials secures Toyota and Ford maintenance contract renewals. |
| Pay-per-Ton Service Contract Expansion | Asset-light leasing in Turkey and Mexico penetrates mid-tier foundries excluded from captive regeneration investment. |
| CE-MDR Compliance Certification Program | Enclosed dust-handling specifications command specification premiums from BMW and Porsche operations. |
| Hybrid System Configuration Development | Dual-stage thermal-mechanical units capture mixed phenolic-urethane binder demand from lost-foam casting lines. |
| Geographic Manufacturing Footprint in India | Local assembly near Rajkot and Coimbatore clusters compresses delivery timelines against European rivals. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with foundry operations managers, equipment procurement leads at automotive OEMs, aftermarket service heads, and refractory materials suppliers; and secondary validation through SEC filings of listed industrial equipment manufacturers, German mechanical engineering association reports, EPA enforcement action databases, and BIS quality mandate documentation. Bottom-up triangulation against top-down trade flow analysis ensured segmentation integrity across mechanical, thermal, and hybrid system categories.
Forecast inputs considered automotive casting volume trajectories, OSHA silica exposure limit enforcement intensity, and REACH phenolic binder restriction timelines across the projection horizon. Segmentation modeling tracked product type, application intensity, end-user capital sophistication, and technology energy profile. CAGRs were derived from installed base replacement cycles and greenfield capacity additions rather than macroeconomic extrapolation alone. Natural gas price volatility bands and electrification-driven aluminum casting mix shifts provided scenario boundaries.
Stress conditions across natural gas input costs, ECHA substance approval delays, and Indian PLI scheme incentive continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OSHA enforcement consistency and automotive powertrain casting demand stabilization. Quarterly review of METI pilot program advancement, EPA silica citation trends, and Turkish organized industrial zone contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Cable Winches Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Welding Equipment Market