
 North America Air to Water Heat Pump Market | 2026-2036
North America Air to Water Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
North America Air to Water Heat Pump Market Analysis
Canada is fragmenting as a manufacturing base for cold-climate air to water heat pump systems, with Ontario and Quebec emerging as assembly hubs serving cross-border demand. Daikin Comfort Technologies North America leverages its inverter-driven compressor platforms to dominate premium residential segments. Carrier sustains broad distribution through its dealer network across the Upper Midwest and Northeast corridors. Bosch Thermotechnology anchors European-derived engineering expertise in hydronic system integration for North American specifications.
An air to water heat pump extracts thermal energy from ambient air and transfers it via refrigerant cycle to a water-based distribution system, typically achieving coefficient of performance ratings between two and four depending on source temperature and load conditions. The technology serves primary heating, cooling, and domestic hot water production in buildings with hydronic radiator, in-floor, or fan-coil terminal units. Split systems occupy the largest installed base among product type categories due to flexibility in matching outdoor compressors with diverse indoor hydronic modules. Retrofit installations represent the fastest-growing installation type segment as municipalities in Massachusetts, Vermont, and British Columbia impose fossil fuel heating restrictions on existing building stock.
The Inflation Reduction Act, administered through IRS guidance and coordinated with DOE efficiency standards, shapes consumer economics through point-of-sale rebates and tax credits for heat pump conversions. NRCan and provincial utilities in Canada operate parallel incentive structures through the Canada Greener Homes Initiative and Quebec's Hydro-Québec electrification programs. EPA SNAP regulations on refrigerant phase-downs are forcing manufacturers toward lower-global-warming-potential working fluids ahead of compliance deadlines. Stakeholders must monitor cold-climate performance certification thresholds under CSA and AHRI test procedures as these specifications increasingly determine product eligibility for incentive programs and utility procurement.
Market Dynamics
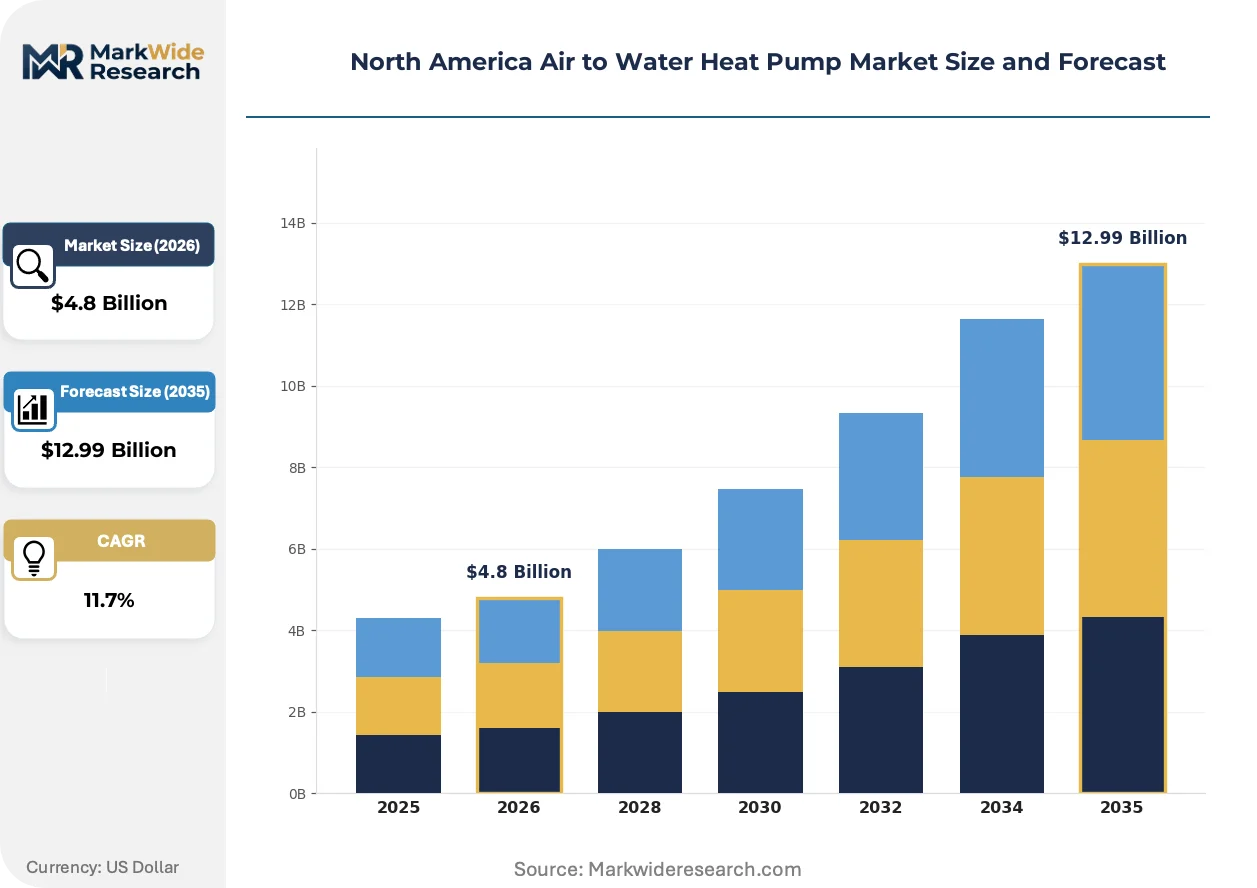
The Inflation Reduction Act's tax credit architecture is compressing payback periods for residential heat pump conversions, forcing manufacturers to reconfigure product portfolios around cold-climate performance certification thresholds.
Growth Catalysts
- IRA Point-of-Sale Rebates:The Inflation Reduction Act's 25C and 25D provisions reduce upfront capital barriers for homeowners replacing fossil fuel boilers in Minnesota, Wisconsin, and Maine.
- Electrification Mandates:Massachusetts and Vermont building codes now prohibit new fossil fuel heating in existing structures, creating replacement demand for hydronic-compatible heat pump systems.
- CSA Cold-Climate Certification:The Canadian Standards Association's enhanced test procedures for sub-zero coefficient of performance ratings are qualifying premium equipment for utility procurement programs.
Market Restraints
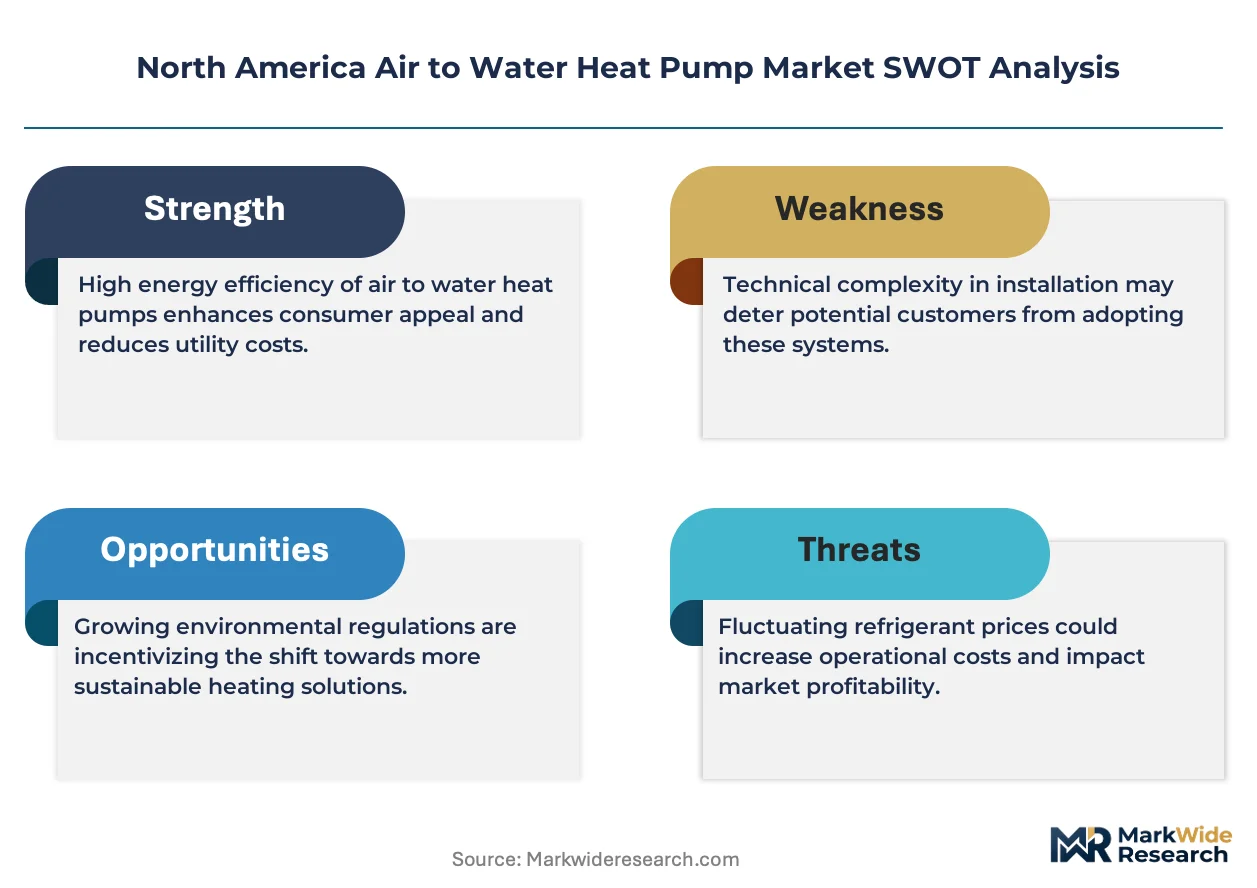
- Copper and Aluminum Input Volatility:Compressor heat exchangers and refrigerant piping rely on base metals exposed to commodity price swings, compressing assembler margins during procurement cycles.
- Refrigerant Supply Concentration:EPA SNAP phase-down timelines for high-global-warming-potential working fluids are narrowing supplier options ahead of R-454B and R-290 scale-up.
- Defrost Cycle Efficiency Losses:Ambient temperatures below minus fifteen degrees Celsius degrade coefficient of performance ratings, limiting equipment viability in northern prairie installations without auxiliary thermal storage.
Strategic Opportunities
- Quebec Electrification Programs:Hydro-Québec's residential conversion incentives remain underpenetrated relative to Ontario and British Columbia, offering first-mover positioning for cold-climate-certified equipment.
- Multi-Family Hydronic Retrofits:Central boiler replacements in 1960s-era apartment buildings in Chicago and Detroit represent an emerging application segment with concentrated decision-making.
- Smart Grid Integration:Convergence of inverter-driven compressors with utility demand-response protocols is enabling new revenue streams through frequency regulation services in PJM and ISO-NE territories.
Industry Challenges
- Refrigerant Handling Certification:EPA Section 608 technician requirements for lower-flammability A2L working fluids are creating bottlenecks in installer workforce expansion across New England states.
- Legacy Hydronic System Compatibility:Mismatch between heat pump output temperatures and existing cast-iron radiator designs in pre-1980 housing stock forces costly distribution system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Air to Water Heat Pump Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Packaged Units, Mini-splits, Chillers End User: Residential, Commercial, Industrial, Educational Installation Type: New Construction, Retrofit, Replacement, Upgrades Seasonality: Summer, Winter, Year-round, Transition |
| Companies Covered | Daikin Comfort Technologies North America, Carrier, Bosch Thermotechnology, Samsung, Trane, Johnson Controls, LG Electronics, Rheem Manufacturing Company, Arctic Heat Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Air to Water Heat Pump Market Emerging Trajectories
Refrigerant chemistry, compressor control logic, and system architecture are converging to extend operational range into sub-zero conditions previously served only by fossil fuel boilers.
Variable-speed inverter technology is hybridizing with vapor-injection compressor staging to maintain heating capacity at ambient temperatures below minus twenty degrees Celsius. Cold-climate states including Maine and Minnesota are specifying this architecture for residential retrofits where electric resistance backup was previously mandatory. Equipment cost premiums are compressing as production scales for North American voltage and refrigerant specifications.
The EPA's SNAP program is accelerating refrigerant transitions toward R-454B and R-1234yf blends with sub-700 global warming potential ratings. Manufacturers are requalifying heat exchanger designs and safety controls to accommodate mild flammability classifications ahead of 2025 compliance deadlines. Cold-climate product lines face the most complex recertification burden due to higher refrigerant charge sizes and extended operating pressures.
Utility-managed installation programs are displacing traditional HVAC contractor channels in Massachusetts and Vermont electrification corridors. Residential customers in these states now initiate conversions through Mass Save and Efficiency Vermont portals rather than independent equipment quotes. This channel shift is concentrating volume with assemblers holding pre-approved product lists and certified installer networks.
North America Air to Water Heat Pump Market Segmentation
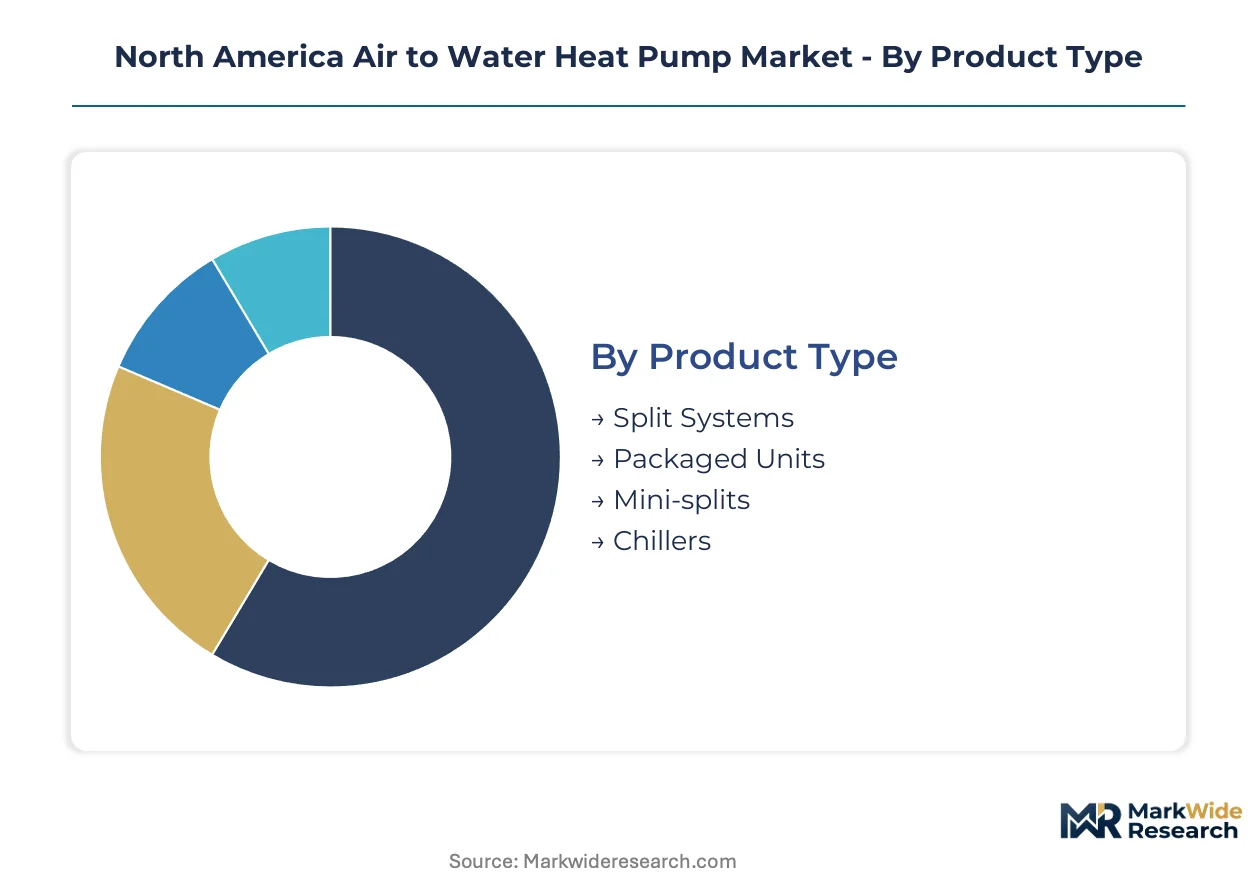
Equipment configuration and deployment context determine performance certification pathways and incentive eligibility across the North American regulatory landscape. Understanding how product architecture, end-use requirements, and installation setting interact reveals where cold-climate engineering investments concentrate.
Product Type:
Compressor configuration and refrigerant circuit architecture define the technical boundaries for cold-climate performance certification under CSA and AHRI protocols.
- Split Systems:Separate outdoor compressor modules pair with indoor hydronic distribution units through refrigerant piping, enabling flexible matching to legacy radiator or in-floor systems. Demand concentrates in Minnesota and Wisconsin residential retrofits where existing hydronic infrastructure requires modular outdoor placement away from mechanical rooms.
- Packaged Units:Integrated compressor and heat exchanger assemblies in single outdoor cabinets simplify installation but constrain siting flexibility. Maine coastal municipalities specify these for tight lot configurations where indoor equipment space is unavailable.
- Mini-splits:Compact refrigerant-distribution systems serve smaller thermal loads with reduced refrigerant charge volumes.
- Chillers:Centralized water-glycol production units serve multi-zone commercial applications with secondary pumping.
Split systems hold installed capacity. Packaged units is rotating up the share rankings.
End User:
Load profile intensity and operating hour accumulation create divergent total-cost-of-ownership economics across customer categories.
- Residential:Single-family and multi-family dwellings with variable occupancy patterns prioritize coefficient of performance ratings at moderate ambient temperatures. Massachusetts and Vermont building code electrification mandates are accelerating replacement cycles for fossil fuel boilers in 1960s-era housing stock.
- Commercial:Office and retail buildings with extended operating hours demand higher capacity maintenance at part-load conditions. Chicago and Detroit central business districts are specifying cold-climate-certified equipment for district heating conversions.
- Industrial:Process heating and facility thermal management applications with steady base loads.
- Educational:K-12 and university campuses with seasonal occupancy variations.
Residential dominates current deployment volume. Commercial is expanding most quickly as municipal electrification mandates extend beyond single-family housing.
Installation Type:
Site constraints and existing infrastructure condition determine distribution system modification requirements and project economics.
- Retrofit:Existing building conversions from fossil fuel boilers require hydronic compatibility assessment and potential emitter resizing. British Columbia's CleanBC program and Massachusetts fossil fuel restrictions are concentrating demand in this category across pre-1980 housing with cast-iron radiator systems.
- New Construction:Ground-up building integration allows optimized heat pump sizing and low-temperature distribution design from inception. Quebec's updated building code requirements are mandating heat pump readiness in new residential developments.
- Replacement:Direct equipment swaps where existing distribution systems are already heat-pump-compatible.
- Upgrades:Capacity expansion or efficiency enhancement of operational heat pump installations.
Retrofit commands policy-driven momentum. New construction is climbing the fastest as electrification mandates embed in provincial and state building codes.
Seasonality:
Operating period definition shapes equipment specification for defrost cycle frequency and auxiliary heat integration.
- Winter:Heating-dominant operation with ambient temperatures cycling through defrost thresholds. Northern prairie installations in Manitoba and Saskatchewan specify vapor-injection compressors for sustained capacity below minus twenty degrees Celsius.
- Year-round:Continuous heating and cooling operation with seasonal reversal. Ontario and New York State utilities prioritize this specification for demand-response program eligibility.
- Summer:Cooling-only or cooling-dominant operation with limited heating duty.
- Transition:Shoulder-season operation with moderate ambient temperatures and reduced load intensity.
Year-round dominates utility procurement specifications. Winter is gaining share fastest as cold-climate certification thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity for cold-climate air to water heat pump systems clusters in Ontario and Quebec, with Canadian facilities supplying cross-border demand into the northern United States. This supply-side concentration shapes regional deployment patterns and certification requirements across North America.
United States
Residential retrofits in Minnesota, Wisconsin, and Maine drive equipment replacement cycles as homeowners abandon fossil fuel boilers. The Inflation Reduction Act's 25C and 25D tax credit provisions reduce upfront capital barriers for clean heating conversions. Cold-climate performance certification under AHRI test procedures determines product eligibility for utility procurement programs in the Upper Midwest.
Canada
Ontario and Quebec have emerged as manufacturing hubs for cold-climate air to water heat pump systems serving North American demand. NRCan and provincial utilities operate parallel incentive structures through the Canada Greener Homes Initiative and Hydro-Québec electrification programs. British Columbia's CleanBC program concentrates retrofit demand in pre-1980 housing stock with cast-iron radiator systems.
Mexico
Northern border states are developing component supply relationships for compressor and heat exchanger manufacturing serving North American assemblers. Mexican industrial clusters provide copper tubing and aluminum fin stock exposed to commodity price volatility affecting assembler margins. Baja California and Chihuahua house metalworking facilities supporting cross-border HVAC supply chains.
North America Air to Water Heat Pump Market Vendor Landscape
Global diversified HVAC conglomerates and regional cold-climate specialists split the market between premium residential segments and utility-scale procurement channels. The vendor base organizes around three strategic archetypes: inverter-technology platform owners, hydronic system integration specialists, and cold-climate performance certification leaders. Competitive positioning hardens through M&A activity targeting compressor control capabilities and strategic partnerships with utility-managed installation programs.
Within the inverter-technology tier, Daikin Comfort Technologies North America and Carrier occupy positions defined by compressor platform breadth and distribution network density. Bosch Thermotechnology anchors the European-derived engineering expertise archetype for hydronic system integration. These three companies exemplify how manufacturing scale and certification depth determine access to pre-approved product lists in Massachusetts and Vermont electrification corridors.
| Leading Market Players |
|---|
| Daikin Comfort Technologies North America |
| Carrier |
| Bosch Thermotechnology |
| Samsung |
| Trane |
| Johnson Controls |
| LG Electronics |
| Rheem Manufacturing Company |
| Arctic Heat Pumps |
| Others |
Supply Flow & Price Mechanics
Ontario and Quebec compressor assembly clusters concentrate upstream manufacturing for North American demand, anchoring margin pools with inverter-platform owners while commodity-exposed component suppliers absorb aluminum and copper volatility. Equipment assemblers face asymmetric pricing power where cold-climate certification thresholds determine utility procurement eligibility and point-of-sale rebate access.
Pricing Analysis
The Inflation Reduction Act dictates the pricing tier structure across residential retrofit channels, separating cold-climate-certified equipment eligible for 25C and 25D incentives from standard-performance units excluded from Mass Save and Efficiency Vermont portals. Pricing stratifies across premium, standard, and economy tiers based on AHRI certification level and vapor-injection compressor architecture. Cost compression in standard-tier equipment is intensifying because aluminum fin stock and copper tubing face commodity price swings. Residential retrofits in pre-1980 housing with cast-iron radiators show highest price sensitivity due to distribution system modification requirements, while commercial district heating conversions in Chicago and Detroit demonstrate lowest sensitivity given concentrated decision-making and energy cost savings.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk for copper tubing and aluminum heat exchanger components crossing the northern border. Manufacturing draws from Mexican metalworking clusters in Baja California and Chihuahua, South Korean inverter control module suppliers, and Canadian final assembly facilities in Ontario and Quebec. Raw material dependencies center on copper ore from Chilean mines, aluminum from Canadian smelters, and rare-earth magnets for compressor motors. Single-source vulnerability concentrates in EPA SNAP-compliant refrigerant supply ahead of R-454B scale-up. Distribution runs through utility-managed installation programs in Massachusetts and Vermont displacing traditional HVAC contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against fossil fuel boilers and electric resistance heating, with incumbents facing displacement risk from natural gas infrastructure lock-in and emerging thermal battery hybrids.
For Market Incumbents: Entrench cold-climate certification leadership by pre-qualifying equipment for CSA sub-zero performance thresholds and Mass Save pre-approved product lists before R-454B refrigerant recertification deadlines compress competitor response windows. Secure backward integration into inverter control module production to defend margin position against South Korean component suppliers. Channel control through certified installer networks in Vermont and Massachusetts electrification corridors limits new entrant access to policy-driven volume. For New Entrants and Emerging Players: Quebec electrification corridors represent the most penetrable entry point given Hydro-Québec incentive underpenetration relative to Ontario and British Columbia. Mid-market commercial buildings in Detroit and Chicago with 1960s-era central boilers offer concentrated decision-making for first equipment placements. A go-to-market angle through utility demand-response program partnerships in PJM and ISO-NE territories enables revenue stacking beyond equipment margins. For Investors and Strategic Acquirers: Capital is best deployed toward cold-climate compressor platform specialists with existing AHRI certification and vapor-injection IP, given five-to-ten year regulatory tailwinds for electrification mandates. Acquisition targets should demonstrate pre-approved status in Massachusetts and Vermont utility programs. The signal to watch is EPA SNAP refrigerant phase-down enforcement pace determining recertification cost burdens for sub-scale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate Certification Investment | AHRI and CSA sub-zero performance ratings unlock Mass Save and Efficiency Vermont procurement eligibility. |
| Refrigerant Transition R&D | R-454B heat exchanger redesign ahead of EPA SNAP deadlines preserves market access. |
| Utility Program Partnership | Pre-approved product list status in Massachusetts and Vermont electrification corridors concentrates volume. |
| Backward Integration into Controls | In-house inverter module production reduces exposure to South Korean supplier concentration. |
| Installer Network Certification | EPA Section 608 A2L technician training programs create bottleneck control in New England states. |
Methodological Framework
Operator-level perspectives from HVAC contractor operations managers, utility program administrators at Mass Save and Efficiency Vermont, compressor platform engineering directors, and residential retrofit project developers anchored the qualitative base. Secondary validation drew from DOE efficiency standard filings, EPA SNAP regulatory dockets, NRCan Greener Homes program data, AHRI certification directories, and CSA test procedure documentation. Bottom-up equipment shipment analysis triangulated against top-down building stock electrification modeling.
Scenario-bracketing around Inflation Reduction Act implementation pace, refrigerant phase-down enforcement timing, and cold-climate certification threshold evolution shaped projection boundaries across the analysis window. Segmentation dimensions modeled include product architecture, end-use intensity, installation context, and operating period specification. CAGRs were derived from equipment replacement cycle analysis and policy-driven retrofit demand curves. Forecast inputs incorporated building code electrification mandate adoption rates and utility incentive program budget allocations.
Practitioners should monitor EPA SNAP enforcement timing, copper and aluminum commodity price volatility, and Massachusetts building code expansion to adjacent states for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Compressor Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Global Air Curtain Market