
 Global Air Duct Market | 2026-2036
Global Air Duct Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Duct Market Analysis
Aftermarket service revenue is reshaping margin distribution across the Global Air Duct Market, pulling profitability from pure manufacturing toward lifecycle maintenance contracts. Lindab Group anchors its position through captive distribution networks across Northern Europe. Saint-Gobain leverages materials science expertise to differentiate in fiberglass and composite duct solutions. Thermaflex specializes in flexible insulation systems that compete on thermal efficiency metrics in commercial retrofit channels.
Air ducts are engineered conduits, typically fabricated from galvanized steel, aluminum, or polymer composites with specified friction loss coefficients and leakage class ratings, designed to distribute conditioned air within mechanical ventilation and climate control systems. Rigid metal ducts dominate commercial and institutional installations where fire resistance and structural integrity are specified, while flexible ducts capture residential and modular applications where routing complexity demands adaptability. Fiberglass and composite materials are gaining specification share in healthcare and cleanroom end uses where acoustic attenuation and microbial resistance carry premium weight.
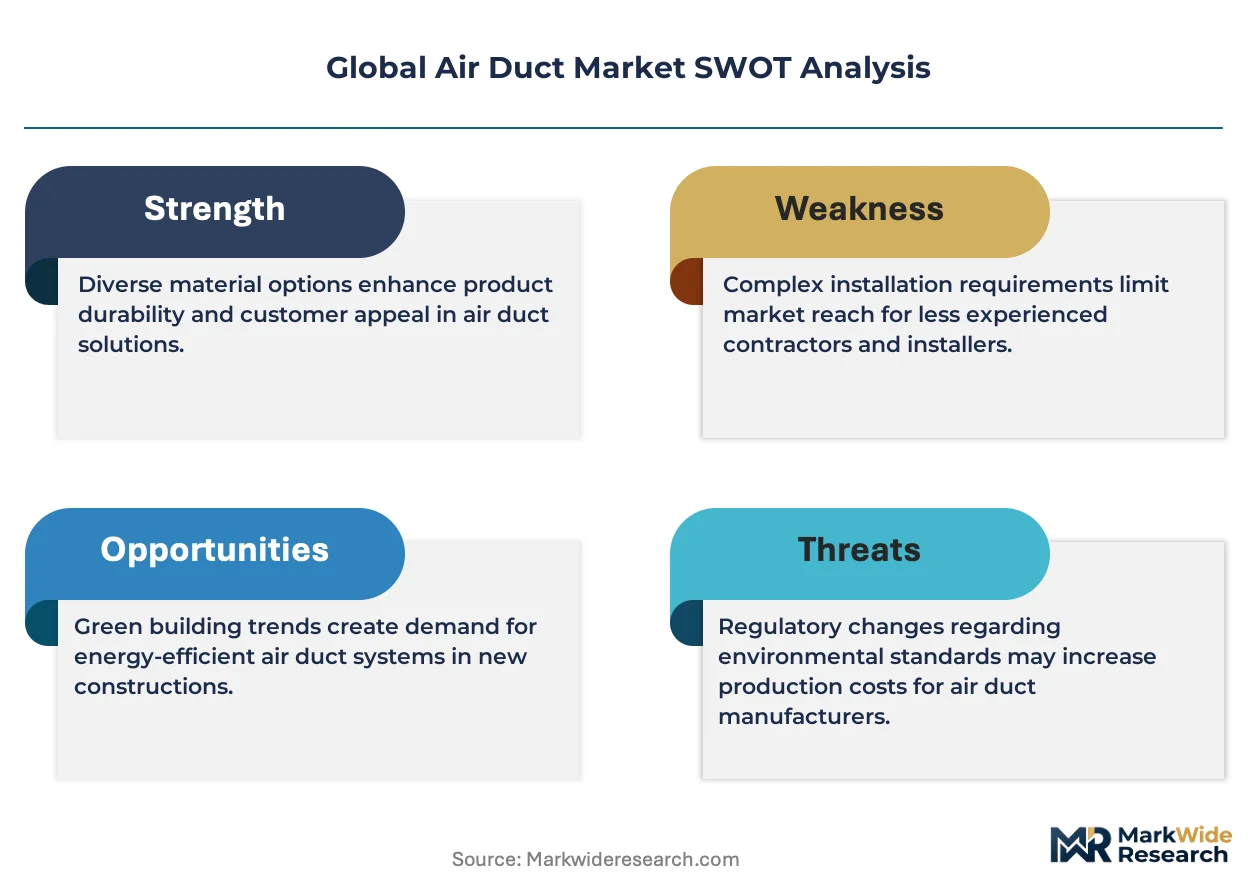
ASHRAE standards, the EU F-Gas Regulation, and China's GB building codes collectively dictate thermal efficiency thresholds, fire-smoke safety classifications, and refrigerant-handling ventilation requirements that determine product compliance and market access. The US EPA and OSHA frameworks further constrain fabrication processes and installation protocols through emissions and workplace exposure limits. Stakeholders must monitor evolving energy performance certifications and cross-border material content rules to anticipate specification shifts before procurement cycles lock.
Market Dynamics
Energy efficiency mandates are compressing product lifecycles across the Global Air Duct Market, forcing manufacturers to accelerate thermal performance upgrades ahead of regulatory deadlines. Building certification programs now specify leakage class ratings that obsolete legacy fabrication standards.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phase-down policies tighten ventilation performance standards across commercial retrofits, accelerating duct replacement cycles in Germany and France.
- Healthcare infrastructure:Acoustic attenuation specifications in hospital HVAC systems pull fiberglass and composite material adoption in surgical suites and imaging facilities.
- China's GB building codes:Green building mandates in tier-one cities specify thermal efficiency thresholds that expand duct system deployments in Shanghai and Shenzhen commercial towers.
Market Restraints
- Steel and aluminum input volatility:Raw material price swings compress fabrication margins, particularly for galvanized steel rigid duct producers serving institutional clients.
- Specialized insulation supply concentration:Polymer composite feedstock production clusters in East Asia create vulnerability for North American and European duct manufacturers.
- Fire-smoke safety classification complexity:Divergent national testing protocols between ASHRAE, EU CPR, and China's GB standards fragment product certification costs.
Strategic Opportunities
- Modular construction channels:Prefabricated duct assemblies for off-site building modules capture specification share in UK and Netherlands commercial developments.
- Lifecycle maintenance contracts:Aftermarket service revenue pools expand as building operators outsource duct cleaning, sealing, and thermal performance monitoring.
- Antimicrobial coating convergence:Integration of silver-ion and photocatalytic surface treatments with fiberglass substrates targets healthcare and pharmaceutical cleanroom specifications.
Industry Challenges
- Sheet metal fabrication skills shortage:Qualified HVAC installers with certified welding and sealing competencies face supply constraints across US and German construction markets.
- Leakage class certification timelines:Third-party testing backlogs for Class A and Class B duct ratings delay product launches and contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Duct Market |
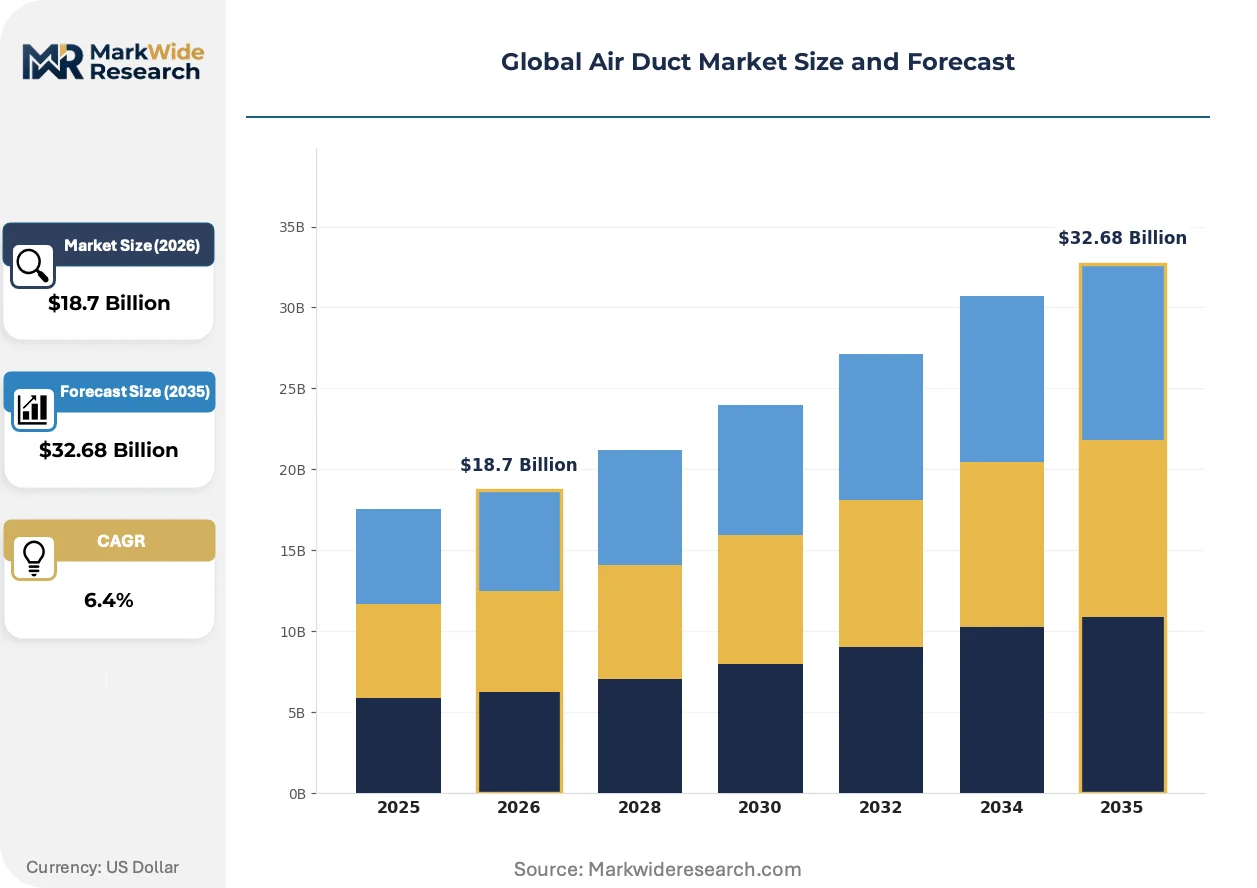
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Ducts, Rigid Ducts, Semi-Rigid Ducts, Spiral Ducts Material: Metal, Plastic, Fiberglass, Composite Installation Type: New Construction, Retrofit, Replacement, Modular End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Lindab Group, Saint-Gobain, Thermaflex, Deflecto, M&M Manufacturing, Novaflex Group, DC Duct & Sheet Metal, Eastern Sheet Metal, Dundas Jafine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Duct Market Emerging Trajectories
Digital fabrication and smart building integration are redefining how duct systems are specified, manufactured, and maintained across commercial and institutional installations.
Pre-insulated phenolic foam duct panels are rendering obsolete traditional sheet-metal-with-wrap insulation assemblies in mid-rise commercial buildings. Facility managers in UK and Australian office markets specify these systems for reduced installation labor and compact ceiling plenum profiles. The technology compresses mechanical contractor bidding margins while shifting value capture toward panel fabricators with CNC cutting capabilities.
China's GB 50365 energy efficiency standards and MIIT green manufacturing directives tighten thermal transmittance requirements for HVAC distribution systems in new construction. These rules accelerate specification of composite and high-performance metal ducts in Beijing and Guangzhou commercial towers. Domestic manufacturers respond by upgrading in-house testing laboratories to reduce third-party certification delays.
Performance-based maintenance agreements now displace traditional equipment-only procurement in US healthcare and education verticals. Building operators in California and Texas negotiate contracts tying contractor payments to measured leakage rates and energy consumption outcomes. This model compresses upfront capital outlays while extending vendor relationships across fifteen-to-twenty year service horizons.
Global Air Duct Market Segmentation
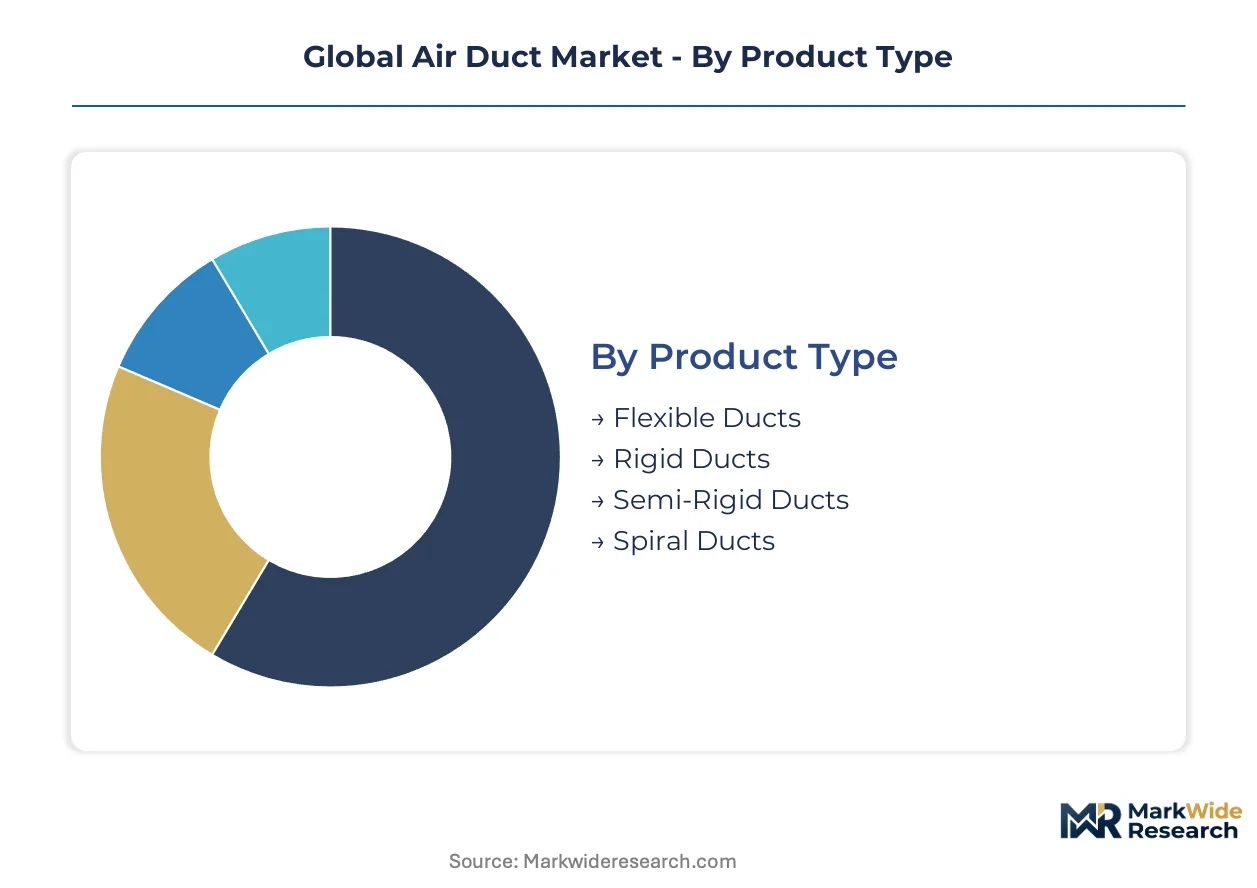
Segmentation in the Global Air Duct Market determines service attach rates and lifecycle revenue capture. Product architecture, material selection, and installation context dictate maintenance intensity and replacement frequency across customer verticals.
Product Type:
After-sales-service intensity varies sharply by duct architecture, with rigid systems demanding scheduled inspection protocols and flexible configurations requiring periodic replacement rather than repair.
- Flexible Ducts:Polymer-jacketed assemblies with wire reinforcement enable complex routing through confined ceiling plenums. Residential retrofits in Germany and France specify these for apartment HVAC upgrades under EU F-Gas Regulation timelines, though thermal degradation limits service life to 10-15 years.
- Rigid Ducts:Galvanized steel or aluminum rectangular and round sections deliver fire-rated performance with ASHRAE-specified leakage class ratings. Commercial towers in Shanghai and Shenzhen mandate rigid fabrication for high-pressure primary distribution, anchoring long-term sealing and cleaning service contracts.
- Semi-Rigid Ducts:Aluminum composite hybrids balance install flexibility with shape retention for light commercial applications.
- Spiral Ducts:Helically wound metal construction optimizes airflow efficiency in industrial ventilation and cleanroom specifications.
Rigid ducts hold the largest share; momentum sits with flexible configurations in residential retrofit channels.
Material:
Cost tier stratification separates commodity metal fabrication from premium composite systems with antimicrobial and acoustic performance specifications.
- Metal:Galvanized steel and aluminum dominate commercial and institutional specifications where fire resistance and structural integrity are codified. US healthcare facilities specify metal construction for operating room ventilation under ASHRAE 170 standards, though raw material volatility compresses fabrication margins.
- Fiberglass:Rigid and flexible fiberglass substrates deliver acoustic attenuation and thermal insulation in a single assembly. Hospital surgical suites and imaging facilities in Texas and California specify fiberglass for noise control compliance, pulling demand toward antimicrobial-coated variants.
- Plastic:PVC and polymer formulations serve residential and light commercial applications with corrosion resistance.
- Composite:Phenolic foam and multi-layer laminates target high-performance commercial specifications with reduced weight.
Metal construction commands the largest installed base; fiberglass is climbing the fastest in healthcare verticals.
Installation Type:
Application context determines project scale, margin structure, and the balance between equipment revenue and labor-intensive installation services.
- New Construction:Greenfield commercial and residential developments enable optimized duct routing and integrated building automation. Tier-one Chinese cities specify high-efficiency distribution systems under GB 50365 standards, with Beijing and Guangzhou towers requiring thermal transmittance certification before occupancy approval.
- Retrofit:Existing building HVAC upgrades accelerate replacement cycles where legacy systems fail leakage class thresholds. UK office markets specify pre-insulated phenolic panels for mid-rise retrofits, compressing mechanical contractor labor hours while shifting value to panel fabricators.
- Replacement:End-of-life system swaps in residential and light commercial segments prioritize speed and minimal disruption.
- Modular:Off-site fabricated duct assemblies for prefabricated building modules capture specification share in Netherlands commercial developments.
New construction retains the largest project volume; modular installation is gaining share fastest in Northern European markets.
End User:
Customer type dictates specification sophistication, compliance burden, and the prevalence of performance-based maintenance contracting.
- Commercial:Office towers, retail complexes, and hospitality facilities specify leakage class ratings and thermal efficiency metrics. California and Texas building operators negotiate outcome-based maintenance agreements tying contractor payments to measured energy consumption, extending vendor relationships across fifteen-to-twenty year horizons.
- Institutional:Hospitals, schools, and government facilities impose fire-smoke safety and acoustic standards that obsolete commodity products. Surgical suites in US healthcare systems require fiberglass with silver-ion antimicrobial coatings, creating specification premiums for compliant fabricators.
- Residential:Single-family and multi-family housing prioritizes cost-efficient flexible duct routing and rapid installation.
- Industrial:Manufacturing and process facilities demand corrosion-resistant and high-velocity duct systems for exhaust and ventilation.
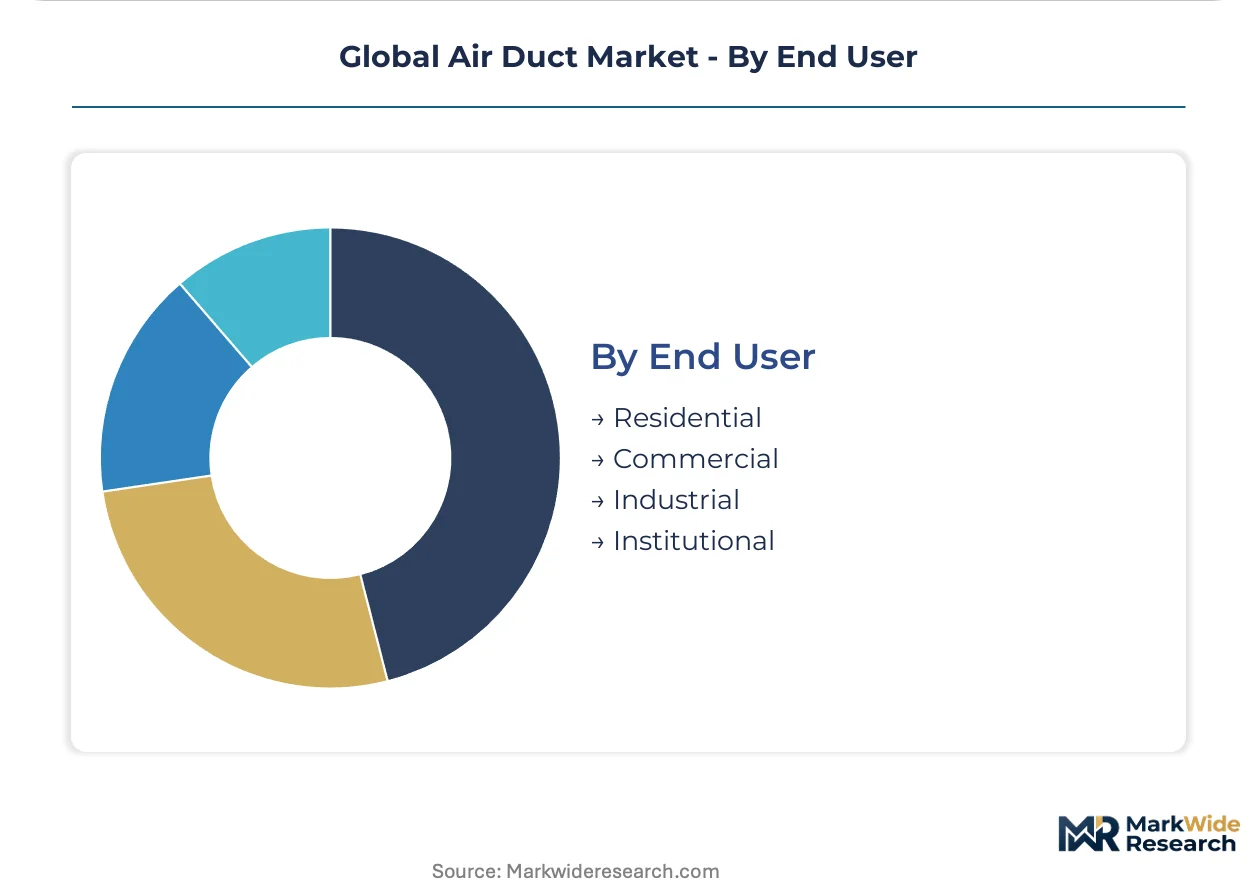
Commercial verticals hold the largest share; institutional specifications are expanding most quickly under healthcare infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France exhibit the lowest price elasticity, accepting premium rigid duct systems to meet EU F-Gas Regulation compliance deadlines. Chinese and Indian buyers show higher sensitivity, prioritizing cost-efficient flexible configurations despite shorter replacement cycles.
United States
Healthcare infrastructure investment drives fiberglass duct specification in Texas and California surgical facilities. ASHRAE 170 standards mandate antimicrobial performance for operating room ventilation. Los Angeles and Houston clusters concentrate fabrication capacity serving institutional retrofit channels.
Germany
Commercial building retrofits accelerate rigid duct replacement under EU F-Gas refrigerant-phase-down timelines. REACH compliance constrains polymer composite feedstock selection for flexible systems. The Ruhr industrial corridor anchors sheet metal fabrication serving Northern European export markets.
China
GB 50365 energy efficiency standards tighten thermal transmittance thresholds for new commercial towers. MIIT green manufacturing directives push domestic fabricators toward in-house testing laboratory upgrades. Shanghai and Shenzhen construction markets specify high-performance distribution systems for tier-one city occupancy approvals.
United Kingdom
Modular construction adoption pulls prefabricated duct assembly demand in London and Birmingham commercial developments. Building Regulations Part L efficiency requirements compress legacy system replacement cycles. The Midlands manufacturing belt concentrates panel fabrication capacity for phenolic foam distribution systems.
India
Urban commercial construction in Mumbai and Bangalore expands rigid metal duct deployment for high-rise HVAC distribution. Bureau of Indian Standards fire safety classifications fragment product certification pathways. The Delhi-NCR corridor concentrates fabrication capacity serving institutional and hospitality verticals.
Global Air Duct Market Vendor Landscape
Capability concentration sits with specialized fabricators holding captive testing laboratory access; scale advantage sits with diversified building materials conglomerates with multi-regional distribution networks. The market structures around three tiers: premium composite specialists, mid-market metal fabricators, and commodity flexible duct producers. Dominant competitive moves include backward integration into polymer feedstock production and geographic expansion through distribution network acquisition.
Within the metal fabrication tier, Lindab Group exemplifies the Northern European specialist archetype with captive distribution infrastructure. Saint-Gobain occupies a position representing materials science diversification into fiberglass composite systems. Thermaflex anchors the flexible insulation specialist segment competing on thermal efficiency metrics.
| Leading Market Players |
|---|
| Lindab Group |
| Saint-Gobain |
| Thermaflex |
| Deflecto |
| M&M Manufacturing |
| Novaflex Group |
| DC Duct & Sheet Metal |
| Eastern Sheet Metal |
| Dundas Jafine |
| Others |
Supply Flow & Price Mechanics
Steel and aluminum input volatility compresses fabrication margins across galvanized metal duct tiers while simultaneously forcing geographic sourcing consolidation toward East Asian smelter networks. This commodity exposure widens pricing spreads between rigid metal systems and flexible polymer alternatives as manufacturers pass through cost fluctuations unevenly across product architectures.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement channels in Germany and France where EU F-Gas Regulation compliance deadlines anchor multi-year rigid duct supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates antimicrobial-coated fiberglass for healthcare from commodity galvanized steel and residential flexible configurations. Cost compression in standard metal tiers intensifies because raw material volatility outpaces contract renegotiation cycles. Residential retrofit buyers in India exhibit highest price sensitivity while German commercial operators accept premium rigid specifications with bundled lifecycle maintenance.
Supply Chain Analysis
Tariff exposure between China and North American markets dominates supply chain risk calculations for polymer composite feedstock procurement. Manufacturing concentration clusters in China, South Korea, and Germany with polymer-jacketed flexible duct production drawing from East Asian petrochemical complexes. Single-source vulnerability concentrates in specialized phenolic foam insulation substrates where limited qualified suppliers serve European prefabrication demand. Distribution runs through captive networks for premium metal fabricators and open wholesale channels for commodity flexible producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Air Duct Market functions as a defensive-moat industry where regulatory certification entrenchment creates durable switching costs for institutional specification holders. Building code compliance timelines and leakage class testing backlogs protect incumbent positions against rapid competitive displacement.
For Market Incumbents: Entrench positions through backward integration into polymer feedstock production and captive testing laboratory accreditation to compress third-party certification delays. Capacity addition in Shanghai and Shenzhen addresses Chinese green building mandate growth while insulating against REACH-compliant feedstock constraints threatening European flexible system margins.
For New Entrants and Emerging Players: India's tier-two urban commercial construction represents the most penetrable white-space target where Bureau of Indian Standards fire safety fragmentation creates specification arbitrage opportunities for mid-market metal fabricators. Modular construction channels in Netherlands and UK commercial developments offer project-based entry with lower incumbent channel lock-in.
For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant-phase-down timelines reshape the acquisition landscape toward rigid duct specialists with proven Class A leakage certification and established German distribution infrastructure. Watch for MIIT green manufacturing directive enforcement intensity in China as the signal indicating domestic fabrication upgrade investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive supply of REACH-compliant composites insulates margin compression from East Asian petrochemical volatility. |
| In-House Testing Laboratory Accreditation | GB 50365 and ASHRAE leakage class certification delays compress from months to weeks for qualified facilities. |
| Lifecycle Maintenance Contract Expansion | Performance-based agreements in California healthcare extend vendor relationships across fifteen-to-twenty year horizons. |
| Antimicrobial Coating Integration | Silver-ion surface treatments on fiberglass capture surgical suite specifications under ASHRAE 170 standards. |
| Modular Prefabrication Capacity Buildout | Off-site duct assembly for UK Building Regulations Part L compliance captures mid-rise commercial retrofit share. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with HVAC mechanical contractors, facilities managers at hospital systems, procurement leads at commercial real estate developers, and distribution channel partners across Northern European and North American markets. Secondary validation drew from ASHRAE standard documentation, EU F-Gas Regulation implementation guidance, China's GB building code filings, customs trade data for steel and aluminum duct exports, and SEC disclosures from listed building materials conglomerates. Bottom-up project pipeline assessment triangulated against top-down construction spend allocation models.
Calibration against historical leakage class certification timelines and retrofit replacement cycle data anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, material composition, installation context, and end-use vertical with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to construction spend elasticity coefficients and energy efficiency mandate enforcement schedules. Industry-specific inputs incorporated EU refrigerant-phase-down implementation pacing and Chinese tier-one city green building occupancy approval throughput.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese domestic producers or rapid antimicrobial coating technology shifts would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Strip Warmer Market