
 Europe Air to Water Heat Pump Market | 2026-2036
Europe Air to Water Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air to Water Heat Pump Market Analysis
Multi-sourcing of compressor and heat exchanger supply is broadening as European OEMs reduce dependency on single-component vendors. Daikin leverages captive inverter manufacturing to sustain margin control across Nordic distribution channels. Vaillant Group anchors its position through dedicated hydronic system integration, while NIBE Group specializes in modular tank architectures that compete effectively in Scandinavian residential retrofits.
Europe air to water heat pump systems transfer ambient thermal energy to hydronic distribution networks using refrigerant cycles with typical coefficient of performance ratings between three and five at standard conditions, serving residential and commercial space heating and domestic hot water production. Monobloc configurations lead volume deployment due to simplified outdoor-only installation requirements, while inverter technology captures expanding share as variable-speed modulation aligns with European seasonal efficiency metrics. Split architectures retain structural importance in dense urban retrofits where indoor unit placement flexibility governs project feasibility.
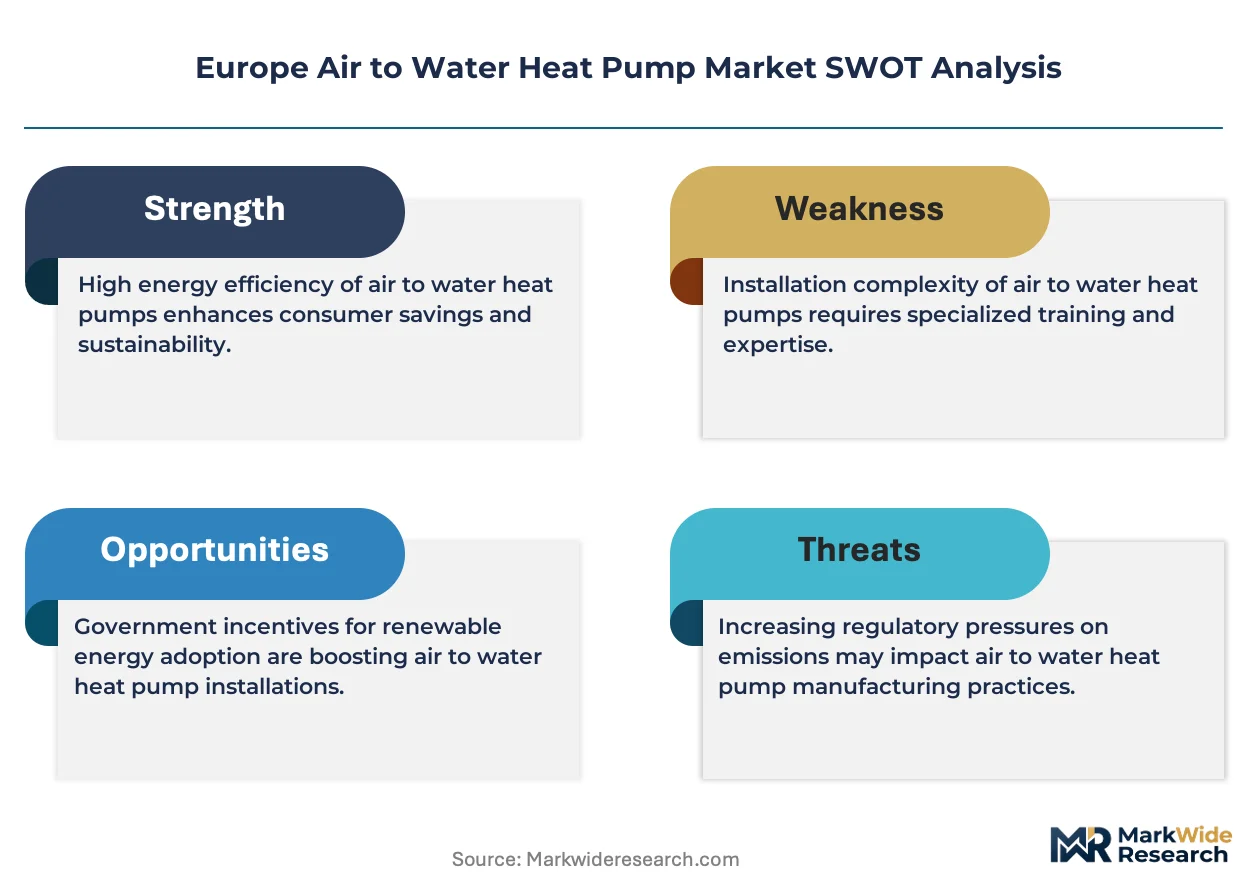
The EU Green Deal, F-Gas Regulation, and CE marking under the Ecodesign Directive collectively mandate minimum seasonal performance factors and restrict high-global-warming-potential refrigerants, reshaping product development roadmaps and import compliance costs. EMA-aligned energy performance certificates in member states now directly influence consumer subsidy eligibility and financing access. Stakeholders must monitor refrigerant transition timelines and national building code harmonization to anticipate which technology configurations will secure preferential regulatory treatment.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing refrigerant choices and mandating higher seasonal performance factors, forcing OEMs to redesign heat exchanger architectures and inverter control logic while installers scramble to certify on low-GWP refrigerant handling.
Growth Catalysts
- Building stock renovation mandates:The EU Green Deal requires member states to double renovation rates by 2030, directing subsidy flows toward fossil-fuel replacements in single-family housing across Germany and France.
- F-Gas phasedown schedules:The regulation's quota system is accelerating R-32 and R-290 adoption, creating replacement demand for legacy R-410A systems in Scandinavian and Baltic markets.
- Heat pump readiness standards:New construction in the Netherlands and Austria must pre-install hydronic distribution compatible with air-to-water units, embedding future demand into building permits.
Market Restraints
- Copper and rare-earth input volatility:Compressor motor laminations depend on neodymium prices indexed to Chinese export quotas, squeezing margin predictability for mid-tier OEMs.
- Installer capacity concentration:Certified refrigeration technicians cluster in Germany and northern Italy, leaving Iberian and eastern European markets underserved during peak retrofit seasons.
- Natural gas price anchoring:Residential consumers in Poland and Hungary benchmark operating costs against subsidized piped gas, delaying payback calculations even with national incentives.
Strategic Opportunities
- Multi-family hydronic retrofits:District heating conversions in Denmark and Sweden create demand for centralized air-to-water plants serving 50-plus unit buildings with shared buffer tanks.
- Hybrid heat pump-gas boiler systems:The German BEG subsidy program now covers bivalent installations, opening transitional pathways for conservative renovators unwilling to abandon fossil backup entirely.
- Installer certification platforms:Digital training networks addressing the F-Gas certification gap in Romania and Bulgaria can capture distribution relationships before incumbent OEMs establish local academies.
Industry Challenges
- Refrigerant handling credential scarcity:The F-Gas Regulation's person certification requirements outpace vocational training capacity in southern and eastern Europe, delaying project starts.
- Legacy hydronic integration complexity:Victorian-era radiator systems in UK terraced housing require flow temperature upgrades or emitter replacements, extending sales-to-commissioning timelines.
- Seasonal performance verification:Ecodesign Directive testing protocols differ from real-world seasonal coefficient of performance, exposing OEMs to warranty claims and reputational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air to Water Heat Pump Market |
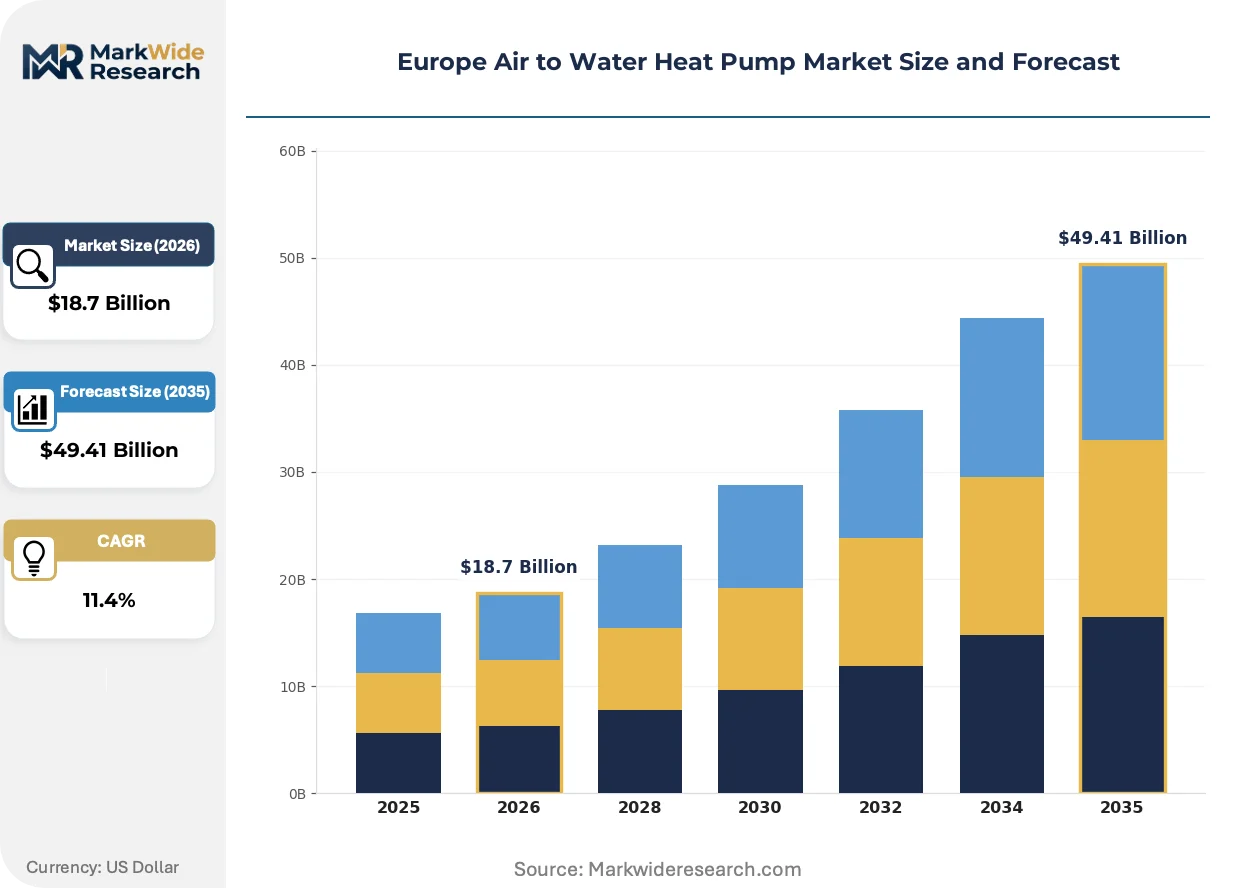
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monobloc, Split, Hybrid, Integrated End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Retrofitting, Upgrades, Replacement Technology: Inverter, Non-Inverter, Smart Control, Scroll Compressor |
| Companies Covered | Daikin, Vaillant Group, NIBE Group, Bosch Thermotechnology, Mitsubishi Electric, Carrier, Panasonic, Stiebel Eltron, Viessmann Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air to Water Heat Pump Market Emerging Trajectories
Inverter modulation and refrigerant chemistry are converging to redefine system efficiency benchmarks, while distribution channels fragment between traditional HVAC wholesalers and direct-to-installer digital platforms.
R-290 (propane) refrigerant circuits are consolidating in monobloc outdoor units designed for sub-150 gram charge limits, sidestepping indoor leak detection requirements. German and Austrian OEMs are adopting these architectures fastest, betting on simplified regulatory compliance. The technology is consolidating competitive positioning around charge minimization rather than pure thermodynamic efficiency.
The F-Gas Regulation's phasedown mechanism tightens HFC quota allocations annually, forcing importers to secure refrigerant supply contracts before seasonal production ramps. This policy is compressing inventory planning horizons and favoring OEMs with captive fluorochemical supply agreements. Nordic markets with earlier R-32 transitions are now least exposed to quota volatility.
Single-family renovators increasingly demand packaged solutions combining heat pump, buffer tank, and smart controls through single-source procurement. Traditional wholesaler channels lose share to OEM-direct portals offering configuration tools and installer matching. France and Belgium exhibit the fastest channel migration, where national subsidy portals integrate directly with manufacturer quoting systems.
Europe Air to Water Heat Pump Market Segmentation
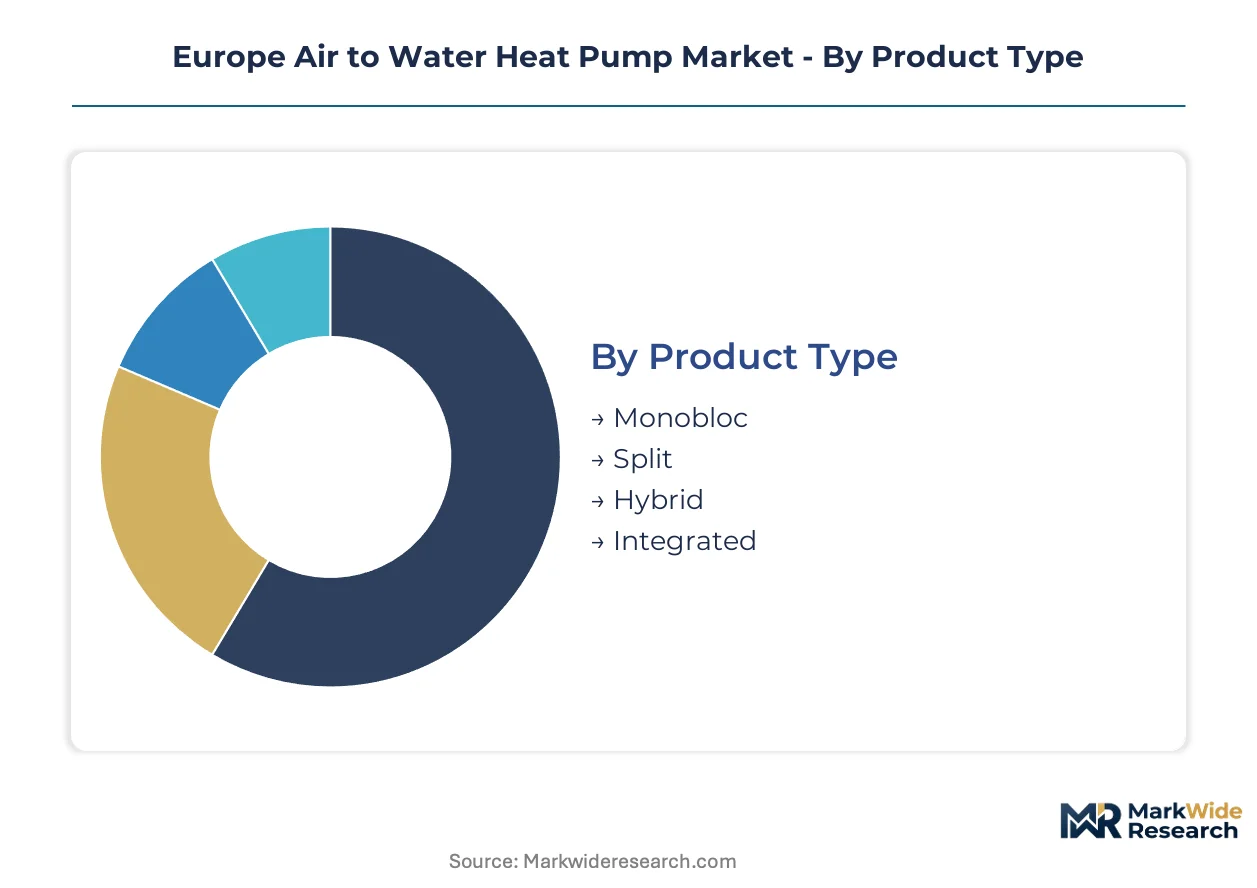
Product configuration, end-use application, and installation context determine unit specifications, refrigerant charge limits, and distribution channel requirements across European markets. Segmentation reveals where inverter technology and monobloc architectures concentrate margin capture versus where split systems and hybrid configurations retain structural importance.
Product Type:
Component sourcing for heat exchangers and compressors clusters around German and Italian suppliers, with refrigerant circuit design driving final assembly location decisions.
- Monobloc:Self-contained outdoor units house the complete refrigeration cycle, eliminating indoor refrigerant lines and simplifying F-Gas compliance for installers. Single-family renovators in Germany and France absorb concentrated volumes as the EU Green Deal tightens building decarbonization mandates for fossil-fuel replacements.
- Split:Separated indoor and outdoor modules connect via refrigerant piping, enabling flexible placement in dense urban retrofits where outdoor space constraints govern feasibility. Victorian terraced housing in the UK and apartment blocks in Paris and Milan retain structural demand for this architecture.
- Hybrid:Bivalent systems pair air-to-water heat pumps with retained gas boiler backup, qualifying for German BEG subsidies while addressing conservative renovator risk aversion.
- Integrated:Factory-matched combinations of heat pump, buffer tank, and hydronic controls ship as single SKU solutions, gaining traction in Belgian and French direct-to-installer digital channels.
Monobloc absorbs the bulk of installed capacity; integrated systems are expanding most quickly through OEM-direct procurement portals.
End User:
Customer type dictates unit scale, seasonal performance factor requirements, and subsidy eligibility pathways under national implementations of EU directives.
- Residential:Single-family and multi-family dwellings drive volume deployment, with EPC-linked financing in France and the Netherlands conditioning purchase decisions on seasonal efficiency ratings.
- Commercial:Hotels, offices, and retail spaces require higher kilowatt outputs and demand multi-unit cascade configurations, particularly in Nordic markets with district heating conversion timelines.
- Industrial:Process heat applications and warehouse heating utilize mid-scale air-to-water systems where waste heat recovery integration affects project economics.
- Institutional:Schools, hospitals, and municipal buildings face public procurement rules that extend vendor qualification timelines while embedding Ecodesign Directive compliance into tender specifications.
Residential commands absolute volume; commercial applications show the steepest expansion trajectory as building renovation mandates intensify across member states.
Installation Type:
Project context determines labor skill requirements, timeline compression, and the viability of legacy hydronic integration versus complete system replacement.
- New Construction:Heat pump readiness standards in the Netherlands and Austria mandate pre-installed hydronic distribution, embedding future air-to-water demand into building permits before equipment selection occurs.
- Retrofitting:Existing building stock renovations dominate German and French markets, with installer capacity bottlenecks during peak seasons constraining realized volume despite subsidy availability.
- Upgrades:Partial system enhancements targeting efficiency improvements or refrigerant transitions concentrate in Scandinavian markets with earlier R-32 adoption curves.
- Replacement:End-of-life swaps for legacy R-410A systems accelerate under F-Gas quota pressure, particularly in Baltic states where import dependency heightens refrigerant supply risk.
Retrofitting carries the majority of current deployment; new construction is gaining share fastest through regulatory embedding of heat pump compatibility.
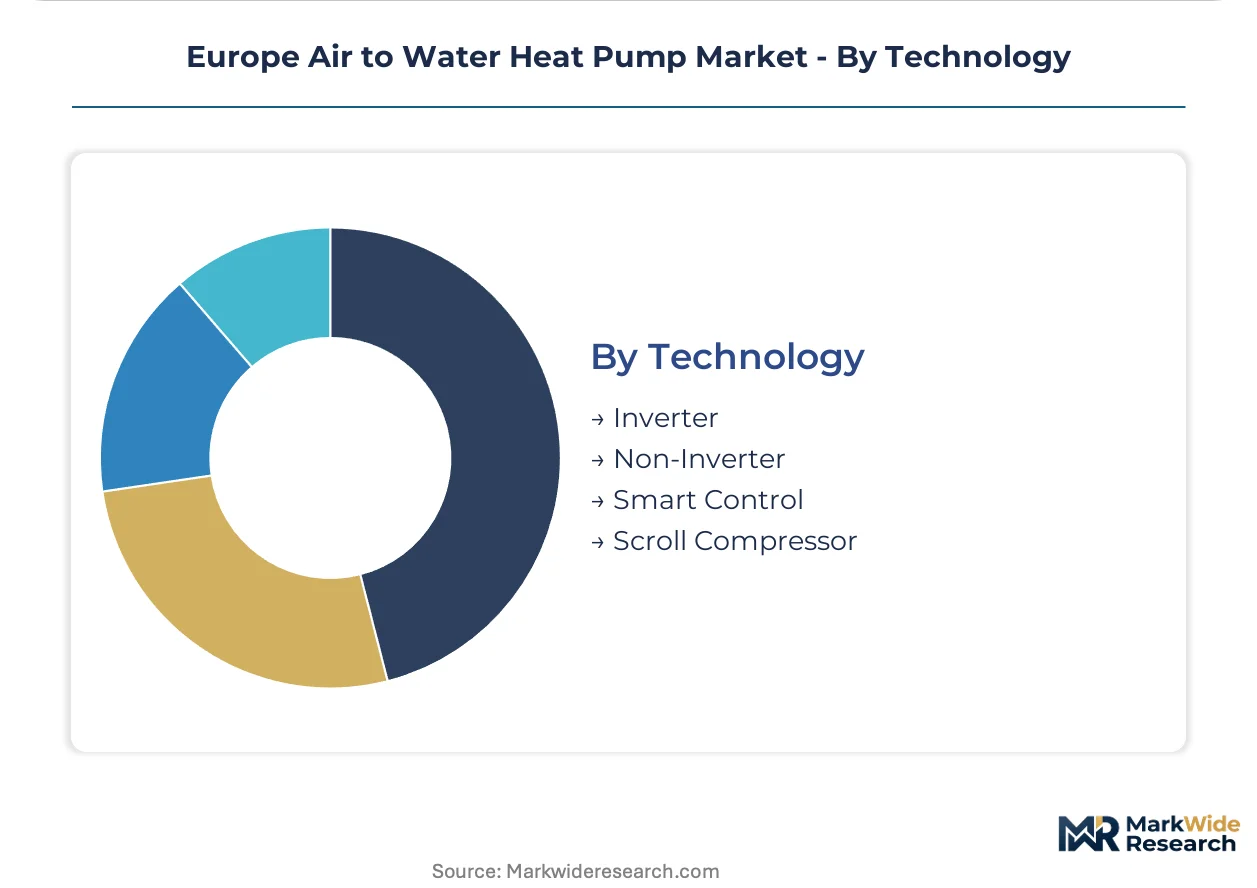
Technology:
Inverter manufacturing capability and refrigerant chemistry choices concentrate competitive differentiation among OEMs with captive component production or exclusive fluorochemical supply agreements.
- Inverter:Variable-speed modulation aligns with European seasonal efficiency metrics, capturing expanding share as EMA-aligned energy performance certificates directly influence consumer subsidy eligibility.
- Non-Inverter:Fixed-speed compressors retain cost-sensitive niche applications in eastern European markets where natural gas price anchoring delays payback calculations.
- Smart Control:Connected thermostats and predictive optimization algorithms integrate with national demand-response programs in Denmark and Sweden, enabling grid-stabilization revenue streams.
- Scroll Compressor:Refrigerant-agnostic compression technology supports R-290 transition roadmaps while maintaining manufacturing scale economies across product lines.
Inverter technology dominates new installations; smart control integration is climbing the fastest as utility tariff structures evolve toward time-of-use optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium deposits in China's Inner Mongolia and Jiangxi provinces anchor compressor motor supply chains, while European OEMs diversify laminations sourcing through Swedish and German rare-earth processing facilities.
Germany
The BEG subsidy program drives single-family retrofit volumes across Bavaria and North Rhine-Westphalia. The F-Gas Regulation accelerates R-290 adoption timelines for domestic manufacturers. Berlin-Brandenburg clusters host inverter control logic development centers serving Nordic export markets.
France
EPC-linked financing conditions purchase decisions in Île-de-France and Auvergne-Rhône-Alpes. The EU Green Deal implementation mandates fossil-fuel replacement in social housing stock. Lyon-based hydronic system integrators capture renovation project flows from Parisian suburbs.
Sweden
District heating conversion timelines in Stockholm and Gothenburg create centralized plant demand for multi-family buildings. National building codes embed heat pump readiness standards into new construction permits. Malmö manufacturers specialize in modular tank architectures for Baltic export.
Netherlands
Heat pump readiness mandates in Randstad new construction pre-install hydronic distribution networks. The Ecodesign Directive shapes seasonal performance factor requirements for Dutch OEMs. Eindhoven Region clusters concentrate smart control development for demand-response integration.
United Kingdom
Victorian-era radiator retrofit complexity extends sales-to-commissioning timelines in London and Midlands terraced housing. The Boiler Upgrade Scheme channels subsidy flows toward monobloc installations. Scottish installers develop expertise in split-system urban deployments for Glasgow and Edinburgh apartment blocks.
Europe Air to Water Heat Pump Market Vendor Landscape
Global majors compete with regional champions across refrigerant transition roadmaps and inverter manufacturing depth. Japanese and German conglomerates anchor premium-tier positioning through captive component production. Mid-tier European specialists concentrate on hydronic integration and modular tank architectures. Competitive moves cluster around F-Gas certification platform development and direct-to-installer digital channel expansion.
Within the captive manufacturing tier, Daikin and Mitsubishi Electric represent archetypes of backward-integrated compressor and inverter control production. Among European hydronic specialists, Vaillant Group and NIBE Group occupy positions emphasizing system integration and modular storage solutions. Stiebel Eltron exemplifies the mid-scale German fabricant archetype competing on installer certification density and regional distribution relationships.
| Leading Market Players |
|---|
| Daikin |
| Vaillant Group |
| NIBE Group |
| Bosch Thermotechnology |
| Mitsubishi Electric |
| Carrier |
| Panasonic |
| Stiebel Eltron |
| Viessmann Group |
| Others |
Supply Flow & Price Mechanics
Family-owned German hydronic specialists anchor mid-tier pricing discipline through captive component production and installer academy networks, compressing margin elasticity for competitors dependent on outsourced compressor supply. Their ownership structure enables long-term refrigerant transition bets without quarterly earnings pressure, while private-equity-rolled-up distributors in France and Belgium extract working capital efficiencies that feed aggressive direct-to-installer channel pricing.
Pricing Analysis
Warranty and service bundling separates premium OEM positioning from unbundled transactional sales through traditional HVAC wholesalers. Three-tier pricing structure across premium, standard, and economy levels reflects inverter manufacturing depth, CE marking tier, and after-sales service coverage. Pricing pressure stems from copper and rare-earth input volatility squeezing mid-tier fabricants. Eastern European residential renovators exhibit highest price sensitivity due to natural gas price anchoring, while Nordic district heating contractors prioritize seasonal performance factor guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing for compressor motor laminations, exposing European OEMs to export quota disruptions. Component sourcing clusters in Germany, Italy, and China, drawing from copper strip mills, aluminum fin stock, and fluorochemical refrigerant supply. Supply chain risk centers on F-Gas Regulation quota compression tightening inventory planning horizons. Distribution runs through traditional HVAC wholesalers losing share to OEM-direct digital portals in France and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer capacity scarcity props pricing power for certified refrigeration technicians, creating a supply-constrained market where project starts outpace qualified labor availability. This bottleneck sustains margin capture for OEMs with dense training academy networks.
For Market Incumbents: Lock in refrigerant supply contracts before seasonal production ramps, securing captive fluorochemical agreements that shield against F-Gas quota volatility. Expand inverter manufacturing capacity in Berlin-Brandenburg clusters to serve Nordic export demand. Prioritize hydronic system integration depth over pure equipment sales to defend against emerging modular tank specialists.
For New Entrants and Emerging Players: Digital installer certification platforms address the F-Gas credential gap in Romania and Bulgaria, capturing distribution relationships before incumbent OEMs establish local academies. Target Iberian retrofit markets underserved during peak seasons. Pursue hybrid heat pump-gas boiler configurations qualifying for German BEG subsidies as the most penetrable entry wedge.
For Investors and Strategic Acquirers: R-290 monobloc adoption rates crossing threshold penetration in German and Austrian markets is the leading indicator that refrigerant chemistry transition winners are separating from laggards. Five-to-ten year viability favors OEMs with backward-integrated compressor production and captive inverter control logic. Watch Baltic state R-410A replacement acceleration as signal of quota-driven supply stress inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| R-290 Refrigerant Transition | Monobloc architectures sidestep indoor leak detection requirements under F-Gas Regulation, consolidating competitive positioning for German and Austrian OEMs. |
| Installer Certification Platform Buildout | Digital training networks capture distribution relationships in underserved eastern European markets before incumbents establish physical academies. |
| Direct-to-Installer Channel Expansion | OEM-direct portals with configuration tools displace traditional HVAC wholesalers in France and Belgium subsidy integration flows. |
| Hybrid System Configuration Development | Bivalent heat pump-gas boiler combinations qualify for German BEG subsidies while addressing conservative renovator risk aversion. |
| Modular Tank Architecture Specialization | Scandinavian manufacturers leverage factory-matched buffer tank integration to compete in multi-family district heating conversion timelines. |
Methodological Framework
Document review covered EU regulatory filings, F-Gas Regulation quota allocations, national building code implementations, and Ecodesign Directive technical documentation, complemented by interviews with product development executives at European OEMs, HVAC wholesale procurement directors, certified refrigeration technicians, and hydronic system integrators. Secondary validation drew from customs trade data, SEC filings of listed heating equipment manufacturers, and national subsidy program disbursement records. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Output modeling generated volume and value trajectories across product configuration, end-use application, installation context, and technology type dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory mandate timelines. Industry-specific inputs included F-Gas phasedown schedules, national renovation rate targets, and installer certification capacity buildout curves.
Caveats apply where refrigerant supply disruptions, copper price spikes, or installer training bottlenecks could materially shift the outlook beyond modeled assumptions. Forecasts reflect documented regulatory timelines and subsidy program durability assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Hydronic Radiators Market