
 Europe Heating Radiator Market | 2026-2036
Europe Heating Radiator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Heating Radiator Market Insights
The EU Ecodesign Directive is broadening the cost-of-entry calculus for radiator manufacturers by mandating stricter minimum efficiency thresholds and seasonal performance metrics. Vasco Group leverages its low-temperature panel radiator portfolio to meet these standards without sacrificing thermal output. Kermi GmbH anchors its position through backward integration into precision steel pressing and surface coating. Stelrad Limited competes on manufacturing scale, operating one of Europe's largest pressed-steel radiator plants from its UK base.
Europe heating radiators are heat-emitting devices constructed from steel, aluminum, or cast iron, designed to release thermal energy from circulating hot water or electric elements through convection and radiation, typically rated by heat output in watts and operating pressure in bars. Panel radiators dominate volume across residential replacement cycles due to their favorable cost-to-output ratio and compatibility with condensing boilers. Aluminum variants are gaining share in new-build segments where lighter weight and faster response times offset premium positioning. Steel retains margin concentration in commercial specifications requiring higher durability and pressure tolerance.
CE marking under the EU Construction Products Regulation governs structural integrity and thermal performance claims, while national building codes in Germany, France, and Italy layer additional efficiency and installation requirements that fragment compliance pathways. The EU Green Deal's building renovation targets are redirecting public subsidy flows toward high-efficiency heat emitters, tightening the link between regulatory eligibility and product certification. Stakeholders must monitor how the F-Gas Regulation's phase-down of fluorinated refrigerants indirectly reshapes heat pump pairing requirements and radiator specification standards.
Market Dynamics
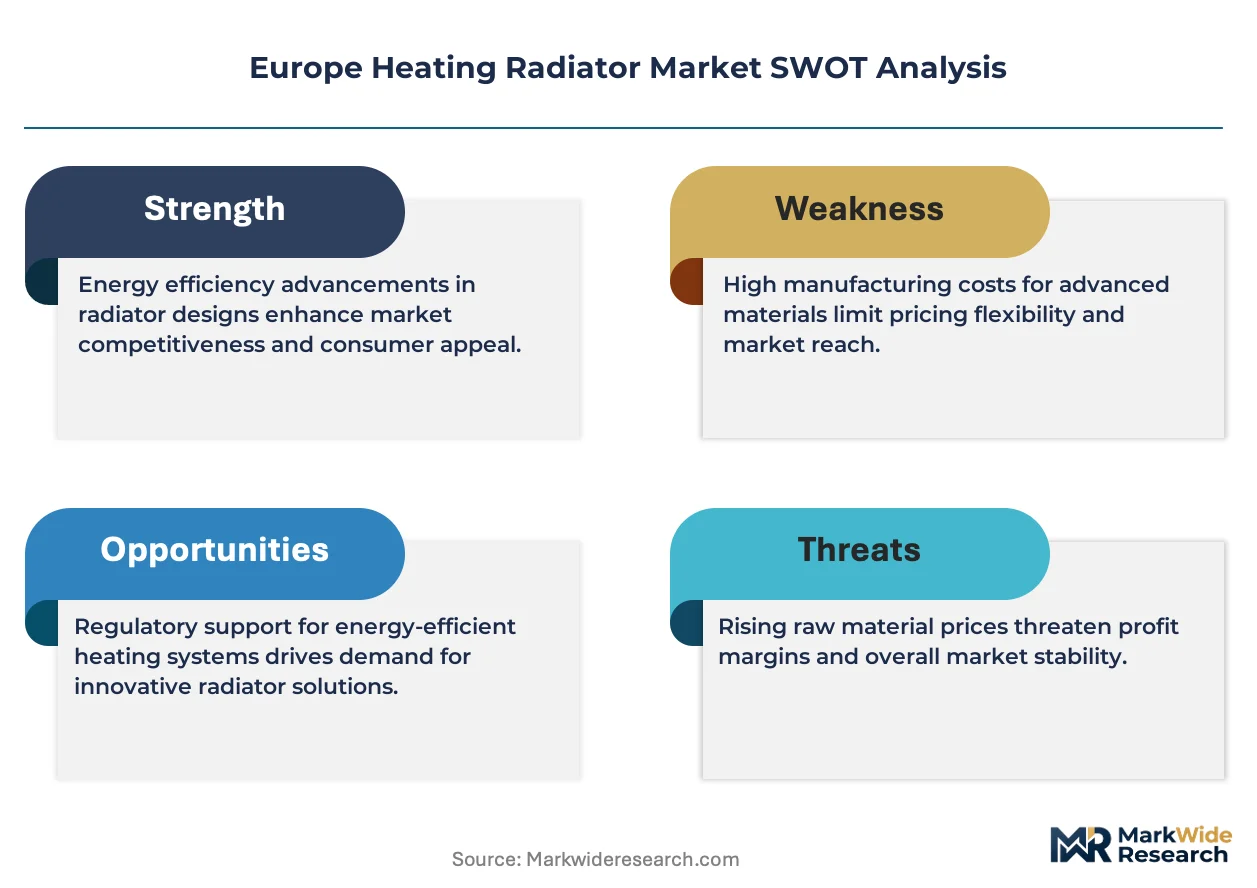
The EU Ecodesign Directive is compressing replacement cycles across European heating systems by disqualifying low-efficiency emitters from subsidy eligibility. This regulatory pressure is redirecting capital toward low-temperature-compatible radiator designs and heat pump pairing requirements.
Growth Catalysts
- EU Green Deal building renovation targets:Member states must double renovation rates, channeling public funds toward certified high-efficiency heat emitters in residential retrofits.
- Heat pump deployment acceleration:Germany's residential sector is replacing fossil-fuel boilers with electric heat pumps that require low-temperature radiators to maintain thermal output.
- Poland's urban construction corridor:Rapid urbanization in Warsaw and Krakow is generating new-build demand for aluminum radiators with faster response characteristics.
Market Restraints
- Steel price volatility:Pressed-steel radiator manufacturers face margin compression from fluctuating hot-rolled coil costs and energy-intensive surface coating inputs.
- Supply concentration in Eastern European pressing:A limited supplier base for precision steel forming equipment creates bottleneck risk for capacity expansion.
- Heat emitter substitution:Underfloor heating systems are capturing floor space in premium new-build segments where screed installation is viable.
Strategic Opportunities
- Romania and Bulgaria retrofit waves:These markets show underpenetrated high-efficiency radiator adoption with EU cohesion funds now accessible for building upgrades.
- Smart thermostatic valve integration:Convergence of IoT sensors with radiator controls enables zone-based energy management for multi-unit residential buildings.
- CE marking plus national certification bundling:Manufacturers can capture margin by pre-certifying products for Germany's BAFA subsidy eligibility alongside baseline compliance.
Industry Challenges
- Welding technician scarcity:Precision steel radiator fabrication requires certified TIG welders that Eastern European labor markets struggle to supply at scale.
- Condensing boiler compatibility testing:Retrofit projects demand validation of existing pipework pressure tolerance, extending sales-to-installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Heating Radiator Market |
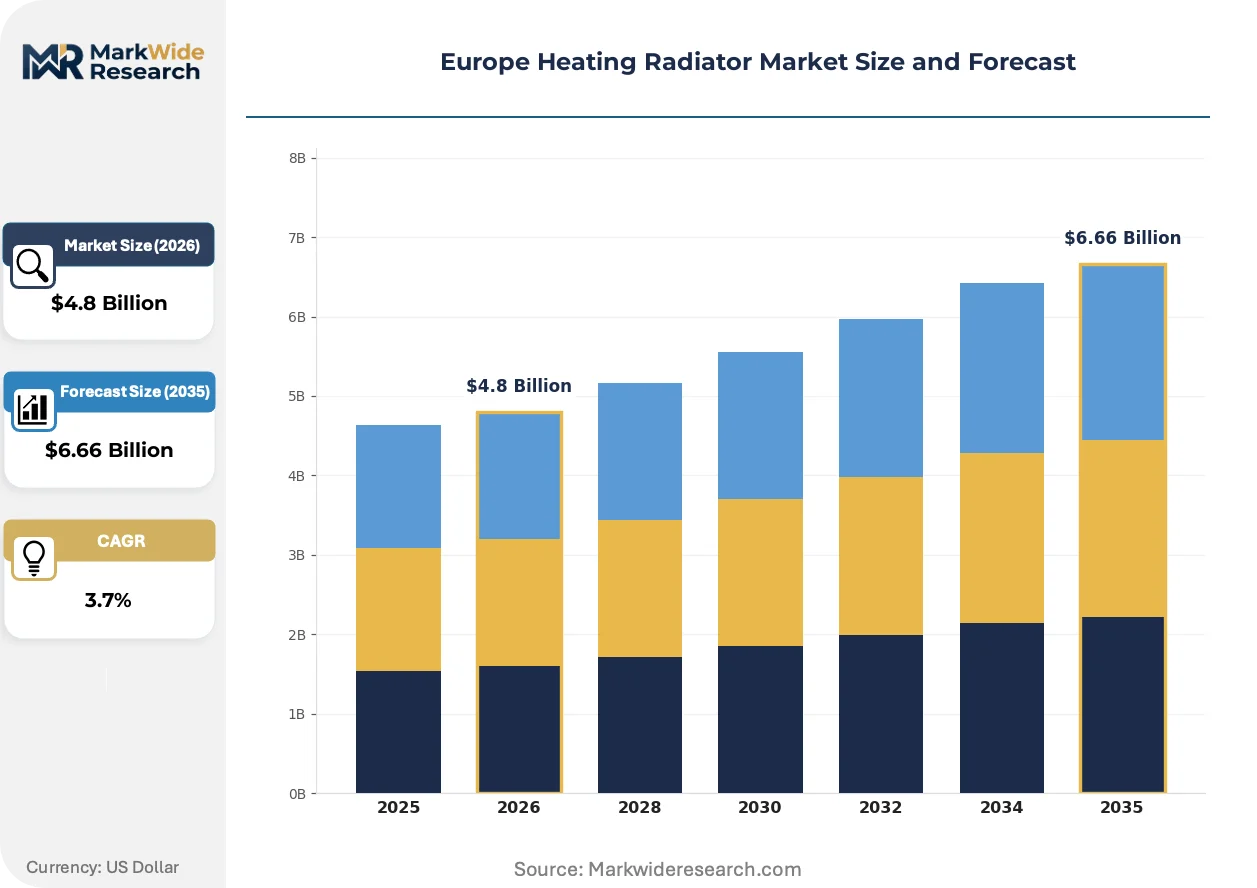
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Radiators, Column Radiators, Electric Radiators, Towel Warmers Material: Steel, Aluminum, Cast Iron, Plastic Installation Type: Wall-Mounted, Freestanding, Integrated, Portable End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Vasco Group, IRSAP S.p.A., Stelrad Limited, Danfoss, Kermi GmbH, Zehnder Group AG, Purmo Group, Arbonia AG, KORADO, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Heating Radiator Market Trends and Innovations
Low-temperature heat emitter design is consolidating market preferences as heat pump adoption accelerates across Northern Europe. Product development now prioritizes thermal output at reduced flow temperatures rather than peak wattage ratings.
Aluminum-cast hybrid radiator construction is consolidating share in new-build specifications where weight reduction and corrosion resistance justify premium positioning. French and Italian developers specify these variants for multi-story residential towers with structural load constraints. The technology is consolidating procurement criteria around lifecycle cost rather than upfront capital expenditure.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules that indirectly reshape heat pump pairing requirements and radiator specification standards. Installers must now verify heat emitter compatibility with lower-temperature heat pump output curves. Germany's Federal Office for Economic Affairs and Export Control has tightened subsidy verification protocols, forcing manufacturers to pre-certify seasonal performance metrics.
Buying committees in social housing authorities are consolidating supplier relationships around framework agreements with multi-year service attachments. Poland's municipal housing associations now bundle radiator replacement with 10-year maintenance contracts. This procurement pattern concentrates volume among manufacturers with captive installation networks and certified service capabilities.
Europe Heating Radiator Market Segmentation
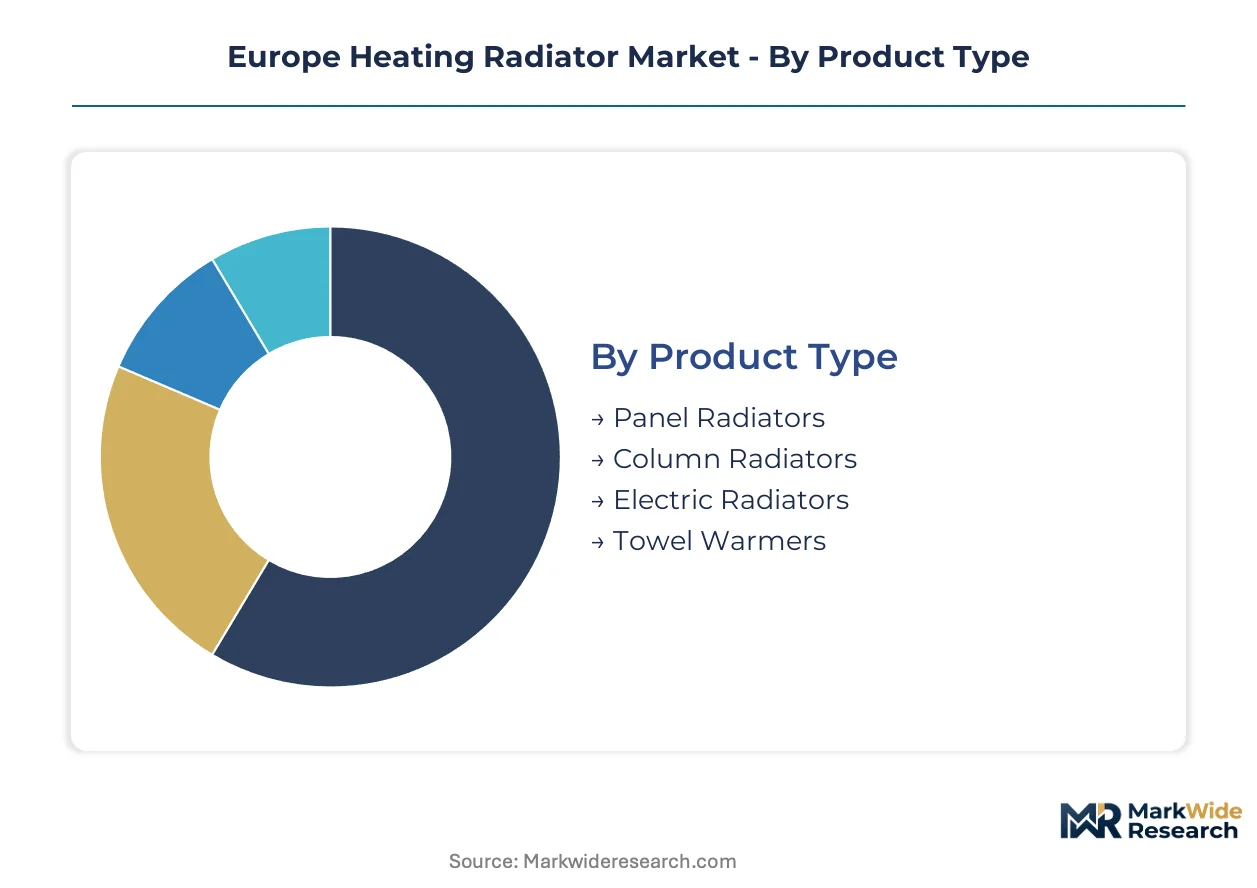
Radiator procurement decisions in Europe hinge on thermal output specifications, installation constraints, and subsidy eligibility tied to efficiency certification. Manufacturers must align production portfolios across material types and mounting configurations to capture diverging demand from residential retrofits versus new-build commercial specifications.
Product Type:
Capital intensity varies sharply across radiator architectures, with pressed-steel panel production demanding the heaviest upfront tooling investment for precision forming and coating lines.
- Panel Radiators:Constructed from layered steel sheets with convective fins, these units dominate replacement cycles in Germany and Poland due to compatibility with condensing boilers and heat pump systems. Residential retrofit programs channel volume toward low-temperature variants that maintain output at reduced flow temperatures.
- Column Radiators:Cast iron or steel sectional designs retain specification in heritage building renovations across France and Italy where aesthetic continuity outweighs efficiency premiums. Higher water content slows response times but extends thermal retention in intermittently heated spaces.
- Electric Radiators:Resistance-element units with programmable controls serve off-grid properties and supplementary heating in UK social housing where gas connection is impractical.
- Towel Warmers:Ladder-style steel or aluminum rails combine space heating with laundry drying in bathroom specifications across Spanish and Portuguese residential developments.
Panel radiators absorb the bulk of installed capacity; electric radiators are expanding most quickly in electrification corridors where heat pump pairing is mandatory.
Material:
Raw material selection determines corrosion resistance, thermal conductivity, and compliance with EU Ecodesign Directive weight-to-output efficiency thresholds.
- Steel:Cold-rolled carbon steel with phosphate pre-treatment and epoxy-polyester powder coating delivers pressure tolerance above 10 bar for commercial specifications. German and UK manufacturers maintain captive pressing capacity to control surface finish quality.
- Aluminum:Die-cast or extruded aluminum alloys enable rapid thermal response and weight reduction for multi-story residential towers in Warsaw and Krakow where structural load limits constrain specification.
- Cast Iron:Traditional sectional construction persists in Eastern European district heating networks where high operating temperatures and water quality variability demand material durability.
- Plastic:Polymer composite housings encase electric heating elements in portable units and budget residential segments where capital cost minimization overrides lifecycle efficiency.
Steel commands the largest production footprint by tonnage; aluminum is climbing the fastest as new-build specifications prioritize weight reduction and heat pump compatibility.
Installation Type:
Mounting configuration shapes distribution channel requirements, with wall-mounted units demanding precise dimensional standardization and freestanding variants requiring floor-load certification.
- Wall-Mounted:Bracket-fixed steel and aluminum panels constitute the default specification across European residential replacement markets, with German DIN standard drilling patterns ensuring interoperability with existing pipework.
- Freestanding:Column and designer radiators on floor feet serve retrofit projects where wall structural integrity is compromised or heritage preservation restricts drilling.
- Integrated:Built-in convectors and trench heating systems embed within floor slabs or window walls in Scandinavian commercial specifications where glazed facades dominate heat loss calculations.
- Portable:Plug-in electric units with caster mobility address temporary heating needs in UK rental markets and construction-phase site offices.
Wall-mounted systems anchor manufacturing volume; integrated solutions are gaining share fastest in premium commercial segments where architectural integration is valued.
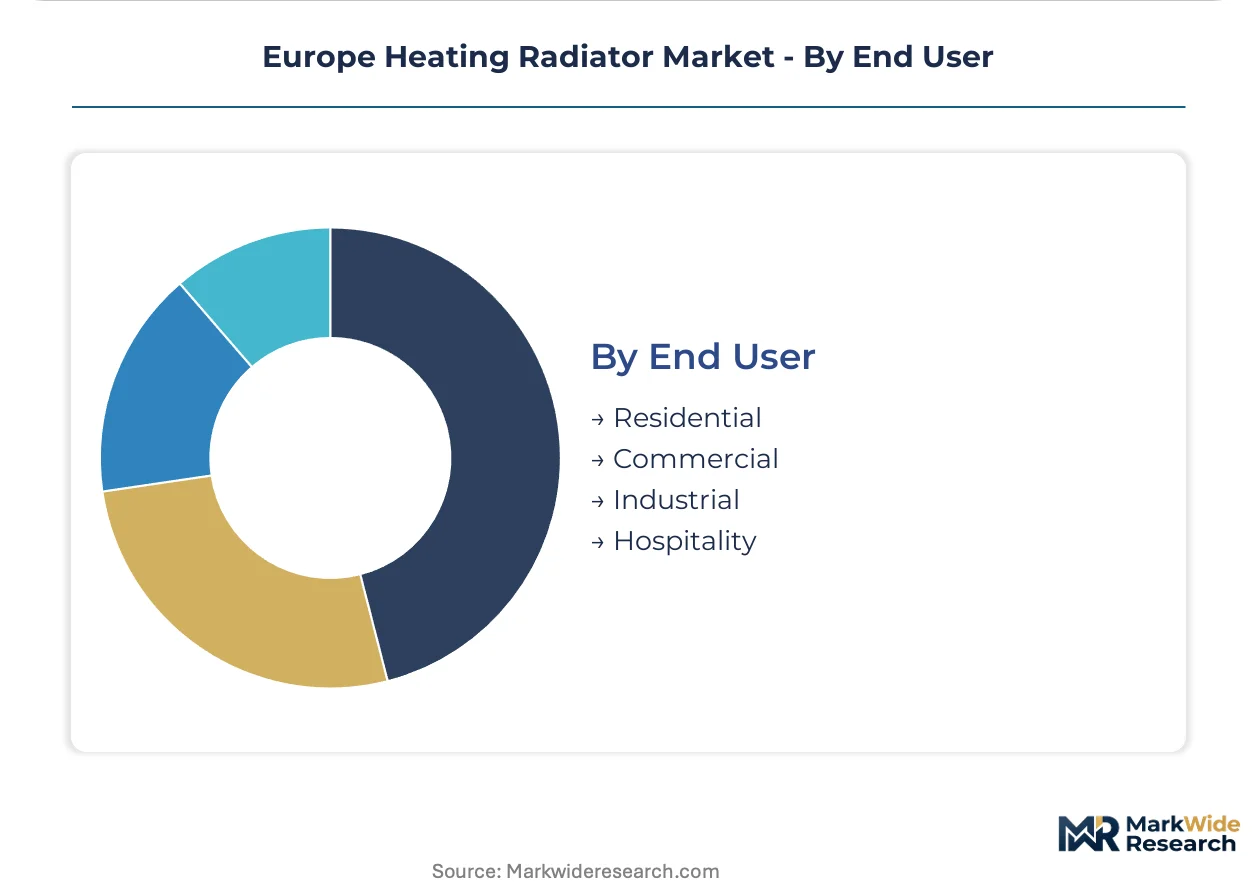
End User:
Customer type determines pricing tolerance, certification requirements, and service attachment expectations, with social housing authorities imposing the most stringent framework agreement terms.
- Residential:Single-family and multi-unit dwellings drive replacement cycles across Germany, Poland, and Romania where EU cohesion funds subsidize efficiency upgrades. Homeowners prioritize low-temperature compatibility for heat pump pairing.
- Commercial:Office and retail specifications demand zonal control integration and 15-year lifecycle warranties, with French and Italian developers specifying aluminum-cast hybrids for load-constrained structures.
- Industrial:Manufacturing facilities and warehouses require high-output units with enhanced corrosion resistance for aggressive atmospheres, typically sourced through MRO procurement channels.
- Hospitality:Hotels and serviced apartments specify designer towel warmers and low-surface-temperature variants to balance guest comfort with liability mitigation.
Residential applications hold the greatest installed base; commercial end-use is expanding most rapidly as building renovation targets tighten across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones attract radiator manufacturers through tax holidays and infrastructure subsidies, concentrating new production capacity near Warsaw and Krakow. These zones redirect investment flows from Western European legacy sites toward lower-cost fabrication clusters with EU cohesion fund access.
Germany
Federal subsidies for building energy efficiency under the BAFA program accelerate residential radiator replacement cycles. The Federal Office for Economic Affairs and Export Control tightened verification protocols for seasonal performance metrics. Manufacturing clusters in North Rhine-Westphalia and Bavaria supply low-temperature panel designs for heat pump pairing.
Poland
Rapid urbanization in Warsaw and Krakow generates new-build demand for aluminum radiators with faster thermal response characteristics. EU cohesion funds now finance municipal housing association retrofits with 10-year maintenance contract bundles. Silesian manufacturing corridors host precision steel pressing operations serving German and Czech markets.
France
Social housing authorities consolidate procurement through framework agreements demanding multi-year service attachments. ANSM and national building codes layer efficiency requirements atop CE marking baseline compliance. Lyon and Marseille developers specify aluminum-cast hybrid radiators for multi-story towers with structural load constraints.
Italy
Heritage building renovations across Lombardy and Veneto sustain demand for column radiators where aesthetic continuity outweighs efficiency premiums. National building codes fragment compliance pathways beyond EU Construction Products Regulation standards. Emilia-Romagna fabricators specialize in cast iron sectional designs for district heating networks.
United Kingdom
Social housing electrification programs expand electric radiator deployment where gas connection is impractical. Stelrad Limited operates one of Europe's largest pressed-steel radiator plants from its UK base. Midlands manufacturing clusters serve replacement cycles driven by condensing boiler upgrades and retrofit efficiency targets.
Europe Heating Radiator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material and configuration segments. The vendor base organizes into three tiers: integrated steel pressers with captive coating capacity, aluminum die-casters serving new-build weight constraints, and electric element assemblers for off-grid applications. Dominant competitive moves include backward integration into precision forming equipment and pre-certification bundling for national subsidy eligibility alongside baseline CE marking.
Among German-based fabricators, Kermi GmbH and Zehnder Group AG exemplify the premium-tier archetype through precision engineering positioning. Vasco Group represents the low-temperature specialization vector with Belgian origins. These three occupy positions within a structure where geographic proximity to subsidy administration centers and captive installation networks determine framework agreement access.
| Leading Market Players |
|---|
| Vasco Group |
| IRSAP S.p.A. |
| Stelrad Limited |
| Danfoss |
| Kermi GmbH |
| Zehnder Group AG |
| Purmo Group |
| Arbonia AG |
| KORADO |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between BAFA-eligible low-temperature designs and baseline CE-marked units splits pricing power across German and Polish procurement channels while concentrating premium supply among captive pressing operations in North Rhine-Westphalia and Silesia. This divergence feeds back into raw material sourcing, where hot-rolled coil contracts for efficiency-tier radiators carry longer tenors and stricter surface-finish specifications than commodity-grade alternatives.
Pricing Analysis
Short-lead-time premiums for low-temperature panel radiators command pricing advantages in German retrofit channels where BAFA subsidy deadlines compress installation windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by seasonal performance certification and heat pump compatibility testing. Pricing pressure stems from steel price volatility and energy-intensive coating inputs, with social housing authorities exhibiting highest price sensitivity through framework-agreement volume aggregation while hospitality developers show lowest sensitivity for designer-specified towel warmers.
Supply Chain Analysis
Single-source vulnerability sits with precision steel pressing equipment suppliers concentrated in Germany, Italy, and Czechia. Raw material dependencies center on hot-rolled carbon steel coils, epoxy-polyester powder coatings, and aluminum die-cast alloys sourced from European smelters. Supply chain risk manifests as welding technician scarcity across Eastern European labor markets. Distribution runs through captive installation networks for framework-agreement access and merchant wholesalers for replacement-cycle spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe heating radiator market sits in a technology-transition phase as low-temperature heat emitter designs displace legacy high-temperature steel panels optimized for fossil-fuel boilers. Heat pump deployment acceleration across Northern Europe is reshaping product specifications and procurement criteria.
For Market Incumbents: Anchor market position through backward integration into precision steel pressing and pre-certification bundling for Germany's BAFA subsidy eligibility alongside baseline CE marking. Defend against underfloor heating substitution in premium new-build segments by expanding aluminum-cast hybrid portfolios for multi-story towers with structural load constraints. Prioritize captive installation network expansion in Poland's municipal housing association channels. For New Entrants and Emerging Players: EU Green Deal building renovation targets in Romania and Bulgaria open a window for high-efficiency radiator penetration with EU cohesion fund financing. Target underpenetrated retrofit waves in Eastern European district heating networks where cast iron replacement cycles lag Western standards. Enter through smart thermostatic valve integration partnerships for zone-based energy management in multi-unit residential buildings. For Investors and Strategic Acquirers: Re-rating potential sits with aluminum die-casters possessing heat pump-compatible product portfolios given accelerating electrification mandates across EU member states. Long-term viability favors specialists with captive coating capacity and certified service networks rather than pure-play assemblers. Monitor F-Gas Regulation phase-down schedules as inflection indicator for heat pump pairing requirement tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Steel Pressing | Kermi GmbH and German incumbents control surface finish quality through captive forming capacity. |
| Low-Temperature Product Portfolio Expansion | Vasco Group leverages specialized designs to meet EU Ecodesign Directive efficiency thresholds without thermal output sacrifice. |
| Smart Thermostatic Valve Integration | IoT sensor convergence enables zone-based energy management for Poland's municipal housing associations. |
| Pre-Certification Bundling for National Subsidies | Manufacturers capture margin by securing Germany's BAFA eligibility alongside baseline CE marking compliance. |
| Aluminum-Cast Hybrid Construction Scale-Up | French and Italian developers specify these variants for Warsaw and Krakow multi-story towers with structural constraints. |
Research Methodology
Document review covered EU Construction Products Regulation filings, BAFA subsidy verification protocols, and F-Gas Regulation implementation schedules, complemented by interviews with radiator manufacturing executives, municipal housing association procurement directors, certified installation contractors, and heat pump system integrators. Secondary validation drew from customs trade data for steel and aluminum inputs, national building code repositories, and EU cohesion fund disbursement records. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Cross-referencing historical replacement cycle patterns against panel-input projections from industry stakeholders shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, material composition, mounting configuration, and end-use application. CAGRs were derived from installed base turnover rates, new-build construction permits, and efficiency-regulation compliance deadlines. Heat pump deployment curves and steel price volatility indices served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for low-temperature heat emitter designs; alternative pathways for heat pump output curve optimization would alter the outlook for aluminum versus steel specification splits. Deviation in EU Ecodesign Directive enforcement timing or BAFA subsidy budget allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
North America Commercial HVAC Market