
 Steam Heat Exchanger Market | 2026-2036
Steam Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Heat Exchanger Market Analytics
Power utilities are unwinding their historical dominance as chemical processors and food manufacturers claim a larger share of new steam heat exchanger orders. Alfa Laval AB leverages its plate heat exchanger portfolio to serve dairy pasteurization lines across Europe. Kelvion Holding GmbH anchors its position through specialized corrosion-resistant coatings for aggressive chemical streams. API Heat Transfer competes in the North American refinery segment with custom-engineered shell-and-tube bundles.
A steam heat exchanger transfers thermal energy from steam to a secondary fluid without direct contact, typically operating at pressures from vacuum to 200 bar and temperatures exceeding 500°C in supercritical power cycles, with materials ranging from carbon steel to titanium and nickel alloys depending on corrosion exposure. Shell-and-tube configurations still occupy the largest installed base due to legacy compatibility and high-pressure tolerance, though plate heat exchangers are displacing them in sub-30 bar applications where footprint and thermal efficiency matter more. The HVAC application segment remains mature with thin margins, while pharmaceutical end users sustain premium pricing for sanitary-grade units with full traceability and ASME-BPE compliance.
The US EPA enforces Maximum Achievable Control Technology standards that effectively mandate efficiency upgrades in steam systems at major industrial sources, while the EU F-Gas Regulation indirectly shapes thermal equipment selection by restricting refrigerant-based alternatives in certain heating duties. China's GB standards for pressure vessels and Japan's METI energy efficiency directives both impose design certification burdens that favor established suppliers with in-country testing capabilities. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus for imported versus domestically fabricated heat exchange equipment.
Market Dynamics
Chemical processors in Germany's Ruhr corridor and US Gulf Coast are retiring legacy shell-and-tube units faster than suppliers can deliver compact plate alternatives, compressing lead times and reshaping competitive positioning.
Growth Catalysts
- EPA Maximum Achievable Control Technology standards:US industrial facilities face mandated efficiency upgrades in steam systems, forcing replacement of aging thermal equipment with higher-performance models.
- Plate heat exchanger technology:Compact designs deliver superior thermal efficiency below 30 bar operating pressure, winning specification in dairy pasteurization and chemical processing lines.
- Ruhr industrial corridor concentration:Refinery and petrochemical clusters in Germany drive synchronized replacement cycles for corrosion-resistant coated units.
Market Restraints
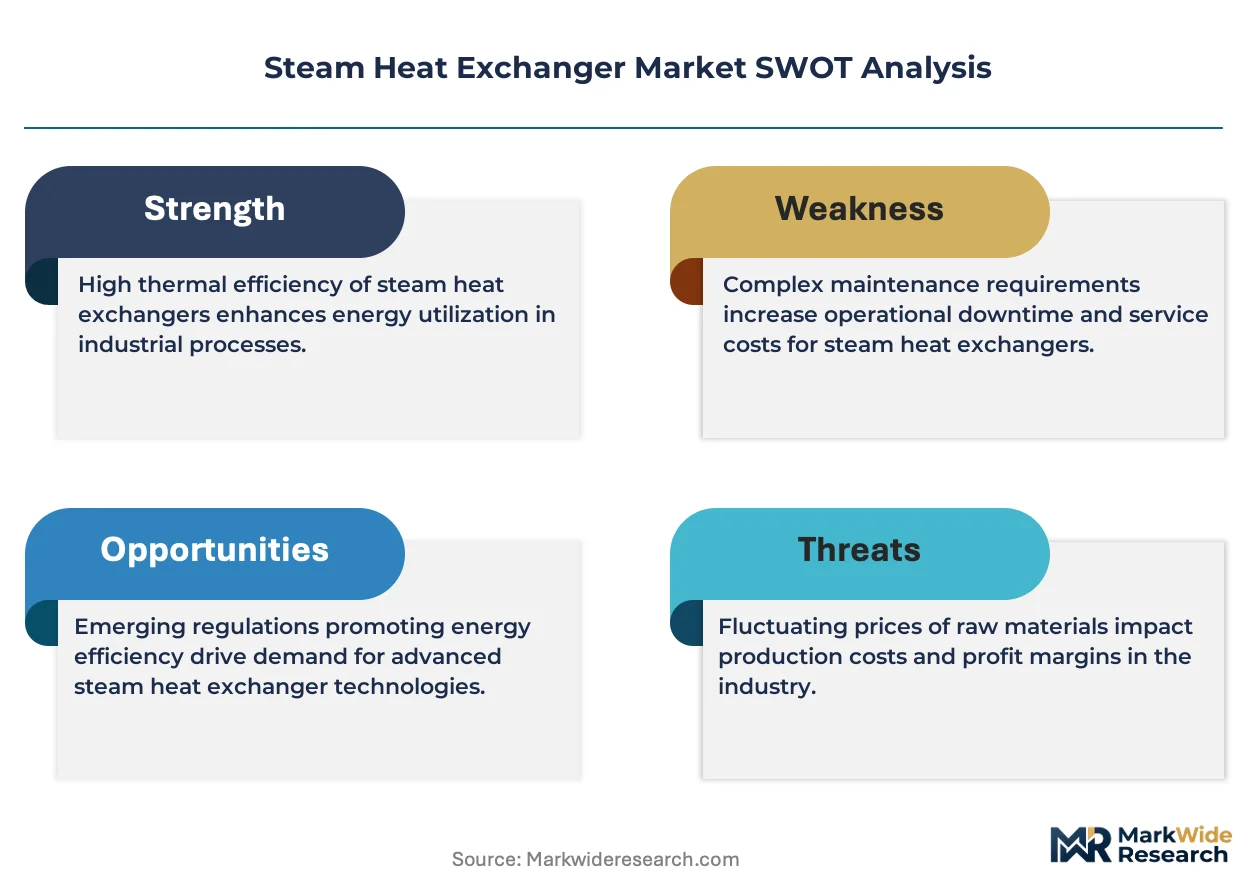
- Nickel alloy input volatility:Titanium and nickel-based materials face price swings that compress fabrication margins for supercritical-rated equipment.
- Supply concentration in established fabricators:In-country pressure vessel certification requirements in China and Japan favor incumbent suppliers with captive testing facilities.
- Shell-and-tube legacy lock-in:High-pressure tolerance above 200 bar and installed base compatibility slow displacement in power utility applications.
Strategic Opportunities
- Pharmaceutical sanitary-grade segment:ASME-BPE compliant units with full material traceability command premium pricing from vaccine and biologics manufacturers.
- Carbon border adjustment mechanisms:Emerging trade rules reshape cost calculus for imported versus domestically fabricated equipment, favoring regional production footprints.
- Digital twin integration:Convergence of thermal design software with predictive maintenance platforms enables performance-guaranteed service contracts.
Industry Challenges
- Pressure vessel welder certification scarcity:Qualified ASME code welders for high-alloy materials command premiums that inflate project labor costs.
- Legacy control system integration:New compact heat exchangers require protocol translation to communicate with existing plant distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Heat Exchanger Market |
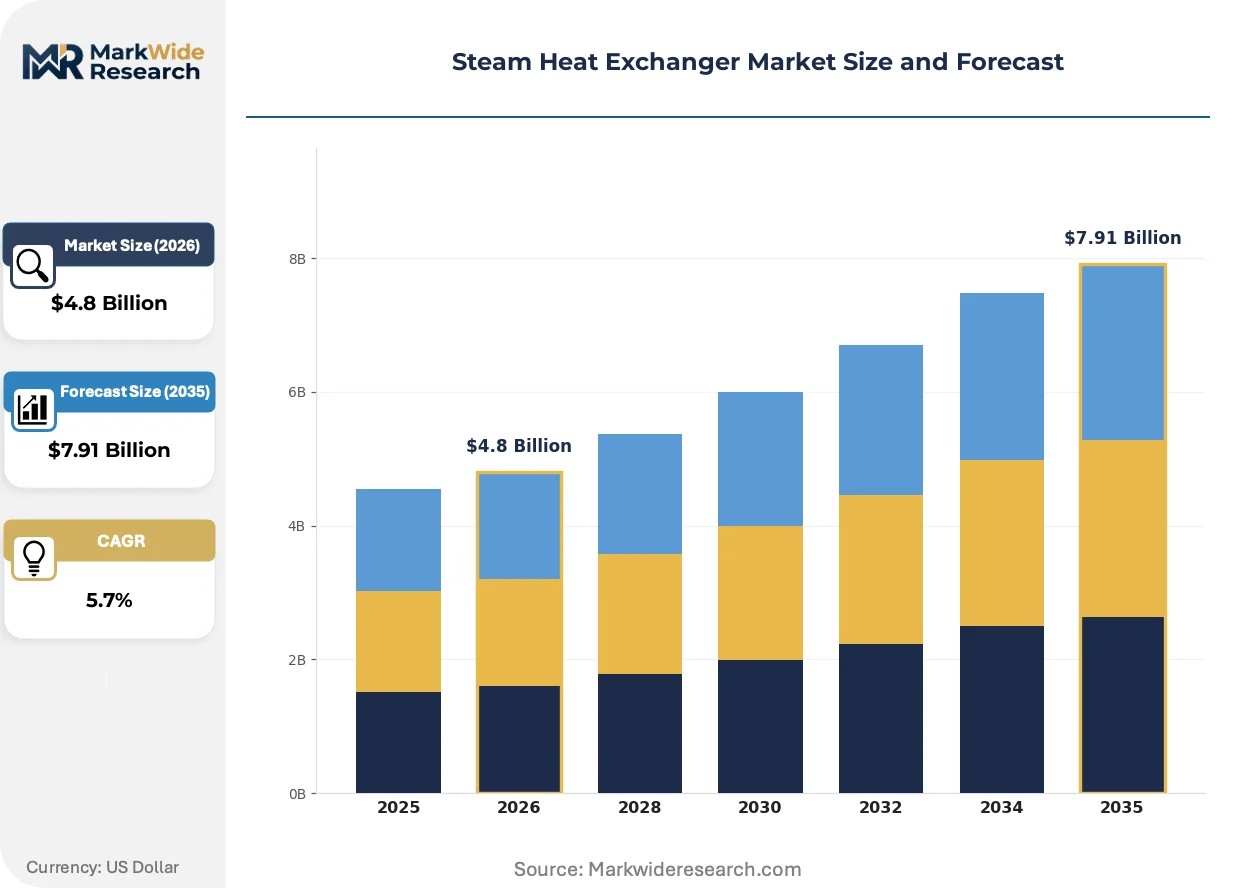
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Shell & Tube, Plate, Air Cooled, Double Pipe Application: Power Generation, Chemical Processing, Food & Beverage, HVAC End User: Manufacturing, Oil & Gas, Pharmaceuticals, Textile Installation: Indoor, Outdoor, Modular, Fixed |
| Companies Covered | Alfa Laval AB, Kelvion Holding GmbH, API Heat Transfer, SPX FLOW, Danfoss, GEA Group, GE Vernova, Thermax Limited, Mersen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Heat Exchanger Market Evolving Landscape
Equipment specification is pivoting from pressure rating supremacy toward thermal efficiency density, with buyers prioritizing footprint reduction and heat transfer coefficients over legacy compatibility.
Printed circuit heat exchanger technology is fragmenting the sub-50 bar segment. These diffusion-bonded microchannel units deliver heat transfer surface densities exceeding 1,000 m²/m³. Offshore platform operators and floating LNG producers are specifying them for weight-critical installations. The technology is fragmenting procurement patterns by enabling modular skid packages that displace field-fabricated shell-and-tube farms.
The EU F-Gas Regulation restricts refrigerant-based heating alternatives in industrial thermal duties, indirectly elevating steam heat exchanger specification in food processing and pharmaceutical plants. Facilities facing refrigerant phase-down timelines are converting direct-expansion systems to steam-heated secondary loops. German dairy cooperatives and Dutch greenhouse operators are most affected, accelerating plate heat exchanger orders for low-pressure steam service.
Buyer consolidation among multinational chemical conglomerates is compressing vendor qualification timelines. Procurement teams at BASF, Dow, and LyondellBasell now mandate unified technical standards across their global plant portfolios. This behavior is eliminating regional specification variations that previously protected local fabricators. The shift is most visible in the US Gulf Coast and Belgium's Antwerp port cluster, where integrated chemical sites are standardizing on single-source heat exchanger frameworks.
Steam Heat Exchanger Market Segmentation
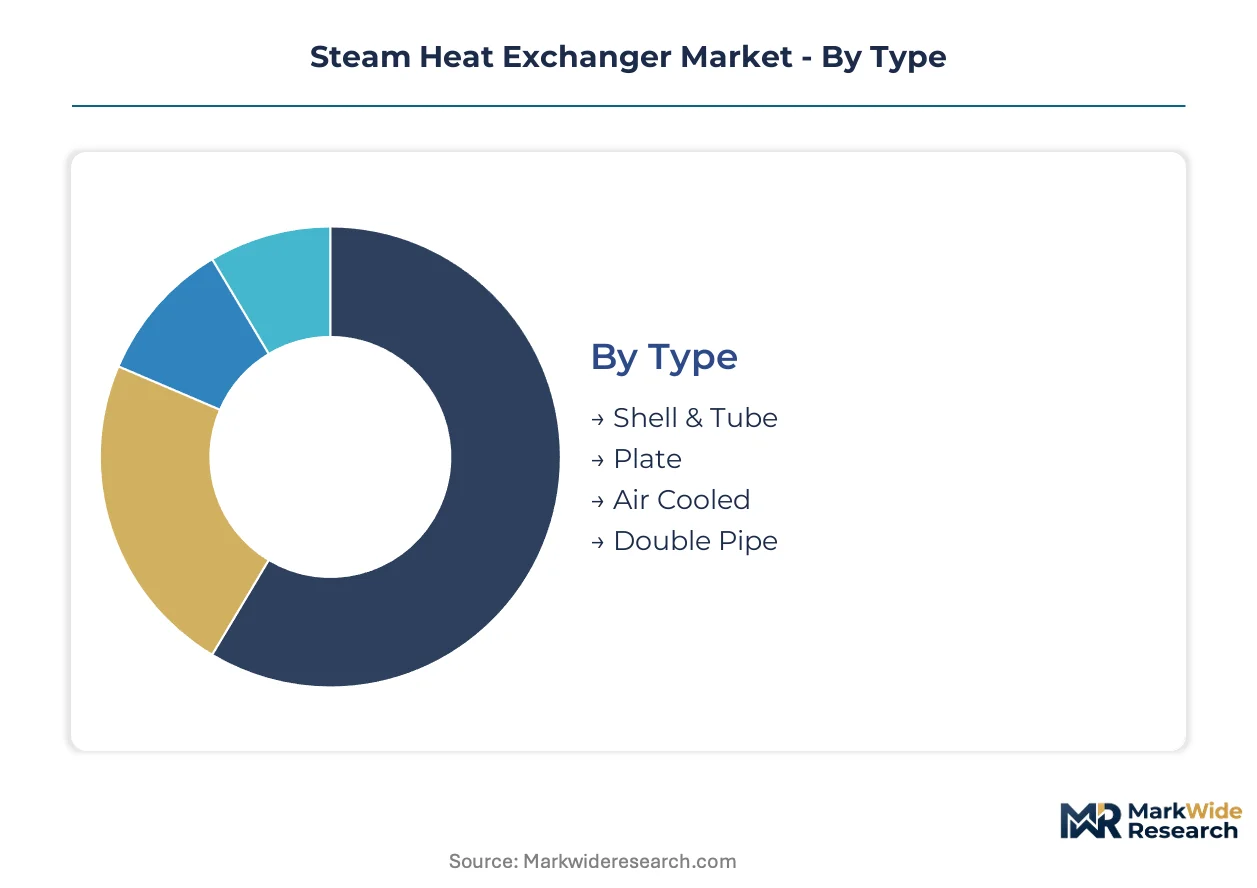
Steam heat exchanger procurement patterns diverge sharply across equipment types and end-use environments. Specification priorities shift from pressure tolerance in legacy power utilities to footprint efficiency in European dairy processing and Asian pharmaceutical plants.
Type:
Shell-and-tube configurations dominate domestic procurement in established industrial corridors, while plate designs capture export-led demand from Southeast Asian chemical processors seeking compact thermal solutions.
- Shell & Tube:These cylindrical pressure vessels route steam through tube bundles enclosed in outer shells, accommodating operating pressures above 200 bar. Demand concentrates in US Gulf Coast refineries and Germany's Ruhr corridor, where EPA emissions standards and EU industrial efficiency directives force replacement of aging units.
- Plate:Corrugated metal plates create turbulent flow paths with heat transfer coefficients three to four times higher than shell-and-tube equivalents. Southeast Asian food processors and European dairy cooperatives specify these for sub-30 bar pasteurization lines where floor space commands premium valuations.
- Air Cooled:Finned-tube bundles dissipate heat to ambient air, eliminating cooling water infrastructure. Remote oilfield installations and desert-region chemical plants favor these for water-scarce environments.
- Double Pipe:Concentric tube arrangements handle small-scale thermal duties with minimal capital outlay. Laboratory and pilot-plant operators specify these for R&D validation before scaling to production units.
Shell-and-tube commands the established base. The steepest expansion runs through plate configurations.
Application:
Chemical processing applications sustain premium pricing through corrosion-resistant material specifications, while HVAC installations compete on thin margins in mature building services markets.
- Power Generation:Supercritical steam cycles demand nickel-alloy construction for temperatures exceeding 500°C. US utilities and Japanese power operators drive procurement for combined-cycle gas turbine plants.
- Chemical Processing:Aggressive acid streams and high-purity solvent recovery require titanium-clad or tantalum-lined surfaces. BASF and Dow standardize these specifications across their global plant portfolios.
- Food & Beverage:Sanitary-grade plate units with full material traceability serve pasteurization and sterilization duties. EU F-Gas Regulation restrictions accelerate steam-based system conversions in Dutch greenhouse and German dairy operations.
- HVAC:District heating substations and commercial building heat recovery applications emphasize first-cost minimization over thermal efficiency density.
Power generation anchors historical procurement volumes. Food and beverage applications are climbing the fastest as refrigerant phase-downs force thermal system redesigns.
End User:
Oil and gas operators specify heavy-duty units for offshore platform constraints, while pharmaceutical manufacturers drive the most stringent certification requirements.
- Manufacturing:General industrial process heating spans automotive paint curing to rubber vulcanization, with specification diversity fragmenting vendor standardization efforts.
- Oil & Gas:Floating LNG producers and North Sea platform operators prioritize weight-critical printed circuit heat exchanger technology for modular skid packages.
- Pharmaceuticals:Vaccine and biologics manufacturers mandate ASME-BPE compliance with full material traceability and electropolished surfaces. These units command 40-60 percent price premiums over standard industrial grades.
- Textile:Dyeing and finishing operations consume substantial steam volumes, with procurement concentrated in Bangladesh, Vietnam, and India's Tamil Nadu industrial belt.
Manufacturing represents the broadest installed base. Pharmaceutical specifications are gaining share fastest through biologics capacity expansion.
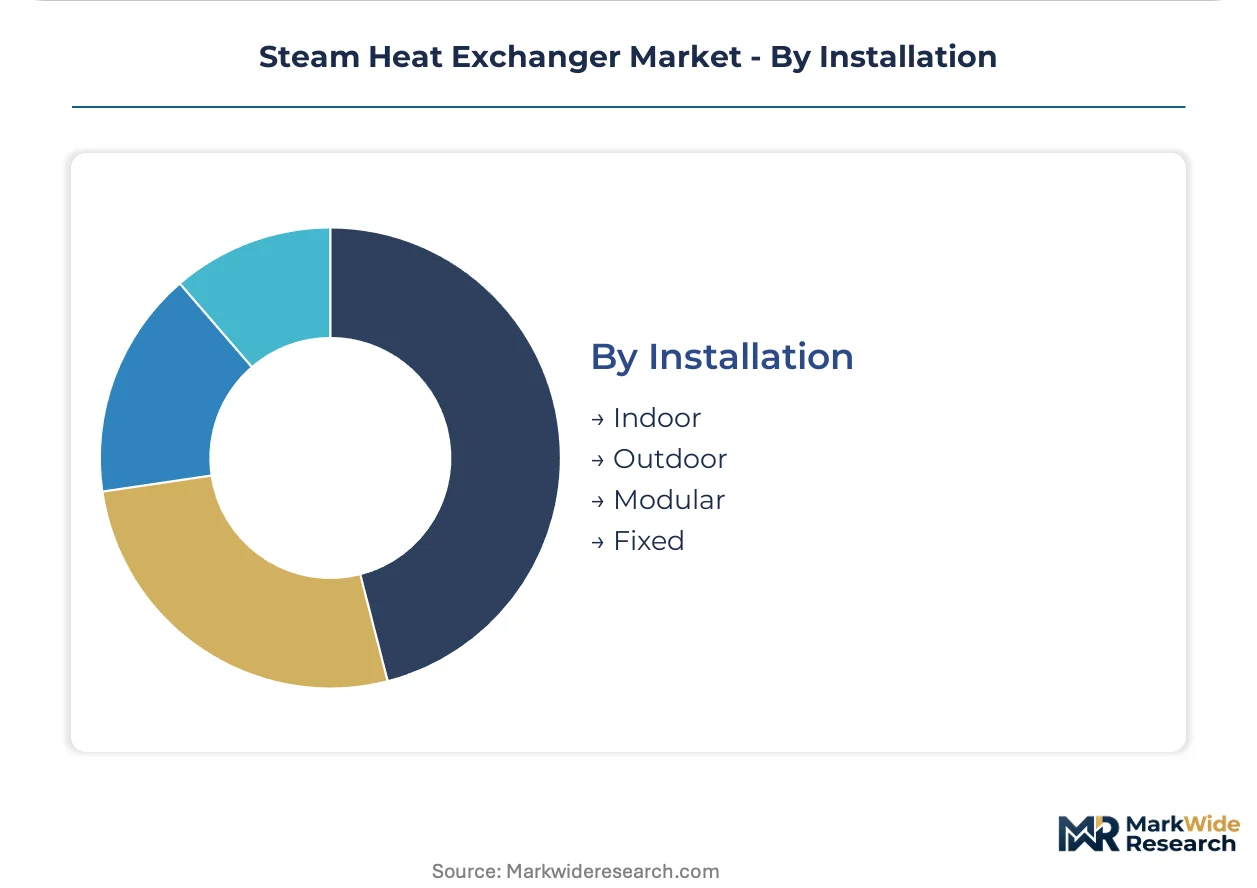
Installation:
Modular configurations enable factory acceptance testing before site delivery, reducing field commissioning risk for remote or hazardous environments.
- Indoor:Climate-controlled machinery halls protect sensitive plate gasket materials and instrumentation from temperature cycling and corrosive atmospheres.
- Outdoor:Weather-resistant enclosures with trace heating prevent freeze damage in Canadian oil sands and Russian arctic production facilities.
- Modular:Pre-assembled skid packages integrate pumps, controls, and heat exchangers on single structural frames. Offshore platform operators and rapid-deployment chemical plants favor these for schedule compression.
- Fixed:Permanent concrete foundations and embedded piping suit large shell-and-tube installations with decades-long service expectations.
Fixed installations retain the largest historical footprint. Modular approaches are expanding most quickly through offshore and remote site development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators supply corrosion-resistant units to Ruhr corridor refineries while Southeast Asian chemical processors import compact plate designs for footprint-constrained installations.
United States
EPA Maximum Achievable Control Technology standards force efficiency upgrades at Gulf Coast petrochemical facilities. The agency's industrial emissions rules compress replacement timelines for aging shell-and-tube infrastructure. Houston-area refineries and Louisiana chemical plants drive procurement of supercritical-rated nickel-alloy units.
Germany
Ruhr industrial corridor clusters synchronize replacement cycles for aggressive chemical stream applications. The EU F-Gas Regulation restricts refrigerant alternatives in food processing thermal duties. BASF and Dow procurement teams in Ludwigshafen and Antwerp standardize specifications across integrated chemical sites.
China
GB pressure vessel standards impose design certification burdens favoring established suppliers with captive testing capabilities. The country's dual carbon goals accelerate efficiency mandates in industrial steam systems. Yangtze River Delta chemical processors expand procurement of titanium-clad units for high-purity solvent recovery.
Japan
METI energy efficiency directives drive specification of advanced thermal equipment in combined-cycle gas turbine plants. National regulators mandate performance benchmarks that elevate heat transfer coefficient requirements. Chubu region power operators and Osaka Bay chemical clusters anchor domestic demand for supercritical-rated construction.
India
CEA efficiency guidelines and BIS pressure vessel codes reshape procurement patterns for process industries. The PLI scheme for manufacturing incentivizes domestic fabrication capacity expansion. Gujarat and Maharashtra industrial belts drive demand for sanitary-grade plate units in pharmaceutical and dairy applications.
Steam Heat Exchanger Market Competitive Landscape
Player mix skews toward diversified thermal equipment conglomerates with captive alloy fabrication capabilities. Market structure concentrates around three tiers: integrated multinationals with full material traceability systems, regional specialists in corrosion-resistant coatings, and scale-driven fabricators serving HVAC replacement markets. Strategic moves center on backward integration into nickel alloy supply chains and technology licensing for printed circuit microchannel designs.
Among Nordic-based thermal engineering groups, Alfa Laval AB represents the plate heat exchanger archetype with dairy pasteurization positioning across European cooperatives. German fabricators Kelvion Holding GmbH anchor the corrosion-resistant coating specialization tier for aggressive chemical streams. North American custom engineering specialists including API Heat Transfer occupy the refinery-focused shell-and-tube segment with project-specific bundle fabrication capabilities.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Kelvion Holding GmbH |
| API Heat Transfer |
| SPX FLOW |
| Danfoss |
| GEA Group |
| GE Vernova |
| Thermax Limited |
| Mersen |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German fabricators and Ruhr corridor chemical processors lock in nickel alloy supply access while capping price volatility exposure across multi-year replacement cycles. These arrangements bind procurement teams at BASF and Dow to Kelvion Holding GmbH and Alfa Laval AB for corrosion-resistant plate units, embedding volume commitments that shelter margins from spot market swings in titanium and nickel-based inputs.
Pricing Analysis
Current-generation plate heat exchangers command 25-40 percent premiums over prior-generation shell-and-tube equivalents in sub-30 bar applications, while next-generation printed circuit microchannel units extract further uplifts for weight-critical offshore installations. Three-tier pricing structure across premium, standard, and economy levels separates ASME-BPE compliant pharmaceutical grades from industrial chemical specifications and HVAC replacement stock. Cost compression in the standard tier is intensifying because Chinese fabricators with GB pressure vessel certification are expanding export capacity into Southeast Asian dairy and chemical markets. Food and beverage processors exhibit the highest price sensitivity due to thin pasteurization line margins, while vaccine manufacturers accept premium positioning for full material traceability.
Supply Chain Analysis
Germany and China anchor heat exchanger fabrication capacity, with German suppliers dominating corrosion-resistant coating specialization and Chinese fabricators scaling titanium-clad production for domestic chemical processors. Raw material draws from Indonesian nickel mining, Russian titanium sponge, and South Korean specialty steel rolling feed into pressure vessel construction. Single-source vulnerability concentrates in qualified ASME code welders for high-alloy materials, where certification scarcity inflates project labor costs. Distribution runs through direct OEM relationships for large chemical conglomerates and regional distributor networks serving HVAC replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steam heat exchanger procurement is accelerating through regulatory efficiency mandates and refrigerant phase-down timelines, with the EU F-Gas Regulation forcing thermal system redesigns across food processing and pharmaceutical plants.
For Market Incumbents: Secure backward integration into nickel alloy supply chains to buffer margin compression from titanium and nickel price volatility. Defend against printed circuit heat exchanger displacement in sub-50 bar segments by embedding digital twin capabilities into service contracts, creating switching costs for chemical processors in Germany's Ruhr corridor and the US Gulf Coast. For New Entrants and Emerging Players: Anchor in the pharmaceutical sanitary-grade segment where ASME-BPE compliance barriers protect premium pricing and biologics capacity expansion sustains order flow. Target modular skid package specification for offshore platform operators and floating LNG producers, leveraging weight-critical printed circuit technology to displace field-fabricated shell-and-tube farms through factory acceptance testing protocols. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with captive corrosion-resistant coating capabilities and in-country pressure vessel certification in China or Japan. The five-to-ten year viability window favors fabricators with digital twin integration platforms that enable performance-guaranteed service contracts. Watch for carbon border adjustment mechanism implementation as the signal indicating regional production footprint advantages over import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Mitigates titanium price volatility exposure for supercritical-rated equipment fabricators. |
| Digital Twin Platform Development | Enables predictive maintenance contracts that lock in chemical processor replacement cycles. |
| ASME-BPE Certification Investment | Captures 40-60 percent pharmaceutical pricing premiums from vaccine and biologics manufacturers. |
| Modular Skid Package Expansion | Compresses commissioning schedules for offshore platform and remote chemical plant deployments. |
| Regional Production Footprint Establishment | Positions ahead of carbon border adjustment mechanisms reshaping import cost calculus. |
Research Methodology
Operator-level perspectives from plant engineers, procurement leads at chemical processors, aftermarket service heads, and pressure vessel certification inspectors anchored the qualitative base for this analysis. Primary fieldwork across Germany's Ruhr corridor, the US Gulf Coast, and China's Yangtze River Delta combined with secondary validation from SEC filings, customs trade data, ACC and Cefic industry reports, and EPA enforcement databases. Bottom-up unit economics from individual replacement projects triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Sensitivity analysis tested demand elasticity under varying EPA enforcement intensity and EU F-Gas Regulation phase-down timelines across the projection horizon. Segmentation dimensions modeled include equipment type, operating pressure tier, end-use industry, material specification grade, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating replacement cycle timing, capacity expansion announcements, and efficiency mandate compliance deadlines. Industry-specific inputs encompassed welder certification scarcity premiums and nickel alloy spot price correlation coefficients.
Decision-makers should treat outputs as directional under sustained EPA Maximum Achievable Control Technology enforcement and EU industrial efficiency directive compliance; material deviation in regulatory stringency or nickel alloy price trajectories would warrant model refresh. Forecasts embed assumptions around printed circuit heat exchanger adoption rates in offshore applications and pharmaceutical biologics capacity expansion timelines. Recalibration cycles align with material shifts in carbon border adjustment mechanism implementation and METI energy efficiency directive revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
South Korea HVAC Market