
 Global Air Handling Units (AHU) Market | 2026-2036
Global Air Handling Units (AHU) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Handling Units (AHU) Market Foresight
The EU Green Deal is repositioning AHU procurement across European commercial real estate by embedding energy performance benchmarks into renovation mandates. Daikin Industries leverages its heat pump integration expertise to dominate premium modular configurations in East Asian data center projects. Carrier Global anchors North American hospital and laboratory demand through extensive service networks and EPA-compliant filtration systems. Trane Technologies differentiates via deep R&D intensity in energy recovery ventilator technology for cold storage applications.
An air handling unit is an enclosed mechanical assembly comprising fans, heating and cooling coils, air filtration chambers, and dampers designed to condition and circulate air within HVAC systems, typically operating at static pressures between 1 and 12 inches of water column. Its primary purpose is to regulate temperature, humidity, and air quality in enclosed environments ranging from pharmaceutical cleanrooms to airport terminals. Modular AHU configurations lead volume shipments due to their field-adaptable footprint and reduced installation downtime in retrofit commercial buildings. Energy recovery technology represents the fastest-expanding technology segment as operators pursue heat wheel and plate exchanger solutions to comply with escalating building energy codes. Custom-built AHU commands the deepest margin pools where pharmaceutical facilities and research laboratories specify stainless steel construction, HEPA integration, and redundant fan arrays.
The U.S. EPA and DOE jointly shape AHU demand through minimum efficiency standards for commercial fan systems and refrigerant phase-down schedules under the AIM Act. China's MIIT enforces GB standards on motor efficiency and air leakage rates that constrain market access for non-compliant imports. India's BIS certification requirement for HVAC equipment, coupled with the CEA's energy conservation building code, is redirecting procurement toward variable air volume systems in new commercial construction. Stakeholders must monitor how refrigerant transition timelines and regional efficiency tier upgrades will reshape supplier qualification criteria and retrofit prioritization across their installed base.
Market Dynamics
Refrigerant phase-down mandates under the AIM Act and parallel EU F-Gas Regulation revisions are forcing simultaneous redesign of heat exchange architectures and compressor specifications across all major supply bases.
Growth Catalysts
- EU Green Deal renovation mandates:Commercial building retrofit quotas in Germany and France are accelerating replacement cycles for legacy ventilation infrastructure.
- Data center cooling densification:Hyperscale facilities in Singapore and Japan are specifying high-static-pressure modular configurations to support liquid-cooled server racks.
- Heat recovery wheel adoption:Plate exchanger and enthalpy wheel integration is penetrating pharmaceutical cleanrooms to capture exhaust energy and reduce HVAC electrical loads.
Market Restraints
- Copper and aluminum price volatility:Coil material cost swings compress margin visibility for custom-built stainless steel pharmaceutical units.
- Motor supply concentration:High-efficiency EC motor production clusters in China create single-source exposure for European AHU assemblers.
- Refrigerant transition friction:R-410A phase-down timelines compress engineering validation windows before R-454B and R-32 system redesigns must deploy.
Strategic Opportunities
- India commercial construction code expansion:CEA energy conservation mandates in Mumbai and Bangalore are redirecting new build specifications toward variable air volume systems.
- Healthcare filtration upgrade cycles:EPA-compliant HEPA integration for hospital isolation wards creates specification pull-through for premium modular platforms.
- Digital twin convergence:Building management system integration with predictive maintenance algorithms is opening recurring software revenue streams for AHU OEMs.
Industry Challenges
- Controls engineering scarcity:BACnet and Modbus protocol specialists are in short supply relative to demand for smart AHU commissioning.
- Legacy ductwork incompatibility:Retrofit projects face field adaptation costs when connecting modern low-leakage units to existing galvanized steel distribution.
- Multi-standard certification lag:Simultaneous GB, JIS, and AHRI testing requirements extend product launch timelines for pan-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Handling Units (AHU) Market |
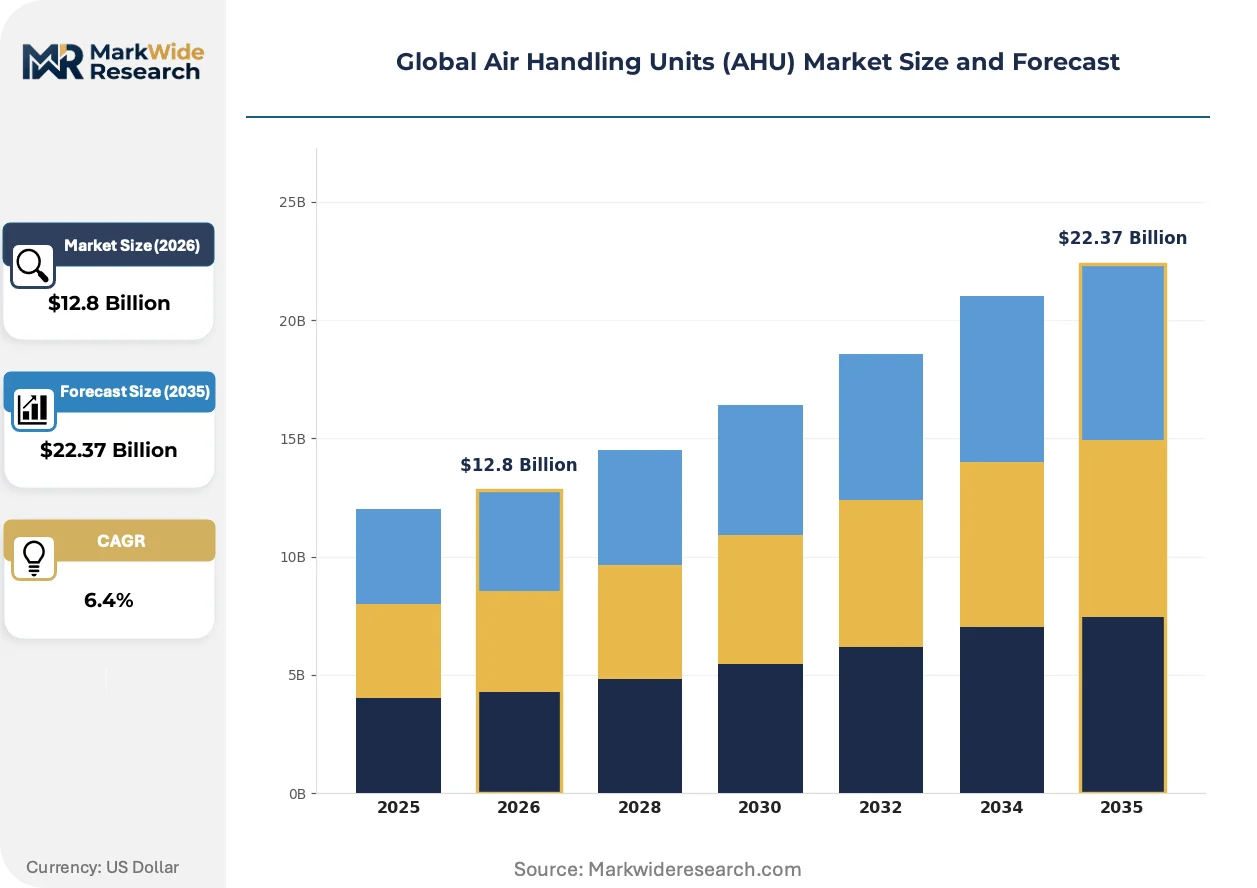
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular AHU, Packaged AHU, Custom-built AHU, Vertical AHU, Horizontal AHU Technology: Variable Air Volume, Constant Air Volume, Energy Recovery, Heat Pump, Ultraviolet Germicidal Irradiation Application: Commercial Buildings, Data Centers, Pharmaceutical Facilities, Educational Institutions, Airport Facilities End User: Cold Storage Facilities, Food Processing Plants, Research Laboratories, Hospitality Venues, Sports Arenas |
| Companies Covered | Daikin Industries Ltd, Carrier Global Corporation, Trane Technologies plc, Johnson Controls International plc, Systemair AB, Lennox International Inc, TROX GmbH, Munters AB, LG Electronics Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Handling Units (AHU) Market Shifts & Advancements
Active magnetic bearing centrifugal compressors and refrigerant-free indirect evaporative cooling are compressing the technical boundaries of what air handling architectures can achieve without direct expansion refrigeration.
Indirect evaporative cooling media is decentralizing thermal management authority in data center white spaces by eliminating compressor-based refrigeration from perimeter air handling. Colocation operators in Northern Virginia and Frankfurt are deploying these units at 15-30kW rack densities previously reserved for chilled water systems. The technology is decentralizing mechanical infrastructure investment toward the rack row level and reducing central plant capital intensity.
The EU F-Gas Regulation's stepped GWP reduction schedule is banning refrigerants with global warming potential above 750 in new stationary equipment from 2027 onward. AHU manufacturers must validate alternative heat pump integration or shift toward hydronic coil configurations served by external chillers. Cold storage and pharmaceutical warehouse specifications in the Netherlands and Denmark are most exposed, with engineering teams accelerating R-290 and CO2 subcritical system partnerships.
Lifecycle service contracting is displacing transactional equipment procurement in healthcare and laboratory verticals. Buyers in Boston and Basel are unbundling capital expenditure from filter replacement, coil cleaning, and controls calibration through ten-year performance agreements. This reconfiguration concentrates vendor selection criteria on service network density rather than upfront unit pricing.
Global Air Handling Units (AHU) Market Segmentation
AHU procurement patterns diverge sharply across product architectures, control technologies, and facility types. Capital allocation decisions by infrastructure owners determine which configurations dominate volume shipments versus margin capture.
Product Type:
Capital intensity varies dramatically across AHU form factors, with field-fabricated systems demanding engineering labor and standardized platforms leveraging manufacturing scale.
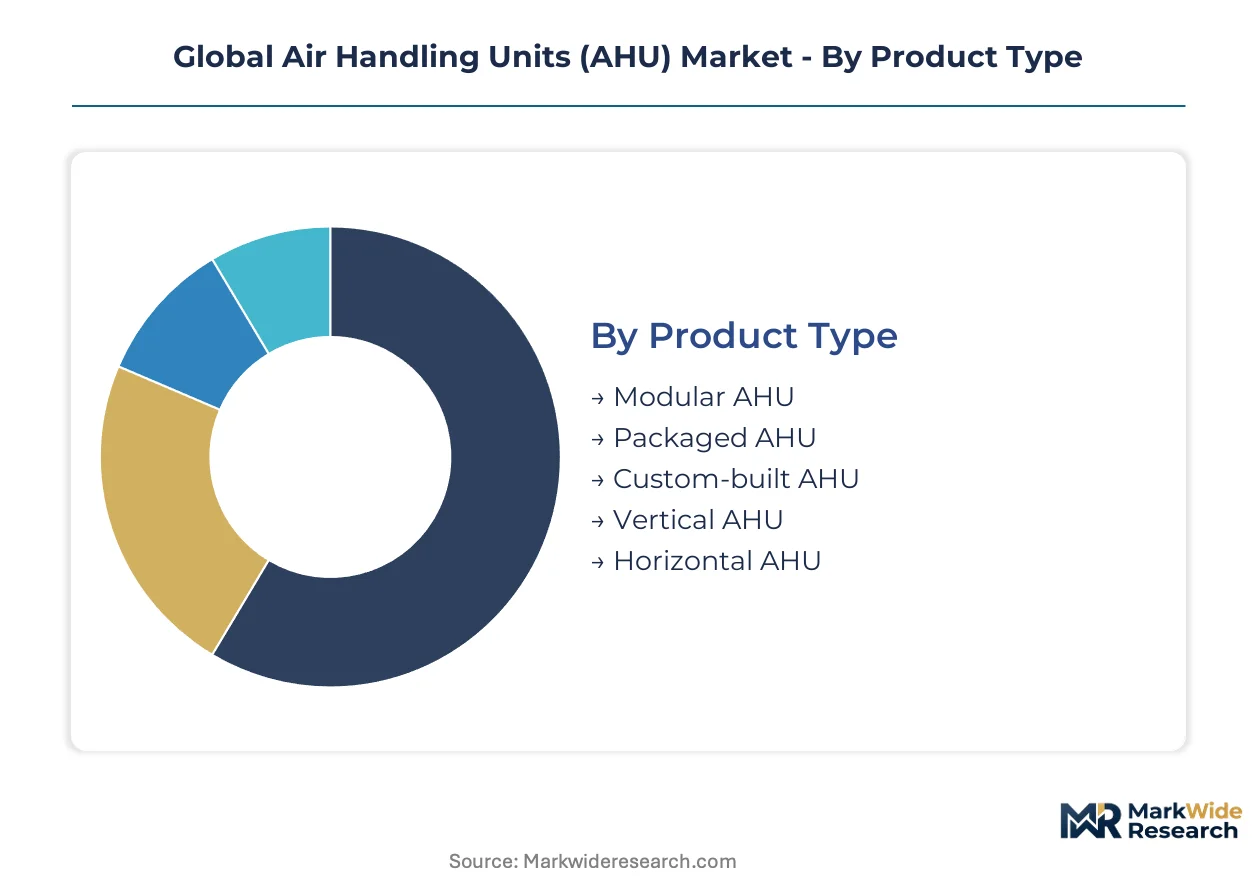
- Modular AHU:Factory-assembled sections with bolt-together casings and plug-and-play controls. Data centers in Singapore and Japan specify these for rapid deployment alongside liquid-cooled server racks.
- Custom-built AHU:Site-engineered stainless steel enclosures with redundant fan arrays and HEPA integration. Pharmaceutical cleanrooms in Basel and Boston absorb the highest unit costs for compliance-critical specifications.
- Packaged AHU:Self-contained rooftop units with integrated compressors and economizer dampers. Strip malls and mid-rise offices in Texas and Florida favor these for single-source warranty coverage.
- Vertical AHU:Floor-mounted configurations with upward airflow discharge. Mechanical penthouses in Mumbai and Bangalore deploy these where horizontal duct routing is constrained.
- Horizontal AHU:Ceiling-suspended units with side-mounted fan arrays. Retrofit commercial buildings in Frankfurt and Paris select these for minimal floor space consumption.
Modular AHU absorbs the bulk of installed capacity; custom-built AHU is expanding most quickly.
Technology:
Control sophistication separates premium pricing tiers, with advanced algorithms commanding substantial engineering premiums over fixed-speed alternatives.
- Variable Air Volume:Damper-modulated airflow responding to zone-level demand signals. New commercial construction in Mumbai and Bangalore specifies these under CEA energy conservation mandates.
- Energy Recovery:Heat wheel and plate exchanger systems capturing exhaust thermal energy. Pharmaceutical cleanrooms in Denmark and the Netherlands adopt these to reduce HVAC electrical loads under EU Green Deal benchmarks.
- Constant Air Volume:Fixed airflow rates maintained regardless of load variation. Legacy hospital wings in Chicago and Philadelphia retain these for infection control reliability.
- Heat Pump:Refrigerant-based heating and cooling within a single packaged unit. Cold storage facilities in Germany integrate these with CO2 subcritical systems for F-Gas compliance.
- Ultraviolet Germicidal Irradiation:UV-C lamp arrays integrated into coil and filter sections. Hospital isolation wards in Boston specify these for EPA-compliant pathogen suppression.
Variable Air Volume dominates new construction specifications; energy recovery is climbing the fastest under tightening building energy codes.
Application:
Facility type dictates performance requirements spanning filtration grade, redundancy architecture, and static pressure capability.
- Commercial Buildings:Mid-efficiency filtration and standard redundancy for office and retail environments. EU Green Deal renovation mandates in Germany and France are accelerating replacement cycles for legacy ventilation infrastructure.
- Data Centers:High-static-pressure configurations supporting 15-30kW rack densities. Hyperscale facilities in Northern Virginia and Frankfurt deploy indirect evaporative cooling units to reduce central plant capital intensity.
- Pharmaceutical Facilities:Stainless steel construction with HEPA terminal filtration and unidirectional airflow. Research campuses in Basel and Boston require custom engineering for cGMP compliance.
- Educational Institutions:Standard efficiency units with basic economizer control. K-12 districts in Texas prioritize first-cost minimization over lifecycle performance.
- Airport Facilities:Smoke evacuation capabilities and high-capacity filtration for concourse environments. Terminal expansions in Dubai and Singapore specify these for passenger volume surges.
Commercial Buildings account for the greatest installed base; data centers are gaining share fastest.
End User:
Operational criticality determines specification stringency, with process-dependent facilities tolerating minimal downtime risk.
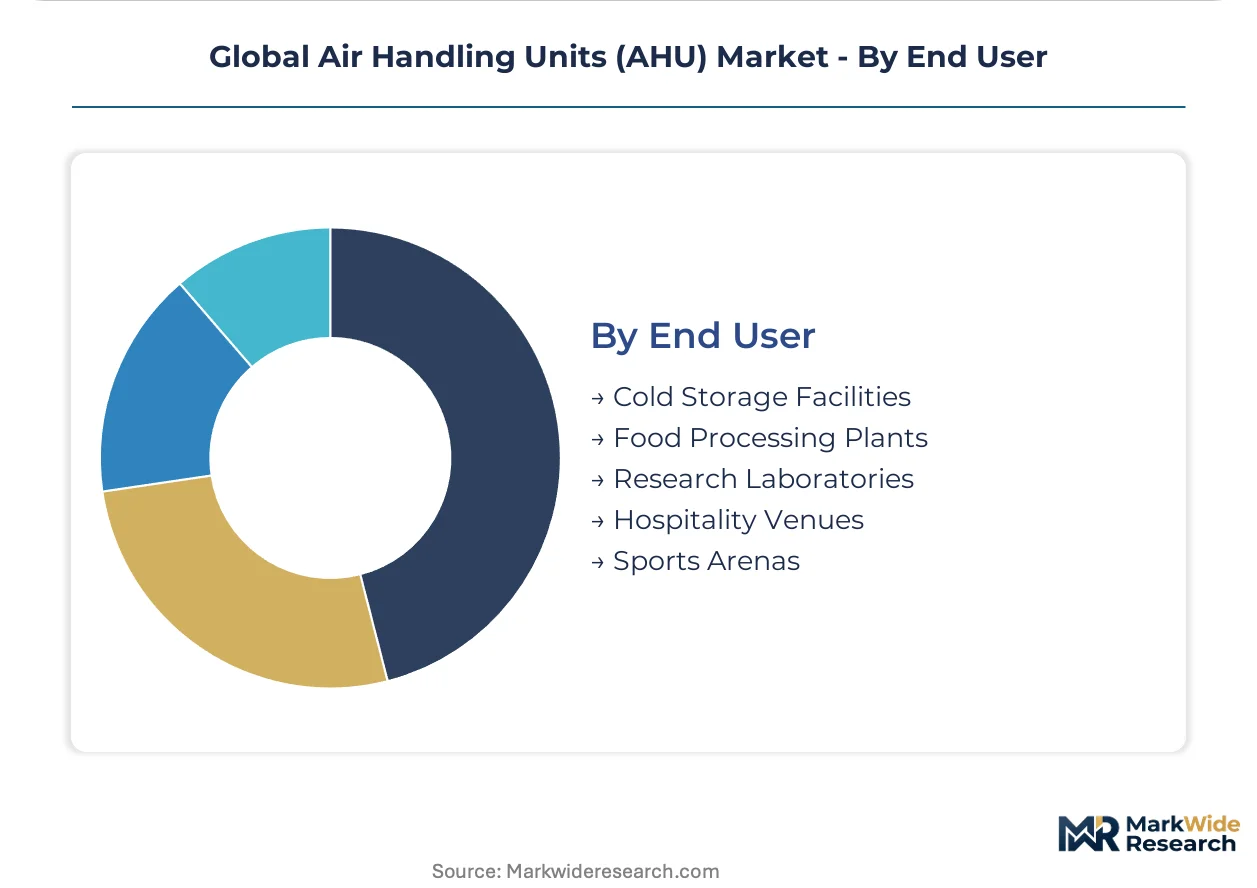
- Cold Storage Facilities:Low-temperature coil designs with defrost sequencing and redundant refrigeration circuits. Distribution warehouses in the Netherlands accelerate R-290 and CO2 system partnerships under F-Gas Regulation timelines.
- Research Laboratories:Precision humidity control and chemical fume containment. NIH-funded facilities in Maryland and California specify these for grant compliance and researcher safety.
- Food Processing Plants:Washdown-rated enclosures and stainless steel construction for hygiene zones. Poultry and dairy operations in Iowa and Wisconsin favor these for USDA inspection readiness.
- Hospitality Venues:Acoustically attenuated fan sections and guest room zoning. Casino resorts in Las Vegas and Macau deploy these for occupant comfort differentiation.
- Sports Arenas:Smoke purge capabilities and rapid ventilation for crowd evacuation. Stadium renovations in London and Melbourne integrate these for fire code compliance.
Cold storage facilities represent the most demanding specification environment; research laboratories are expanding most quickly under federal funding cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and Germany while consumption concentrates in data center hubs across Singapore and cold storage corridors in the Netherlands. This production-consumption divide shapes regional procurement strategies and regulatory compliance priorities.
United States
Hyperscale data center construction in Northern Virginia and hospital renovation cycles in Chicago drive specification demand. The EPA's commercial fan efficiency standards and AIM Act refrigerant phase-down timelines constrain equipment selection windows. Dallas-Fort Worth manufacturers are expanding modular production lines to serve Texas commercial construction.
Germany
Cold storage warehouse expansion and pharmaceutical facility upgrades in Frankfurt absorb premium custom-built units. The EU F-Gas Regulation and Green Deal renovation mandates accelerate heat pump integration and energy recovery adoption. Bavarian engineering clusters are validating R-290 and CO2 subcritical system partnerships for F-Gas compliance.
China
Data center cooling densification in Shanghai and Beijing plus commercial building stock modernization sustain volume procurement. MIIT's GB standards on motor efficiency and air leakage rates filter import access. Yangtze River Delta manufacturers dominate EC motor supply for regional AHU assemblers.
India
Commercial construction in Mumbai and Bangalore redirects specifications toward variable air volume systems. BIS certification requirements and CEA energy conservation building codes reshape new build procurement. Gujarat fabrication clusters are scaling modular output for domestic data center projects.
Singapore
Hyperscale facility operators specify high-static-pressure modular configurations for liquid-cooled server rack densities. National sustainability mandates and tropical climate design codes push indirect evaporative cooling adoption. Jurong industrial estates concentrate regional distribution for Southeast Asian data center markets.
Global Air Handling Units (AHU) Market Competitive Landscape
The competitive structure tilts toward diversified HVAC conglomerates with heat pump integration expertise and specialized air treatment fabricators with cleanroom credentials. Tiering separates premium modular platforms with digital twin capabilities from standardized packaged units competing on first-cost minimization. Strategic archetypes include heat pump-integrated system houses, pharmaceutical-grade custom engineers, and data center cooling specialists. Dominant competitive moves encompass refrigerant transition partnerships and lifecycle service contract unbundling.
Within the diversified conglomerate tier, Daikin Industries Ltd, Carrier Global Corporation, and Trane Technologies plc exemplify scale-driven positions spanning multiple geographies and application verticals. These Japan-based and US-based entities anchor premium-tier competition through integrated climate technology portfolios and extensive service network density.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Carrier Global Corporation |
| Trane Technologies plc |
| Johnson Controls International plc |
| Systemair AB |
| Lennox International Inc |
| TROX GmbH |
| Munters AB |
| LG Electronics Inc |
| Others |
Supply & Pricing Matrix
Captive EC motor production in China's Yangtze River Delta anchors both supply security and pricing power for regional AHU assemblers serving data center and pharmaceutical verticals. This upstream control over high-efficiency motor supply insulates domestic manufacturers from copper and aluminum volatility while forcing European and North American competitors into premium positioning or partnership dependency.
Pricing Analysis
Margin tightening in custom-built stainless steel pharmaceutical units reflects coil material cost swings and extended engineering validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates HEPA-integrated redundant systems from basic modular configurations and packaged rooftop units. Price differentiation hinges on certification grade and geographic delivery cost, with EU F-Gas compliance adding engineering premiums. Healthcare and laboratory buyers show lowest price sensitivity due to grant-funded procurement and cGMP mandate rigidity; K-12 educational institutions in Texas and Florida represent the most cost-conscious segment.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification and China's MIIT GB standards are reshaping sourcing toward Gujarat fabrication clusters and Yangtze River Delta motor suppliers. Manufacturing gravity centers on China, Germany, and India for coil fabrication and final assembly. Raw material dependencies span copper for heat exchange coils, aluminum for casing construction, and rare-earth elements for EC motor magnets. Single-source vulnerability concentrates in high-efficiency EC motor supply from Chinese producers. Distribution runs through regional HVAC wholesalers and direct OEM service networks for lifecycle contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AHU market functions as a cost-of-compliance arena where the EU F-Gas Regulation's stepped GWP reduction schedule erects a technical barrier-to-entry moat favoring incumbents with validated alternative refrigerant partnerships and heat pump integration expertise.
For Market Incumbents: Deepen backward integration into EC motor supply or captive coil manufacturing to defend margin position against copper volatility and Chinese motor export constraints. Anchor service network density in Northern Virginia and Frankfurt data center corridors to capture lifecycle contracting displacement of transactional procurement. Prioritize R-290 and CO2 subcritical system partnerships before F-Gas ban enforcement tightens supplier qualification windows. For New Entrants and Emerging Players: The EU Green Deal renovation mandates in Germany and France open a window for modular AHU specialists with rapid field-adaptable deployment capabilities. Target pharmaceutical cleanroom retrofits in Basel and Boston where stainless steel construction and HEPA integration command deepest margin pools. Pursue digital twin integration with building management systems as a software-recurring revenue wedge against capital-equipment incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified HVAC conglomerates seeking heat pump integration expertise or pharmaceutical-grade cleanroom credentials. Long-term viability favors suppliers with validated F-Gas-compliant refrigerant portfolios and dense service networks in healthcare and data center verticals. Watch refrigerant transition timeline acceleration as the inflection signal for distressed asset availability among laggard system houses.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Partnership | R-290 and CO2 subcritical validation secures F-Gas compliance for cold storage specifications in the Netherlands. |
| Lifecycle Service Contract Unbundling | Ten-year performance agreements in Boston and Basel hospitals displace upfront pricing with recurring filter and calibration revenue. |
| Digital Twin Platform Integration | Predictive maintenance algorithms embedded in building management systems open software revenue streams for modular AHU OEMs. |
| Backward Integration into EC Motors | Captive motor production insulates European assemblers from Chinese supply concentration and tariff exposure. |
| Indirect Evaporative Cooling Scale-Up | Refrigerant-free architectures capture 15-30kW rack density specifications in Northern Virginia and Frankfurt colocation markets. |
Research Methodology
Document review covered SEC 10-K filings, EU F-Gas Regulation implementation guidance, and MIIT GB standard documentation, complemented by interviews with HVAC plant engineers, data center facility managers, pharmaceutical GMP compliance officers, and hospital procurement directors. Secondary validation drew from AHRI certification databases, customs trade records for coil and motor imports, and building energy code adoption tracking across CEA and EPA jurisdictions. Bottom-up unit shipment estimates triangulated against top-down construction spending and data center capex disclosures.
Cross-referencing historical penetration curves with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, control technology sophistication, facility type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves and replacement cycle acceleration under EU Green Deal mandates. Industry-specific forecast inputs encompass data center rack density evolution and refrigerant phase-down timeline compliance costs.
The model assumes a particular technology adoption path; alternative pathways for magnetic bearing centrifugal compressors or refrigerant-free indirect evaporative cooling would alter the outlook for traditional heat pump-integrated architectures. Forecasts reflect assumptions around F-Gas enforcement consistency, copper price regime stability, and EC motor supply chain resilience. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
North America Ceiling Cassette Market
HVAC Equipment
Compressor Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
China Residential Heat Pump Market