
 Global Air Curtain Market | 2026-2036
Global Air Curtain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Curtain Market Analysis
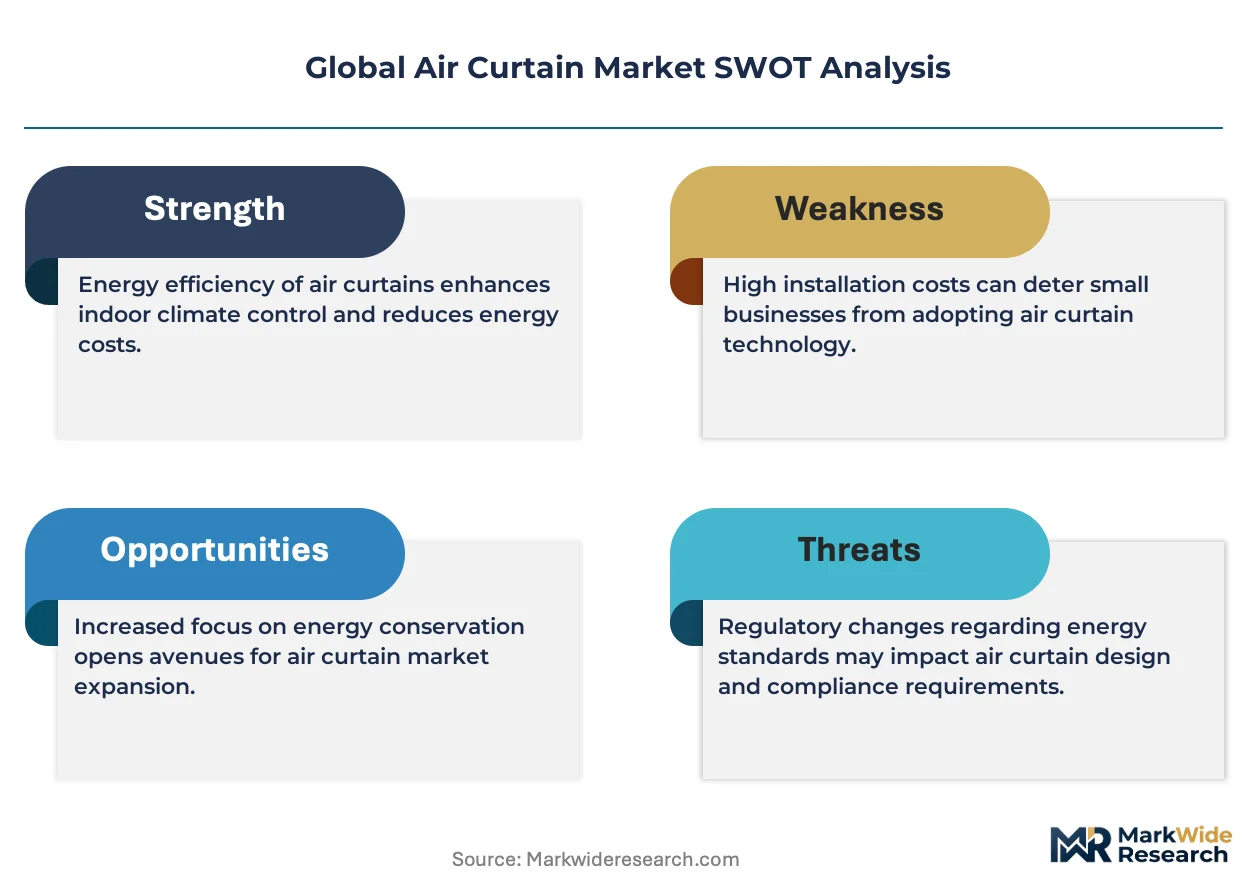
ISO 9001 certification cycles is collapsing the supplier base for premium commercial air curtains, leaving only quality-audited manufacturers in the running. Mars Air Systems leverages its vertical integration across motor fabrication and sheet-metal housing to sustain price competitiveness in North American distribution. Berner International anchors its position through deep channel control over specification-driven architectural and consulting engineer networks.
An air curtain is a fan-powered device that generates a high-velocity, laminar stream of air across an open doorway to separate two distinct environments without physical closure; units typically operate at air velocities between 1,500 and 3,500 feet per minute and incorporate centrifugal or cross-flow blowers driven by single-phase or three-phase motors. Electric air curtains dominate current volume due to simpler retrofit compatibility and lower installation cost, while hydronic variants capture margin pools in facilities with existing boiler infrastructure. Wall-mounted installation leads across retail and restaurant applications, though ceiling-recessed units are gaining specification share in new hospital construction where space constraints and aesthetic requirements converge.
The EU F-Gas Regulation and CE marking directives constrain refrigerant-linked air curtain configurations sold across Europe, while the U.S. Department of Energy efficiency standards shape motor and blower specifications for units deployed in American commercial buildings. China's GB standards and NMPA-equivalent equipment safety frameworks add compliance layers for manufacturers sourcing components from or selling into that manufacturing base. Stakeholders must monitor evolving efficiency thresholds and refrigerant-phaseout timelines to align R&D roadmaps with jurisdiction-specific compliance deadlines.
Market Dynamics
ISO 9001 certification cycles are collapsing the supplier base for premium commercial air curtains, concentrating procurement among quality-audited manufacturers while disqualifying uncertified competitors from specification-driven architectural channels.
Growth Catalysts
- EU F-Gas Regulation:Cold chain logistics operators in Germany and the Netherlands are expanding deployment at refrigerated loading docks to meet lower-GWP refrigerant compatibility mandates.
- Boiler infrastructure retrofit:Hydronic air curtains capture margin pools in facilities with existing heating systems, displacing electric units in institutional buildings with captive thermal assets.
- Texas and California distribution corridors:Demand concentrates in these U.S. logistics clusters where high-throughput fulfillment centers prioritize energy separation at dock doors.
Market Restraints
- Copper and electrical steel volatility:Motor fabrication costs fluctuate with commodity input prices, compressing margins for manufacturers without captive supply arrangements.
- Chinese component dependency:GB standards and NMPA-equivalent safety frameworks add compliance layers that extend qualification timelines for sourcing from this manufacturing base.
- Physical door substitution:High-speed roll-up doors compete for the same energy-separation applications in controlled environments with stricter thermal requirements.
Strategic Opportunities
- Hospital new construction:Ceiling-recessed units gain specification share where space constraints and aesthetic requirements converge in healthcare infrastructure.
- CE marking alignment:Manufacturers can capture displaced share from non-compliant suppliers as EU efficiency thresholds tighten refrigerant-linked configurations.
- IoT-enabled predictive maintenance:Sensor integration with building management systems creates recurring revenue streams through performance monitoring contracts.
Industry Challenges
- Aerodynamic engineering talent:Laminar airflow design expertise sits concentrated among legacy manufacturers, constraining new entrant product development velocity.
- Multi-jurisdiction certification lag:Simultaneous compliance with DOE efficiency standards, CE marking directives, and China's GB standards extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Curtain Market |
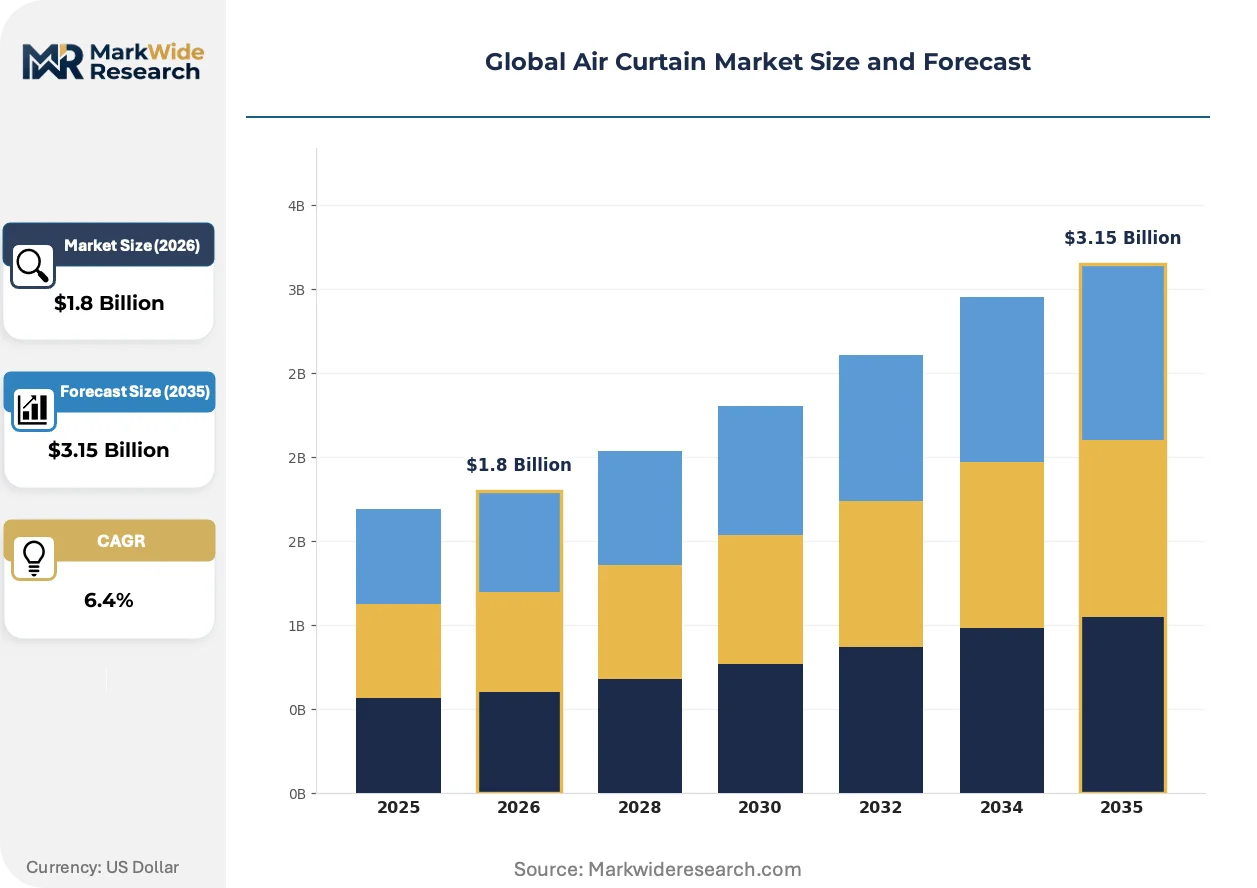
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
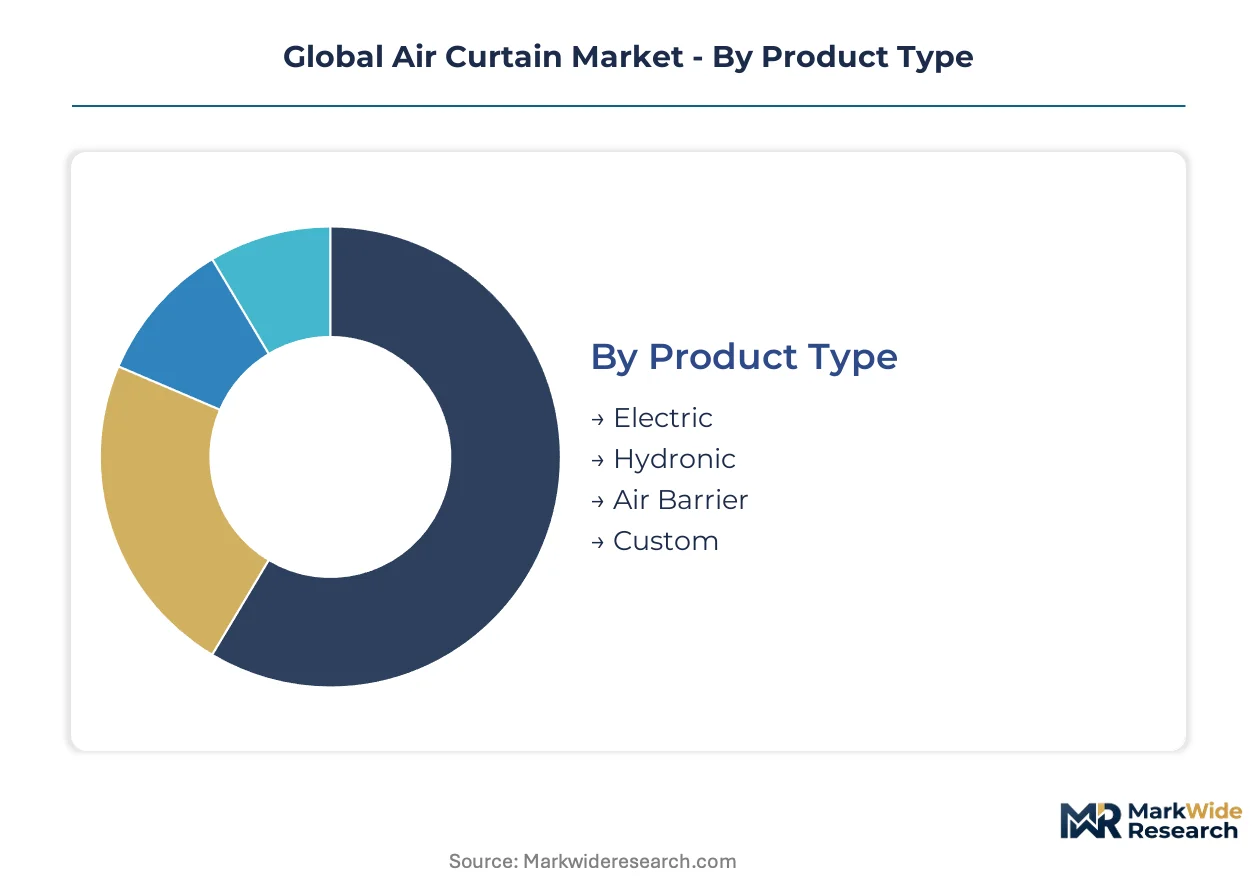
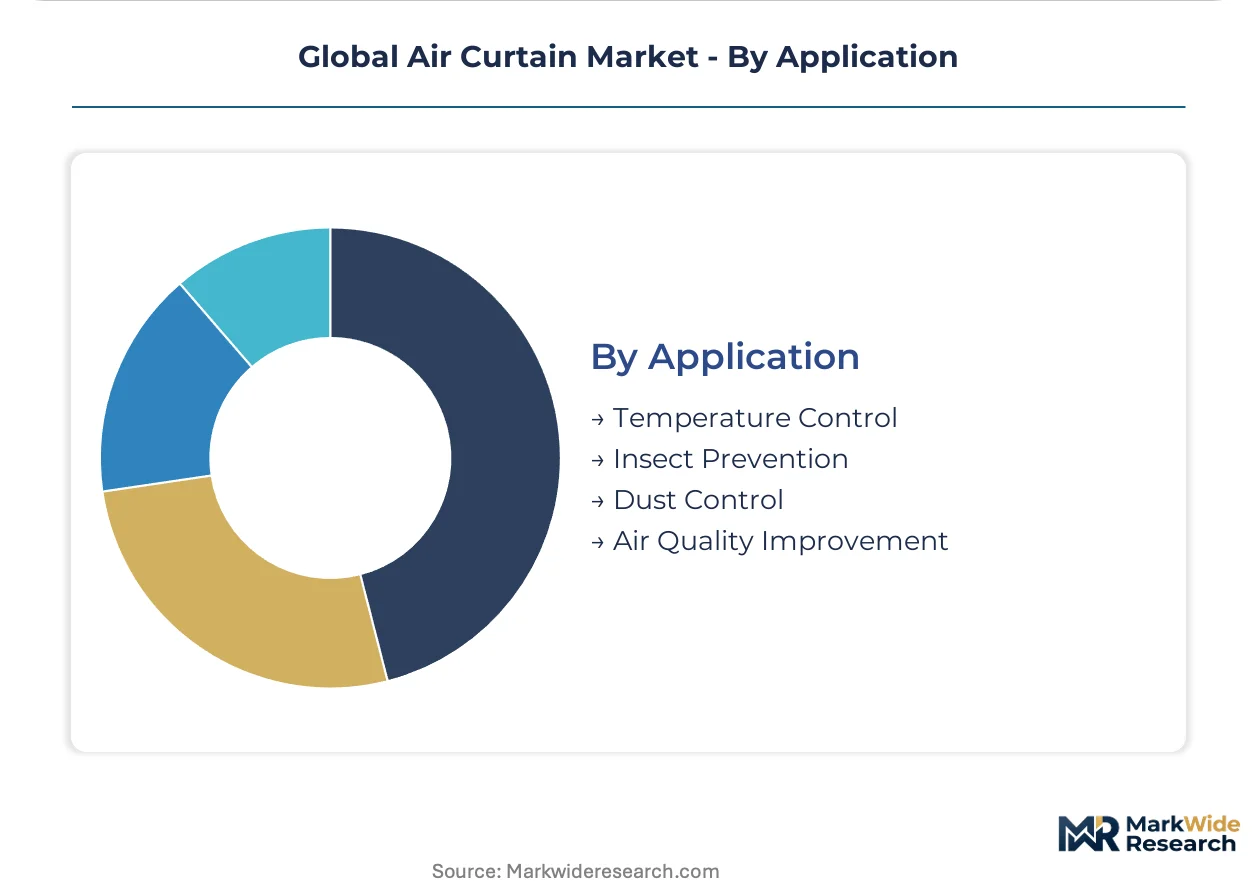
| Segmentation | Product Type: Electric, Hydronic, Air Barrier, Custom Installation Type: Wall-Mounted, Ceiling-Mounted, Portable, In-Built End User: Retail Stores, Warehouses, Hospitals, Restaurants Application: Temperature Control, Insect Prevention, Dust Control, Air Quality Improvement |
| Companies Covered | Mars Air Systems, Berner International, Panasonic Corporation, Mitsubishi Electric Corporation, Airtecnics, Frico AB, Systemair AB, Daikin Industries, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Curtain Market Emerging Trajectories
Active reshaping of the Global Air Curtain Market centers on three vectors: motor and blower technology divergence, regulatory compression of refrigerant-compatible designs, and specification channel consolidation among quality-certified suppliers.
EC motor technology is fragmenting the traditional single-phase and three-phase motor landscape in air curtain fabrication. Centrifugal blower manufacturers adopting electronically commutated drives are capturing specification share from legacy induction motor suppliers in retail and restaurant retrofit applications. This shift is compressing the addressable market for conventional motor architectures while expanding premium pricing tiers for efficiency-optimized configurations.
REACH and RoHS substance restrictions are constraining material choices in European-sold units, particularly affecting coatings and electrical insulation in motor windings. Manufacturers serving the EU market are reformulating component specifications to eliminate restricted substances ahead of compliance deadlines. Hospital and pharmaceutical end-uses in Germany and France face the tightest material qualification requirements, driving accelerated supplier audits.
Architectural specification channels are consolidating around quality-audited manufacturers with demonstrated compliance documentation. Consulting engineer networks in North America and Europe now require ISO 9001 certification as a minimum qualification threshold for commercial project inclusion. This behavioral shift disadvantages uncertified competitors and deepens incumbent control over high-value new construction specifications in Texas, California, and the Netherlands logistics corridors.
Global Air Curtain Market Segmentation
Air curtain procurement patterns diverge sharply across product architectures, mounting configurations, and end-use environments. Specification engineers weight thermal performance against installation constraints, while facility managers prioritize retrofit compatibility and operational cost profiles.
Product Type:
EU F-Gas Regulation and DOE efficiency standards create divergent compliance burdens across thermal technologies, advantaging designs with lower-GWP refrigerant compatibility and electronically commutated motor architectures.
- Electric:Single-phase and three-phase motor configurations dominate retrofit installations due to simplified electrical infrastructure requirements. Demand concentrates in Texas and California distribution corridors where fulfillment centers prioritize rapid deployment at dock doors without boiler dependencies.
- Hydronic:Coil-based heat exchange systems leverage existing boiler infrastructure in institutional buildings, capturing margin pools in German cold chain logistics facilities and Netherlands refrigerated loading docks where captive thermal assets reduce operating expenditure.
- Air Barrier:Unheated laminar flow units serve climate-moderated separation applications in retail and restaurant environments.
- Custom:Bespoke specifications address pharmaceutical cleanrooms and hospital surgical suites with material qualifications under REACH and RoHS substance restrictions.
Established volume favors Electric; emerging adoption favors Hydronic.
Installation Type:
Mounting configuration selection tracks building vintage, ceiling height constraints, and aesthetic requirements across healthcare, retail, and logistics end-uses.
- Wall-Mounted:Bracket-attached units at 2.1-3.0 meter heights serve retrofit retail and restaurant applications with minimal structural modification. Specification share concentrates in existing commercial building stock across US distribution corridors where rapid deployment outweighs spatial integration concerns.
- Ceiling-Mounted:Recessed and surface-mounted configurations address space constraints in German and French hospital new construction where consulting engineer networks prioritize aesthetic integration with HVAC systems.
- Portable:Freestanding units enable temporary deployment in seasonal retail and event logistics applications.
- In-Built:Architecturally integrated systems embed within façade elements for specification-driven new construction in Netherlands logistics facilities.
Wall-Mounted retains procurement volume leadership; Ceiling-Mounted climbs the fastest in healthcare specifications.
End User:
Facility type determines performance tier requirements, maintenance protocols, and specification channel access.
- Retail Stores:High-traffic entrance applications prioritize reliability and visual integration with storefront design. Deployment concentrates in US regional shopping corridors where energy separation at automatic doors reduces HVAC load.
- Warehouses:Loading dock thermal barriers dominate cold chain logistics specifications in Germany and the Netherlands, driven by EU F-Gas Regulation compliance mandates for lower-GWP refrigerant-compatible configurations.
- Hospitals:Infection control and space constraints drive ceiling-recessed specifications in Texas and California healthcare construction.
- Restaurants:Kitchen-to-dining separation and insect prevention guide compact wall-mounted selection in high-turnover food service environments.
Warehouse procurement leads absolute volume; Hospital specifications command premium pricing tiers.
Application:
Functional purpose shapes blower specification, velocity calibration, and control system complexity.
- Temperature Control:Heated and unheated laminar flow systems maintain thermal zones across open doorways. Cold chain logistics operators in Germany specify high-velocity configurations for refrigerated dock applications under tightening EU efficiency thresholds.
- Insect Prevention:High-velocity air streams at 1,500-2,500 feet per minute block flying pest ingress. Food service and pharmaceutical facilities in California distribution corridors deploy these units under USDA-adjacent sanitation protocols.
- Dust Control:Filtered air barrier systems protect clean manufacturing environments from particulate contamination.
- Air Quality Improvement:Integrated filtration and ionization configurations address indoor environmental quality in Texas healthcare and Netherlands logistics facilities.
Temperature Control anchors procurement volume; Air Quality Improvement gains specification share in healthcare infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites the Netherlands' position as Europe's refrigerated logistics gateway, while the Texas-California distribution corridor anchors North American throughput. These named assets concentrate air curtain deployment at loading docks where thermal separation reduces energy expenditure.
United States
Fulfillment centers along the Texas-California logistics corridor deploy electric air curtains at high-velocity dock doors to manage HVAC loads. DOE efficiency standards shape motor specifications for commercial buildings. Dallas-Fort Worth and Los Angeles Basin distribution clusters prioritize rapid retrofit compatibility over hydronic infrastructure.
Germany
Cold chain operators at Hamburg and Bremerhaven ports expand refrigerated loading dock installations under EU F-Gas Regulation mandates. REACH substance restrictions constrain motor winding coatings and electrical insulation materials. Bavarian pharmaceutical manufacturers specify custom units for cleanroom applications with stringent material qualifications.
Netherlands
Rotterdam port logistics operators deploy lower-GWP refrigerant-compatible configurations at temperature-controlled warehouses. CE marking directives govern equipment safety frameworks for European distribution. Eindhoven region cold storage facilities integrate ceiling-recessed units with existing HVAC infrastructure.
China
GB standards and NMPA-equivalent safety frameworks extend qualification timelines for component sourcing and finished equipment sales. Dual carbon goals accelerate efficiency-optimized motor adoption in commercial buildings. Yangtze River Delta manufacturing clusters supply centrifugal blowers to international OEMs.
Japan
METI efficiency guidelines shape electronically commutated motor specifications for commercial building retrofits. JIS standards govern equipment safety and performance testing protocols. Kanto region Tokyo-Osaka logistics corridor concentrates specification-driven procurement for retail and hospital applications.
Global Air Curtain Market Vendor Landscape
Listed leaders compete with private specialists across motor fabrication and sheet-metal housing integration. The supplier base concentrates among ISO 9001-certified manufacturers as uncertified competitors face disqualification from architectural specification channels. Three archetypes dominate: vertically integrated motor fabricators, specification-driven architectural specialists, and scale-oriented HVAC conglomerates. Competitive moves center on backward integration into captive motor production and deep channel control over consulting engineer networks.
Within the vertically integrated tier, Mars Air Systems and Berner International exemplify contrasting strategic positions. Mars Air Systems represents the fabrication-integrated archetype through in-house motor and housing production. Berner International occupies the specification-channel specialist position through architectural and consulting engineer network penetration. Panasonic Corporation anchors the diversified electronics conglomerate archetype with scale advantages in motor and control system manufacturing.
| Leading Market Players |
|---|
| Mars Air Systems |
| Berner International |
| Panasonic Corporation |
| Mitsubishi Electric Corporation |
| Airtecnics |
| Frico AB |
| Systemair AB |
| Daikin Industries |
| Toshiba Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Yangtze River Delta motor fabricators lock in both centrifugal blower supply access and eighteen-month price visibility for North American OEMs navigating copper and electrical steel volatility.
Pricing Analysis
Volume-discount tiering structures stratify across ISO 9001-certified premium manufacturers, standard-tier electric motor suppliers, and uncertified economy producers. Price differentiation hinges on certification grade and captive motor production, with premium tiers commanding margin premiums for EC motor architectures. Pricing pressure stems from commodity input volatility in copper windings and laminated electrical steel. Cold chain logistics operators in Germany exhibit lowest price sensitivity due to regulatory compliance mandates, while US retail retrofit buyers prioritize lowest installed cost.
Supply Chain Analysis
Yangtze River Delta manufacturing clusters anchor global centrifugal blower and EC motor component supply. Raw material dependencies center on copper cathodes, cold-rolled electrical steel, and rare-earth magnet materials for advanced motor architectures. Supply chain risk concentrates in single-source vulnerability for high-efficiency motor laminations subject to export licensing delays. Distribution runs through specification-driven architectural channels in North America and Europe, with direct OEM procurement dominating volume tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where ISO 9001 certification creates regulatory entrenchment, erecting switching costs that disqualify uncertified competitors from specification-driven architectural channels.
For Market Incumbents: Consolidate specification channel control through deeper penetration of consulting engineer networks in Texas and California distribution corridors. Acquire hydronic coil fabrication capabilities to capture margin pools in German cold chain logistics facilities with captive boiler infrastructure. Defensive positioning against EC motor technology disruption requires accelerated R&D in electronically commutated architectures. For New Entrants and Emerging Players: CE marking fast-track programs offer the most penetrable entry path for capturing share from non-compliant suppliers as EU F-Gas Regulation deadlines tighten. Target hospital new construction segments in the Netherlands and Germany where ceiling-recessed specifications favor aesthetic integration over incumbent brand loyalty. Go-to-market execution should prioritize direct specification engagement with healthcare facility consulting engineers rather than distribution channel competition. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated motor fabricators with demonstrated ISO 9001 certification and established specification channel relationships. Long-term viability across a five-to-ten year window favors manufacturers with backward integration into sheet-metal housing and captive EC motor production. Watch for inflection signals in EU F-Gas Regulation enforcement intensity and REACH substance restriction expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EC Motor Production | Captures efficiency-optimized premium tiers as DOE standards tighten motor specifications. |
| CE Marking Alignment Investment | Displaces non-compliant competitors from EU cold chain logistics specifications under F-Gas mandates. |
| Hydronic Coil Capability Addition | Captures margin pools in German and Netherlands facilities with existing boiler infrastructure. |
| Consulting Engineer Network Expansion | Deepens specification control in Texas and California healthcare new construction channels. |
| IoT Sensor Integration Development | Creates recurring revenue streams through predictive maintenance contracts with building management systems. |
Methodological Framework
Two parallel data streams informed the analysis: primary engagement with specification engineers, facility maintenance directors, and HVAC procurement managers across retail, healthcare, and logistics verticals; and secondary validation through DOE efficiency standard filings, EU F-Gas Regulation compliance databases, customs trade records for motor and blower components, and SEC 10-K disclosures from listed HVAC conglomerates. Bottom-up unit deployment estimates triangulated against top-down construction spending and cold chain infrastructure investment data.
Across the analysis window, the forecast framework modeled product type segmentation across electric, hydronic, and custom thermal technologies; installation configurations spanning wall-mounted, ceiling-recessed, and in-built systems; and end-use environments including warehouse logistics, hospital construction, and retail retrofit. CAGRs derived from regression analysis against construction permit data, cold chain capacity expansion announcements, and regulatory compliance deadline schedules. Industry-specific inputs incorporated EU refrigerant phaseout timelines and US efficiency standard revision trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EU F-Gas Regulation enforcement and stable copper pricing; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as REACH substance restriction scope and Chinese GB standards alignment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Air Humidifier and Dehumidifier Market