
 Global Smart Vent Market | 2026-2036
Global Smart Vent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Vent Market Outlook
China is reconfiguring smart vent component manufacturing through expanded Shenzhen and Dongguan electronics corridors. Honeywell leverages its building automation heritage to dominate commercial-grade connected vent systems across North America. Ecobee specializes in Wi-Fi-enabled residential vents with deep thermostat integration, while Tado anchors European market presence through utility partnership channels.
A smart vent is an electronically controlled airflow management device that modulates temperature, humidity, and air quality through motorized louvers, pressure sensors, and wireless communication protocols operating at 2.4 GHz frequency bands. Its primary purpose is to replace static HVAC grilles with zone-responsive units that reduce energy waste by directing conditioned air only to occupied spaces. Motorized vents lead product type revenue due to mature actuator supply chains and installer familiarity, while connected vents represent the fastest-expanding margin pool as subscription-based energy analytics attach to hardware sales. Retrofit installation outpaces new construction in regions with aging building stock and aggressive efficiency retrofit mandates.
The EPA ENERGY STAR program and EU F-Gas Regulation shape product efficiency benchmarks and refrigerant-adjacent HVAC component standards, while China's GB standards enforce electromagnetic compatibility for wireless building devices. FDA oversight does not extend to smart vents, though FCC certification governs radio frequency emissions in the United States. Stakeholders must monitor evolving interoperability mandates between competing wireless protocols as regulatory pressure on building decarbonization intensifies without harmonized cross-border certification frameworks.
Market Dynamics
The EU F-Gas Regulation and EPA ENERGY STAR mandates are compressing product development cycles while retrofit installation economics pull demand toward zone-responsive airflow management. Component suppliers in Shenzhen and Dongguan corridors face capacity constraints as motorized actuator demand outpaces foundry expansion.
Growth Catalysts
- EU Green Deal retrofit mandates:Germany and France enforce building efficiency standards that accelerate replacement of static HVAC grilles with connected zone controls in residential and light commercial structures.
- Wi-Fi 6 protocol adoption:Lower latency wireless communication enables real-time pressure balancing and occupancy-responsive louver positioning without dedicated hub infrastructure.
- Utility demand-response programs:Pacific Gas and Electric and Southern California Edison incentivize residential smart vent installation through bill credits tied to peak-load curtailment.
Market Restraints
- Neodymium magnet cost volatility:Rare earth price swings from Chinese export quotas directly impact motorized vent actuator manufacturing margins.
- Wireless protocol fragmentation:Zigbee, Z-Wave, Thread, and proprietary mesh standards create interoperability friction that lengthens procurement cycles for multi-vendor building automation deployments.
- Static grille substitution:Basic adjustable metal vents at one-tenth the unit cost satisfy price-sensitive landlords in secondary US and Eastern European rental markets.
Strategic Opportunities
- India affordable housing retrofit:Bureau of Indian Standards energy efficiency codes for residential construction create first-mover positioning for cost-optimized connected vent systems.
- AI-driven predictive maintenance:Machine learning models analyzing pressure sensor drift and motor current signatures enable subscription-based HVAC component health monitoring.
- Net-zero building certification:LEED v4.1 and BREEAM Outstanding ratings require granular zone-level airflow control that static distribution systems cannot satisfy.
Industry Challenges
- Building automation technician scarcity:Shortage of certified installers familiar with commissioning wireless mesh networks and pressure-balancing protocols extends project timelines.
- Legacy thermostat integration:Proprietary API limitations from incumbent climate control manufacturers block seamless interoperability with third-party smart vent ecosystems.
- Electromagnetic compliance testing:FCC Part 15 and CE RED certification cycles for new radio frequency modules delay product launches by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Vent Market |
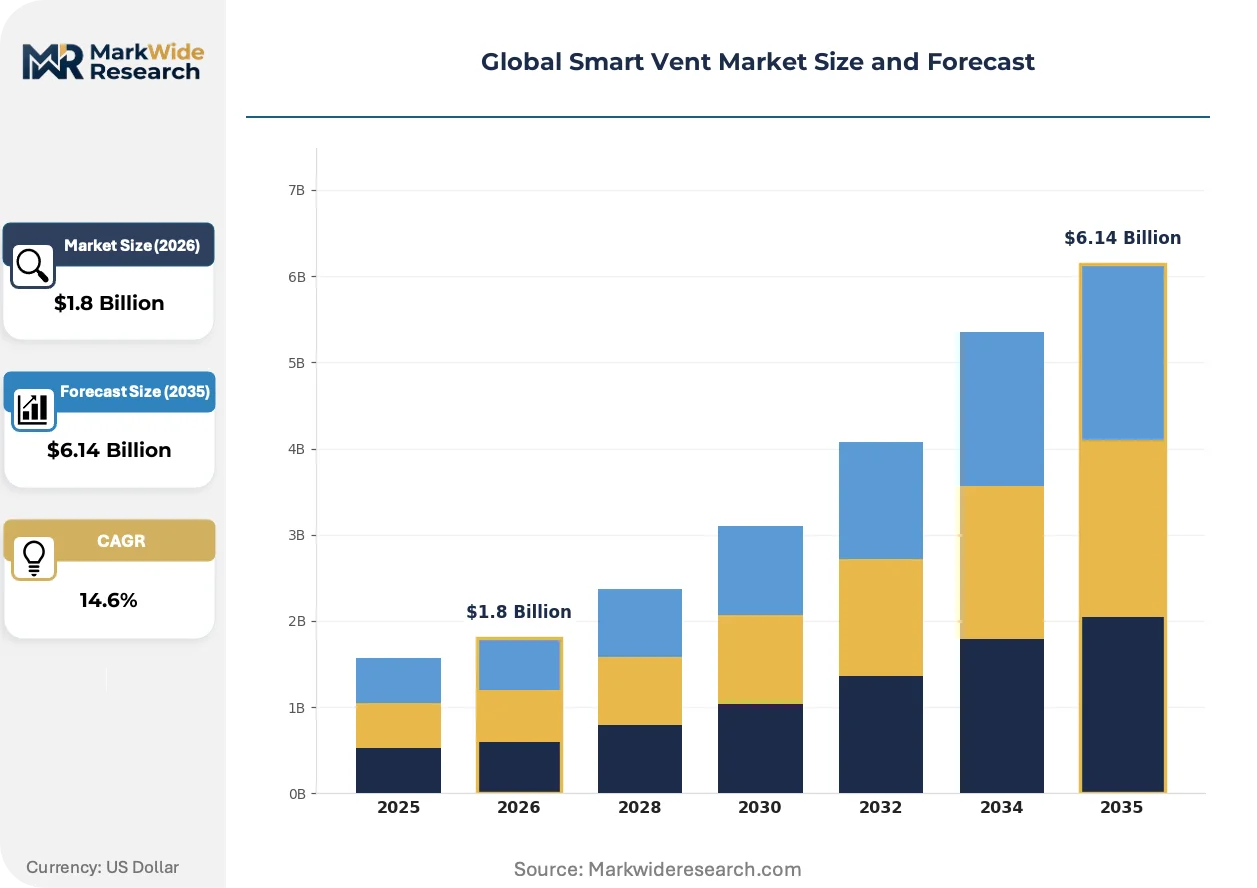
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized Vents, Manual Vents, Connected Vents, Smart Partitions Installation Type: New Construction, Retrofit, DIY, Professional Installation End User: Residential, Commercial, Industrial, Hospitality Technology: Wi-Fi Enabled, Zigbee, Z-Wave, Bluetooth, Others |
| Companies Covered | Honeywell, Nest Labs, Ecovent, Flair, Keen Home, Johnson Controls, Ecobee, Tado, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Vent Market Strategic Shifts
Machine learning inference at the edge is compressing response latency for occupancy detection while battery-free energy harvesting eliminates wiring constraints in retrofit applications. Component miniaturization and solid-state actuator development are simultaneously reshaping product form factors and maintenance economics.
MEMS-based pressure sensors with onboard signal processing are rendering obsolete traditional electromechanical differential pressure switches in residential smart vent designs. Multi-family housing developers in Texas and Florida specify these solid-state alternatives for their zero-calibration requirements and decade-long service intervals. The elimination of mechanical wear points compresses warranty reserve requirements and enables sealed-unit construction.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants tightens efficiency benchmarks for adjacent HVAC components including air distribution systems. Equipment manufacturers serving the German and Dutch markets redesign duct networks to accommodate higher static pressure losses from smaller-diameter, higher-velocity smart vent terminals. This regulatory pressure accelerates R&D spending on low-pressure-drop louver geometries.
Property management platforms now bundle smart vent hardware into tenant experience apps that monetize comfort optimization as a premium amenity. Greystar and AvalonBay pilot subscription models in Class-A multifamily assets where residents pay monthly fees for personalized zone control. This channel innovation concentrates in Sun Belt metros where cooling-dominated climates maximize energy savings visibility.
Global Smart Vent Market Segmentation
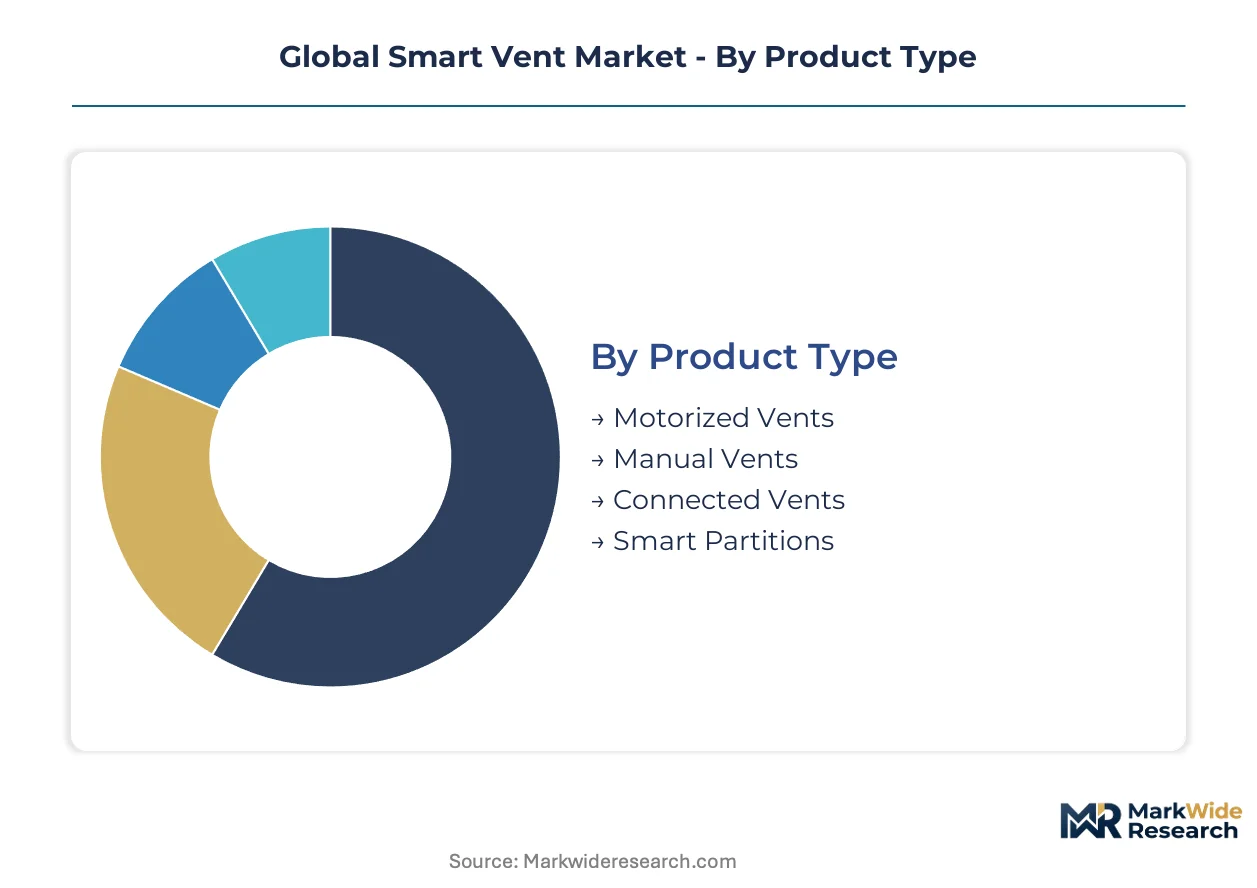
Smart vent segmentation reveals how hardware specifications, deployment pathways, and connectivity protocols fragment addressable demand across radically different buyer economics. Product architecture choices determine whether vendors capture retrofit renovation spend or new construction specification.
Product Type:
Cost tier stratification separates mature actuator-based hardware from emerging subscription-attached intelligence layers.
- Motorized Vents:Electromechanical louvers driven by DC stepper motors and neodymium magnet assemblies enable programmable zone damper functionality without network dependency. Demand concentrates in German residential retrofits where EU Green Deal efficiency mandates accelerate replacement of static grilles in aging multifamily housing stock.
- Connected Vents:Wi-Fi or mesh-enabled units bundle pressure sensors, occupancy detection, and cloud analytics for real-time HVAC optimization. The fastest expansion runs through US utility demand-response programs where Pacific Gas and Electric and Southern California Edison monetize peak-load curtailment through residential bill credits.
- Manual Vents:Basic adjustable metal louvers without electronic actuation satisfy price-sensitive landlords in secondary US rental markets.
- Smart Partitions:Architectural room dividers with integrated airflow management target open-plan commercial fit-outs in Japan and South Korea.
Motorized vents command the established base. The steepest expansion runs through connected vents.
Installation Type:
Deployment pathway determines margin structure and customer acquisition cost exposure across professional versus self-service channels.
- Retrofit:Battery-powered or energy-harvesting designs eliminate wiring constraints in existing structures. Demand concentrates in North American and European regions with aging building stock where aggressive efficiency retrofit mandates compress payback periods for zone-responsive airflow management.
- New Construction:Hardwired smart vent specification during build-out enables deeper Building Management System integration. German and Dutch equipment manufacturers redesign duct networks to accommodate higher static pressure losses from smaller-diameter, higher-velocity terminals.
- DIY:Self-installation kits with magnetic mounting and plug-and-play commissioning target residential consumers through Amazon and home improvement retail channels.
- Professional Installation:Certified technician deployment ensures pressure-balancing calibration and wireless mesh network commissioning for multi-zone commercial deployments.
Retrofit installation captures volume leadership. New construction specification delivers the most durable margin expansion trajectory.
End User:
Customer type segmentation maps divergent performance requirements and procurement authority structures across building categories.
- Residential:Single-family and multifamily dwellings drive unit volume through thermostat integration and utility incentive programs. Class-A multifamily developers in Texas and Florida pilot subscription-based comfort optimization as premium tenant amenities.
- Commercial:Office and retail deployments prioritize BACnet integration and centralized facility management dashboards. LEED v4.1 and BREEAM Outstanding ratings require granular zone-level airflow control that static distribution systems cannot satisfy.
- Industrial:Manufacturing and warehouse applications demand ruggedized actuators with extended temperature tolerance and particulate-resistant sensor housings.
- Hospitality:Hotel guest room installations balance individual climate control with housekeeping override protocols and energy management system integration.
Residential applications anchor unit shipments. Commercial deployments generate the highest average revenue per installation.
Technology:
Wireless protocol selection creates interoperability friction that shapes procurement cycles and ecosystem lock-in dynamics.
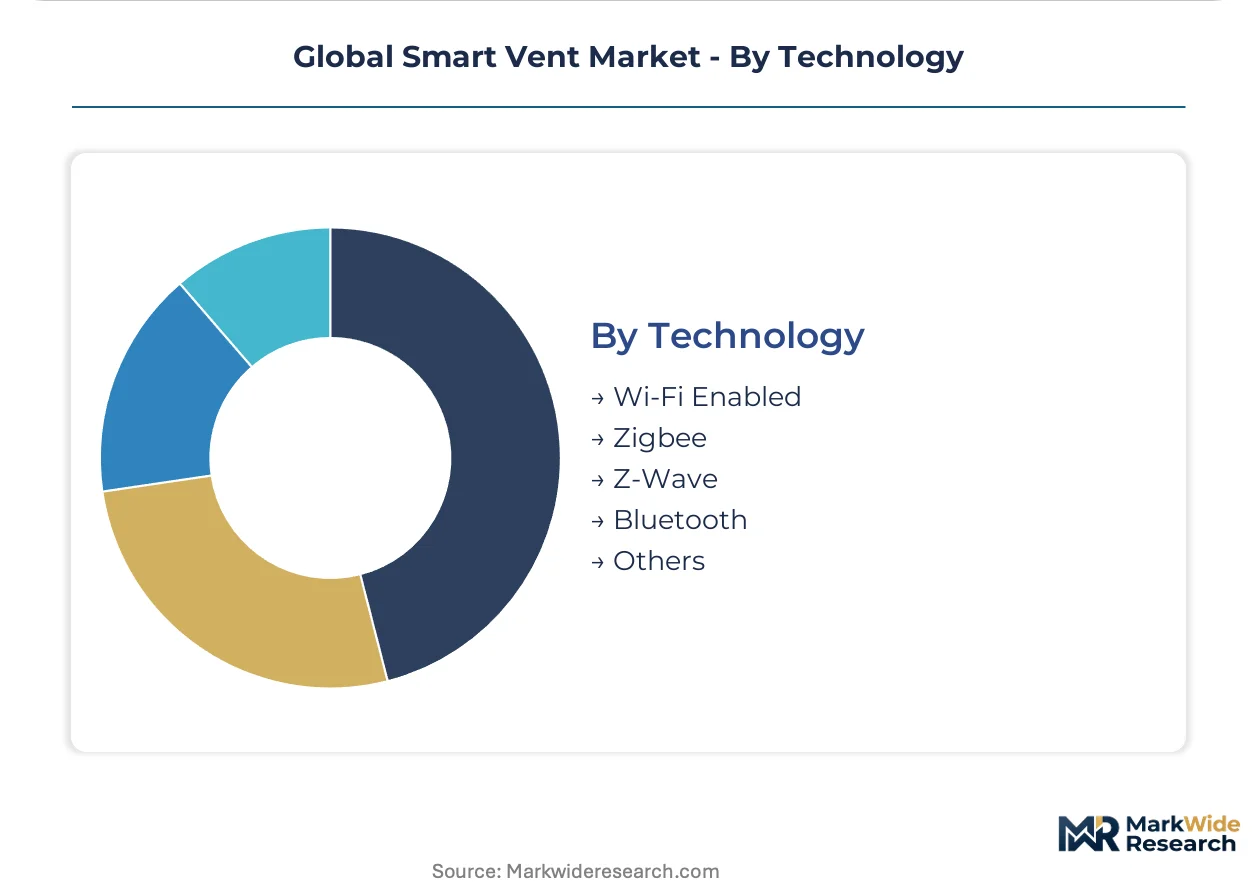
- Wi-Fi Enabled:Direct router connectivity eliminates hub infrastructure and leverages ubiquitous residential network coverage. Wi-Fi 6 protocol adoption enables real-time pressure balancing without dedicated controller hardware.
- Zigbee:Mesh networking with low power consumption suits battery-operated retrofit vents in multi-room residential deployments.
- Z-Wave:Sub-GHz frequency penetration through building materials supports installations in dense European masonry construction.
- Bluetooth:Point-to-point commissioning and firmware updates complement primary wireless backhauls rather than standalone operation.
- Others:Thread protocol and proprietary mesh standards serve ecosystem-specific deployments from major building automation vendors.
Wi-Fi-enabled products dominate residential penetration. Zigbee and Z-Wave retain strength in professionally installed multi-zone systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Shenzhen and Dongguan anchor supply-side capacity, while demand-side momentum concentrates in jurisdictions with aggressive building efficiency mandates and mature smart home infrastructure.
United States
Utility demand-response programs from Pacific Gas and Electric and Southern California Edison monetize residential smart vent installation through peak-load curtailment incentives. The EPA ENERGY STAR program shapes product efficiency benchmarks for HVAC distribution components. Installer networks concentrate in Texas and Florida where Class-A multifamily developers pilot subscription-based comfort optimization.
Germany
EU Green Deal retrofit mandates accelerate replacement of static HVAC grilles in aging multifamily housing stock. The EU F-Gas Regulation tightens efficiency benchmarks for adjacent air distribution systems. Equipment manufacturers in the Rhine-Ruhr and Bavaria regions redesign duct networks to accommodate higher static pressure losses from smart vent terminals.
China
GB standards enforcement for electromagnetic compatibility governs wireless building device certification. Dual carbon goals drive building automation adoption in commercial construction. Shenzhen and Dongguan electronics corridors face capacity constraints as motorized actuator demand outpaces foundry expansion.
Japan
METI efficiency standards for commercial buildings create specification pathways for zone-responsive airflow management. JIS standards govern building automation component interoperability. Tokyo and Osaka metropolitan areas anchor demand for smart partition systems in open-plan commercial fit-outs.
India
Bureau of Indian Standards energy efficiency codes for residential construction create first-mover positioning for cost-optimized connected vent systems. The country's national building regulator advances mandatory efficiency benchmarks for new construction. Maharashtra and Gujarat industrial corridors attract component assembly investments serving affordable housing retrofit demand.
Global Smart Vent Market Competitive Environment
Building automation conglomerates and connected home specialists split the market across divergent channel economics and customer acquisition strategies. The vendor base organizes around heritage in climate control systems versus native digital infrastructure. Three archetypes dominate: diversified industrial conglomerates with BMS integration capabilities, thermostat-native platforms leveraging Wi-Fi connectivity, and utility-partnership channels optimizing for demand-response program eligibility. Competitive moves concentrate on strategic partnerships with property management platforms and backward integration into actuator component supply.
Among diversified industrial conglomerates, Honeywell and Johnson Controls exemplify the building automation heritage archetype, anchoring commercial-grade specification through established installer networks and BACnet integration capabilities. Ecobee and Tado occupy distinct positions within the connected home specialist tier, with the former representing thermostat-native platform strategies and the latter exemplifying utility-channel partnership models. Nest Labs sits within the consumer electronics ecosystem archetype, leveraging parent-company infrastructure for residential smart home integration. These three archetypes—industrial conglomerate, connected home native, and platform-integrated consumer brand—capture divergent margin pools across commercial specification, residential retrofit, and mass-market retail channels.
| Leading Market Players |
|---|
| Honeywell |
| Nest Labs |
| Ecovent |
| Flair |
| Keen Home |
| Johnson Controls |
| Ecobee |
| Tado |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
The Shenzhen-Dongguan electronics corridor's freight cost dynamics compress margins for motorized actuator suppliers while simultaneously enabling price differentiation between premium connected vents and basic motorized units. Neodymium magnet volatility from Chinese export quotas feeds directly into tiered hardware pricing, with downstream buyers in German retrofit markets absorbing cost pass-through more readily than price-sensitive US landlords.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by mandating efficiency benchmarks that separate certified connected vents from basic motorized alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales analytics bundling. Cost compression in the economy tier is intensifying because static grille substitution satisfies secondary rental markets at one-tenth the unit cost. Commercial buyers with LEED certification requirements exhibit the lowest price sensitivity, while Eastern European landlords demonstrate acute elasticity.
Supply Chain Analysis
Extended payment terms from Shenzhen contract manufacturers to Dongguan assembly facilities reveal working capital stress throughout the actuator supply base. Component manufacturing draws from China for neodymium magnets and PCB assemblies, Germany for precision sensor modules, and Taiwan for MEMS fabrication. Single-source vulnerability concentrates in rare earth magnet procurement where Chinese export quotas disrupt foundry expansion timelines. Distribution runs through building automation installer networks in North America and utility partnership channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward property management platforms consolidating procurement authority across Class-A multifamily portfolios. This consolidation fragments negotiating leverage for standalone hardware vendors.
For Market Incumbents: Build ecosystem lock-in moats through deep thermostat API integration and proprietary mesh protocol deployment. Honeywell and Johnson Controls should accelerate backward integration into MEMS pressure sensor supply to offset neodymium cost volatility. Threat from Wi-Fi 6 native entrants demands defensive certification investment for ENERGY STAR and CE RED compliance. For New Entrants and Emerging Players: Build out India affordable housing retrofit channels where Bureau of Indian Standards codes create first-mover positioning for cost-optimized connected vents. White-space concentrates in battery-free energy harvesting designs for aging European masonry construction. Go-to-market leverage rests on utility demand-response program eligibility rather than retail shelf presence. For Investors and Strategic Acquirers: Actuator component specialists with captive foundry relationships represent the most defensible acquisition archetype for long-term positioning through the building decarbonization cycle. Signal to monitor: FCC Part 15 certification backlogs as inflection indicator for new entrant velocity and competitive pressure release.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sensors | Cuts dependency on German sensor imports while compressing warranty reserve requirements for sealed-unit designs. |
| Utility Demand-Response Partnership | Pacific Gas and Electric and Southern California Edison bill credit programs monetize peak-load curtailment through residential installation incentives. |
| Wi-Fi 6 Protocol Migration | Eliminates dedicated hub infrastructure and enables real-time pressure balancing for occupancy-responsive louver positioning. |
| AI-Driven Predictive Maintenance Launch | Machine learning models analyzing motor current signatures unlock subscription-based HVAC component health monitoring revenue. |
| India Affordable Housing Channel Expansion | Maharashtra and Gujarat industrial corridors attract assembly investments serving Bureau of Indian Standards retrofit mandates. |
Study Parameters
A spread of perspectives from HVAC systems integrators, building automation procurement officers, MEMS sensor R&D directors, utility demand-response program managers, and multifamily property technology leads converged on the working assumptions. Primary fieldwork combined with secondary validation against EPA ENERGY STAR filings, EU F-Gas Regulation implementation guidance, FCC Part 15 certification databases, and China GB standards documentation. Bottom-up unit economics triangulated against top-down building stock retrofit penetration models.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture tier, installation pathway, wireless protocol type, end-use building category, and regional regulatory cluster. CAGRs derived from pressure-balancing adoption curves and utility incentive program expansion trajectories. Forecast inputs incorporated neodymium price elasticity coefficients and Wi-Fi 6 router penetration assumptions.
Stress conditions across rare earth export quota severity, wireless protocol interoperability mandates, and building automation technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about retrofit incentive persistence and smart home platform consolidation. Macroeconomic contraction, regulatory harmonization failure, or solid-state actuator breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Germany Heat Pump Market