
 US and Canada Corner Beads and Caps Market | 2026-2036
US and Canada Corner Beads and Caps Market Size, Share, and Industry Trends Forecast 2026-2036
US and Canada Corner Beads and Caps Market Outlook
The US Midwest is rewriting capacity dynamics for corner bead and cap manufacturing as domestic producers expand galvanized steel and vinyl extrusion lines to shorten lead times. ClarkDietrich Building Systems leverages its integrated coil-to-finished-product model to control cost volatility across the Great Lakes corridor. Trim-Tex Inc. anchors the premium vinyl segment through proprietary compound formulations that resist corner cracking in freeze-thaw cycles. Super Stud Building Products dominates light-gauge steel framing accessories, extending its distribution reach through specialty drywall contractor channels.
Corner beads and caps are edge-reinforcement and finishing accessories installed at drywall panel intersections, typically manufactured from galvanized steel, vinyl extrusions, or paper-faced metal with leg dimensions ranging from 7/8 inch to 1-1/4 inch to accommodate standard mud depths. These components prevent corner damage, provide a straight mudding reference, and determine final wall surface durability in both residential and commercial interiors. Metal corner beads retain the largest volume share in commercial renovation where impact resistance governs specification, while vinyl corner beads represent the fastest-growing material category in residential construction as builders prioritize corrosion immunity in humid climates. The distribution channel structure shows margin pools concentrating with specialty distributors who bundle corner beads with joint compound and fastener assortments for contractor job-site delivery.
OSHA silica exposure limits and EPA lead-safe renovation standards directly shape product composition and installation protocol, pushing manufacturers toward low-dust paper-faced alternatives and pre-finished caps that minimize on-site sanding. The National Association of Home Builders certification programs and ASTM C1047 specifications for metal corner beads create tiered quality benchmarks that influence contractor loyalty and architect specification behavior. Stakeholders must monitor evolving state-level energy codes in California and New York that integrate interior air sealing with drywall finishing details, potentially elevating cap performance requirements for airtight construction assemblies.
Market Dynamics
Residential construction velocity across the Sun Belt is compressing lead-time tolerance for corner bead and cap suppliers, forcing distributors to hold larger safety stocks of vinyl and galvanized steel variants near job-site clusters.
Growth Catalysts
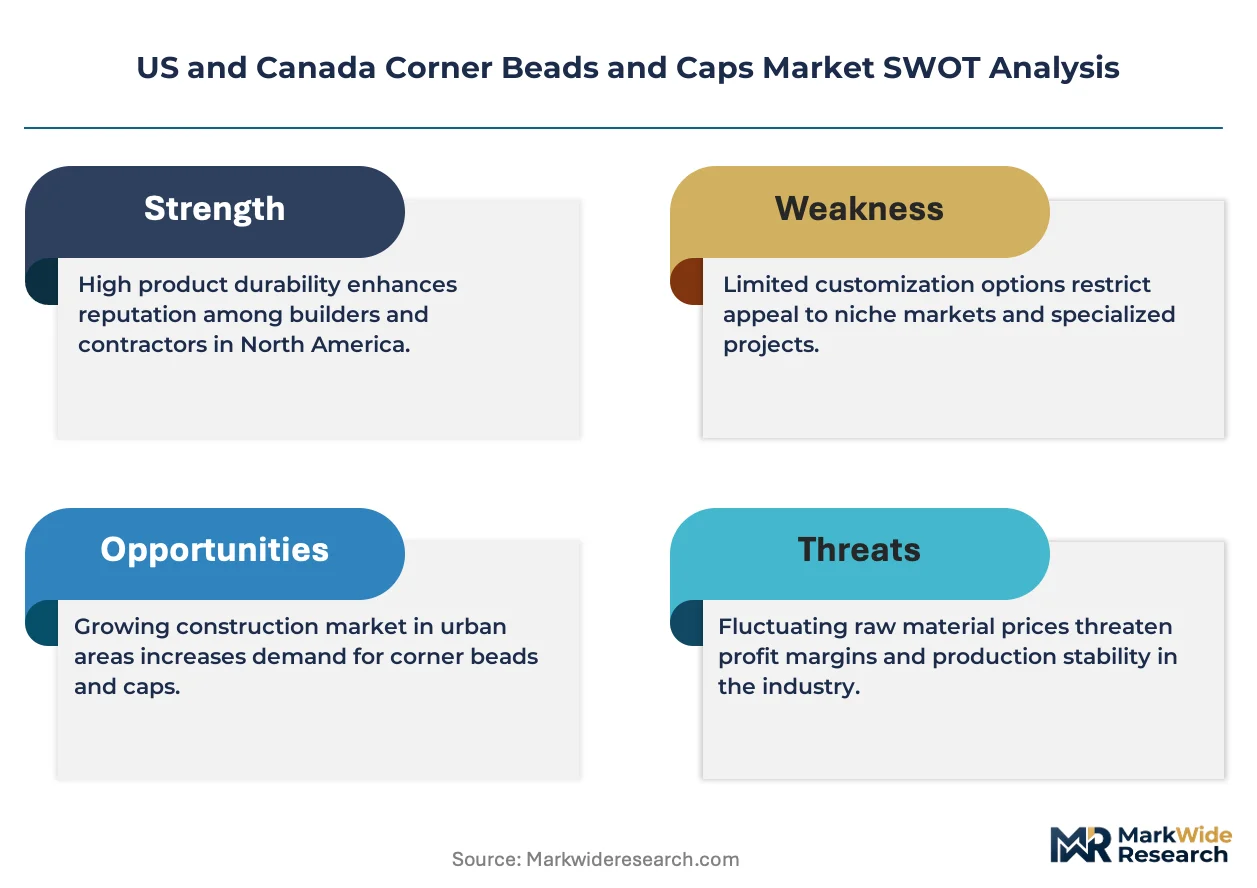
- EPA Lead-Safe Renovation Rules:Contractors performing renovation, repair, and painting in pre-1978 housing must follow strict containment protocols, elevating demand for pre-finished caps that minimize on-site sanding dust.
- Texas Housing Starts:The state's metropolitan construction corridors generate concentrated demand for corrosion-resistant vinyl corner beads suited to humid Gulf Coast conditions.
- Green Building Codes:Evolving state-level energy standards in California and New York integrate interior air sealing with drywall finishing details, expanding specification scope for high-performance cap assemblies.
Market Restraints
- Steel Input Volatility:Galvanized coil prices fluctuate with scrap metal and zinc coating costs, compressing margin predictability for domestic metal corner bead producers.
- Midwest Supply Concentration:A narrow corridor of integrated coil-to-finished-product facilities around the Great Lakes creates geographic vulnerability to winter logistics disruptions.
- Paper-Faced Metal Substitution Limits:Low-dust paper-faced alternatives reduce silica exposure but carry higher per-unit cost, constraining adoption in price-sensitive residential segments.
Strategic Opportunities
- Canadian Prairie Provinces:Underdeveloped specialty distributor networks in Alberta and Saskatchewan present white space for bundled corner bead and joint compound delivery models.
- Freeze-Thaw Formulation Innovation:Proprietary vinyl compounds that resist corner cracking across temperature cycles open specification pathways in northern US climate zones.
- OSHA Silica Compliance Services:Distributors bundling exposure assessment tools with low-dust product lines capture contractor loyalty through regulatory risk mitigation.
Industry Challenges
- Drywall Finisher Labor Shortage:Skilled mudding specialists are aging out faster than apprenticeship programs replenish, compressing installation quality consistency.
- ASTM C1047 Certification Timelines:Third-party testing for metal bead bend radius and coating adhesion extends new product introduction cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Canada Corner Beads and Caps Market |
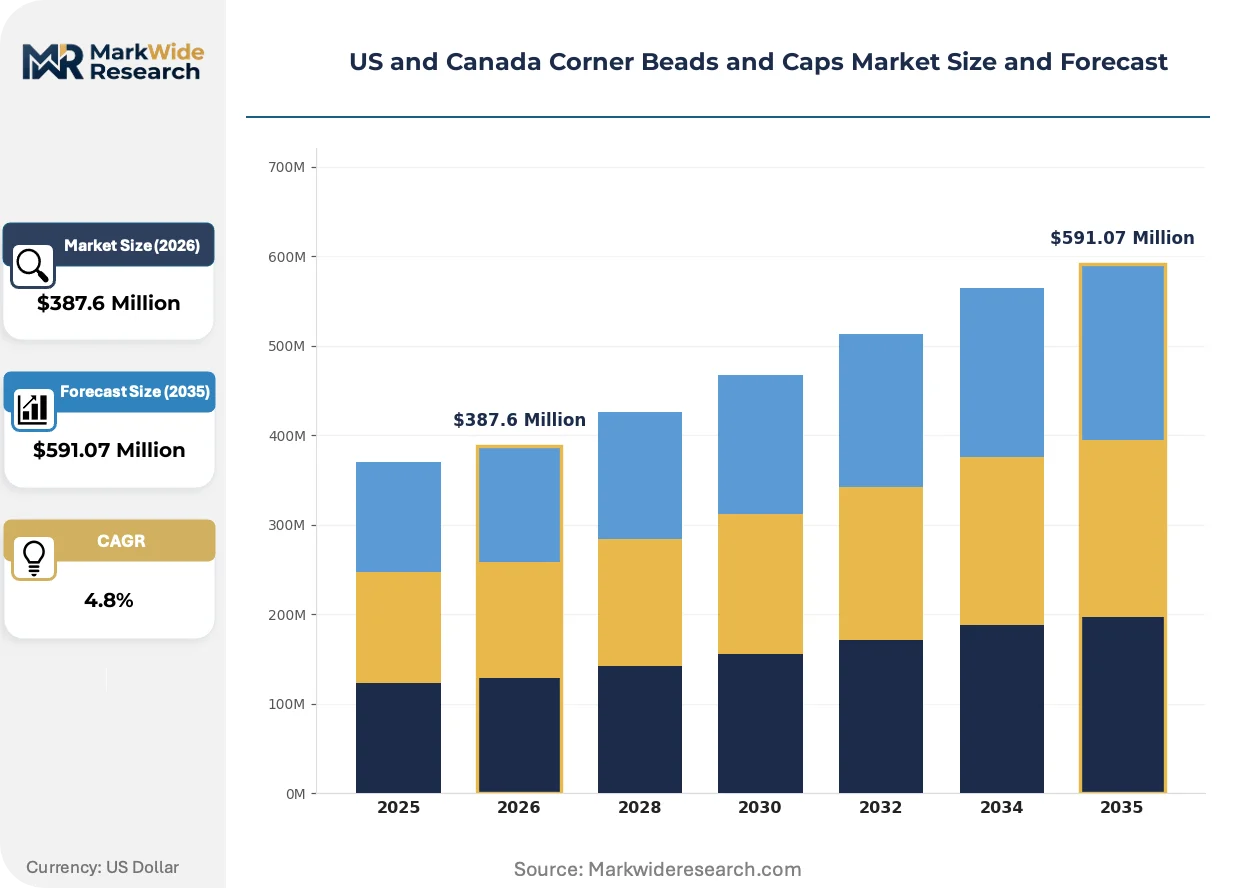
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Corner Beads, Metal Corner Beads, Paper Caps, Plastic Caps Application: Residential Construction, Commercial Renovation, Drywall Installation, DIY Projects Distribution Channel: Retail Stores, Online Marketplaces, Specialty Distributors, Direct Sales End User: Contractors, DIY Enthusiasts, Builders, Architects |
| Companies Covered | Super Stud Building Products, Niles Building Products, ClarkDietrich Building Systems, AMICO, Plastic Components, Inc., Trim-Tex Inc., Gibraltar Building Products, CEMCO Steel, Phillips Manufacturing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Canada Corner Beads and Caps Market Strategic Shifts
Material science advances and installation protocol changes are compressing traditional product lifecycles while elevating performance benchmarks for corner reinforcement accessories.
Composite corner beads integrating fiberglass mesh with vinyl substrates are hybridizing the durability characteristics of metal with the corrosion immunity of polymer extrusions. Multi-family residential developers in Florida and coastal California specify these hybrids to reduce callback rates from humidity-induced corner failures. The technology is hybridizing supplier R&D roadmaps, forcing parallel investment in both steel coating chemistry and polymer compound formulation.
OSHA's respirable crystalline silica standard for construction triggers specification shifts toward pre-finished and paper-faced alternatives that eliminate on-site sanding. Manufacturers now embed low-dust claims into product labeling to accelerate contractor adoption. Commercial renovation contractors in urban cores face the tightest compliance windows, driving fastest uptake of dust-reduction accessories.
Specialty distributors are consolidating procurement for mid-sized drywall contractors through job-site bundle deliveries that combine corner beads, joint compound, and mechanical fasteners. This channel compression displaces traditional two-step distribution through lumber yards. The pattern concentrates most visibly in Texas and Arizona metropolitan corridors where production homebuilders demand just-in-time material flow.
US and Canada Corner Beads and Caps Market Segmentation
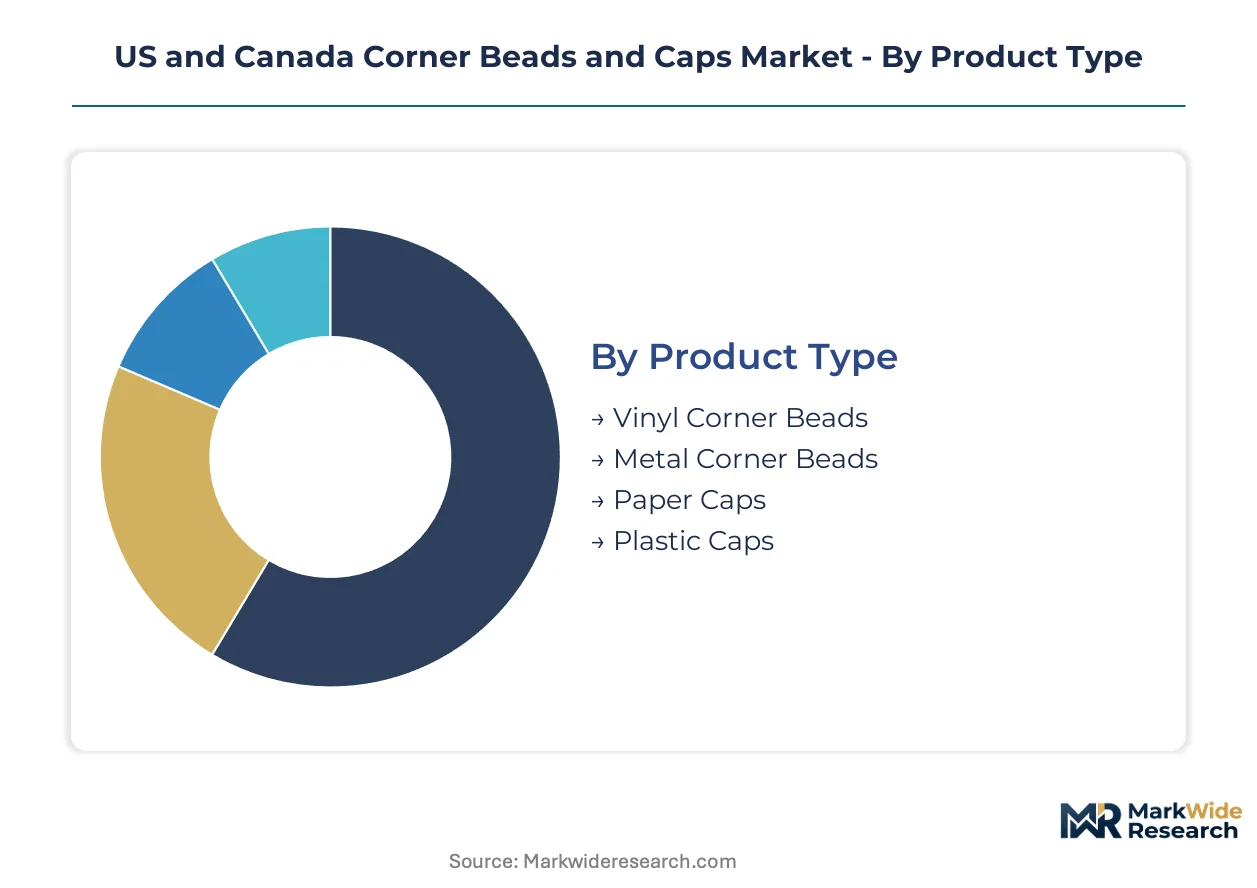
Segmentation in the US and Canada Corner Beads and Caps Market reveals how material specifications, installation protocols, and procurement behaviors diverge across construction verticals. Understanding these splits enables suppliers to align inventory positioning with regional building code evolution and contractor workflow preferences.
Product Type:
Vinyl corner beads, metal corner beads, paper caps, and plastic caps each occupy distinct positions across the use-case spectrum from high-impact commercial corridors to humidity-prone residential envelopes.
- Vinyl Corner Beads:Extruded polymer profiles with integrated reinforcement ribs deliver corrosion immunity without galvanic degradation. Demand clusters in Texas and Florida where Gulf Coast humidity accelerates metal bead failure rates in exterior-facing interior corners. EPA lead-safe renovation rules further amplify specification as vinyl eliminates on-site sanding dust.
- Metal Corner Beads:Galvanized steel profiles with zinc coating weights ranging from G40 to G60 provide impact resistance for high-traffic commercial corridors. ASTM C1047 bend radius specifications govern quality tiers, with certified products commanding loyalty from union drywall contractors in Chicago and Detroit metropolitan construction clusters.
- Paper Caps:Low-dust paper-faced metal alternatives reduce silica exposure during installation, finding uptake in occupied commercial renovations where OSHA compliance windows are tightest.
- Plastic Caps:Injection-molded polymer finishing accessories serve price-sensitive residential segments and DIY channel volumes through retail hardware chains.
Established volume favors metal corner beads; emerging adoption favors vinyl corner beads.
Application:
Application segments trace cost tier divergence, with premium performance specifications concentrating in commercial renovation while residential construction optimizes for material cost efficiency.
- Residential Construction:Production homebuilders in Arizona and Nevada metropolitan corridors specify vinyl and plastic cap combinations to minimize callback liability from corner cracking. Sun Belt housing velocity compresses lead-time tolerance, forcing distributors to hold safety stocks within 100 miles of job-site clusters.
- Commercial Renovation:Urban core retrofit projects in Toronto and Vancouver face stringent OSHA silica exposure limits, driving specification toward pre-finished caps and paper-faced alternatives that eliminate on-site sanding. Lease rollover schedules create concentrated demand spikes in Q2 and Q3 construction windows.
- Drywall Installation:Specialist contractors performing high-volume board hanging prioritize metal bead durability for commercial specifications and vinyl flexibility for residential tract work.
- DIY Projects:Retail channel volumes concentrate in suburban markets where homeowner renovation activity responds to interest rate sensitivity and housing turnover velocity.
Commercial renovation commands premium pricing tiers; residential construction delivers volume scale.
Distribution Channel:
Channel structures reflect customer type stratification, with procurement sophistication separating specialty distributor relationships from transactional retail purchases.
- Specialty Distributors:Bundled job-site delivery of corner beads with joint compound and fastener assortments captures mid-sized drywall contractor loyalty. This channel concentrates margin pools in Texas and Arizona where production builders demand just-in-time material flow.
- Retail Stores:Big-box hardware chains and independent lumber yards serve DIY enthusiasts and small residential contractors with immediate-need inventory access.
- Online Marketplaces:E-commerce penetration remains limited by freight economics for low-value, high-cube products, though specification research increasingly begins through digital channels.
- Direct Sales:National account relationships with production homebuilders bypass distributor markups for volume commitments exceeding regional thresholds.
Specialty distributors consolidate professional contractor procurement; retail channels fragment DIY and small-trade volumes.
End User:
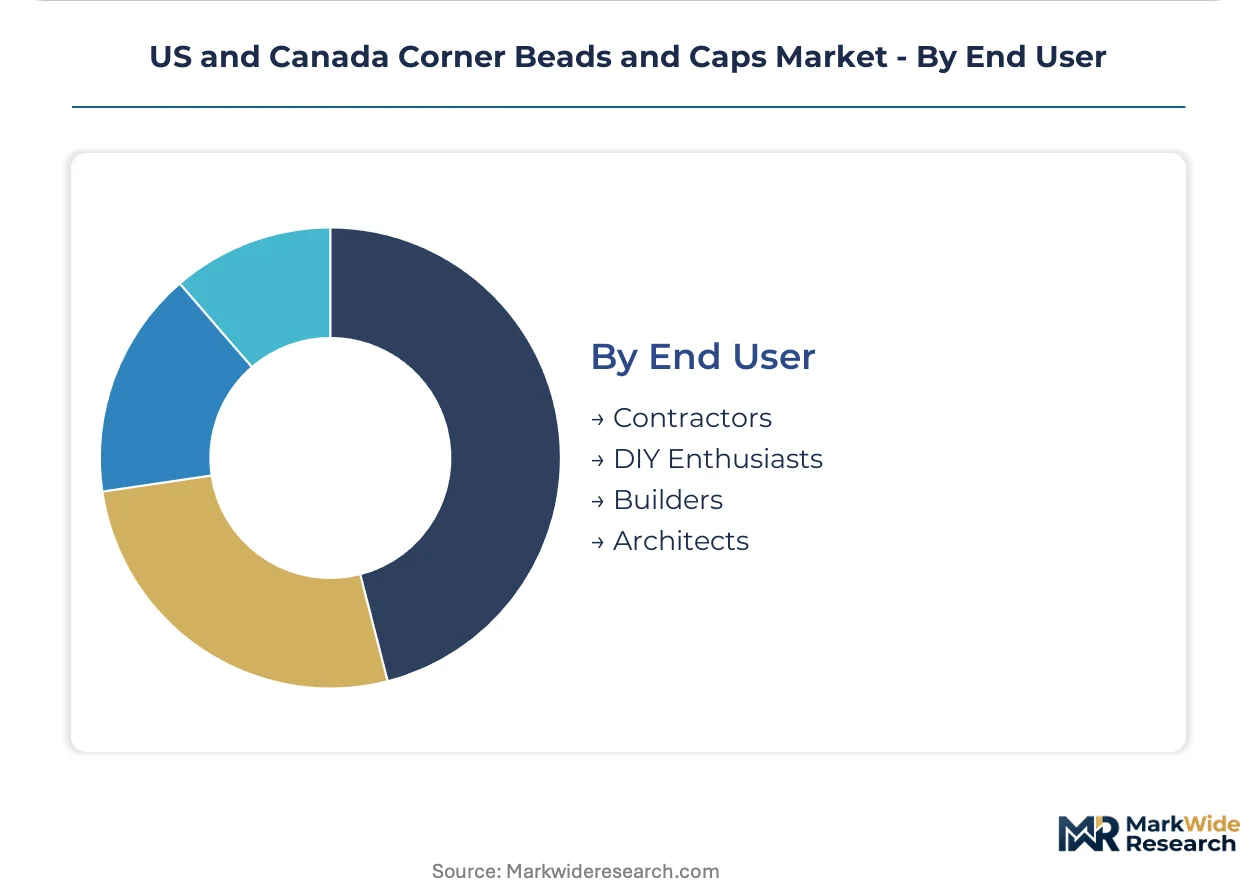
End-user segmentation maps to maturity gradients in specification authority, with architects and builders influencing upstream material selection while contractors and DIY enthusiasts execute downstream procurement.
- Contractors:Union and non-union drywall specialists drive material specification through installation quality reputation and ASTM C1047 certification preferences. Labor shortage pressures in the US Midwest compress installation consistency, elevating demand for forgiving vinyl formulations.
- Builders:Production and custom homebuilders in California integrate corner bead selection with Title 24 energy code air sealing requirements, expanding cap performance specifications for airtight construction assemblies.
- Architects:Commercial project specifications reference ASTM standards and LEED material credits, though actual procurement often delegates to contractor discretion.
- DIY Enthusiasts:Price-sensitive segment with minimal brand loyalty, responding to retail promotion cycles and online tutorial content.
Contractors and builders concentrate volume authority; architects and DIY enthusiasts occupy influence and fragmentation poles respectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA lead-safe renovation rules and OSHA silica exposure standards anchor demand patterns across the US, while Health Canada building code harmonization shapes specification north of the border. Regional construction velocity concentrates in Sun Belt metropolitan corridors and Canadian Prairie expansion zones.
Southwest United States
Texas housing starts in Dallas-Fort Worth and Houston generate concentrated demand for corrosion-resistant vinyl corner beads suited to Gulf Coast humidity. EPA renovation rules elevate pre-finished cap specifications in Houston's historic district retrofit activity. Specialty distributors cluster within 100 miles of San Antonio and Austin job-site corridors to compress lead times.
Southeast United States
Florida's production homebuilding in Tampa and Orlando prioritizes vinyl formulations resisting humidity-induced corner failures. OSHA silica compliance tightens fastest in Miami-Dade commercial renovation, pushing paper-faced alternatives. Jacksonville and Orlando distribution hubs hold expanded safety stocks of low-dust accessories.
West Coast United States
California Title 24 energy code integration of interior air sealing with drywall finishing expands high-performance cap specifications in Los Angeles and San Francisco Bay Area construction. Green building code evolution in Sacramento drives bundled procurement of corner beads with airtightness accessories. San Diego residential velocity concentrates vinyl bead demand.
Midwest United States
Great Lakes corridor manufacturing of galvanized steel corner beads serves Chicago and Detroit commercial renovation markets where ASTM C1047 certification governs union contractor loyalty. Winter logistics disruptions around integrated coil-to-finished-product facilities create seasonal supply vulnerability. Cleveland and Milwaukee distributors buffer inventory ahead of freeze-thaw construction windows.
Canada
Prairie Provinces housing expansion in Calgary and Edmonton presents underdeveloped specialty distributor networks for bundled corner bead and joint compound delivery. Health Canada building code harmonization with US ASTM standards simplifies cross-border product certification. Vancouver and Toronto commercial renovation faces parallel OSHA-equivalent silica exposure protocols.
US and Canada Corner Beads and Caps Market Competitive Environment
Integrated steel processors and specialized vinyl extruders split the market between volume-scale metal fabrication and polymer formulation expertise. The vendor base concentrates geographically around Great Lakes steel coil access and Gulf Coast resin supply corridors. Two strategic archetypes dominate: coil-integrated manufacturers controlling input cost volatility, and compound specialists commanding premium positioning through proprietary formulations. Competitive moves center on distributor consolidation partnerships and freeze-thaw formulation patent filings.
Among coil-integrated manufacturers, ClarkDietrich Building Systems and CEMCO Steel exemplify the backward-integrated archetype with captive supply chain control. Trim-Tex Inc. occupies the specialty compound tier, representing formulation-driven differentiation. Super Stud Building Products anchors the light-gauge steel framing accessories segment. These three companies illustrate how strategic positioning separates cost-control players from premium specification capturers.
| Leading Market Players |
|---|
| Super Stud Building Products |
| Niles Building Products |
| ClarkDietrich Building Systems |
| AMICO |
| Plastic Components, Inc. |
| Trim-Tex Inc. |
| Gibraltar Building Products |
| CEMCO Steel |
| Phillips Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Great Lakes corridor concentration of integrated steel coil processors anchors margin capture downstream, with captive galvanizing lines in Ohio and Indiana feeding finished corner bead extrusion directly to specialty distributors. Vinyl compound formulators along the Gulf Coast resin corridor compete on formulation patents rather than feedstock scale, fragmenting pricing power across material categories.
Pricing Analysis
Geographic price spreads between Texas Sun Belt job sites and Midwest manufacturing clusters reflect freight absorption patterns rather than product differentiation. Three-tier pricing structure across premium ASTM-certified metal, standard vinyl extrusions, and economy plastic caps governs contractor procurement. Cost compression in galvanized steel tiers intensifies because zinc coating volatility passes through to spot purchasing. Production homebuilders in Arizona and Nevada represent the most price-sensitive buyer archetype, while union commercial contractors in Chicago prioritize certification tier over unit cost.
Supply Chain Analysis
Upstream galvanized steel coil draws from integrated mills in the United States and specialty coating facilities in Canada, while vinyl resin feeds from petrochemical complexes along the Texas and Louisiana Gulf Coast. Zinc ingot and PVC compound dependencies expose manufacturers to commodity price swings and force majeure allocations from resin suppliers. Single-source vulnerability concentrates in narrow coil-to-finished-product corridors around the Great Lakes, where winter logistics disruptions cascade to distributor safety stock depletion. Distribution runs through specialty building material distributors who bundle corner beads with joint compound for just-in-time job-site delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA lead-safe renovation enforcement and OSHA silica exposure standards are reshaping material specifications faster than legacy supply chains adapt, creating asymmetric growth windows for compliant product lines. The intersection of regulatory tightening and Sun Belt construction velocity compresses traditional product lifecycles.
For Market Incumbents: Build formulation patent moats around freeze-thaw resistant vinyl compounds to defend against commodity substitution. Backward integration into captive steel coil galvanizing secures margin control against zinc price volatility. Channel consolidation partnerships with specialty distributors in Texas and Arizona lock out regional challengers through exclusive bundle arrangements. For New Entrants and Emerging Players: Canadian Prairie Provinces specialty distributor networks represent the most penetrable entry point, with underdeveloped bundled delivery models in Calgary and Edmonton construction corridors. Pre-finished cap assemblies for occupied commercial renovation bypass established metal bead relationships through OSHA compliance differentiation. Direct sales to mid-sized production homebuilders in Florida bypass incumbent distributor markups for volume commitments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across vinyl extrusion sub-segments as modular compound formulation reduces fixed asset requirements. Acquisition targets should display proprietary polymer R&D pipelines and established specification relationships with Title 24-compliant California builders. The signal to watch is Health Canada building code harmonization progress, which would unlock cross-border manufacturing scale for ASTM-certified producers.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Thaw Formulation Patent Filing | Proprietary vinyl compounds capture northern climate zone specifications from commodity metal alternatives. |
| Specialty Distributor Consolidation Partnership | Exclusive bundle arrangements with Texas and Arizona distributors compress competitor access to production builder accounts. |
| Backward Integration into Galvanizing | Captive coil coating lines in Great Lakes corridor insulate margin from zinc price volatility and supply disruption. |
| Pre-Finished Cap Assembly Launch | OSHA-compliant low-dust products penetrate occupied commercial renovation where sanding restrictions are tightest. |
| Canadian Prairie Distribution Network Buildout | First-mover bundled delivery models in Alberta and Saskatchewan capture housing expansion white space. |
Study Parameters
A standing panel of drywall contractor operations managers, specialty distributor procurement directors, vinyl compound R&D leads, and union apprenticeship coordinators provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement databases, ASTM certification registries, and state-level housing start permits. Trade association filings from the National Association of Home Builders, customs records for galvanized steel coil imports, and SEC disclosures from publicly traded building material distributors anchored quantitative triangulation. Bottom-up volume estimates from distributor inventory turns and top-down construction spend allocation models converged on segment sizing.
Scenario-bracketing around EPA enforcement intensity and Sun Belt housing velocity variations bounded the projection range across the analysis window. Segmentation modeling captured material type, application vertical, distribution channel, and end-user specification authority dimensions. CAGRs derived from historical construction spend elasticities and regulatory adoption curve analysis, with housing start permit forecasts and energy code evolution timelines as key inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate sensitivity for residential construction or zinc commodity price spikes would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and labor availability in drywall finishing trades. Cross-checking against Census Bureau construction spending reports and American Iron and Steel Institute coil shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Corrugated Steel Panels Market