
 North America Agricultural Sprayers Market | 2026-2036
North America Agricultural Sprayers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Sprayers Market Analytics
The dealer network across the U.S. Midwest and Canadian Prairie provinces is fragmenting as manufacturers build direct-to-farm digital platforms and regional service hubs. Deere & Company leverages its precision agriculture software stack to control aftermarket service revenue. AGCO Corporation anchors its position through Fendt and Challenger brand specialization in high-horsepower self-propelled units. Kubota Corporation competes aggressively in mid-range orchard and vineyard equipment where Japanese manufacturing scale meets North American customization demands.
Agricultural sprayers are self-propelled, trailed, or mounted machines engineered to distribute crop protection chemicals, liquid fertilizers, or biological agents across field surfaces with calibrated flow rates typically ranging from ten to 120 gallons per acre and boom widths spanning forty to 150 feet. Their primary commercial purpose centers on maximizing input efficacy while minimizing off-target movement through controlled droplet sizing and GPS-guided section control. Self-propelled sprayers command the dominant share of equipment value given their integration with variable-rate technology and real-time application mapping. Orchard sprayers represent the fastest-growing product configuration as tree nut and vineyard acreage expands across California, Washington, and British Columbia. Crop protection applications generate the largest revenue pool within the application dimension, though fertilization services are gaining share through custom applicator fleets serving cooperative members.
The EPA enforces drift-reduction technology mandates under the Federal Insecticide, Fungicide, and Rodenticide Act, compelling manufacturers to certify nozzles and air-assist systems for reduced droplet spectrum classifications. NHTSA and Transport Canada coordinate on autonomous vehicle guidance that governs operator-optional sprayer deployment on public roadways between fields. OSHA and provincial counterparts in Ontario and Alberta enforce applicator exposure standards that drive cab filtration and closed-transfer system adoption. Stakeholders must monitor how EPA pesticide re-registration timelines and emerging state-level neonicotinoid restrictions in New York and California reshape chemical portfolios and corresponding equipment specifications.
Market Dynamics
Precision application technology is collapsing the traditional trade-off between coverage speed and chemical stewardship across North American row-crop operations. Variable-rate nozzles combined with real-time wind sensors now enable applicators to maintain field speeds above fifteen miles per hour while satisfying EPA drift-reduction mandates.
Growth Catalysts
- EPA Drift-Reduction Mandates:FIFRA certification requirements for reduced droplet spectrum classifications are compelling fleet upgrades across the U.S. Corn Belt. Commercial applicators face permit renewal deadlines tied to equipment compliance.
- Specialty Crop Expansion:Almond and pistachio acreage growth across California's Central Valley is driving demand for air-assist orchard sprayers with targeted canopy penetration capabilities.
- Autonomous Guidance Systems:NHTSA operator-optional vehicle guidance is enabling overnight repositioning between fields, compressing seasonal labor constraints for large-scale Prairie province operations.
Market Restraints
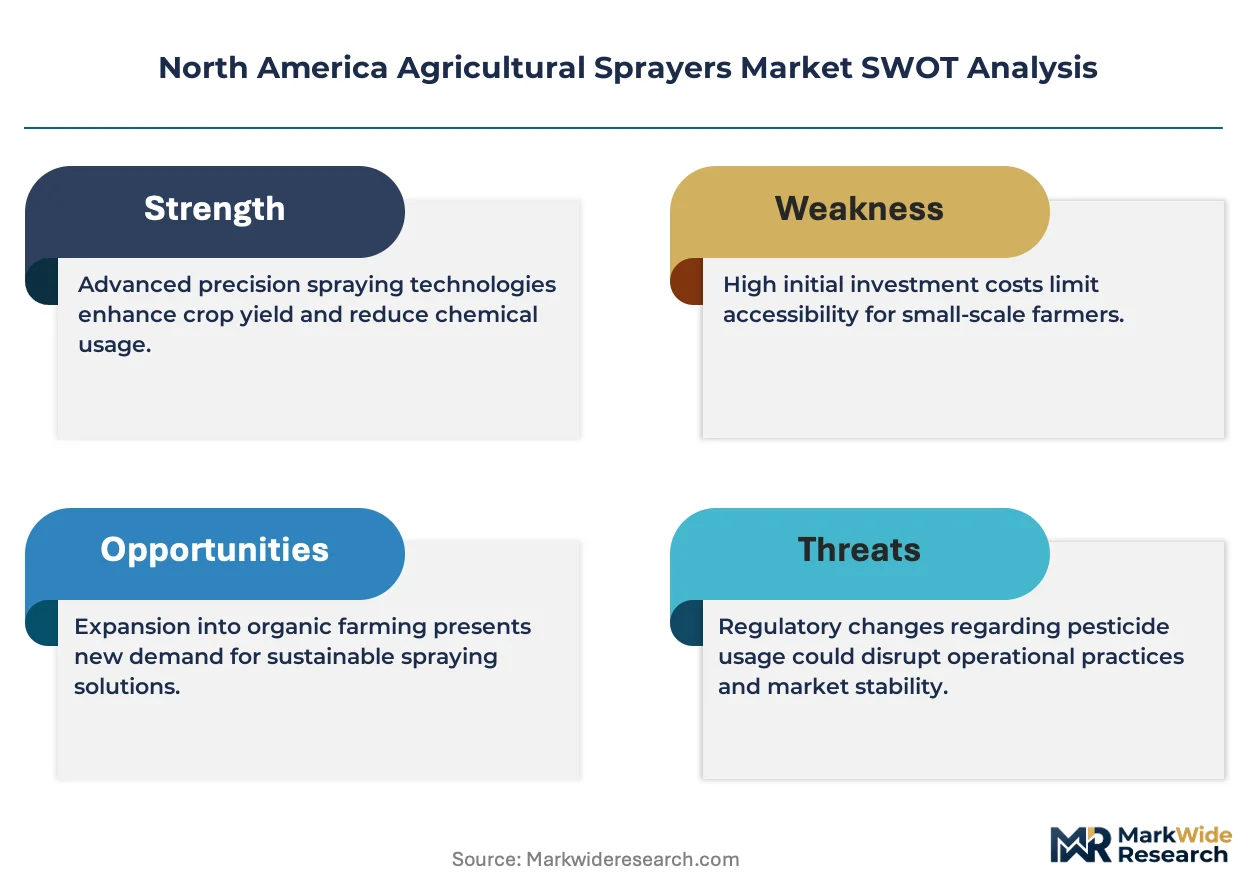
- Stainless Steel Input Volatility:Boom and tank fabrication costs fluctuate with nickel pricing, squeezing margin predictability for mid-range equipment manufacturers serving price-sensitive cooperatives.
- Hydraulic Component Concentration:Precision pump and valve sourcing depends on concentrated German and Italian supplier bases, exposing North American assemblers to transatlantic shipping disruptions.
- Neonicotinoid Portfolio Compression:New York and California state-level restrictions on seed treatments are reducing chemical volume throughput, dampening sprayer utilization rates for corn and soybean applicators.
Strategic Opportunities
- Canadian Prairie Custom Application:Saskatchewan and Manitoba grain cooperatives remain underpenetrated by owned fleets, creating white space for service-based equipment deployment models.
- Biological Agent Compatibility:Fermentation-derived crop protection formulations require specialized tank agitation and filtration systems, opening premium retrofit and new-build segments.
- Closed-Transfer System Mandates:OSHA exposure reduction frameworks are accelerating demand for sealed chemical loading infrastructure, particularly among Washington State tree fruit operations.
Industry Challenges
- Telematics Integration Complexity:Legacy sprayer fleets lack standardized CAN bus architectures, forcing expensive gateway hardware deployment to connect with modern farm management information systems.
- Certified Applicator Pipeline:Commercial operator licensing requirements in Ontario and Alberta face completion backlogs, constraining fleet utilization during compressed application windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Sprayers Market |
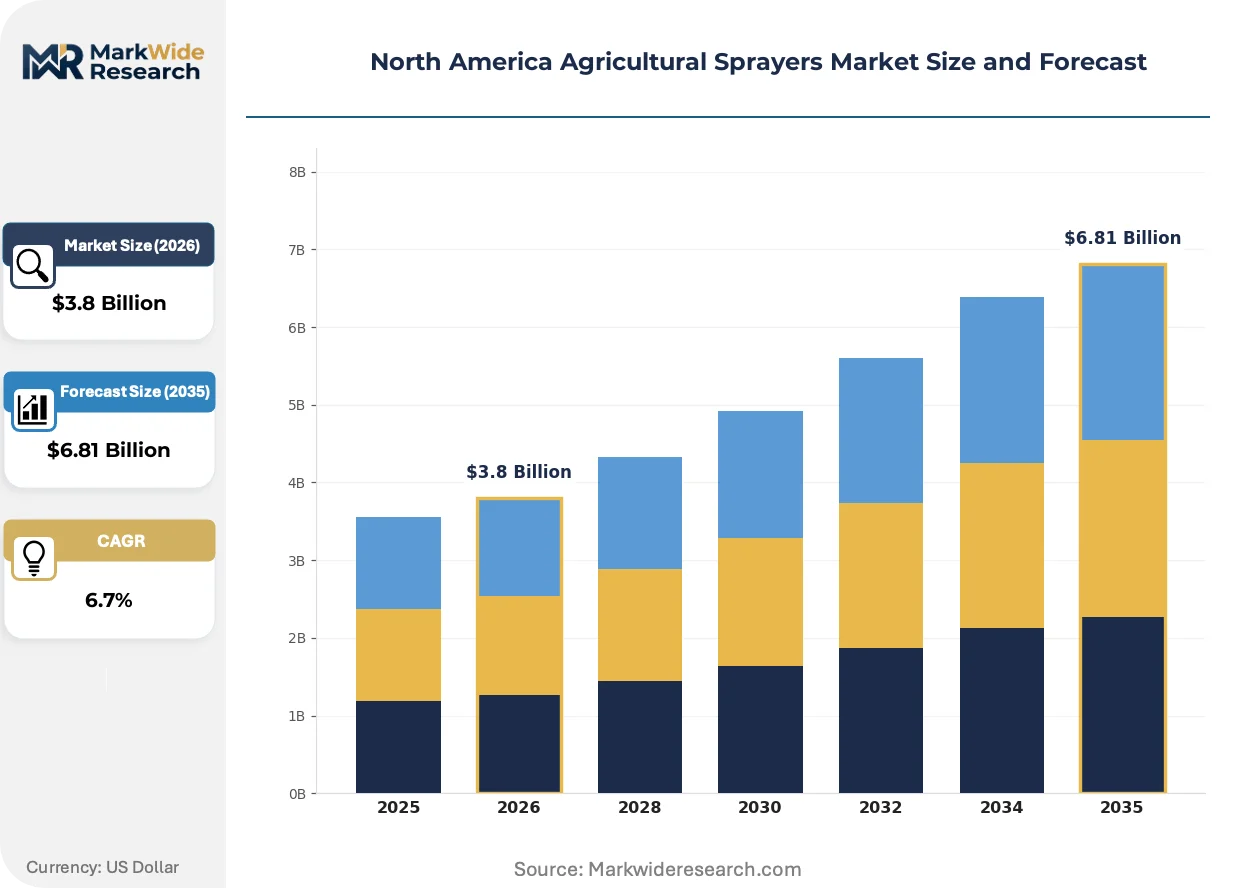
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Row Crop Sprayers, Orchard Sprayers, Aerial Sprayers, Self-Propelled Sprayers Application: Crop Protection, Fertilization, Pest Control, Seed Treatment End User: Farmers, Agricultural Cooperatives, Commercial Growers, Government Agencies Distribution Channel: Direct Sales, Distributors, Online Retail, Dealers |
| Companies Covered | GVM Incorporated, Jacto Inc, Deere & Company, EXEL Industries, Kubota Corporation, AGCO Corporation, GUSS AG, Amazone GmbH & Co. KG, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Sprayers Market Evolving Landscape
Electrification of hydraulic functions and sensor fusion architectures are redefining equipment architecture across self-propelled and trailed configurations. These shifts compress maintenance intervals while expanding real-time decision capabilities.
Individual nozzle control using pulse-width modulation is collapsing the historical compromise between boom width and buffer zone compliance. Large-scale operators across Iowa and Illinois are retrofitting existing booms with solenoid-actuated valves at replacement cycles accelerated by EPA certification timelines. The technology is collapsing field pass counts by enabling variable-rate application across irregular field boundaries without manual nozzle shutoff.
EPA pesticide re-registration timelines under FIFRA are compressing active ingredient availability, forcing equipment manufacturers to validate compatibility with reformulated chemistries on accelerated schedules. Tank material specifications and seal compounds face iterative testing cycles. Specialty crop segments in California's Central Valley bear the highest compliance burden as their chemical portfolios face disproportionate regulatory scrutiny.
Service-based ownership models are displacing outright equipment purchase among mid-scale Corn Belt operations. Regional custom applicators in Nebraska and Kansas are expanding fleet capacity to capture cooperative members seeking to eliminate capital deployment and storage liability. The shift concentrates equipment utilization with professional operators while reducing manufacturer exposure to cyclical replacement demand.
North America Agricultural Sprayers Market Segmentation
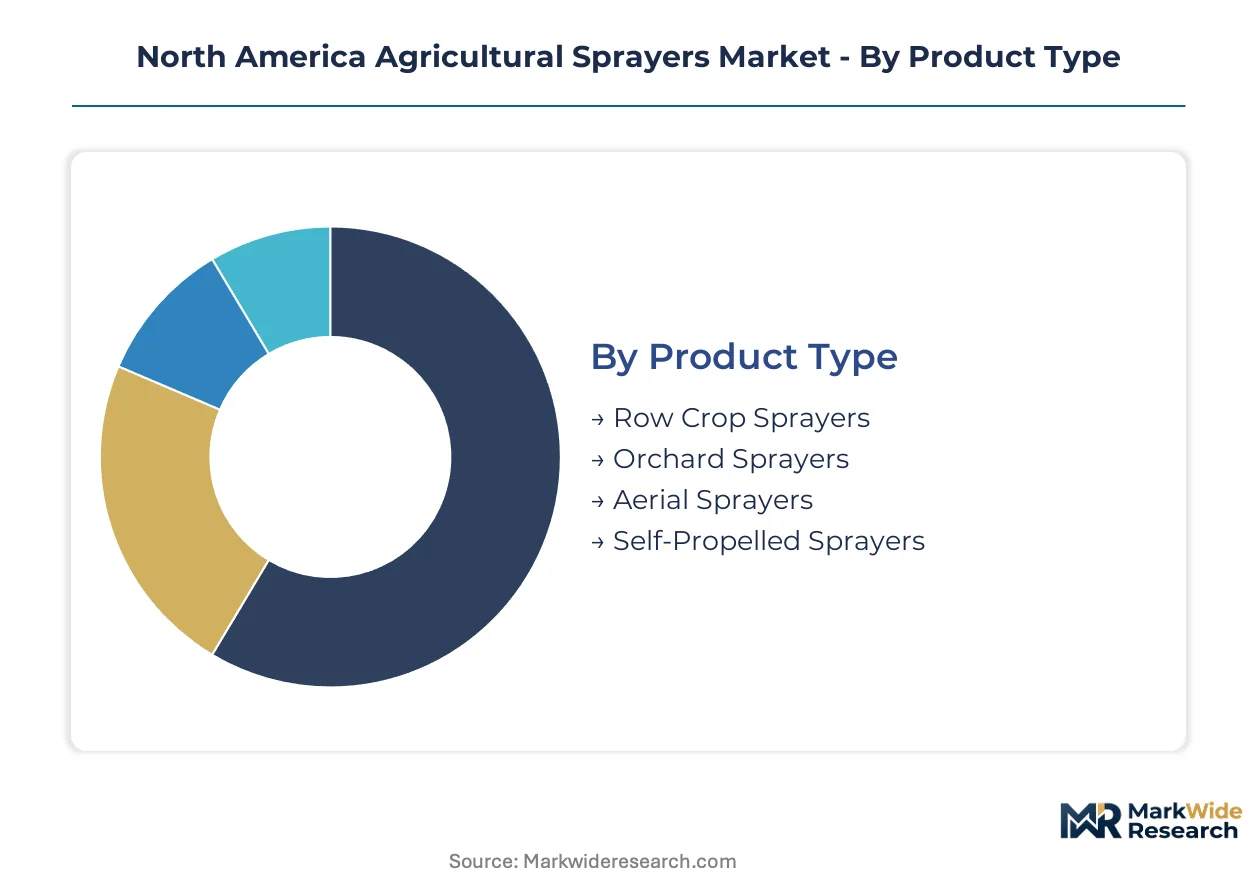
Agricultural sprayer segmentation in North America reflects divergent equipment architectures demanded by row-crop efficiency targets versus specialty crop precision requirements. Equipment specifications vary sharply across application chemistry, farm scale, and procurement channel access.
Product Type:
Use-case spectrum spans high-acreage field operations through precision canopy penetration and aerial coverage.
- Row Crop Sprayers:Trailed and mounted configurations dominate corn and soybean belt operations with boom widths exceeding 90 feet. Demand concentrates among Iowa and Illinois commercial applicators seeking EPA drift-reduction compliance through pulse-width modulation retrofits.
- Orchard Sprayers:Air-assist tower designs deliver targeted droplet penetration into dense almond and pistachio canopies. California Central Valley growers drive specification evolution as tree nut acreage expands across Fresno and Kern counties.
- Aerial Sprayers:Fixed-wing and rotary aircraft serve flood-prone regions where ground equipment access fails. Louisiana rice operations and Red River Valley sugar beet growers maintain seasonal contracts with aerial applicator fleets.
- Self-Propelled Sprayers:High-horsepower units integrate variable-rate technology and real-time mapping for large-scale Prairie province grain operations. Saskatchewan and Manitoba cooperatives favor 120-foot boom configurations with autonomous guidance compatibility.
Established volume favors Row Crop Sprayers; emerging adoption favors Orchard Sprayers.
Application:
Input chemistry type dictates tank material specifications, agitation systems, and nozzle selection across equipment deployments.
- Crop Protection:Herbicide, fungicide, and insecticide applications generate the largest equipment utilization hours. Corn Belt custom applicators face compressed seasonal windows driving fleet capacity expansion.
- Fertilization:Liquid nitrogen and micronutrient delivery demands corrosion-resistant tank linings and precision flow control. Red River Valley potato operations and Florida vegetable growers deploy dedicated fertilization rigs.
- Pest Control:Vector management and invasive species suppression requires ultra-low volume systems with specialized droplet spectra. Texas cotton boll weevil eradication programs and Florida citrus canker response shape regional specifications.
- Seed Treatment:On-farm and centralized treating operations demand enclosed chemical handling systems. Nebraska and Kansas wheat cooperatives invest in closed-transfer infrastructure to satisfy OSHA exposure standards.
Crop Protection commands dominant utilization; Fertilization gains share through cooperative service expansion.
End User:
Capital deployment capacity and chemical handling liability exposure separate ownership models across the value chain.
- Farmers:Owner-operators across the U.S. Corn Belt favor mid-range trailed units with three-point hitch compatibility. Equipment selection prioritizes multi-season versatility across crop rotations.
- Agricultural Cooperatives:Member-owned entities in Minnesota and the Dakotas deploy owned fleets to capture input application margins. Capital pools enable high-horsepower self-propelled acquisition.
- Commercial Growers:Specialty crop operations in Washington's Yakima Valley and British Columbia's Okanagan region specify orchard configurations with GPS-guided section control. Scale permits dedicated equipment for single-crop optimization.
- Government Agencies:Federal and state departments conduct noxious weed control and habitat restoration with amphibious and all-terrain configurations. Bureau of Land Management and provincial agriculture departments maintain specialized rolling stock.
Commercial Growers drive precision technology adoption; Agricultural Cooperatives concentrate fleet ownership.
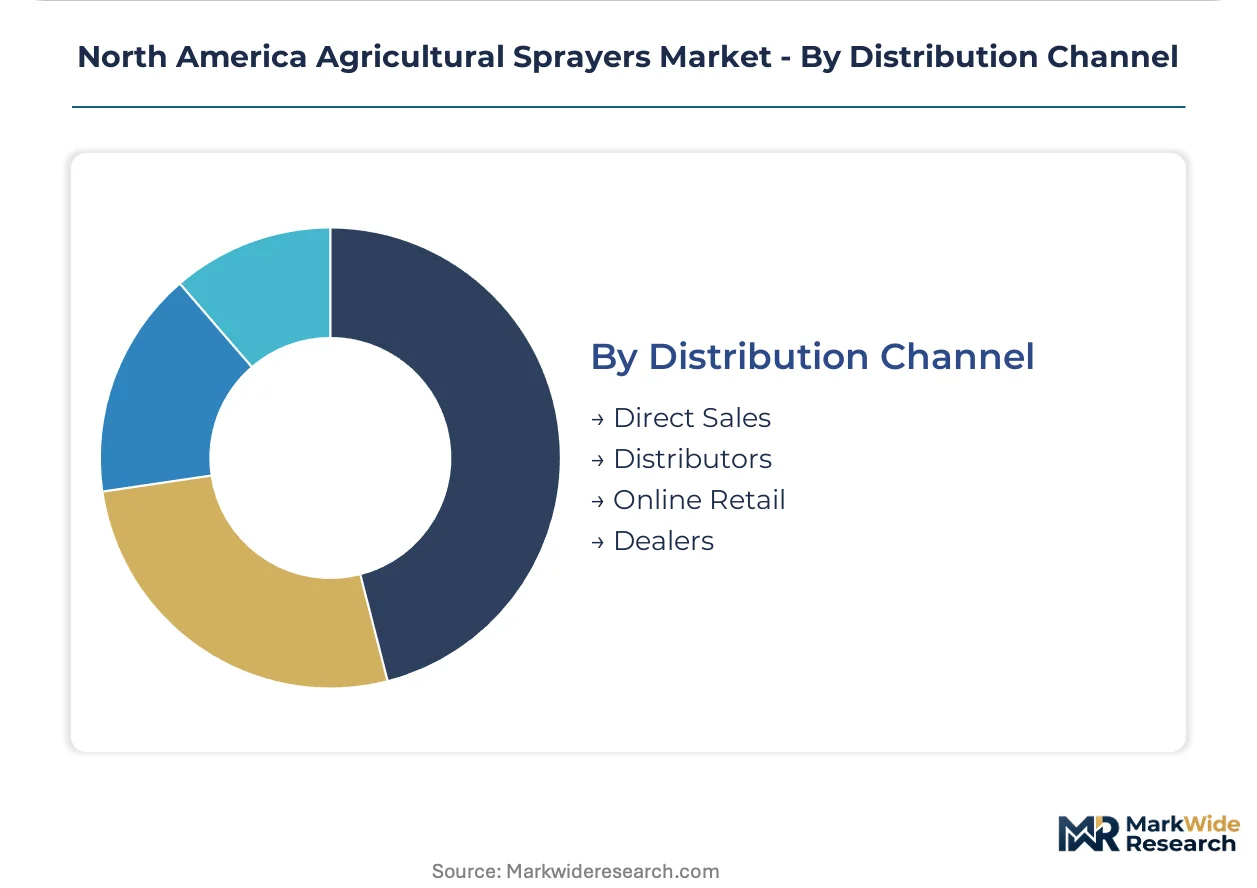
Distribution Channel:
Service proximity and financing access determine procurement pathway selection across farm scales.
- Direct Sales:Manufacturers engage large-scale Prairie province operators and cooperative systems through factory representatives. Volume commitments unlock customized specification and priority delivery scheduling.
- Distributors:Regional agricultural supply houses maintain inventory for immediate availability across secondary markets. Nebraska and Kansas independents compete on parts availability and field technician response times.
- Online Retail:E-commerce platforms capture component, nozzle, and retrofit accessory demand. Small-scale operators research specifications digitally before dealer negotiation.
- Dealers:Branded dealership networks deliver integrated precision agriculture packages with software subscription bundling. Deere and AGCO dealer footprints dominate Midwest service territories.
Dealers retain equipment transaction dominance; Direct Sales penetrates largest cooperative accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River inland waterway system and Canadian National Railway corridors enable efficient equipment distribution from Great Lakes manufacturing centers to Prairie province terminals and Gulf Coast export facilities.
United States
Corn Belt commercial applicators in Iowa and Illinois drive demand for high-capacity self-propelled units with pulse-width modulation retrofits. EPA FIFRA drift-reduction mandates compel fleet upgrades ahead of permit renewal deadlines. California's Central Valley specialty crop belt concentrates orchard sprayer procurement around Fresno and Kern counties as almond acreage expands.
Canada
Saskatchewan and Manitoba grain cooperatives favor 120-foot boom configurations with autonomous guidance compatibility for large-scale Prairie operations. Transport Canada coordinates with NHTSA on operator-optional vehicle standards for overnight field repositioning. Ontario's manufacturing corridor around Guelph and Brantford anchors precision agriculture component fabrication.
Mexico
Sinaloa and Sonora vegetable export zones generate demand for mid-range trailed sprayers serving protected agriculture operations. SADER (Secretaría de Agricultura y Desarrollo Rural) programs promote mechanization adoption among smallholder associations. Guanajuato's Bajío region concentrates precision equipment distribution through Querétaro logistics hubs.
North America Agricultural Sprayers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying pumps, valves, and nozzle assemblies to multiple assemblers. The vendor base stratifies across three tiers: diversified agricultural equipment conglomerates with precision software stacks; mid-scale specialists focused on orchard and vineyard configurations; and regional fabricators serving price-sensitive cooperative markets. Dominant competitive moves include direct-to-farm digital platform deployment and regional service hub establishment bypassing traditional dealer networks.
Among diversified equipment manufacturers, Deere & Company and AGCO Corporation exemplify platform integrators leveraging precision agriculture software to capture aftermarket service revenue. Kubota Corporation anchors the mid-range specialist tier where manufacturing scale meets North American customization requirements. These three entities collectively represent the competitive archetypes reshaping distribution economics across the Corn Belt and Prairie provinces.
| Leading Market Players |
|---|
| GVM Incorporated |
| Jacto Inc |
| Deere & Company |
| EXEL Industries |
| Kubota Corporation |
| AGCO Corporation |
| GUSS AG |
| Amazone GmbH & Co. KG |
| CNH Industrial |
| Others |
Value Network & Pricing Analysis
Stainless steel nickel price volatility determines both equipment tier spreads and supply chain configuration across North American sprayer manufacturing. Boom and tank fabricators pass commodity cost swings through to buyers, compressing margin predictability for mid-range assemblers serving price-sensitive cooperative markets while premium-tier manufacturers absorb volatility through captive sourcing arrangements.
Pricing Analysis
Volume-discount tiering structures separate large-scale Prairie province cooperatives from individual Corn Belt owner-operators. Three-tier pricing stratifies across premium self-propelled configurations with precision agriculture bundling, standard trailed units for diversified crop rotations, and economy-mounted sprayers for smallholder associations. Cost compression in mid-range equipment is intensifying because stainless steel input volatility squeezes fabricator margins. Cooperative buyers exhibit highest price sensitivity due to capital pooling constraints, while commercial specialty crop growers in California's Central Valley demonstrate lowest sensitivity given single-crop optimization requirements.
Supply Chain Analysis
Tariff exposure between Germany and North America dominates precision pump and valve sourcing risks for domestic assemblers. Hydraulic component fabrication concentrates in Germany and Italy, with North American equipment builders drawing from concentrated transatlantic supplier bases for pulse-width modulation systems and air-assist tower assemblies. Raw material dependencies span nickel for stainless steel tanks, specialized polymers for corrosion-resistant linings, and precision-machined aluminum for boom structures. Single-source vulnerability in German hydraulic component supply creates chokepoint exposure during shipping disruptions. Distribution runs through manufacturer-direct channels for largest cooperative accounts and branded dealership networks for immediate availability across secondary Midwest markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified applicator pipeline constraints represent the critical capability gap constraining fleet utilization during compressed seasonal windows. Equipment deployment velocity hinges on resolving licensing completion backlogs in Ontario and Alberta.
For Market Incumbents: Entrench precision agriculture software control through aftermarket service revenue capture. Deere and AGCO should deepen backward integration into CAN bus gateway hardware to connect legacy fleet telematics with modern farm management systems. Defend against service-based ownership displacement by embedding subscription bundling into direct-to-farm digital platforms. For New Entrants and Emerging Players: Build out biological agent compatibility specialization as fermentation-derived crop protection creates premium retrofit demand. Saskatchewan and Manitoba grain cooperatives remain underpenetrated by owned fleets, presenting white space for equipment-as-a-service deployment models. Target closed-transfer system mandates in Washington State tree fruit operations through sealed chemical loading infrastructure partnerships. For Investors and Strategic Acquirers: The market sits at a regulatory-compliance-driven replacement cycle phase that favors precision technology integrators over commodity fabricators. Long-term viability across the projection horizon rests on software-defined equipment architectures and autonomous guidance compatibility. Acquisition targets should demonstrate EPA drift-reduction certification pipelines and pulse-width modulation retrofit capabilities. Monitor NHTSA autonomous vehicle guidance evolution as the signal for overnight repositioning technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pulse-Width Modulation Retrofit Program | EPA FIFRA certification deadlines accelerate boom upgrade cycles across Iowa and Illinois commercial applicator fleets. |
| Closed-Transfer System Deployment | OSHA exposure reduction frameworks drive sealed chemical loading infrastructure adoption in Washington State tree fruit operations. |
| Autonomous Guidance Integration | NHTSA operator-optional standards enable overnight field repositioning for Saskatchewan and Manitoba grain cooperatives. |
| Biological Agent Tank Compatibility | Fermentation-derived crop protection formulations require specialized agitation and filtration system validation. |
| Direct-to-Farm Digital Platform | Manufacturer bypass of traditional dealer networks captures aftermarket service revenue from precision agriculture software stacks. |
Research Methodology
Desk research of EPA FIFRA certification databases, NHTSA autonomous vehicle guidance documents, and agricultural equipment trade customs records preceded structured interviews with commercial applicator fleet managers, precision agriculture software engineers, cooperative procurement officers, and stainless steel component fabricators. Primary fieldwork with Saskatchewan grain cooperative executives and California Central Valley orchard operators validated secondary findings on specialty crop equipment specifications. Bottom-up equipment shipment tallies triangulated against top-down agricultural chemical application acreage estimates.
Assumptions held fixed across the modeling period include EPA drift-reduction mandate enforcement timelines and NHTSA operator-optional vehicle guidance stability. Variables tested encompass stainless steel nickel price trajectory, neonicotinoid restriction expansion across additional state jurisdictions, and autonomous guidance technology adoption curves. Segmentation dimensions modeled span product type configuration, application chemistry compatibility, end-user ownership model, and distribution channel access. CAGRs derived from equipment value deployment rates correlated with chemical input volume projections across the Corn Belt and Prairie provinces.
Practitioners should monitor EPA pesticide re-registration timelines and emerging state-level neonicotinoid restrictions for early signals of chemical portfolio compression. Forecasts reflect assumptions regarding stainless steel input price stability and transatlantic shipping continuity for hydraulic components. Material shifts in EPA FIFRA certification requirements or Transport Canada autonomous vehicle standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Hay Making Machinery Market