
 Agricultural Electric Tractor Market | 2026-2036
Agricultural Electric Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Electric Tractor Market Insights
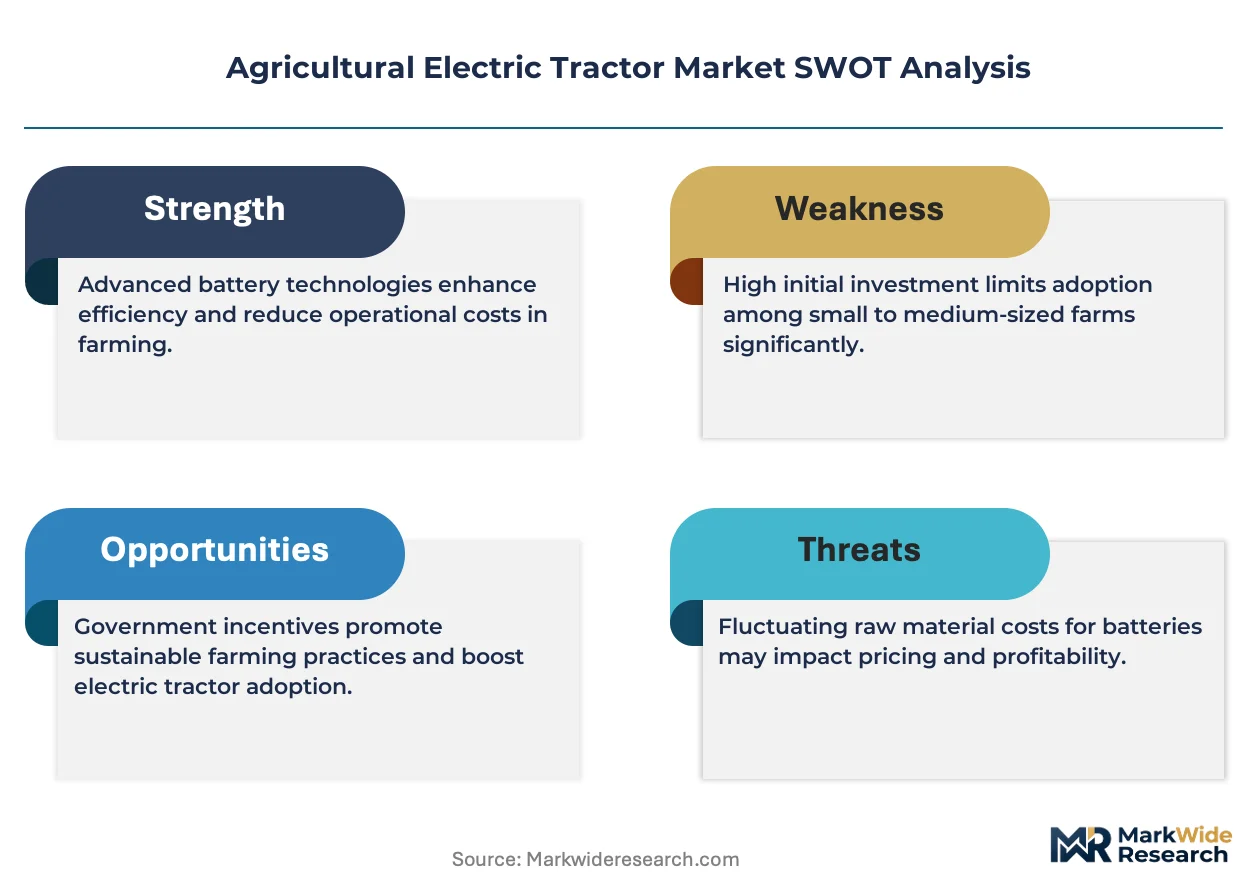
China's Jiangsu and Shandong provinces are narrowing the manufacturing cost gap with European producers through scaled lithium-ion pack assembly and localized permanent magnet motor production. John Deere leverages its precision agriculture software stack to anchor premium electric tractor positioning in North American row-crop segments. Monarch Tractor competes through autonomous operating modes that reduce labor dependency during planting and harvest windows. AGCO Corporation specializes in Fendt-branded battery electric variants for European mixed-farming estates requiring sub-75 HP vineyard maneuverability.
An agricultural electric tractor is a self-propelled farming vehicle powered by rechargeable electrochemical energy storage, typically lithium-ion battery packs rated between 20 kWh and 300 kWh, delivering torque to electric traction motors for tillage, planting, and material handling operations without direct tailpipe emissions. Compact tractors and utility tractors occupy the dominant volume positions, with orchard tractors commanding margin premiums due to narrow-profile chassis requirements and low-clearance cab designs that ICE alternatives struggle to match. Battery electric technology leads commercial deployments while fuel cell electric variants attract interest among large-scale crop farming operators seeking sub-15-minute refueling cycles during intensive seasonal fieldwork.
The EPA's evolving off-road emissions standards and California Air Resources Board's tractor certification requirements are accelerating diesel displacement timelines in US agricultural equipment procurement cycles. EU Green Deal farm sustainability benchmarks and REACH battery material traceability mandates are reshaping supplier qualification criteria across European OEM supply chains. Stakeholders must monitor solid-state battery commercialization timelines and charging infrastructure interoperability standards to assess capital deployment timing for fleet electrification programs.
Market Dynamics
Battery energy density improvements are compressing total cost of ownership differentials between electric and diesel tractor platforms, forcing incumbent OEMs to accelerate platform electrification roadmaps or cede vineyard and orchard segments to specialized entrants.
Growth Catalysts
- California Air Resources Board tractor certification requirements:Farm operators in the Central Valley face accelerating compliance deadlines that eliminate new diesel equipment procurement options. Specialty crop growers are expanding electric fleet commitments to meet farm-level emissions targets ahead of enforcement phases.
- Solid-state cell development:Next-generation electrochemical storage architectures are extending daily operating ranges beyond traditional diesel-equivalent duty cycles. Large-scale crop farming operators can now complete intensive seasonal fieldwork without mid-day charging interruptions.
- Germany's precision farming corridor:Vineyard and orchard operators across Baden-Württemberg and Rhineland-Palatinate face stringent EU F-Gas Regulation compliance deadlines. Narrow-profile electric chassis with low-clearance cab designs are capturing margin premiums that internal combustion alternatives cannot match.
Market Restraints
- Lithium carbonate price volatility:Raw material input cost swings for lithium-ion pack assembly compress OEM margin structures and destabilize fleet electrification ROI calculations for agricultural cooperatives.
- Permanent magnet motor supply concentration:Rare earth processing capacity concentrates in China's Jiangsu and Shandong provinces, creating geopolitical exposure for European and North American tractor manufacturers dependent on scaled motor production.
- Fuel cell electric refueling infrastructure:Sub-15-minute hydrogen refueling cycles attract interest among large-scale operators, but station deployment lags in rural agricultural regions, constraining technology pathway diversification.
Strategic Opportunities
- Indian sub-40 HP tractor segment:Agricultural electrification remains underpenetrated among smallholder farming operations where diesel dominates procurement patterns. Localized lithium-ion pack assembly partnerships could unlock volume positions.
- Autonomous operating mode convergence:Integration of driverless field navigation with electric powertrains reduces labor dependency during planting and harvest windows. Precision agriculture software stacks anchor premium positioning in row-crop segments.
- EU Green Deal farm sustainability benchmarks:REACH battery material traceability mandates reshape supplier qualification criteria, creating first-mover advantages for OEMs with documented circular economy protocols and recycled content verification systems.
Industry Challenges
- High-voltage technician certification gaps:Agricultural equipment service networks lack sufficient trained personnel for battery pack diagnostics and thermal management system maintenance, extending downtime recovery intervals.
- Charging infrastructure interoperability standards:Fragmented connector protocols and communication bus architectures complicate fleet-wide charging depot planning for mixed-OEM agricultural operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Electric Tractor Market |
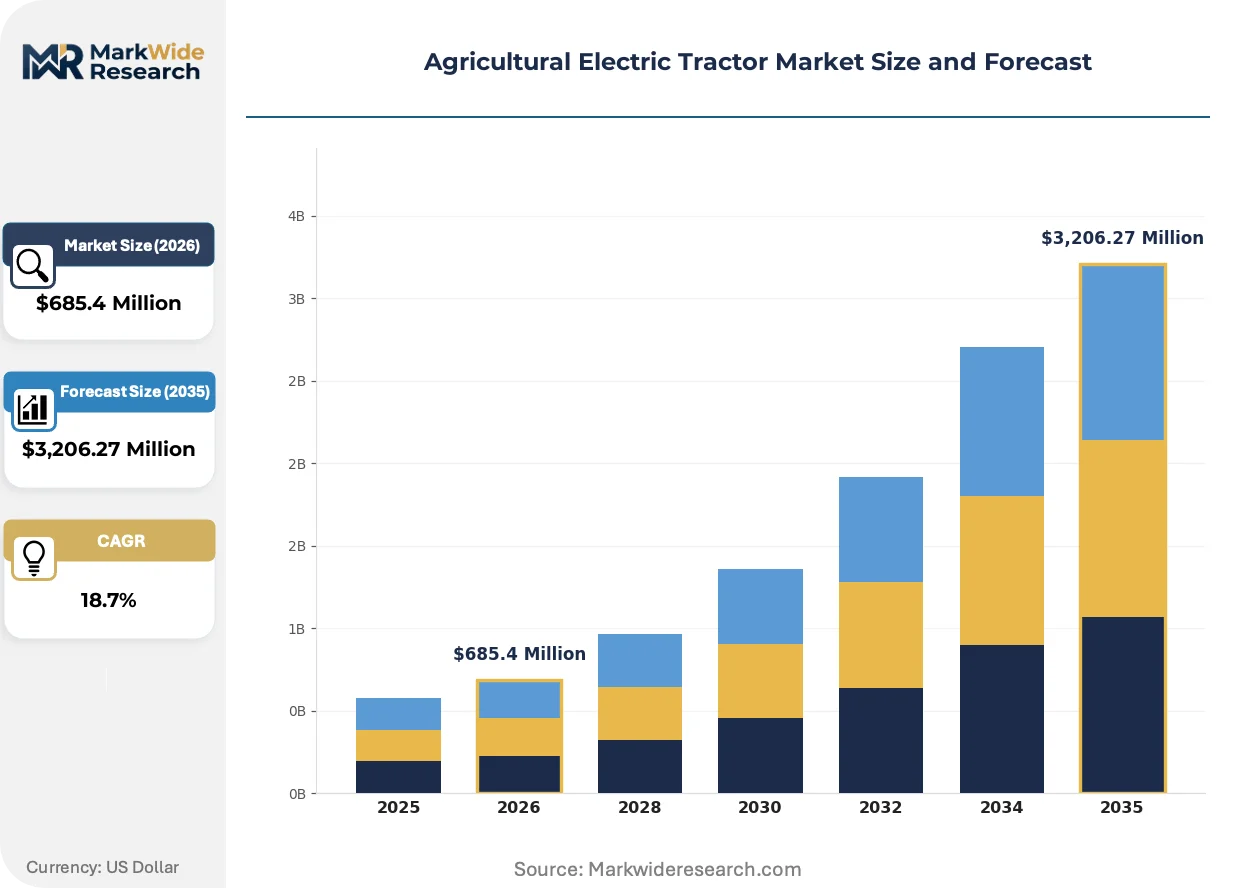
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Orchard Tractors, Garden Tractors End Use: Crop Farming, Livestock Farming, Horticulture, Forestry Technology: Battery Electric, Plug-in Hybrid, Fuel Cell Electric, Solar Electric Power Rating: Below 25 HP, 25 to 50 HP, 51 to 75 HP, Above 75 HP |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Monarch Tractor, Solectrac, Fendt, Mahindra & Mahindra, Escorts Kubota Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Electric Tractor Market Trends and Innovations
Electrification is rewriting competitive boundaries between established agricultural equipment manufacturers and technology-focused entrants, with software-defined functionality and energy management systems emerging as primary differentiation vectors rather than mechanical specifications alone.
Modular battery pack architectures with standardized cell-to-pack interfaces are rendering obsolete the proprietary powertrain integration strategies that historically locked customers into single-OEM service ecosystems. Vineyard and orchard operators in France's Champagne region are adopting swappable battery configurations at pace, enabling continuous operation through rapid pack exchange rather than fixed charging cycles. This technical trajectory is compressing after-sales revenue streams for incumbent distributors dependent on captive parts and service arrangements.
The EU F-Gas Regulation phase-down schedule for hydrofluorocarbon-based cooling systems is accelerating electric tractor adoption in temperature-sensitive specialty crop segments. Agricultural equipment manufacturers must redesign thermal management architectures to comply with refrigerant restrictions while maintaining battery pack performance across variable field conditions. German mixed-farming estates requiring sub-75 HP maneuverability are prioritizing Fendt-branded battery electric variants with compliant climate control systems ahead of certification deadlines.
Cooperative purchasing agreements among agricultural producer organizations are consolidating equipment procurement decisions into fewer, larger transactions with extended service and energy management provisions. Traditional dealer networks in Iowa and Illinois face disintermediation pressure as row-crop operators negotiate direct fleet electrification programs with OEMs and third-party charging infrastructure providers. This behavioral shift is most visible in North American corn-soybean belts where scale economies favor centralized energy procurement and predictive maintenance contracts over transactional equipment sales.
Agricultural Electric Tractor Market Segmentation
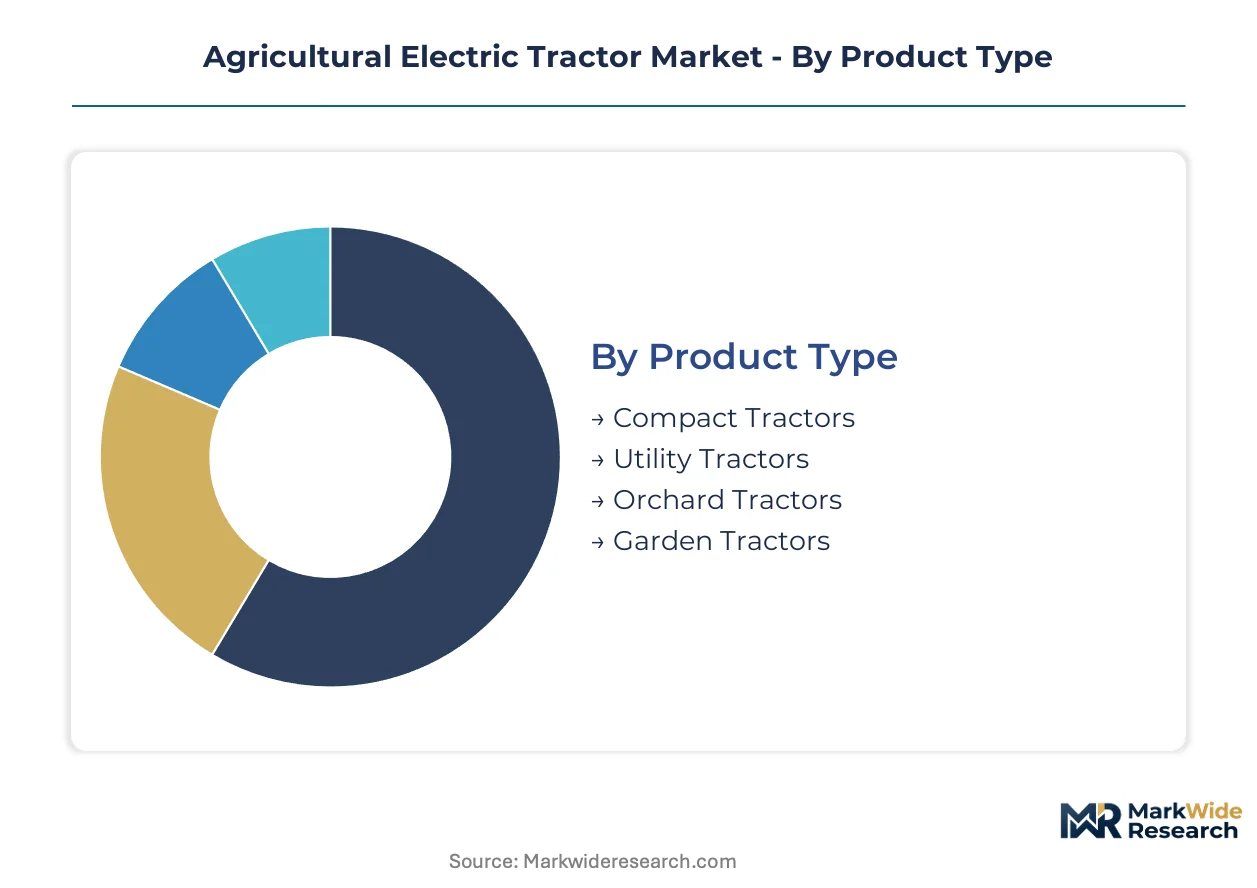
Electrification trajectories diverge sharply across tractor configurations and duty cycles. Segment boundaries reflect distinct battery pack sizing requirements, thermal management architectures, and charging infrastructure dependencies that reshape procurement economics for different agricultural operations.
Product Type:
Mature utility platforms dominate fleet electrification programs, while emerging narrow-profile chassis designs unlock specialty crop segments previously inaccessible to electric alternatives.
- Compact Tractors:Self-propelled units rated between 20 and 50 HP with lithium-ion packs from 20 kWh to 80 kWh, optimized for material handling and light tillage on small-to-medium holdings. Demand clusters among California Central Valley specialty crop growers facing CARB certification deadlines for diesel displacement.
- Utility Tractors:Versatile platforms spanning 50 to 100 HP with modular battery architectures enabling swappable pack configurations during intensive seasonal windows. German mixed-farming estates across Baden-Württemberg prioritize these units for sub-75 HP maneuverability combined with precision agriculture software integration.
- Orchard Tractors:Narrow-profile chassis with low-clearance cab designs and sub-40 kWh packs optimized for vineyard row spacing. Champagne region operators in France adopt these for continuous operation through rapid battery exchange systems.
- Garden Tractors:Sub-25 HP residential and small commercial units with integrated battery packs for landscaping and hobby farming applications. European garden equipment distributors stock these for estate maintenance contracts.
Utility tractors retain volume leadership; orchard tractors hold the steepest expansion curve.
End Use:
Application-driven duty cycles determine battery thermal management specifications and charging depot placement strategies across agricultural value chains.
- Crop Farming:Large-scale grain and oilseed operations requiring 8-16 hour field cycles with minimal downtime. Solid-state cell development is extending daily operating ranges beyond diesel-equivalent duty cycles for Iowa and Illinois row-crop operators.
- Livestock Farming:Manure handling, feed transport, and barn ventilation applications with intermittent duty cycles favoring opportunity charging. Dairy cooperatives in Wisconsin deploy these for barn-to-field material movement with mid-day plug-in intervals.
- Horticulture:Greenhouse and nursery operations with enclosed-space emissions constraints driving zero-tailpipe requirements. Netherlands greenhouse clusters adopt battery electric units for internal logistics under EU F-Gas Regulation compliance timelines.
- Forestry:Logging and land management applications with high-torque demands and remote operational profiles. Fuel cell electric variants attract interest here for sub-15-minute refueling cycles where charging infrastructure remains undeveloped.
Crop farming commands installed base dominance; horticulture applications are climbing the fastest as enclosed-space mandates tighten.
Technology:
Powertrain architecture selection hinges on duty cycle predictability, refueling infrastructure access, and capital deployment timelines for fleet operators.
- Battery Electric:Lithium-ion pack architectures from 20 kWh to 300 kWh delivering torque through permanent magnet synchronous motors without direct emissions. This pathway leads commercial deployments across vineyard and orchard segments where daily operating ranges fall within single-charge capabilities.
- Plug-in Hybrid:Dual-mode systems combining electric traction with range-extending combustion generators for intermittent high-load operations. Livestock farming applications in regions with sparse charging infrastructure favor this transitional configuration.
- Fuel Cell Electric:Hydrogen proton-exchange membrane systems enabling rapid refueling for continuous seasonal fieldwork. Large-scale crop farming operators in Germany's precision farming corridor evaluate these for harvest window intensity where charging downtime proves prohibitive.
- Solar Electric:Integrated photovoltaic arrays supplementing grid or depot charging for low-intensity applications. Indian smallholder operations pilot these for sub-40 HP irrigation and light tillage with minimal infrastructure dependency.
Battery electric retains technology leadership; fuel cell electric gains share fastest among large-scale operators seeking refueling parity with diesel.
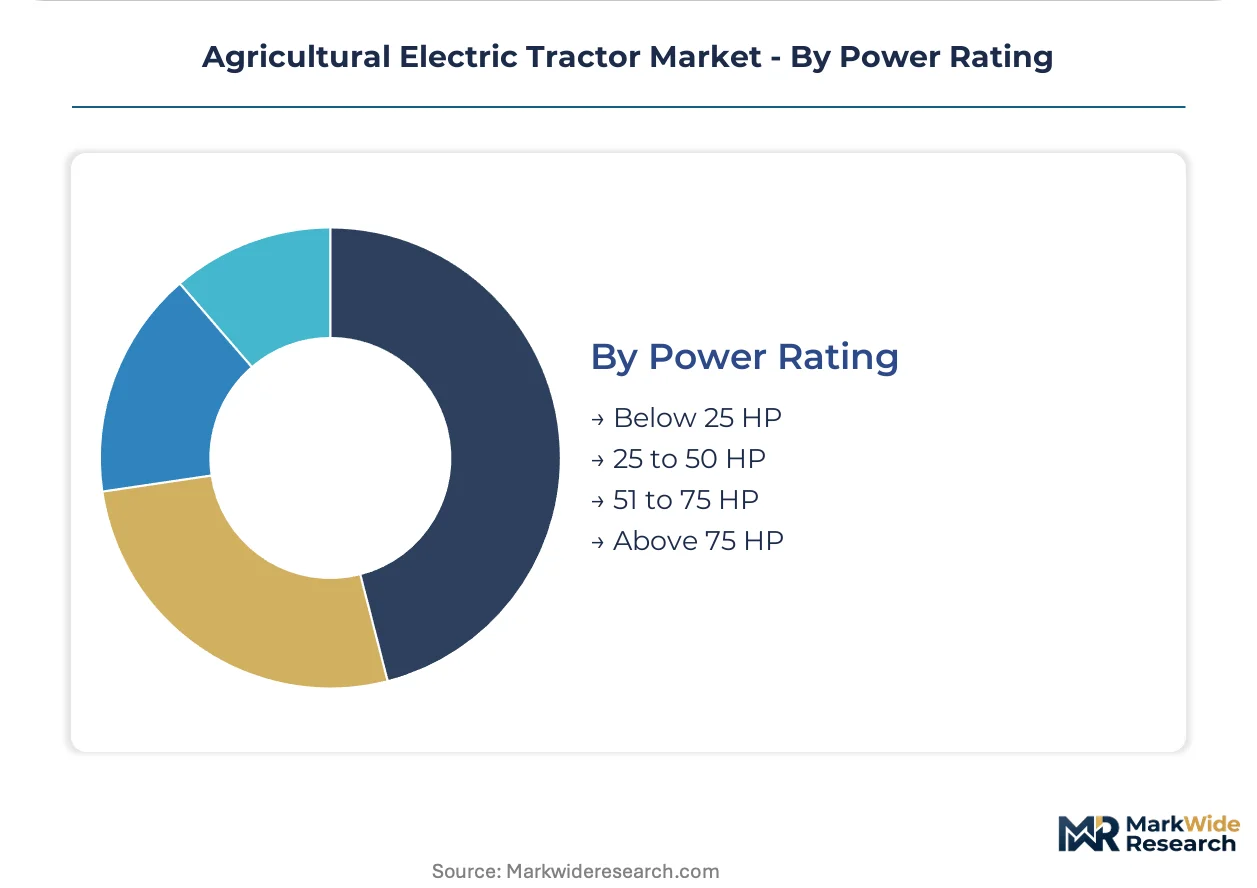
Power Rating:
Horsepower segmentation aligns battery pack cost structures with operational revenue generation potential across farm scale categories.
- Below 25 HP:Entry-level electric platforms for garden maintenance and smallholder horticulture. India's agricultural electrification programs target this band for localized lithium-ion pack assembly partnerships.
- 25 to 50 HP:Mid-range utility configurations dominating European vineyard and orchard electrification. France's Champagne region operators standardize on this rating for narrow-row maneuverability.
- 51 to 75 HP:Premium compact and utility tractors capturing margin premiums in mixed-farming estates. German Fendt-branded variants concentrate demand here for precision agriculture integration.
- Above 75 HP:High-torque platforms for primary tillage and heavy material handling with largest battery pack requirements. North American row-crop segments await solid-state commercialization for viable total cost of ownership in this band.
The 25 to 50 HP band dominates shipment volumes; above 75 HP applications show the steepest technology improvement trajectory as energy density advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's hydrogen import terminal underwrites Germany's role as Europe's agricultural electrification logistics hub, connecting Jiangsu-manufactured battery packs to Central European farming equipment supply chains.
United States
California's Central Valley specialty crop growers face CARB tractor certification deadlines that eliminate new diesel procurement options. The EPA's evolving off-road emissions standards compress displacement timelines for Iowa and Illinois row-crop operators. Precision agriculture software integration concentrates development activity in the Midwest corn-soybean belt.
Germany
Vineyard and orchard operators across Baden-Württemberg and Rhineland-Palatinate face stringent EU F-Gas Regulation compliance deadlines for hydrofluorocarbon cooling systems. The REACH battery material traceability mandate reshapes supplier qualification criteria across OEM supply chains. Stuttgart's precision farming corridor anchors Fendt-branded battery electric variant development for mixed-farming estates.
China
Jiangsu and Shandong provinces narrow manufacturing cost gaps through scaled lithium-ion pack assembly and localized permanent magnet motor production. The MIIT dual carbon goals accelerate domestic agricultural equipment electrification roadmaps. Ningbo's port infrastructure exports battery modules to European and Southeast Asian tractor assemblers.
India
Agricultural electrification remains underpenetrated among smallholder farming operations where diesel dominates sub-40 HP procurement patterns. The PLI scheme for advanced chemistry cell manufacturing attracts localized pack assembly partnerships. Maharashtra's agricultural machinery clusters pilot solar-electric configurations for irrigation applications.
France
Champagne region vineyard operators adopt swappable battery configurations for continuous narrow-row operation. The EU Green Deal farm sustainability benchmarks enforce emissions reporting across agricultural cooperatives. Reims-based equipment distributors face margin compression as cooperative purchasing agreements consolidate procurement decisions.
Agricultural Electric Tractor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on battery cell and permanent magnet motor supply. The vendor base spans consolidated agricultural equipment multinationals with precision agriculture software stacks, specialized electric tractor entrants with autonomous operating modes, and Asian manufacturing conglomerates with scaled lithium-ion assembly capacity. Three archetypes dominate: legacy OEMs defending row-crop positions through electrified variants, technology-focused entrants capturing vineyard and orchard premiums via narrow-profile chassis, and component suppliers backward integrating into pack assembly. Competitive moves concentrate on strategic partnerships for charging infrastructure interoperability and portfolio diversification into swappable battery architectures.
Among legacy equipment manufacturers, Deere & Company and AGCO Corporation exemplify platform integrators leveraging precision agriculture software to anchor premium positioning. Kubota Corporation represents the Asian manufacturing archetype with established distribution density in sub-75 HP utility segments. Monarch Tractor occupies the technology-entrant tier, competing through autonomous operating modes that reduce labor dependency during intensive seasonal windows.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Monarch Tractor |
| Solectrac |
| Fendt |
| Mahindra & Mahindra |
| Escorts Kubota Limited |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Jiangsu province's lithium-ion cell assembly lines is compressing pack-level pricing and forcing tiered volume commitments from European tractor assemblers. This utilization dynamic simultaneously erodes OEM margin structures and accelerates procurement centralization among agricultural cooperatives seeking locked-in cell supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates precision-agriculture-integrated platforms from basic utility configurations and entry-level garden equipment. Price differentiation hinges on software stack sophistication and battery pack modularity, with California specialty crop cooperatives showing highest sensitivity due to CARB compliance-driven fleet refresh cycles. Cost compression in standard-tier utility tractors is intensifying because of Chinese pack assembly competition. Premium positioning remains least price-sensitive among German mixed-farming estates prioritizing Fendt-branded vineyard maneuverability.
Supply Chain Analysis
Contract manufacturing concentration rests with CATL and BYD cell assembly facilities in Jiangsu and Shandong, supplemented by LG Energy Solution's Korean output for European premium tier qualification. Permanent magnet motor production draws from Chinese rare earth processing, South Korean winding automation, and Japanese magnetic material refinement. Single-source vulnerability concentrates in dysprosium and terbium supply from Chinese separation facilities. Distribution runs through Stuttgart's precision farming corridor for European OEM integration and Moline's dealer networks for North American row-crop penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural cooperative purchasing consolidation across Iowa and Illinois is shifting procurement leverage toward volume-buyer organizations with direct OEM negotiation capacity. This buyer-power concentration fragments traditional dealer intermediary economics.
For Market Incumbents: Entrench software-defined functionality as the primary lock-in mechanism against Monarch Tractor's autonomous operating mode encroachment. Deepen backward integration into battery pack assembly through joint ventures with Jiangsu cell producers to secure supply priority during lithium carbonate volatility. Prioritize charging infrastructure interoperability certification to defend against third-party depot providers disintermediating dealer service networks.
For New Entrants and Emerging Players: India's sub-40 HP smallholder segment offers the most penetrable white space given diesel dominance and minimal electrification infrastructure. Target Maharashtra's agricultural machinery clusters with solar-electric configurations requiring minimal grid dependency. Pursue localized pack assembly partnerships under the PLI scheme to bypass incumbent distribution density.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision agriculture software providers with predictive maintenance contracts and energy management subscriptions. Long-term viability favors platform integrators with documented circular economy protocols meeting REACH traceability mandates. Monitor solid-state battery commercialization timelines as the critical inflection signal for above-75 HP segment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Architecture Deployment | Champagne region vineyard operators adopt rapid pack exchange for continuous narrow-row operation cycles. |
| Precision Agriculture Software Integration | John Deere anchors premium positioning through data-driven field navigation and predictive maintenance contracts. |
| EU F-Gas Regulation Thermal System Redesign | German Fendt-branded variants prioritize compliant climate control ahead of hydrofluorocarbon phase-down deadlines. |
| Charging Infrastructure Interoperability Partnership | Mixed-OEM agricultural operations demand unified connector protocols for fleet-wide depot planning. |
| Localized Lithium-Ion Pack Assembly | Indian PLI scheme attracts partnerships targeting sub-40 HP smallholder electrification programs. |
Research Methodology
Cross-validation between OEM platform engineering interviews and agricultural cooperative procurement records anchors the qualitative findings. Primary fieldwork engaged tractor fleet managers, precision agriculture software developers, battery pack thermal engineers, and dealer network operations heads across California, Iowa, Baden-Württemberg, and Jiangsu. Secondary validation drew from EPA off-road emissions filings, CARB tractor certification databases, EU F-Gas Regulation implementation reports, and MIIT dual carbon goal disclosures. Bottom-up shipment estimates triangulated against top-down OEM revenue attribution by powertrain architecture.
Calibration against historical electrification adoption curves in adjacent off-road equipment segments informed the projection framework across the analysis window. Segmentation dimensions modeled include tractor configuration, power rating band, end-use application, and technology pathway with regional regulatory cluster overlays. CAGRs derived from installed base replacement cycles, fleet electrification program announcements, and energy density improvement trajectories. Solid-state battery commercialization timelines and charging infrastructure deployment rates served as key scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese manufacturing conglomerates backward integrating into European distribution would shift outcomes. Quarterly review of lithium carbonate futures pricing and CARB enforcement phase transitions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Brazil Tractors Market