
 Vietnam Agricultural Tractor Market | 2026-2036
Vietnam Agricultural Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Agricultural Tractor Market Analytics
Steel-reinforced composite hoods and lighter aluminum transmission housings are restructuring total cost of ownership for Vietnamese tractor buyers. Kubota Corporation leverages its localized assembly plant in Vinh Phuc to sustain price competitiveness against fully imported units. VEAM anchors the domestic supply base through in-house diesel engine production and government procurement relationships. Mahindra & Mahindra competes aggressively in the northern highlands with ruggedized two-wheel-drive platforms tailored to hillside terracts.
An agricultural tractor is a self-propelled power unit with a rated engine output typically spanning 15 to 300 horsepower, designed to pull or power mounted implements for soil tillage, seeding, crop management, and material transport across uneven farmland terrain. Diesel engines dominate the Vietnamese market due to torque characteristics, fuel availability, and established service networks in rural communes. Compact tractors represent the fastest-expanding product category as smallholder plots fragment and orchard operations proliferate in Lam Dong and Binh Thuan provinces. Individual farmers constitute the deepest end-user pool, though farming cooperatives command superior bargaining power and access to state-backed credit lines for fleet purchases.
Vietnam's Ministry of Agriculture and Rural Development sets type-approval requirements for imported agricultural machinery, while the national standards body administers emissions and safety testing protocols that filter non-compliant suppliers from distribution channels. The country's central bank coordinates preferential lending rates through the Vietnam Bank for Social Policies, directly shaping seasonal purchase cycles. Stakeholders must monitor how electric engine prototypes perform in prolonged monsoon conditions before committing capital to next-generation product lines.
Market Dynamics
Vietnam's tightening national technical standards for diesel engine emissions are forcing importers to re-engineer powertrain offerings or exit distribution channels entirely. This regulatory compression is restructuring competitive positioning across the Mekong Delta and Red River Delta procurement corridors.
Growth Catalysts
- Preferential Lending Rates:The Vietnam Bank for Social Policies coordinates subsidized credit lines that compress seasonal purchase cycles for farming cooperatives seeking fleet expansion.
- Mekong Delta Mechanization:Rice farming cooperatives are expanding mechanized land preparation fleets to offset labor migration to urban manufacturing zones.
- Compact Tractor Demand:Smallholder plot fragmentation in Lam Dong and Binh Thuan provinces is accelerating orchard-specific equipment procurement.
Market Restraints
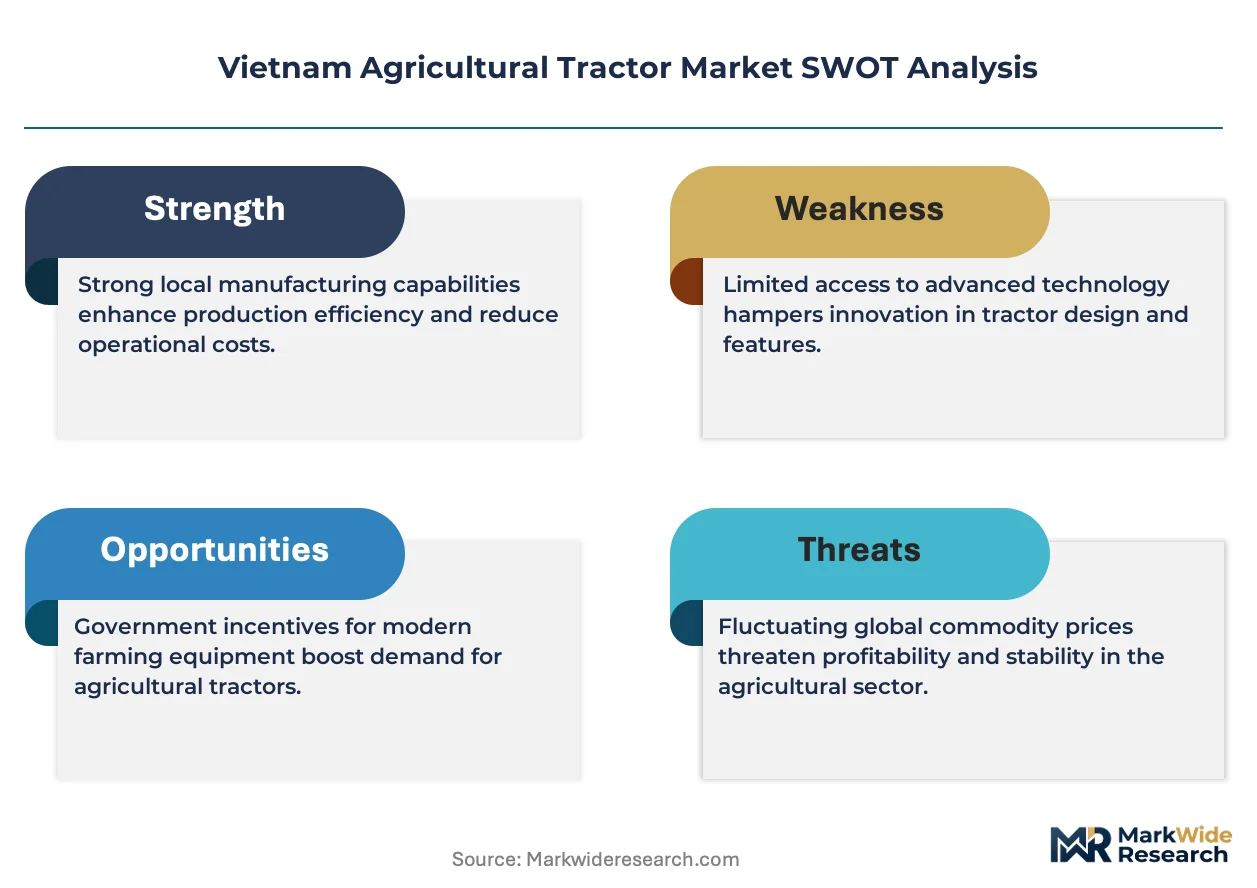
- Steel-Aluminum Input Volatility:Fluctuating global prices for steel-reinforced composites and aluminum transmission housings compress margin visibility for domestic assemblers.
- Import Dependency:Diesel engine technology concentrates among Japanese and Indian suppliers, exposing buyers to currency-adjusted pricing swings.
- Emissions Compliance Friction:Type-approval requirements from Vietnam's Ministry of Agriculture and Rural Development extend lead times for non-certified powertrain introductions.
Strategic Opportunities
- Electric Powertrain Pilots:Battery-electric prototypes tested through monsoon cycles in Vinh Phuc could unlock first-mover positioning before national electrification mandates emerge.
- Highland Terrain Specialization:Ruggedized two-wheel-drive platforms for hillside vegetable cultivation in Lao Cai and Ha Giang remain underpenetrated versus delta markets.
- Service Network Unbundling:Independent repair collectives in rural communes offer alternative channel structures beyond manufacturer-captive service centers.
Industry Challenges
- Diagnostic Skill Scarcity:Electronic fuel injection and after-treatment systems require technician training that outpaces vocational institute output in northern provinces.
- Homologation Timeline Compression:Accelerated emissions testing protocols strain engineering resources as multiple product lines require simultaneous recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Agricultural Tractor Market |
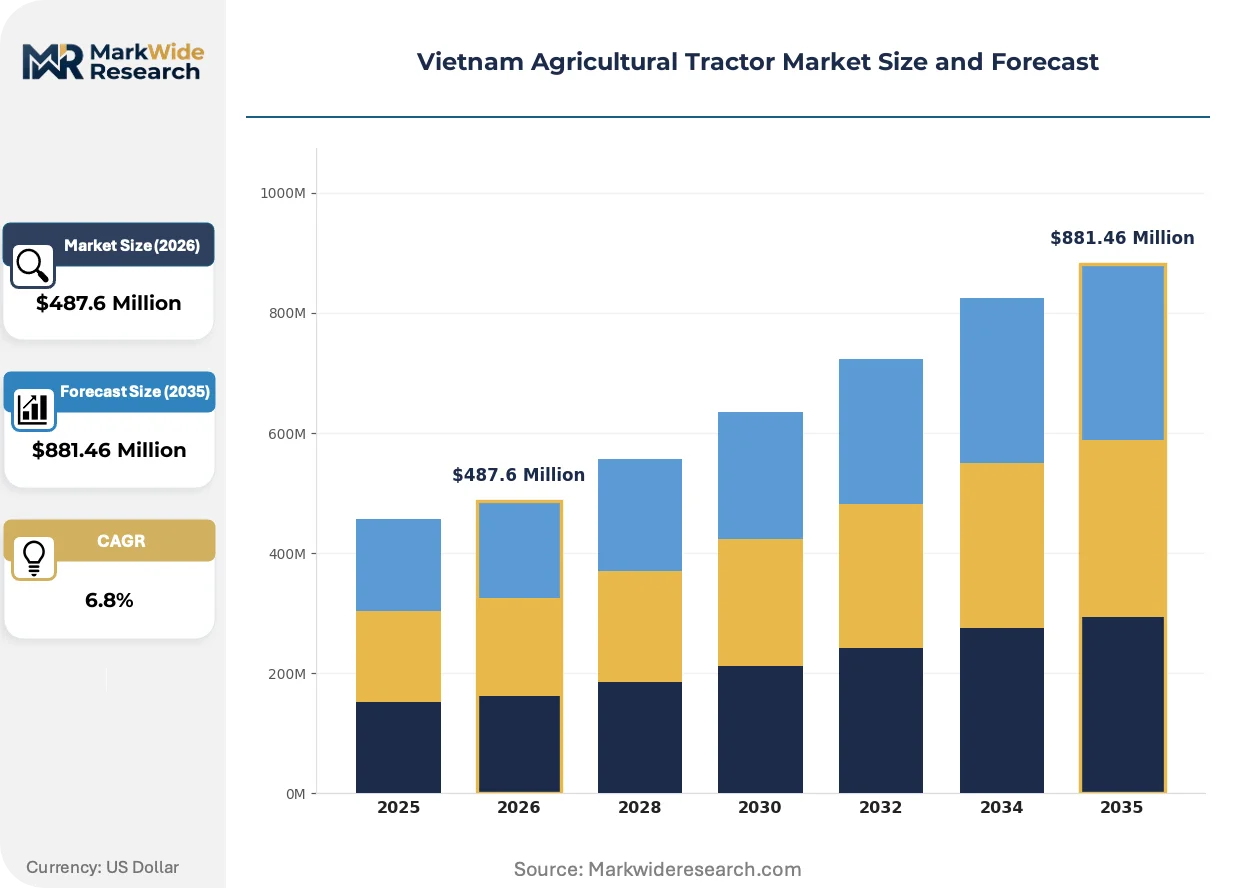
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
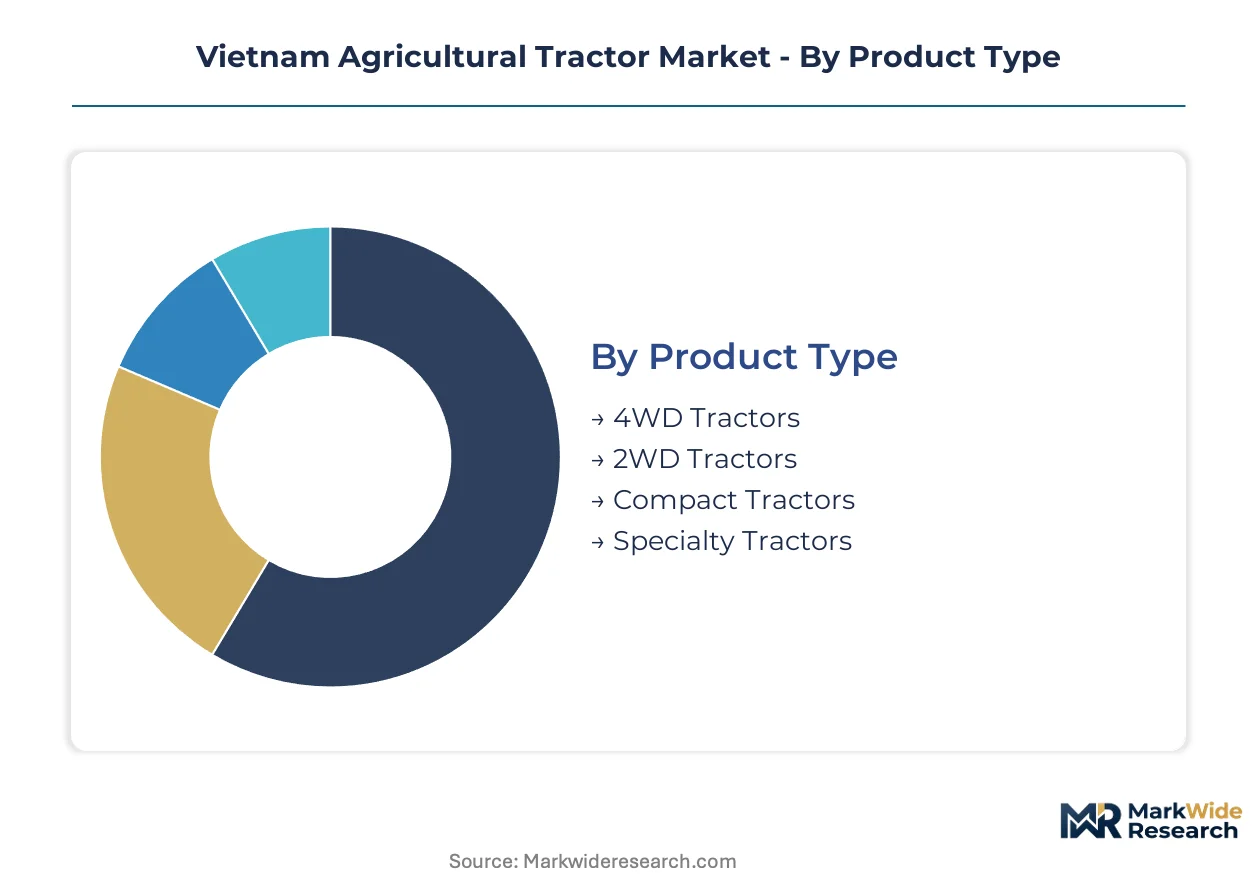
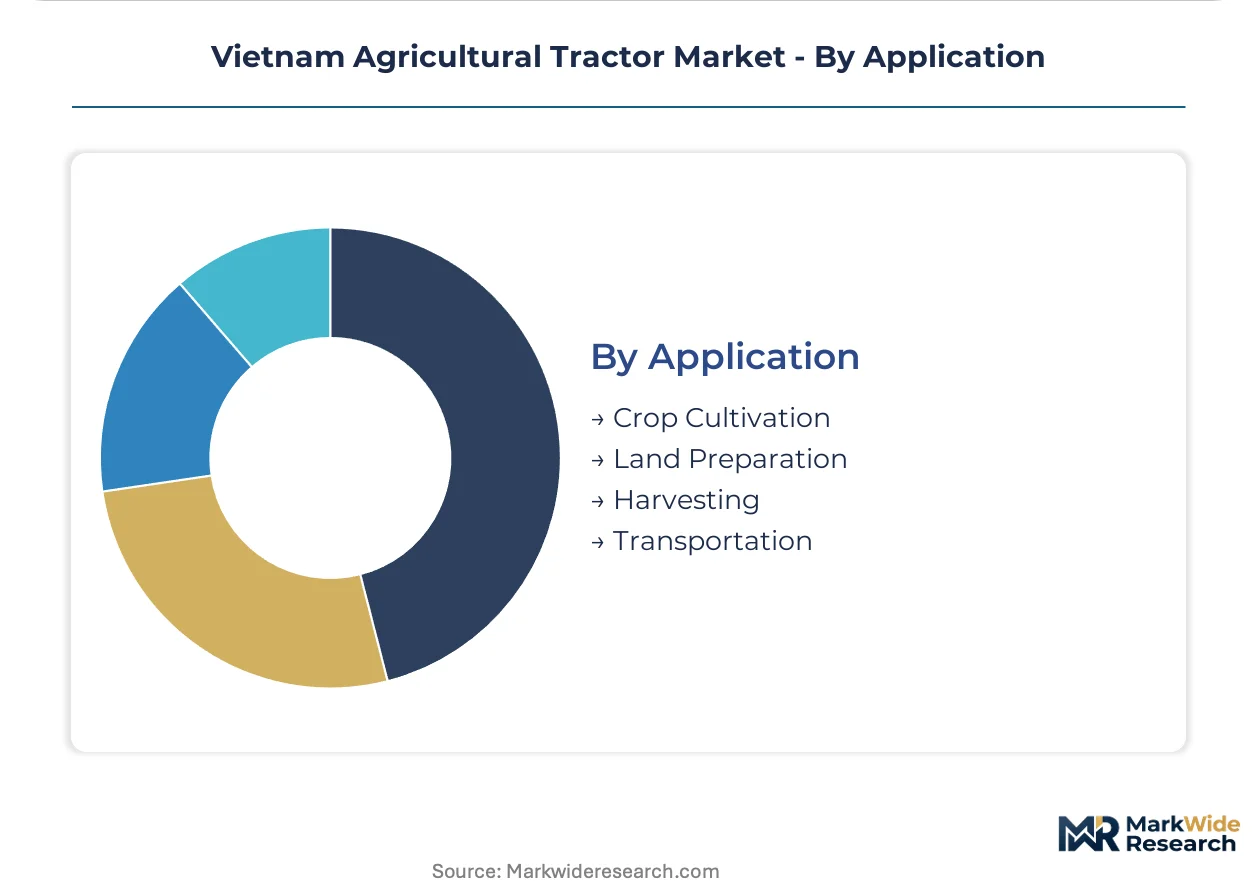
| Segmentation | Product Type: 4WD Tractors, 2WD Tractors, Compact Tractors, Specialty Tractors End User: Farming Cooperatives, Individual Farmers, Agricultural Contractors, Large Enterprises Engine Type: Diesel Engines, Electric Engines, Gasoline Engines, Hybrid Engines Application: Crop Cultivation, Land Preparation, Harvesting, Transportation |
| Companies Covered | Kubota Corporation, Yanmar Holdings, CNH Industrial, CLAAS, Vietnam Engine and Agricultural Machinery Corporation (VEAM), John Deere, Mahindra & Mahindra, Truong Hai Auto Corporation (THACO), Iseki, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Agricultural Tractor Market Evolving Landscape
Powertrain electrification, materials lightweighting, and procurement digitization are converging to reshape how Vietnamese farmers acquire and operate field equipment. These forces are compressing traditional replacement cycles while elevating total-cost-of-ownership analytics in purchase decisions.
Steel-reinforced composite hoods are absorbing impact resistance requirements previously met by stamped metal fabrications. Orchard operators in Binh Thuan are specifying these assemblies for narrow-row citrus applications where weight reduction improves maneuverability. The technology is absorbing cost premiums through extended service intervals and corrosion resistance in high-humidity delta conditions.
Vietnam's national standards body has administered tightened emissions testing protocols that filter non-compliant diesel engines from import channels. Industrial consequence falls most heavily on European suppliers lacking localized assembly infrastructure. Northern highland distributors are responding by concentrating inventory on pre-certified Japanese and Indian powertrains with established service footprints.
Farming cooperatives are consolidating procurement authority through state-backed credit aggregation, displacing individual farmer decision-making in fleet transactions. Equipment dealers in the Red River Delta are restructuring sales teams to engage cooperative technical committees rather than single-owner accounts. This concentration is most visible in intensive vegetable zones where shared machinery pools amortize capital across multiple smallholders.
Vietnam Agricultural Tractor Market Segmentation
Segmentation in Vietnam's agricultural tractor market reveals how powertrain specifications, operator scale, and terrain demands fragment procurement patterns across the Mekong Delta and northern highlands. Distinct buyer profiles—cooperative fleets versus individual smallholders—pull equipment specifications in divergent directions.
Product Type:
Supply concentration among Japanese and Indian assemblers funnels production toward specific drivetrain configurations that dominate import channels.
- 4WD Tractors:Four-wheel-drive systems distribute torque across all axles for paddy field traction in flooded Mekong Delta conditions. Rice farming cooperatives in An Giang and Kien Giang provinces prioritize these units for heavy tillage sequences.
- Compact Tractors:Narrow-profile chassis with sub-40 horsepower ratings navigate tight citrus rows in Binh Thuan orchard belts. Lam Dong coffee smallholders are driving procurement volume as plot fragmentation accelerates.
- 2WD Tractors:Two-wheel-drive platforms serve dry-field vegetable cultivation in the Red River Delta where traction demands remain moderate.
- Specialty Tractors:Vineyard-specific and hillside configurations address slope gradients exceeding 15 degrees in Lao Cai terraced zones.
4WD tractors absorb the bulk of installed capacity; compact tractors are expanding most quickly.
End User:
Credit access tiers separate buyers into sharply divergent price sensitivity bands that reshape dealer engagement models.
- Farming Cooperatives:Collective purchasing entities aggregate capital through Vietnam Bank for Social Policies credit lines. Mekong Delta rice cooperatives command fleet-scale discounts unavailable to individual accounts.
- Individual Farmers:Owner-operators of sub-2-hectare plots dominate unit volume but purchase sporadically through seasonal cash flows. Northern highland vegetable growers in Ha Giang fall predominantly in this tier.
- Agricultural Contractors:Service providers rent equipment and labor to smallholders lacking machinery ownership. These operators cycle units faster and prioritize service network density.
- Large Enterprises:Industrial farming conglomerates in the Central Highlands specify premium specifications with extended warranty terms.
Farming cooperatives concentrate procurement authority; individual farmers remain the deepest volume pool.
Engine Type:
Emissions testing protocols from Vietnam's Ministry of Agriculture and Rural Development filter import eligibility across combustion and electrification pathways.
- Diesel Engines:Compression-ignition powertrains deliver torque curves optimized for tillage loads. Established service networks in rural communes sustain their dominance despite tightening emission standards.
- Electric Engines:Battery-electric prototypes undergo monsoon-season trials in Vinh Phuc to validate waterproofing and range degradation. First-mover positioning awaits proven field durability.
- Gasoline Engines:Spark-ignition units occupy niche roles in light-duty transport and small-scale cultivation where capital constraints bite hardest.
- Hybrid Engines:Parallel-hybrid architectures blending diesel prime movers with electric assist remain pre-commercial in Vietnamese distribution channels.
Diesel engines anchor current installed base; electric engines are climbing the fastest among emerging alternatives.
Application:
Seasonal labor migration patterns mechanize specific field operations ahead of others, concentrating equipment deployment in land preparation phases.
- Land Preparation:Primary tillage and seedbed finishing consume the highest horsepower ratings and tractor operating hours. Mekong Delta cooperatives mechanize this stage first to offset rural labor outflows.
- Crop Cultivation:Row-crop maintenance including cultivation and spraying demands maneuverability in intensive vegetable zones of Hung Yen and Vinh Phuc.
- Harvesting:Tractor-powered implements for grain and forage collection operate in compressed seasonal windows requiring high reliability.
- Transportation:Trailer-hauling applications across uneven farm tracks stress transmission durability and braking systems.
Land preparation absorbs the bulk of fleet deployment; crop cultivation is gaining share fastest as orchard mechanization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vinh Phuc province anchors Vietnam's tractor assembly concentration through its specialized industrial zone incentives, drawing Japanese and domestic manufacturers into localized production clusters that reshape import dependency patterns across the northern Red River Delta corridor.
Mekong Delta
Rice farming cooperatives in An Giang and Kien Giang provinces are expanding four-wheel-drive fleet capacity to offset seasonal labor shortages during peak land preparation windows. Vietnam's Ministry of Agriculture and Rural Development channels subsidized credit through the Vietnam Bank for Social Policies specifically for mechanization in this zone. Can Tho serves as the regional distribution hub where dealers stock heavy-tillage configurations optimized for flooded paddy conditions.
Red River Delta
Intensive vegetable cultivation in Hung Yen and Vinh Phuc provinces generates demand for mid-horsepower two-wheel-drive platforms suited to dry-field row crops. The national standards body administers tightened emissions testing protocols that filter non-compliant diesel engines from import channels entering through Hai Phong port. Bac Ninh's industrial corridor hosts component suppliers feeding localized transmission and axle assembly operations.
Central Highlands
Large-scale coffee and pepper estates in Lam Dong and Dak Lak provinces specify premium compact tractors for inter-row cultivation on fragmented hillside plots. Provincial agricultural extension offices coordinate demonstration programs for orchard-specific equipment configurations. Da Lat functions as the regional technical service center where manufacturer-captive workshops handle complex powertrain diagnostics.
Southeast Region
Binh Thuan's citrus belt drives narrow-profile compact tractor procurement for high-density orchard layouts where maneuverability outweighs raw horsepower. The Binh Duong industrial zone supplies steel-reinforced composite hood components to domestic assemblers. Ho Chi Minh City-based distributors maintain inventory buffers for southern provinces facing extended monsoon delivery disruptions.
Northern Highlands
Terraced vegetable cultivation in Lao Cai and Ha Giang provinces creates specialized demand for ruggedized two-wheel-drive platforms with enhanced braking systems for slope gradients exceeding 15 degrees. Provincial rural development programs prioritize mechanization access for ethnic minority farming communities. Ha Giang City hosts a sparse service network where independent repair collectives fill gaps left by manufacturer-captive centers.
Vietnam Agricultural Tractor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with localized assemblers holding structural cost advantages in volume tiers while fully imported brands dominate premium specifications. The competitive set organizes around three strategic archetypes: Japanese multinationals with regional assembly infrastructure, Indian scale players leveraging ruggedized platform specialization, and domestic state-linked manufacturers with captive engine production. Market participants defend position through backward integration into powertrain sourcing and geographic concentration in government procurement corridors.
Within the multinational tier, Kubota Corporation and Yanmar Holdings exemplify the localized assembly archetype, while Vietnam Engine and Agricultural Machinery Corporation occupies a position anchoring domestic supply through in-house diesel engine capabilities. Mahindra & Mahindra represents the Indian scale-specialist model competing in terrain-specific configurations.
| Leading Market Players |
|---|
| Kubota Corporation |
| Yanmar Holdings |
| CNH Industrial |
| CLAAS |
| Vietnam Engine and Agricultural Machinery Corporation (VEAM) |
| John Deere |
| Mahindra & Mahindra |
| Truong Hai Auto Corporation (THACO) |
| Iseki |
| Others |
Value Network & Pricing Analysis
Steel-reinforced composite hoods and aluminum transmission housing prices cascade through Vietnamese tractor assembly operations, compressing margin structures for domestic assemblers while elevating landed costs for fully imported units. This raw-material volatility stratifies end-market pricing across cooperative fleet buyers and individual smallholders.
Pricing Analysis
Lead-time premiums for pre-certified powertrain inventory command pricing advantages over spot-market diesel engines awaiting Vietnam's Ministry of Agriculture and Rural Development type-approval. Three-tier pricing structure across premium, standard, and economy levels separates Japanese-assembled units with localized content from Indian ruggedized platforms and bare-bones Chinese imports. Pricing pressure stems from currency-adjusted engine sourcing costs, with individual farmers in northern highlands exhibiting highest price sensitivity versus Mekong Delta cooperatives leveraging Vietnam Bank for Social Policies credit lines.
Supply Chain Analysis
Freight costs from Japanese component hubs and Indian engine plants concentrate import dependency in Hai Phong and Ho Chi Minh City port corridors. Diesel engine technology draws from Japan, India, and Thailand manufacturing bases, while steel-reinforced composites and aluminum castings feed from Chinese and South Korean metallurgical suppliers. Single-source vulnerability in electronic fuel injection systems threatens service continuity, with distribution running through manufacturer-captive dealers and emerging independent repair collectives in rural communes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's agricultural tractor market operates as a vertical-integration race where captive diesel engine production and localized assembly infrastructure determine cost competitiveness. Players are pursuing backward integration into powertrain sourcing to defend margin positions against currency volatility and emissions compliance friction.
For Market Incumbents: Lock in cooperative procurement relationships through Vietnam Bank for Social Policies credit aggregation, securing fleet-scale volume commitments before electric powertrain mandates reshape competitive dynamics. Expand Vinh Phuc assembly capacity to absorb steel-aluminum input volatility through localized content rules, while investing in technician training partnerships to address diagnostic skill scarcity in northern provinces. For New Entrants and Emerging Players: Vietnam's tightening national technical standards for diesel engine emissions opens a window for battery-electric prototype pilots through monsoon validation cycles in Vinh Phuc, securing first-mover positioning before electrification mandates harden. Target the underpenetrated northern highlands terrain segment with ruggedized two-wheel-drive configurations, leveraging independent repair collectives as alternative service channels versus established dealer networks. For Investors and Strategic Acquirers: The window for entry favors domestic assemblers with in-house engine capabilities and government procurement relationships, given the long-term viability of state-backed mechanization programs. Monitor electric powertrain durability signals from Vinh Phuc monsoon trials as the critical inflection indicator for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Assembly Expansion | Vinh Phuc industrial zone incentives reduce import dependency and compress landed costs versus fully imported units. |
| Emissions Compliance Investment | Pre-certification with Vietnam's Ministry of Agriculture and Rural Development accelerates market access before regulatory deadlines. |
| Cooperative Credit Aggregation | Vietnam Bank for Social Policies relationships unlock fleet-scale procurement volumes unavailable to individual account channels. |
| Electric Powertrain Piloting | Monsoon-season validation in Vinh Phuc establishes technical credibility ahead of national electrification mandates. |
| Highland Service Network Buildout | Independent repair collectives in Lao Cai and Ha Giang address diagnostic skill gaps left by manufacturer-captive centers. |
Research Methodology
Document review covered Vietnam Ministry of Agriculture and Rural Development type-approval records, Vietnam Bank for Social Policies credit disbursement data, and customs import manifests for diesel engine categories, complemented by interviews with equipment dealers in Can Tho and Hai Phong, cooperative technical committee members in An Giang, and aftermarket service heads in Da Lat. Secondary validation drew from provincial agricultural extension office reports, industrial zone investment disclosures, and national standards body emissions testing protocols. Bottom-up unit volume estimates triangulated against top-down fleet deployment data across Mekong Delta and Red River Delta corridors.
Historical procurement patterns from cooperative fleet expansions and individual farmer replacement cycles were cross-referenced against panel input from distributor inventory managers and manufacturer regional directors. Segmentation modeling spanned powertrain configuration, operator scale tier, terrain application, and regional credit access intensity. CAGRs were derived from fitted trend extrapolation moderated by regulatory phase-in assumptions and labor migration elasticity coefficients, with monsoon seasonality and emissions compliance timelines as industry-specific forecast inputs.
The model assumes a gradual diesel-to-electric transition pathway; accelerated electrification mandates or battery durability failures in flooded paddy conditions would alter the outlook substantially. Stakeholders should weight assumptions against their own operating context and regional credit access profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Hay Making Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Driverless Tractor Market