
 Hay Making Machinery Market | 2026-2036
Hay Making Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Hay Making Machinery Market Analysis
Dealer networks across North America and Europe are tilting toward service bundling and precision-ag subscription models. Kubota Corporation leverages its compact tractor footprint to push attached mower-conditioners through rural cooperatives. CLAAS KGaA mbH anchors its position in high-density large square balers with proprietary knotter technology. Deere & Company controls fleet financing channels that lock in multi-year replacement cycles among commercial hay exporters.
Hay making machinery encompasses mowers, conditioners, tedders, rakes, and balers engineered to cut, dry, gather, and compress forage crops into storable formats with target moisture below twenty percent. These machines serve livestock producers who must preserve nutritional value across seasonal gaps when pasture growth stalls. Among product type segments, balers command the deepest margin pools due to knotter complexity and replacement part dependency. Semi-automatic technology segments are gaining fastest as labor scarcity pushes mid-scale operators toward autosteering and bale-weighing integration. Conventional technology still dominates installed base volumes across Eastern European smallholder fleets where capital constraints persist.
EPA Tier 4 Final standards and EU Stage V emissions frameworks are forcing engine redesigns that add cost but create regulatory moats against uncertified imports. ISO 4254 safety standards govern guarding and operator protection, shaping export eligibility for manufacturers targeting Australian and Canadian markets. Stakeholders must monitor how California Air Resources Board precedents cascade into other state-level off-road diesel restrictions that could accelerate electric platform development.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing engine architectures while dairy cooperatives in the Great Plains accelerate fleet replacement cycles to secure winter feed supplies.
Growth Catalysts
- Emissions-Driven Equipment Refresh:EPA Tier 4 Final standards for off-road diesel engines are forcing commercial hay exporters to retire pre-compliant machinery ahead of normal depreciation schedules, creating replacement demand.
- Great Plains Cattle Density:Nebraska through the Dakotas corridor concentrates cattle operations on large-field geometries that favor high-capacity mower-conditioners and large square balers.
- Autosteering Integration:Labor scarcity across Midwest dairy cooperatives is pulling mid-scale operators toward semi-automatic technology segments with bale-weighing and GPS guidance.
Market Restraints
- Engine Cost Inflation:EPA Tier 4 Final and EU Stage V redesigns add cost to powertrain architectures, squeezing margin pools for equipment financing channels.
- Smallholder Capital Constraints:Eastern European smallholder fleets lack access to fleet financing, trapping installed base volumes in conventional technology segments.
- Knotter Complexity Premium:Proprietary knotter technology in high-density large square balers creates replacement part dependency that elevates total cost of ownership.
Strategic Opportunities
- Service Bundling Pivot:Dealer networks across North America and Europe are tilting toward precision-ag subscription models that attach recurring revenue to equipment sales.
- Electric Platform Development:California Air Resources Board precedents signal state-level off-road diesel restrictions that favor early electric architecture investment.
- Rural Cooperative Penetration:Compact tractor footprints enable attached mower-conditioner sales through rural cooperatives serving underbanked agricultural regions.
Industry Challenges
- ISO 4254 Certification Timelines:Guarding and operator protection standards govern export eligibility for Australian and Canadian markets, creating compliance bottlenecks for non-integrated manufacturers.
- Legacy Fleet Integration:Semi-automatic technology adoption requires retrofit compatibility with existing tractor hydraulic systems, complicating upgrade paths for mixed-age fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hay Making Machinery Market |
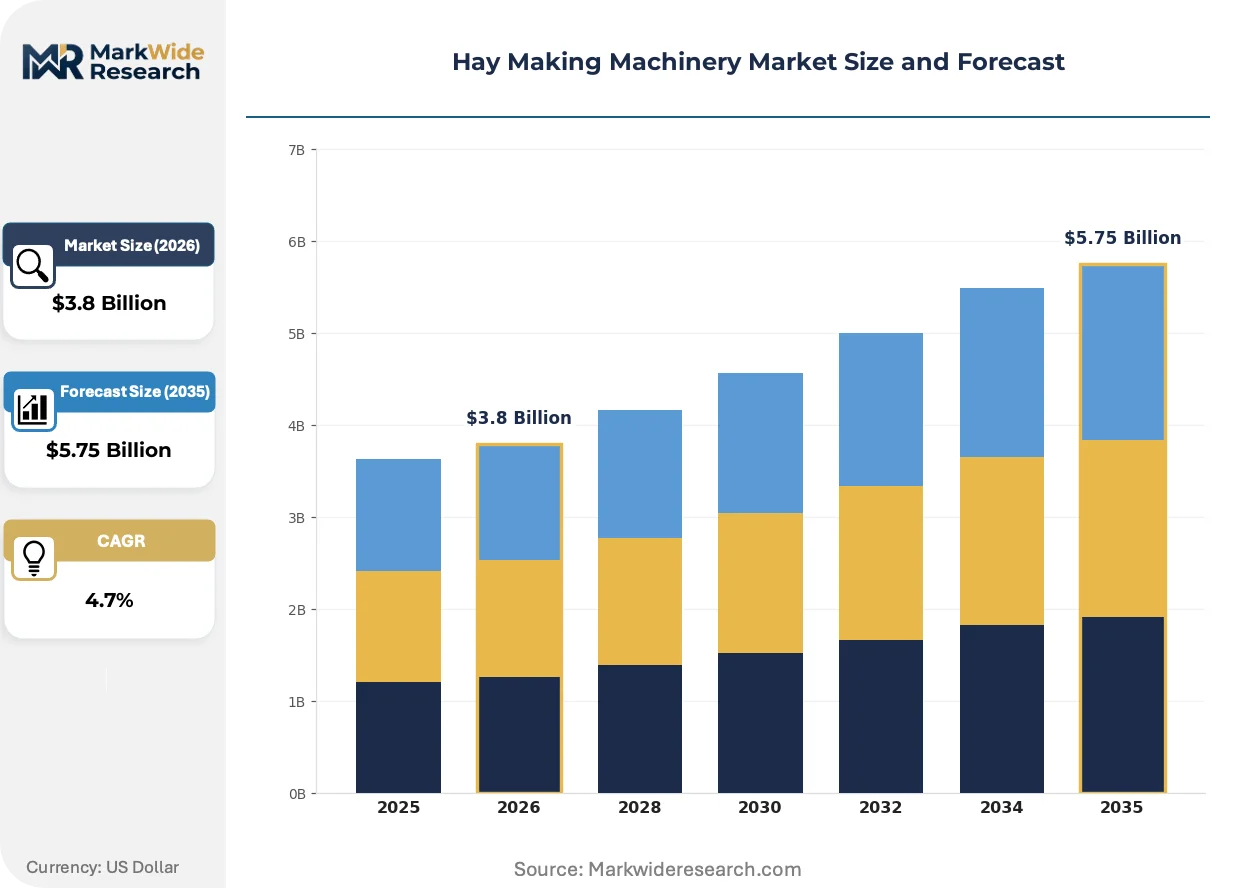
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balers, Mowers, Rakes, Tedders End Use: Agricultural Farms, Commercial Operations, Smallholder Producers, Cooperative Associations Technology: Conventional, Semi-Automatic, Automatic, Electric Installation: Fixed, Mobile, Hired Services, DIY |
| Companies Covered | Kubota Corporation, CLAAS KGaA mbH, Deere & Company, Buhler Industries Inc., Kuhn Group, AGCO Corporation, Vermeer Corporation, Lely Industries N.V., CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hay Making Machinery Market Emerging Trajectories
Precision-ag subscription models and cleaner powertrain architectures are restructuring how hay making machinery is financed, serviced, and replaced across commercial livestock operations.
Bale-weighing and moisture-sensing integration is collapsing the information gap between field cutting and storage decisions. Dairy cooperatives in the Great Plains corridor are adopting these sensor packages at compressed replacement cycles. This technology compression is eliminating post-harvest nutritional loss disputes between growers and feed buyers.
EPA Tier 4 Final standards are forcing engine redesigns that add cost but create regulatory moats against uncertified imports. Equipment manufacturers serving US markets must certify through the EPA's off-road diesel program to maintain fleet financing eligibility. Large square baler producers with certified powertrains are capturing replacement cycles that uncertified competitors cannot access.
After-sales service unbundling is fragmenting traditional dealer revenue models. Equipment buyers in the Midwest United States are separating maintenance contracts from original equipment purchases, pressuring distributors to compete on labor rates and parts availability. This behavioral shift is most visible among commercial hay exporters managing multi-year replacement cycles through captive financing channels.
Hay Making Machinery Market Segmentation
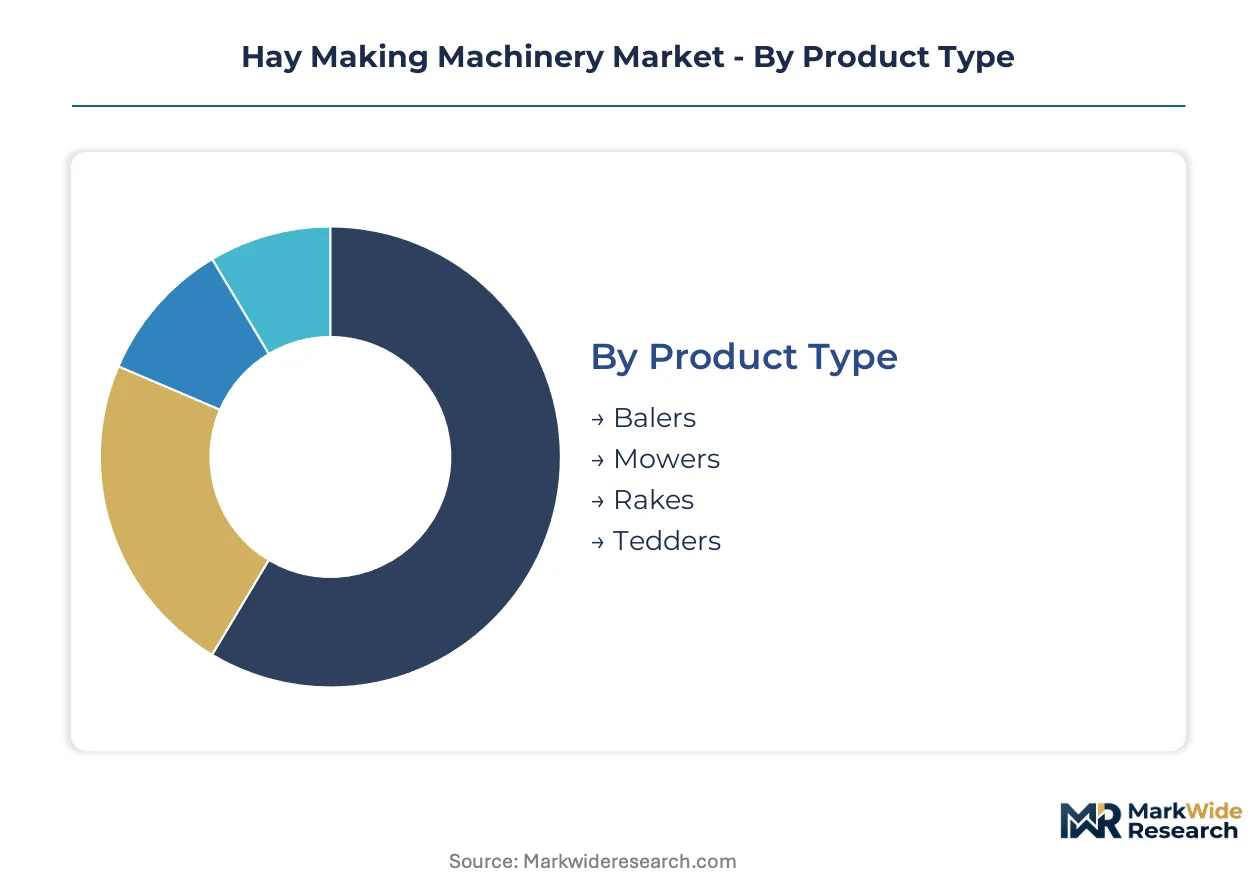
Segmentation in hay making machinery reveals how capital intensity, labor availability, and regulatory pressure split demand across divergent equipment tiers. Understanding these fault lines exposes where margin pools concentrate and which technology transitions will reshape competitive positioning.
Product Type:
Equipment categories diverge sharply by margin structure, replacement frequency, and technical complexity in knotting and conditioning systems.
- Balers:These machines compress dried forage into rectangular or cylindrical bales using twine or wire knotting systems. Large square balers with proprietary knotter technology dominate commercial hay exporter fleets across Nebraska and the Dakotas, where high-density output justifies premium pricing and locked-in parts dependency.
- Mowers:Mower-conditioners cut and crimp forage to accelerate moisture release, with disc and sickle-bar variants serving different field geometries. Dairy cooperatives in the Great Plains corridor favor wide-width disc mowers paired with conditioning rolls that preserve leaf retention in alfalfa stands.
- Rakes:Rotary and wheel rakes gather windrows for baling pickup, with hydraulic folding frames enabling transport between dispersed fields. Demand concentrates among mid-scale operators seeking to minimize leaf loss during consolidation.
- Tedders:Rotary tedders spread and flip cut forage to uniform drying, critical in humid climates where moisture pockets risk spoilage. These units see strongest attachment rates in regions with unpredictable harvest windows.
Balers command the established base. The steepest expansion runs through mower-conditioner bundles sold through cooperative financing channels.
End Use:
Customer scale determines access to fleet financing, precision-ag subscriptions, and emissions-compliant replacement cycles.
- Agricultural Farms:Owner-operated livestock enterprises with 50-500 head herds represent the volume backbone, typically purchasing attached implements through dealer credit programs. These buyers prioritize equipment compatibility with existing tractor hydraulic systems over standalone automation.
- Commercial Operations:Large-scale hay exporters and custom operators run dedicated baling fleets with compressed replacement cycles driven by EPA Tier 4 Final compliance deadlines. Their purchasing power secures multi-year service bundling and telematics subscriptions from captive financing channels.
- Smallholder Producers:Operations under 50 head lack capital access for new equipment, trapping installed base volumes in conventional technology segments and secondary machinery markets.
- Cooperative Associations:Dairy and forage cooperatives aggregate member demand to negotiate fleet discounts and shared machinery pools, particularly across Midwest United States dairy networks securing winter feed supplies.
Commercial operations anchor replacement demand. Cooperative associations are climbing the fastest as aggregated procurement reshapes distributor relationships.
Technology:
Automation tiers separate capital-rich early adopters from constraint-bound legacy operators across divergent regulatory and labor environments.
- Conventional:Manual control systems without GPS guidance or sensor integration dominate Eastern European smallholder fleets where capital constraints block upgrade paths. These machines require operator skill for windrow alignment and bale density management.
- Semi-Automatic:Autosteering, bale-weighing, and moisture-sensing packages address labor scarcity across Midwest dairy cooperatives. This tier gains fastest adoption where retrofit compatibility with mixed-age tractor fleets enables phased investment.
- Automatic:Fully integrated systems with real-time density adjustment and remote monitoring serve commercial hay exporters managing multi-field logistics. These platforms require compatible tractor electronics and dedicated technical support infrastructure.
- Electric:Battery-electric architectures remain pre-commercial but attract development investment following California Air Resources Board precedents signaling state-level off-road diesel restrictions.
Conventional technology holds the installed base majority. Semi-automatic platforms are gaining share fastest as labor economics force mid-scale operator transitions.
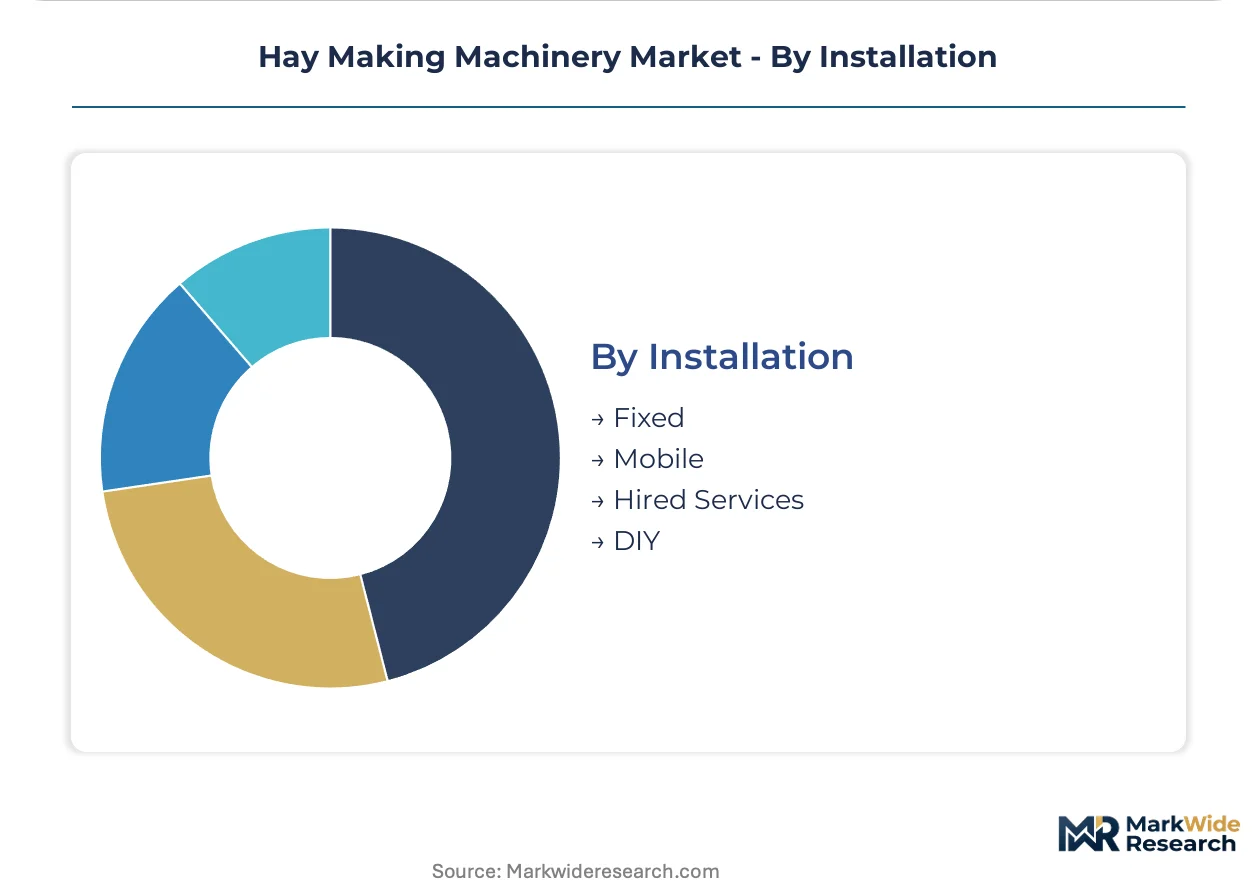
Installation:
Ownership models reflect capital availability, utilization rates, and regional service infrastructure density across fragmented agricultural geographies.
- Fixed:Dedicated on-farm machinery ownership dominates large-field Great Plains operations where annual utilization justifies depreciation schedules. These installations require on-site maintenance capability and parts inventory.
- Mobile:Equipment relocated between owned and leased fields serves diversified crop-livestock operations with seasonal forage demands. Transport logistics and road-legal configuration requirements shape purchasing specifications.
- Hired Services:Custom operators provide baling and mowing on per-acre or per-bale contracts, enabling smallholders to access high-capacity equipment without capital commitment. This model concentrates in regions with established custom operator networks.
- DIY:Self-built or modified equipment persists among hobby farms and extreme cost-constrained operations, though safety certification gaps limit resale and insurance options.
Fixed installation represents the revenue core. Hired services are expanding most quickly as asset-light strategies penetrate capital-constrained producer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final standards and EU Stage V frameworks are accelerating equipment replacement cycles across major agricultural economies, with dairy cooperatives and commercial hay exporters driving concentrated demand in specific field-geometry corridors.
United States
Dairy cooperatives across Nebraska and the Dakotas are expanding fleet purchases of large square balers to secure winter feed supplies. EPA Tier 4 Final emissions standards for off-road diesel engines are compressing replacement schedules among commercial hay exporters. The Great Plains corridor concentrates cattle operations on large-field geometries that favor high-capacity mower-conditioners.
Germany
Engineering-intensive manufacturers anchor European supply chains for knotter technology and conditioning systems. EU Stage V emissions frameworks are forcing powertrain redesigns that add cost but create regulatory moats against uncertified imports. The Baden-Württemberg industrial cluster hosts precision-agriculture development centers serving Central European forage markets.
France
Alfalfa production regions in the Centre-Val de Loire are adopting moisture-sensing baler packages to minimize post-harvest nutritional loss. The country's national agricultural regulator enforces machinery safety standards that govern export eligibility to North African markets. Dairy cooperatives in Normandy are aggregating procurement to negotiate fleet discounts on high-density balers.
Canada
Prairie provinces with extended haying windows are prioritizing tedder and rake combinations that accelerate uniform drying. Health Canada and PMRA oversee equipment safety certification that aligns with ISO 4254 standards for operator protection. Custom operator networks in Alberta are expanding hired-service models that enable smallholders to access high-capacity equipment.
Australia
Export-oriented hay producers in New South Wales and Victoria are integrating bale-weighing systems to eliminate nutritional value disputes with Asian feed buyers. The TGA and national agricultural safety frameworks govern guarding standards that shape import eligibility for European and North American equipment. Irrigation-dependent forage regions are compressing replacement cycles to maintain compliance with export market quality specifications.
Hay Making Machinery Market Vendor Landscape
On the supply side, the industry is tiered between integrated agricultural equipment conglomerates and specialized forage machinery fabricators. The vendor base separates into three strategic archetypes: diversified full-line manufacturers with captive financing channels, precision-agriculture specialists with proprietary sensor integration, and regional fabricators serving cost-constrained smallholder segments. Dominant competitive moves include portfolio diversification into precision-ag subscription services and backward integration into powertrain certification programs that satisfy EPA and EU emissions frameworks.
Within the diversified full-line tier, Deere & Company and CNH Industrial exemplify manufacturers with integrated financing channels that lock in multi-year replacement cycles. CLAAS KGaA mbH occupies a position among precision-agriculture specialists with proprietary knotter technology. These three companies represent distinct competitive positions without implying specific strategic actions or market shares beyond their archetype functions.
| Leading Market Players |
|---|
| Kubota Corporation |
| CLAAS KGaA mbH |
| Deere & Company |
| Buhler Industries Inc. |
| Kuhn Group |
| AGCO Corporation |
| Vermeer Corporation |
| Lely Industries N.V. |
| CNH Industrial |
| Others |
Supply Flow & Price Mechanics
The Union Pacific rail corridor from Omaha to Chicago carries imported knotter assemblies and hydraulic components from European engineering clusters, with freight cost volatility compressing margin pools for distributors serving Great Plains dairy cooperatives while EPA Tier 4 Final certification tiers create price spreads between compliant and non-compliant equipment flows.
Pricing Analysis
Certification level creates the primary spread between EPA Tier 4 Final-compliant large square balers and pre-compliant secondary market units. Three-tier pricing structure across premium certified, standard transitional, and economy conventional levels segments buyers by financing access. Pricing pressure stems from engine cost inflation pushing mid-scale operators toward cooperative fleet pools. Smallholder producers in Eastern Europe exhibit highest price sensitivity, while commercial hay exporters with captive financing channels absorb premium tier markups.
Supply Chain Analysis
Export-control regimes on precision sensor technology limit flows of GPS guidance modules from German engineering centers to non-integrated manufacturers. Component concentration rests in Germany for knotter systems, Japan for compact powertrains, and the United States for emissions-certified diesel engines. Raw material dependencies include high-tensile steel for baler frames, synthetic twines for knotting, and semiconductor chips for autosteering integration. Single-source vulnerability concentrates in proprietary knotter technology licensing. Distribution runs through captive financing channels and rural cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-ag subscription services are expanding faster than hardware sales as dairy cooperatives bundle telematics with fleet financing, creating recurring revenue layers that reshape competitive economics.
For Market Incumbents: Harden defensible positions by securing backward integration into EPA-certified powertrain production and locking multi-year replacement cycles through exclusive service bundling. Electric platform development threatens early movers who delay architecture investment. Certification moats against uncertified imports anchor margin defense. For New Entrants and Emerging Players: Mid-scale commercial operations in underbanked agricultural regions represent the most penetrable entry point for attached mower-conditioner sales through rural cooperative credit programs. Secondary machinery markets for conventional technology segments offer asset-light service models. Target retrofit compatibility with mixed-age tractor fleets as the primary go-to-market wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized forage machinery divisions lacking precision-ag integration. Long-term viability hinges on subscription attach rates exceeding hardware depreciation cycles. Monitor California Air Resources Board precedent adoption across additional state jurisdictions as the inflection signal for electric platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Ag Subscription Launch | Attaches recurring revenue to Deere and CNH fleet financing channels. |
| EPA Powertrain Certification Investment | Creates regulatory moats blocking uncertified import competition. |
| Rural Cooperative Channel Expansion | Enables Kubota compact tractor bundles in underbanked regions. |
| Electric Architecture Development | Positions early movers for California Air Resources Board compliance. |
| Proprietary Knotter Technology Acquisition | Locks replacement part dependency in high-density baler segments. |
Methodological Framework
A spread of perspectives from fleet managers at dairy cooperatives, aftermarket service directors at dealer networks, procurement leads at commercial hay exporters, and regulatory compliance officers at engine manufacturers converged on the working assumptions. Primary field interviews combined with secondary validation from EPA certification databases, USDA agricultural census tract data, ISO 4254 safety standard filings, and equipment financing disclosure records. Bottom-up unit economics triangulated against top-down market sizing.
Demand-supply balance modeling across the projection horizon segmented by product type, technology tier, end-use scale, and installation model. The analytical framework incorporated cattle density geospatial data, field geometry suitability indices, and replacement cycle compression factors from emissions deadlines. CAGRs derived from regression against historical equipment shipment patterns and financing origination volumes. Industry-specific inputs included alfalfa acreage forecasts and cooperative membership aggregation trends.
Practitioners should monitor state-level off-road diesel restriction adoptions and electric platform cost parity milestones for early signals. Forecasts reflect assumptions on regulatory compliance timelines and labor scarcity persistence. Material shifts in federal emissions enforcement intensity or battery-electric total cost of ownership would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market