
 Asia-Pacific Utility Tractor Market | 2026-2036
Asia-Pacific Utility Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Utility Tractor Market Outlook
Electrification of powertrain architectures is rewriting component sourcing and assembly priorities for utility tractor manufacturers across the Asia-Pacific. Kubota Agricultural Machinery leverages its Japanese engineering base to sustain hybrid-electric R&D programs targeting paddy-field applications. Mahindra & Mahindra Ltd anchors South Asian volume through extensive dealer networks spanning India's rural districts. Yanmar Co Ltd competes on compact diesel-electric platforms optimized for terraced hillside operations in Southeast Asia.
Asia-Pacific utility tractors are wheeled agricultural machines typically rated between 40 and 150 horsepower, designed for draft work, material handling, and powered implement operation across small-to-medium landholdings. These machines integrate three-point hitch systems, power take-off shafts, and hydrostatic transmissions to enable tillage, seeding, and transport functions on diversified terrain. Compact tractors occupy the fastest-expanding margin pool as orchard and vineyard operators in Australia's Murray-Darling Basin and China's Shandong Province shift from manual labor to mechanized canopy management. Standard tractors in the 50-100 HP range dominate absolute unit volumes across India's wheat-rice belt and Vietnam's Mekong Delta, where tillage intensity and rental service models sustain fleet turnover. Specialty tractors remain a niche but defend premium pricing in Japan's mountainous prefectures, where ultra-narrow track widths and low-center-of-gravity designs command specification premiums from rice-farming collectives.
India's Central Pollution Control Board and Ministry of Road Transport enforce Bharat Stage emission norms that escalate engine compliance costs for domestic assemblers, while China's Ministry of Ecology and Environment applies GB standards that restrict diesel particulate thresholds for equipment sold in the Yangtze River Economic Belt. Australia's Department of Agriculture imposes biosecurity wash-down protocols on imported used tractors that constrain secondary market supply from Pacific Island trade corridors. Stakeholders must monitor how Indonesia's forthcoming agricultural mechanization roadmap and Thailand's Board of Investment incentives for farm machinery assembly reshape competitive entry points across mainland Southeast Asia.
Market Dynamics
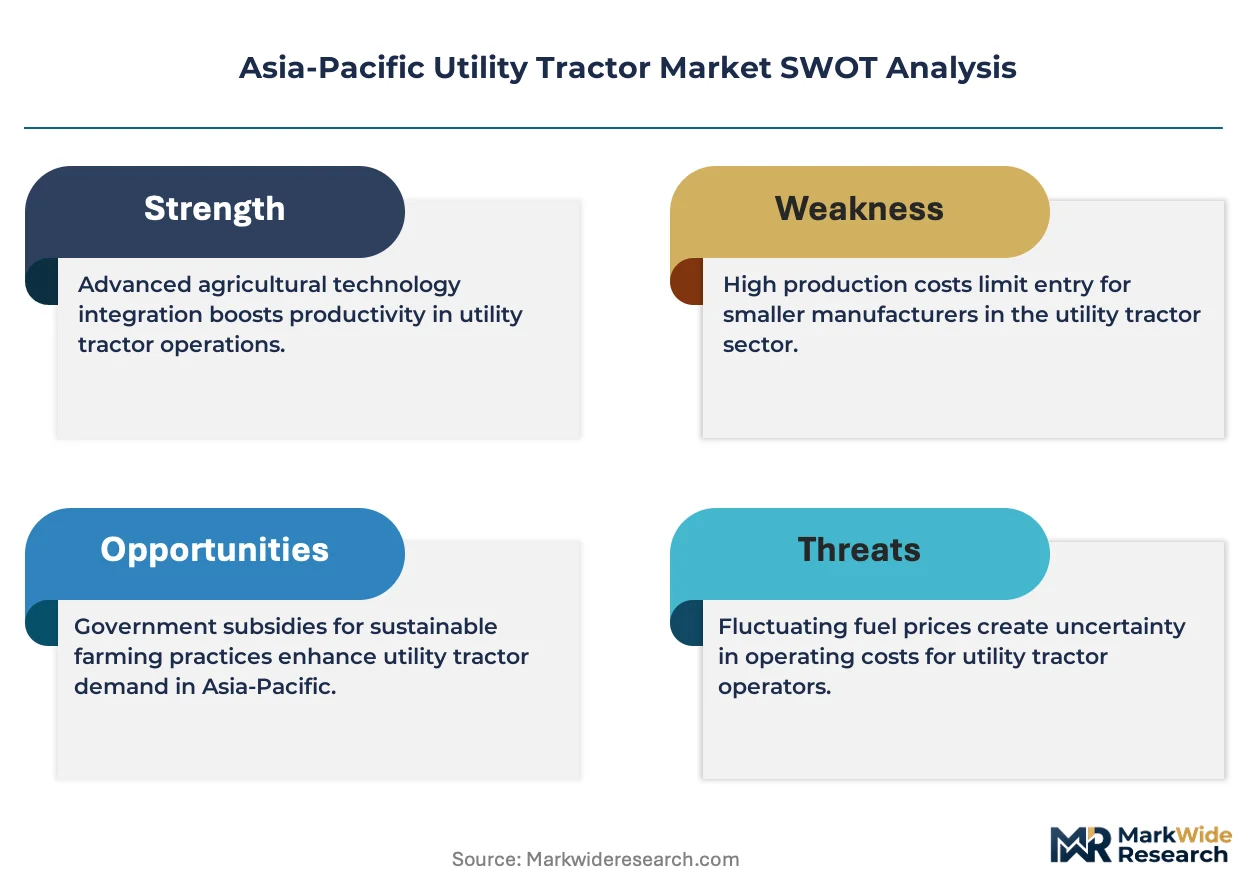
The Bharat Stage emission norms enforced by India's Central Pollution Control Board are forcing domestic assemblers to re-engineer powertrain architectures, compressing margins while accelerating electrification roadmaps across the Indo-Gangetic Plain.
Growth Catalysts
- State-level farm equipment subsidies:India's state governments disburse capital grants and interest-rate concessions that lower acquisition barriers for mid-HP utility tractors in wheat-rice belt districts.
- Hybrid-electric R&D programs:Japanese engineering centers advance paddy-field-optimized powertrains that reduce diesel particulate exposure for operators in flooded cultivation zones.
- Smallholder mechanization cooperatives:Vietnam's Mekong Delta and Indonesia's Java collectives pool capital to acquire rental-service fleets, sustaining replacement cycles beyond individual farm economics.
Market Restraints
- Engine compliance cost escalation:Bharat Stage and China's GB standards impose particulate-filter and after-treatment hardware that adds material cost to diesel powertrains.
- Critical component supply concentration:High-pressure common-rail injection systems and turbocharger assemblies concentrate among a narrow supplier base in Japan and Germany.
- Biosecurity wash-down protocols:Australia's Department of Agriculture inspection requirements constrain used-tractor import volumes from Pacific Island trade corridors.
Strategic Opportunities
- Thailand's Board of Investment incentives:Tax holidays and import-duty exemptions for farm machinery assembly operations attract greenfield manufacturing investments.
- Orchard and vineyard mechanization:Australia's Murray-Darling Basin and China's Shandong Province operators shift from manual labor to compact tractors for canopy management.
- Diesel-to-electric powertrain convergence:Battery-electric prototypes at Indian agricultural institutes demonstrate viability for short-duty-cycle land preparation tasks.
Industry Challenges
- Power electronics technician scarcity:Rural dealer networks lack trained personnel to diagnose inverter and motor-control faults in emerging electric platforms.
- Homologation timeline compression:Concurrent Bharat Stage and GB standard updates force simultaneous certification campaigns across multiple test facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Utility Tractor Market |
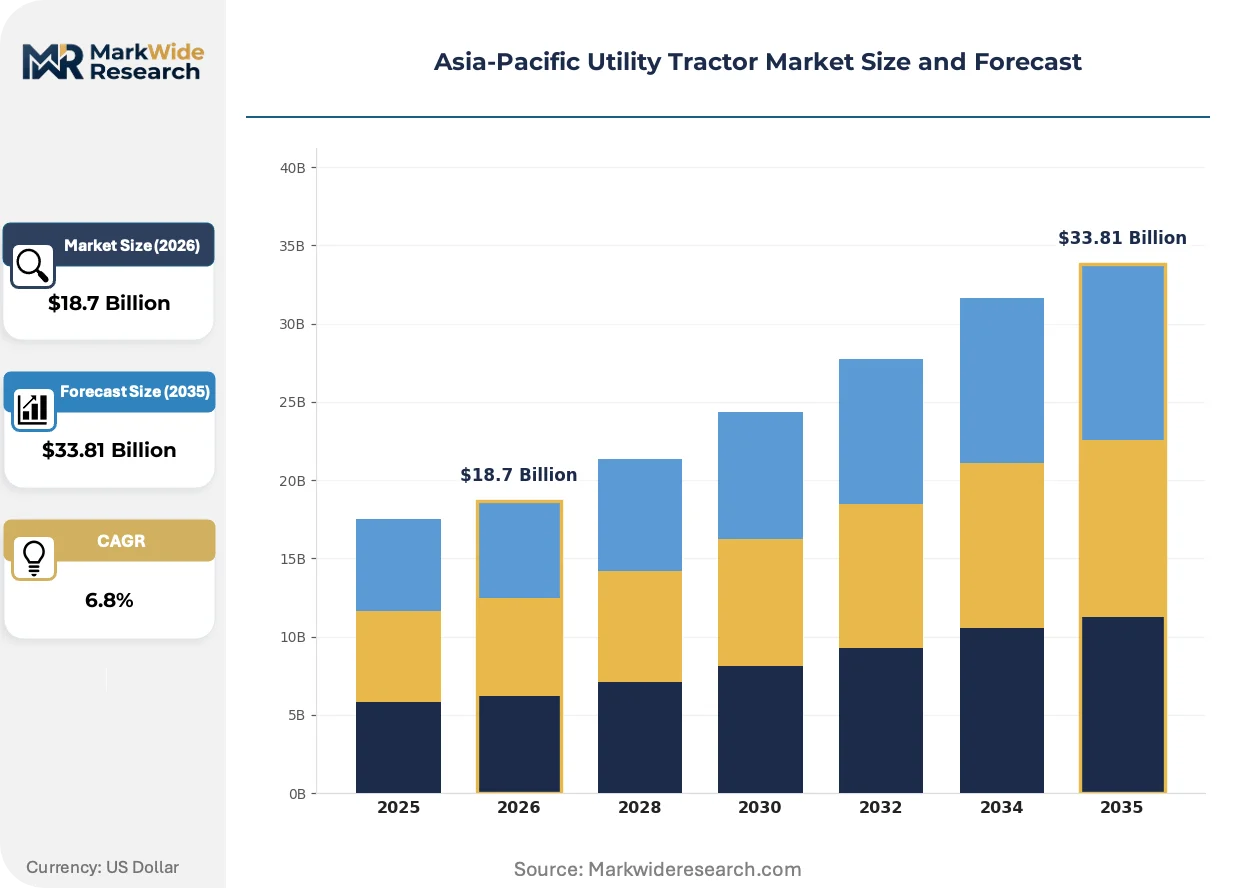
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tractors, Compact Tractors, Specialty Tractors, Utility Tractors End User: Agriculture, Landscaping, Construction, Government Power Rating: Below 50 HP, 50-100 HP, 100-150 HP, Above 150 HP Deployment: On-farm, Agricultural Retail, Rental Services, Export |
| Companies Covered | Mahindra & Mahindra Ltd, Kubota Agricultural Machinery, Deere & Company, AGCO Corporation, CNH Industrial N.V., Escorts Limited, Yanmar Co Ltd, International Tractors Limited, TAFE Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Utility Tractor Market Strategic Shifts
Electrification of utility tractor architectures is collapsing traditional component sourcing patterns while regulatory pressure on diesel emissions intensifies specification divergence across national markets.
Permanent-magnet synchronous motors paired with lithium-iron-phosphate battery packs are collapsing the cost-performance gap between electric and diesel powertrains for sub-75 HP applications. Japanese and South Korean battery suppliers are securing volume commitments from paddy-field equipment specialists. This technology shift is collapsing the historical dominance of multi-cylinder diesel engines in orchard and vineyard segments.
China's Ministry of Ecology and Environment applies GB standards that restrict diesel particulate thresholds for equipment sold in the Yangtze River Economic Belt. Domestic assemblers must revalidate engine families or source compliant powertrains from licensed suppliers. Compact tractor segments in Jiangsu and Zhejiang provinces face the steepest compliance cost absorption.
Equipment-as-a-service contracting is displacing outright purchase among Australian broadacre operators and Vietnamese rice-farming collectives. Rental-service providers bundle maintenance and seasonal availability guarantees into per-hectare pricing. This procurement evolution concentrates fleet ownership among capitalized distributors in Queensland and the Mekong Delta.
Asia-Pacific Utility Tractor Market Segmentation
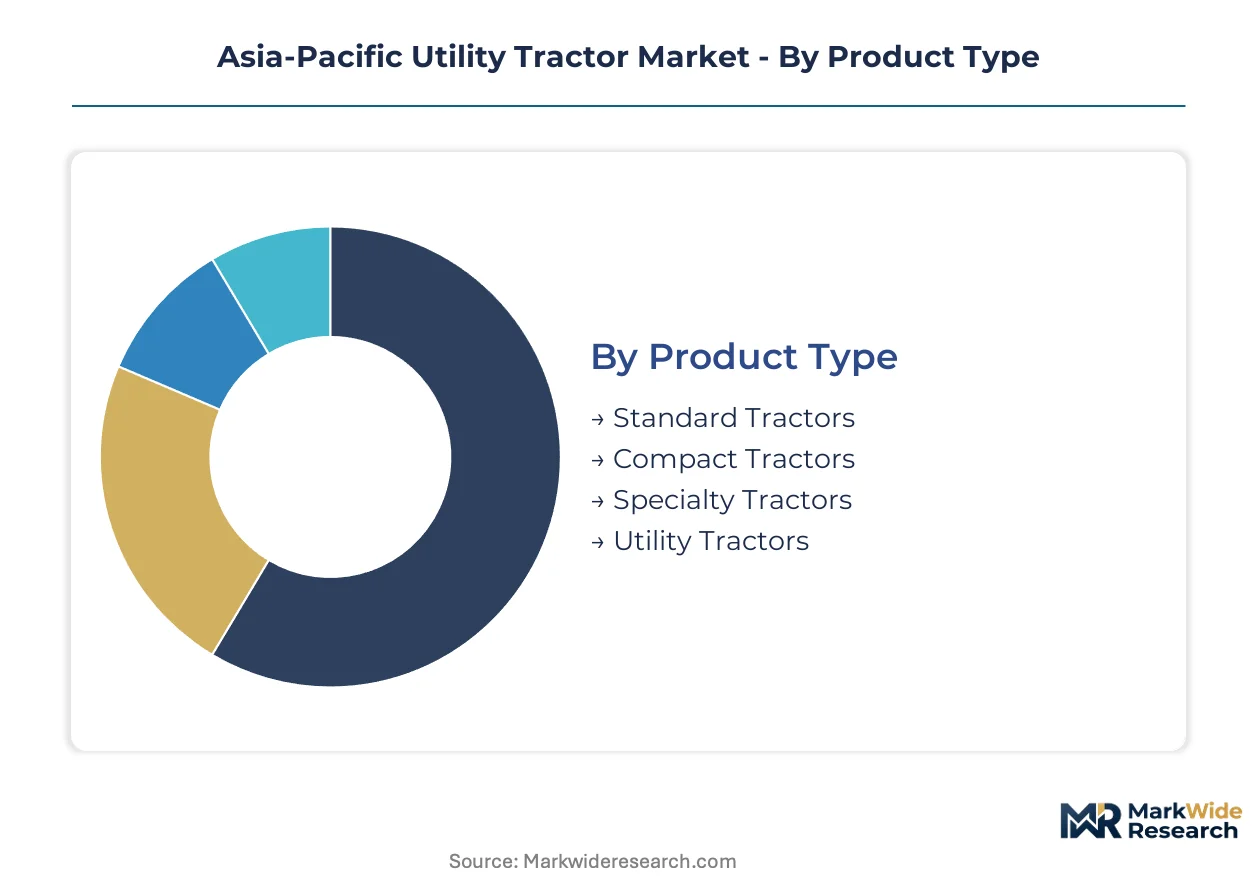
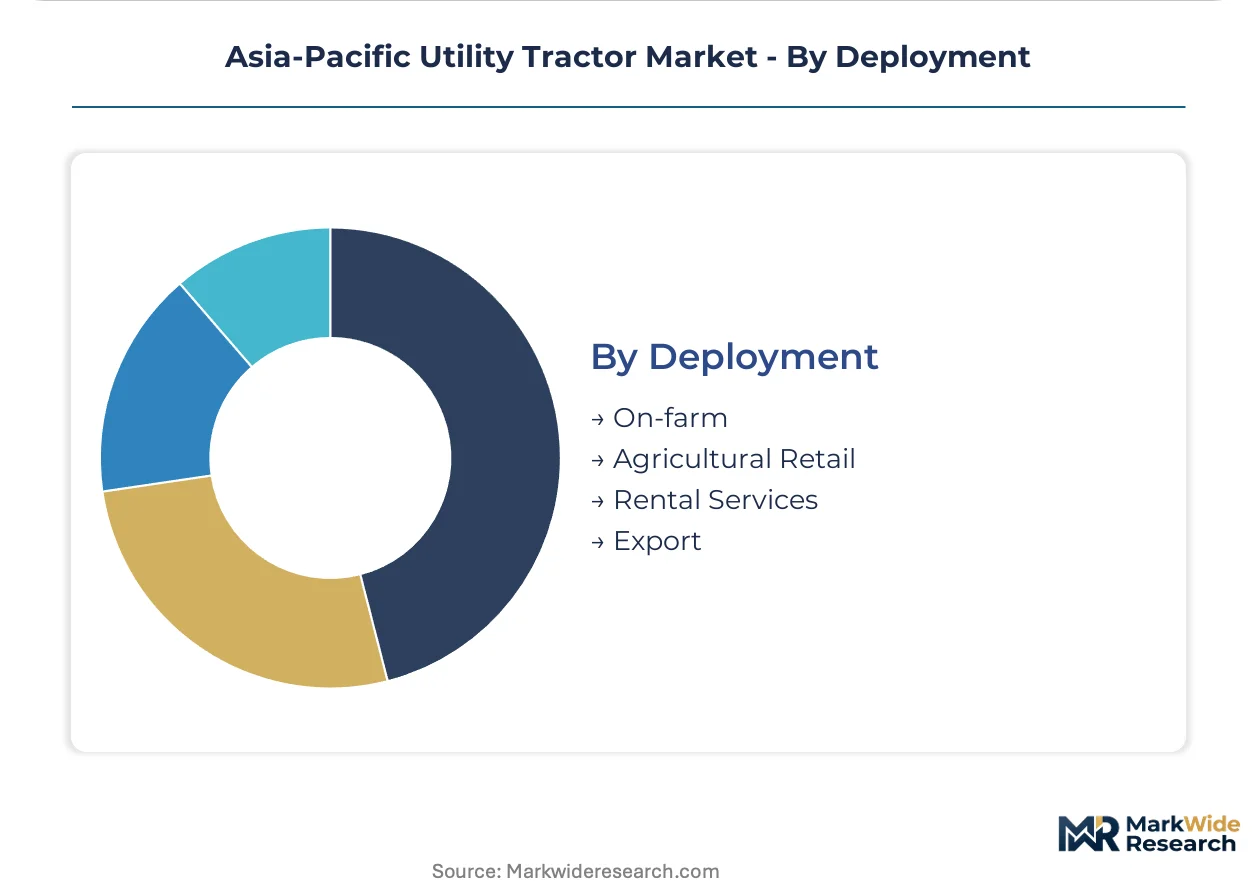
Segmentation in the Asia-Pacific utility tractor market reveals divergent service and support requirements across power classes and deployment models. Rental-service operators demand rapid parts availability and field technician dispatch that reshape distributor network design across India's wheat-rice belt and Vietnam's Mekong Delta.
Product Type:
After-sales-service intensity varies sharply across product architectures, with hydrostatic transmission repairs and precision guidance calibration driving recurring revenue concentration for dealer workshops.
- Standard Tractors:These machines occupy the 50-100 HP range with mechanical transmissions and three-point hitch systems optimized for draft tillage and primary cultivation. Demand concentrates across India's Indo-Gangetic Plain, where state-level farm equipment subsidies and irrigation-linked cropping intensity sustain replacement cycles among smallholder cooperatives.
- Compact Tractors:Orchard and vineyard operators in Australia's Murray-Darling Basin and China's Shandong Province are shifting from manual labor to these sub-40 HP machines for mechanized canopy management and inter-row cultivation.
- Specialty Tractors:Ultra-narrow track widths and low-center-of-gravity designs serve Japan's mountainous prefectures.
- Utility Tractors:General-purpose configurations balance power take-off flexibility with transport efficiency for diversified smallholdings.
Standard tractors hold the largest share; momentum sits with compact tractors.
End User:
Customer procurement sophistication separates institutional buyers from individual operators, with government tenders demanding extended warranty terms and documented maintenance histories.
- Agriculture:Smallholder farming cooperatives in Southeast Asia are expanding mechanized land preparation, pooling capital to acquire rental-service fleets that sustain replacement cycles beyond individual farm economics in Vietnam's Mekong Delta and Indonesia's Java.
- Landscaping:Municipal parks departments and golf course operators in Australia's capital cities specify low-noise diesel-electric hybrids for urban proximity work.
- Construction:Material handling and site preparation tasks utilize mid-HP utility platforms with loader attachments.
- Government:Agricultural extension services and state farm corporations procure through centralized tender processes with domestic content requirements.
Agriculture dominates absolute volumes; landscaping is gaining share fastest.
Power Rating:
Engine displacement tiers align with distinct component supply chains and emission compliance cost structures across Bharat Stage and China's GB standards.
- Below 50 HP:Single-cylinder and twin-cylinder engines serve terraced hillside operations in Southeast Asia with minimal after-treatment hardware.
- 50-100 HP:Four-cylinder diesels with turbocharging and common-rail injection dominate India's wheat-rice belt, where particulate-filter compliance adds material cost for domestic assemblers.
- 100-150 HP:Six-cylinder configurations support heavy tillage and transport functions on medium landholdings.
- Above 150 HP:Premium powertrains serve broadacre operations and commercial rental fleets with extended duty cycles.
50-100 HP holds the largest share; below 50 HP is expanding most quickly.
Deployment:
Channel structure determines inventory financing exposure and residual value risk allocation across the equipment lifecycle.
- On-farm:Individual owner-operators in India's rural districts purchase through dealer networks with state-subsidized credit.
- Agricultural Retail:Distributor showrooms in Thailand and Indonesia stock mid-HP inventory for immediate delivery.
- Rental Services:Equipment-as-a-service contracting bundles maintenance and seasonal availability guarantees into per-hectare pricing, concentrating fleet ownership among capitalized distributors in Queensland and the Mekong Delta.
- Export:Secondary market supply from Pacific Island trade corridors faces Australia's biosecurity wash-down protocols that constrain import volumes.
On-farm deployment holds the largest share; rental services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder cooperatives and rental-service operators concentrate demand across distinct national agricultural zones, with state subsidy programs and emission compliance timelines fragmenting procurement patterns.
India
State-level farm equipment subsidies in Punjab and Haryana sustain replacement cycles for mid-HP utility tractors among wheat-rice belt cooperatives. The Central Pollution Control Board enforces Bharat Stage emission norms that escalate engine compliance costs for domestic assemblers. Mahindra & Mahindra Ltd anchors volume through extensive dealer networks spanning rural districts of Uttar Pradesh and Bihar.
China
Orchard operators in Shandong Province are shifting from manual labor to compact tractors for mechanized canopy management. The Ministry of Ecology and Environment applies GB standards that restrict diesel particulate thresholds for equipment sold in the Yangtze River Economic Belt. Jiangsu and Zhejiang province assemblers face steep compliance cost absorption in compact tractor segments.
Japan
Rice-farming collectives in mountainous prefectures command specification premiums for ultra-narrow track width designs. METI supports hybrid-electric R&D programs targeting paddy-field applications through domestic engineering centers. Kubota Agricultural Machinery leverages its Japanese engineering base to sustain electrification roadmaps for flooded cultivation zones.
Vietnam
Mekong Delta smallholder cooperatives pool capital to acquire rental-service fleets that sustain replacement cycles beyond individual farm economics. The Ministry of Agriculture and Rural Development promotes mechanization roadmaps that reshape competitive entry points for utility tractor distributors. Can Tho and An Giang provinces concentrate fleet ownership among capitalized rental-service providers.
Australia
Broadacre operators in Queensland and New South Wales are adopting equipment-as-a-service contracting that bundles maintenance into per-hectare pricing. The Department of Agriculture imposes biosecurity wash-down protocols on imported used tractors that constrain secondary market supply from Pacific Island trade corridors. Murray-Darling Basin orchard operators specify low-noise diesel-electric hybrids for urban proximity work.
Asia-Pacific Utility Tractor Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three strategic archetypes: diversified agricultural conglomerates with captive distribution networks, compact equipment specialists with paddy-field optimization capabilities, and broadacre machinery providers with rental-service bundling expertise. Dominant competitive moves include geographic expansion through state-level subsidy alignment and technology licensing for emission-compliant powertrain architectures.
Among India-based diversified manufacturers, Mahindra & Mahindra Ltd and Escorts Limited occupy positions anchoring South Asian volume through rural dealer network density. Kubota Agricultural Machinery and Yanmar Co Ltd represent the compact-specialist archetype with Japanese engineering heritage. Deere & Company exemplifies the broadacre-rental bundling model in Australian and Southeast Asian deployment channels.
| Leading Market Players |
|---|
| Mahindra & Mahindra Ltd |
| Kubota Agricultural Machinery |
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Escorts Limited |
| Yanmar Co Ltd |
| International Tractors Limited |
| TAFE Ltd |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Zhejiang province manufacturing clusters anchor diesel powertrain assembly capacity for compact tractor segments, with Bharat Stage and GB standard compliance costs transmitting directly into OEM pricing power across India's wheat-rice belt and China's Yangtze River Economic Belt.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate procurement between Indian domestic assemblers and tier-1 suppliers. Three-tier pricing structure across premium, standard, and economy levels separates emission-compliant powertrains from basic mechanical transmissions from entry-grade single-cylinder platforms. Cost compression in the below-50 HP segment is intensifying because common-rail injection and particulate-filter hardware add material burden. Smallholder cooperatives in Vietnam's Mekong Delta exhibit highest price sensitivity, while Australian broadacre rental-service operators demonstrate lowest sensitivity due to bundled maintenance contracting.
Supply Chain Analysis
Contract manufacturing for high-pressure common-rail systems and turbocharger assemblies concentrates among Japanese and German tier-1 suppliers, with foundry and machining capacity tethered to Nagoya and Stuttgart industrial zones. Power electronics for emerging electric platforms draws from South Korean and Chinese battery cell suppliers, while precision transmission castings feed from Indian and Thai metalworking clusters. Single-source vulnerability in semiconductor-based engine control modules creates exposure to automotive-sector demand surges. Distribution runs through Mahindra and Escorts dealer networks in rural India, Kubota's captive channels in Japan, and Deere's rental-service bundling operations in Queensland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific utility tractor market fragmentation creates opportunity pockets as electrification roadmaps and emission compliance timelines diverge across national regulatory clusters, opening niches for specialized powertrain providers and regional assembly operations.
For Market Incumbents: Insulate core margin pools in India's 50-100 HP segment by deepening backward integration into transmission casting and final assembly operations in Uttar Pradesh and Bihar. Accelerate certification investment for Bharat Stage VI powertrain architectures ahead of regulatory enforcement timelines. Counter emerging electric-platform threats through captive hybrid-electric R&D programs targeting paddy-field applications.
For New Entrants and Emerging Players: Establish a beachhead in Thailand's Board of Investment incentive zones for farm machinery assembly, leveraging tax holidays and import-duty exemptions to bypass established dealer network barriers. Target Indonesia's Java-based smallholder mechanization cooperatives with compact diesel-electric platforms optimized for terraced hillside operations. Pursue equipment-as-a-service contracting models that bundle maintenance into per-hectare pricing, mirroring Vietnamese Mekong Delta rental-service structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural conglomerates seeking to divest non-core tractor assembly operations amid margin compression from emission compliance costs. Long-term viability hinges on electric-platform transition readiness and state-level subsidy alignment capabilities. Monitor Indonesia's forthcoming agricultural mechanization roadmap publication as inflection signal for competitive entry point reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Powertrain Development | Kubota's paddy-field-optimized R&D programs reduce diesel particulate exposure for flooded cultivation operators. |
| State-Level Subsidy Alignment | Mahindra's dealer network density in Punjab and Haryana captures capital grant disbursements for wheat-rice belt cooperatives. |
| Equipment-as-a-Service Contracting | Queensland rental-service providers bundle maintenance guarantees into per-hectare pricing for broadacre operators. |
| Emission Compliance Certification | Domestic assemblers revalidate engine families against concurrent Bharat Stage and GB standard updates. |
| Thailand Board of Investment Entry | Greenfield manufacturing investments leverage tax holidays for farm machinery assembly operations. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with tractor OEM procurement directors, agricultural cooperative fleet managers, state agricultural department subsidy administrators, and powertrain component suppliers; combined with secondary validation against Ministry of Agriculture mechanization roadmaps, Central Pollution Control Board emission compliance filings, customs trade data for engine and transmission imports, and SEC 10-K disclosures from listed agricultural equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down addressable landholding calculations across the Indo-Gangetic Plain, Mekong Delta, and Murray-Darling Basin.
Forecast inputs span power rating tiers, deployment models, and national regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include product architecture, end-use application, horsepower class, and channel structure. CAGRs derived from replacement cycle analysis, subsidy program longevity assessments, and electrification adoption curve projections. Industry-specific inputs incorporate irrigation-linked cropping intensity indices and rental-service fleet penetration rates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, rural credit availability, and state fiscal capacity would shift the trajectory. Forecasts reflect assumptions on subsidy continuity and emission standard enforcement cadence. Quarterly review of state-level equipment grant disbursement rates and prototype demonstration outcomes at Indian agricultural institutes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Hay Making Machinery Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Agricultural Machinery Market