
 Mexico Agricultural Machinery Market | 2026-2036
Mexico Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Agricultural Machinery Market Foresight
Water scarcity protocols under Mexico's National Water Commission (CONAGUA) are shifting demand toward drip-compatible tractors and precision irrigation systems. Deere & Company leverages its Monterrey distribution network to dominate premium tractor segments in northern Mexico. Kubota Corporation anchors its position among mid-size fruit and vegetable growers through specialized compact equipment. AGCO Corporation competes via localized assembly operations that reduce import duty exposure for harvester lines.
Agricultural machinery encompasses self-propelled and towed equipment engineered to specifications such as 50–400 horsepower ratings, three-point hitch compatibility, and ISOBUS electronic control interfaces, performing soil tillage, planting, crop protection, and grain handling functions. Tractors sustain the largest revenue share as foundational fleet assets across Mexican row-crop and specialty operations. Precision farming technology is expanding fastest as GPS-guided autosteer and variable-rate application systems penetrate commercial operations seeking input optimization. Harvesters occupy concentrated margin pools in high-value export crops including berries, tomatoes, and avocados where mechanization reduces perishable losses.
SEMARNAT environmental certifications govern engine emissions standards for equipment sold in Mexico, while NOM-044-SEMARNAT-2014 diesel particulate limits shape manufacturer product configurations. The Secretariat of Agriculture (SADER) coordinates FIRA-backed machinery financing that channels demand toward domestically assembled units meeting local content thresholds. Stakeholders must monitor evolving biosecurity requirements for cross-border equipment movement and align procurement timelines with peso-denominated credit cycles.
Market Dynamics
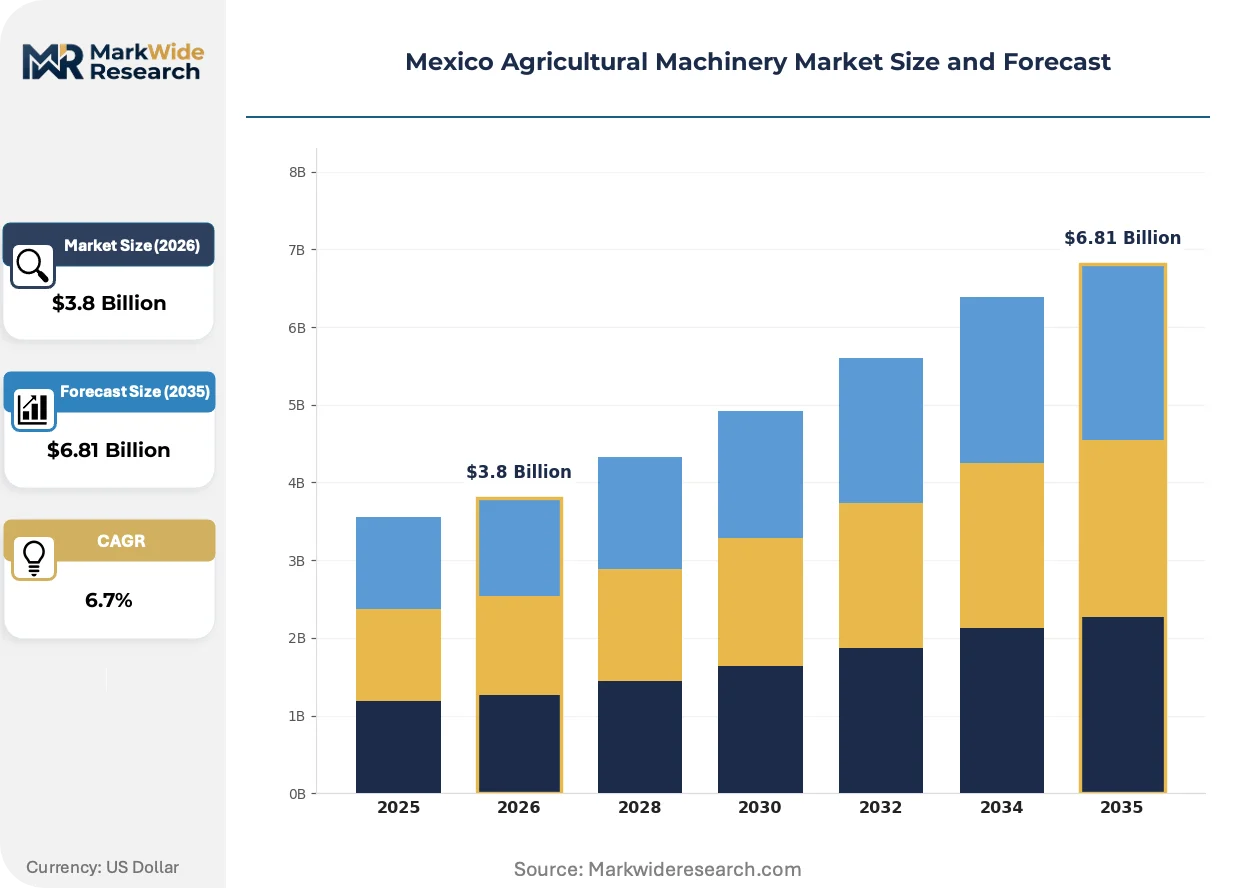
FIRA-backed financing channels are accelerating mechanization across Mexico's irrigated corridors, while CONAGUA water scarcity mandates force equipment replacement cycles toward precision-compatible platforms.
Growth Catalysts
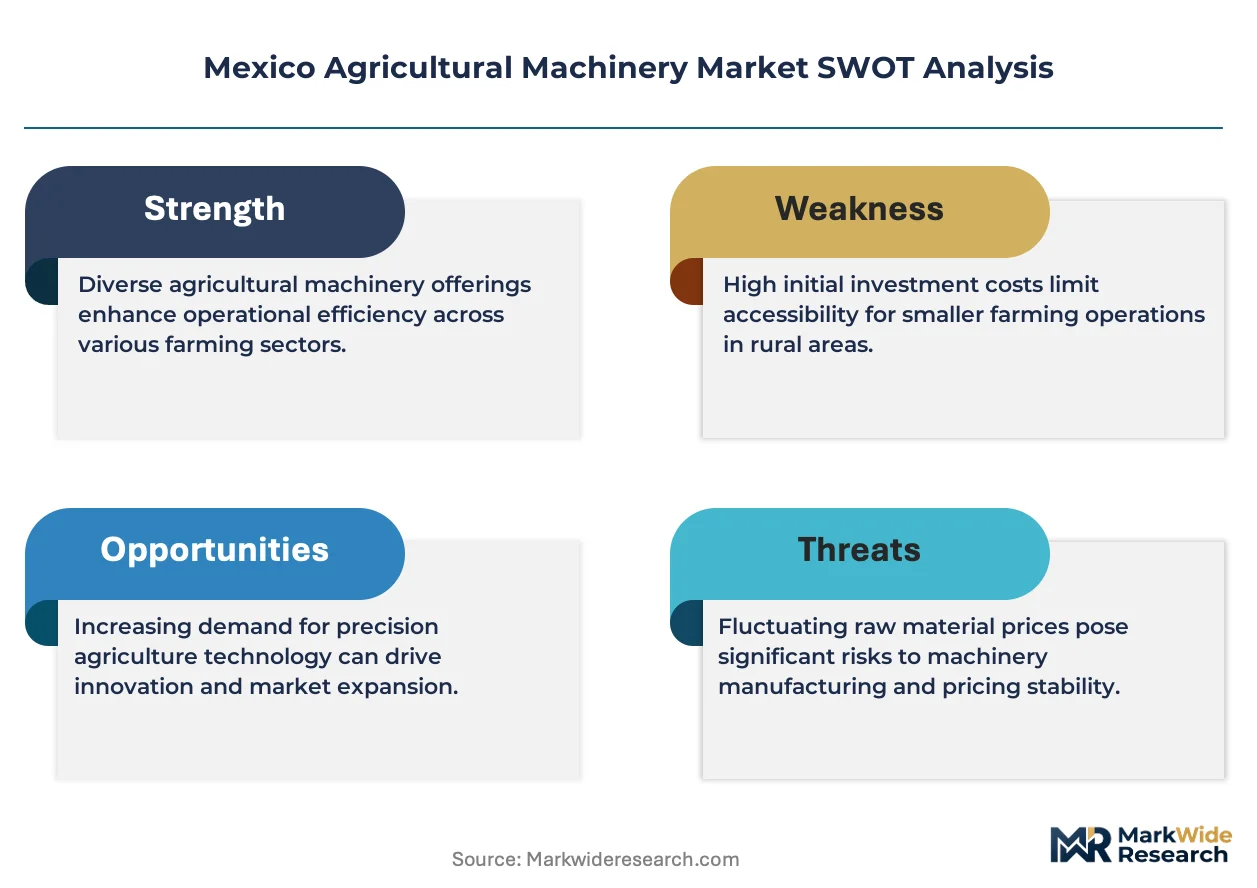
- SEMARNAT Emissions Standards:Tier-compliant engine upgrades are unlocking replacement demand as older fleets face operational restrictions in high-altitude production zones.
- Bajío Irrigation Infrastructure:Expansion of pressurized water networks in Guanajuato and Querétaro is pulling demand for compatible tillage and planting systems.
- Telematics Integration:ISOBUS-enabled fleet management platforms are reducing input waste and justifying premium equipment acquisition for cost-conscious growers.
Market Restraints
- Steel Price Volatility:Chassis and implement fabrication costs fluctuate with global metallurgical input markets, compressing assembler margins on fixed-price contracts.
- Import Dependency:Powertrain and hydraulic component supply concentrates in Asian manufacturing clusters, exposing Mexican distributors to extended lead times and currency mismatch.
- Credit Access Gaps:Smallholder operations in southern states lack collateral for FIRA-backed instruments, constraining addressable market expansion below 50-horsepower segments.
Strategic Opportunities
- Yucatán Peninsula Expansion:Citrus and tropical fruit plantations are under-mechanized relative to national averages, creating first-mover positioning for compact equipment specialists.
- SADER Local Content Incentives:Assembly operations meeting domestic value-add thresholds qualify for accelerated depreciation benefits and preferential financing terms.
- Autosteer-Variable Rate Convergence:Bundled precision agriculture packages are penetrating mid-size operations previously priced out of GPS-guided systems.
Industry Challenges
- Mechatronics Skill Scarcity:Diagnostic and repair capabilities for electronic control systems lag fleet complexity, extending downtime and eroding total cost-of-ownership calculations.
- NOM-044 Certification Timelines:Emissions compliance testing bottlenecks delay product launches by 8-14 months, misaligning inventory cycles with planting season demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Agricultural Machinery Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders Technology: Precision Farming, Conventional Farming, Automation, GPS Application: Crop Production, Livestock Management, Soil Preparation, Irrigation End User: Farmers, Agricultural Cooperatives, Contractors, Government |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, Kubota Corporation, Mahindra & Mahindra Ltd., Yanmar Co., Ltd., SDF Group (Same Deutz-Fahr), CLAAS KGaA mbH, International Tractors Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Agricultural Machinery Market Shifts & Advancements
Telematics and precision agriculture platforms are compressing the information gap between equipment operators and agronomic decision-makers across Mexican commercial operations.
Electric and hybrid powertrains are absorbing development priority from conventional diesel architectures as SEMARNAT prepares stricter particulate limits for 2027 implementation. Large vegetable exporters in Sinaloa are piloting battery-electric utility tractors for greenhouse and packing facility operations. The technology is absorbing regulatory anticipation and repositioning R&D budgets toward electrification roadmaps.
CONAGUA's water-use efficiency mandates are reshaping equipment specifications across northern irrigation districts. Drip-compatible tractor configurations with narrow tire profiles and precision seeding attachments are becoming default requirements for new credit approvals. The policy shift is compressing demand for conventional flood-irrigation equipment in Chihuahua and Sonora.
Leasing and managed service contracts are displacing outright ownership among mid-scale operators in Jalisco and Michoacán. Equipment-as-a-service models bundle maintenance, telematics, and seasonal flexibility into per-hectare fee structures. This reconfiguration is most visible among berry and avocado exporters seeking to preserve working capital for perishable handling infrastructure.
Mexico Agricultural Machinery Market Segmentation
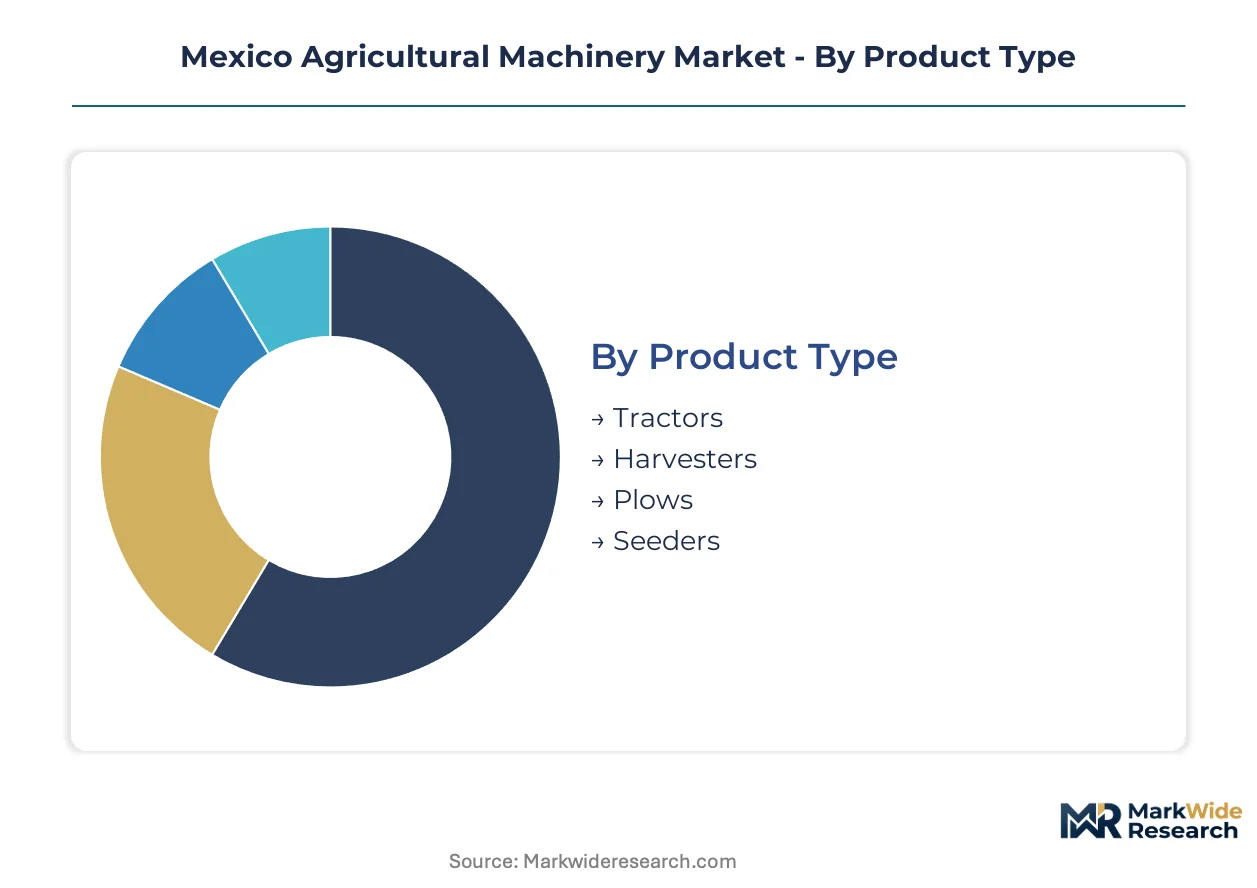
Mexico's agricultural machinery segmentation reveals how equipment specifications align with distinct operational scales across the Bajío wheat belt and Sinaloa vegetable corridors. Understanding these divides exposes where financing programs like FIRA channel capital and where precision technology penetrates fastest.
Product Type:
Equipment specifications range from compact utility platforms to high-horsepower row-crop systems, with powertrain ratings and hitch configurations determining regional deployment patterns.
- Tractors:Self-propelled units spanning 50–400 horsepower ratings with three-point hitch compatibility and ISOBUS electronic interfaces form the foundational fleet assets across Mexican row-crop and specialty operations. Sinaloa and Jalisco commercial farms are expanding mechanized planting fleets, pulling demand toward premium horsepower segments.
- Harvesters:Mechanized collection systems engineered for grain, forage, and high-value specialty crops occupy concentrated margin pools in berry, tomato, and avocado operations where perishable loss reduction justifies capital intensity. Bajío region irrigated corridors are retrofitting fleets with precision headers.
- Plows:Towed tillage implements with adjustable depth control and reversible moldboard configurations prepare seedbeds across Mexico's diverse soil profiles. Chihuahua and Sonora wheat operations are replacing conventional flood-irrigation-compatible tillage with drip-compatible narrow-profile systems.
- Seeders:Precision planting equipment with variable-rate metering and depth control attachments enables uniform emergence in irrigated vegetable production. Guanajuato and Querétaro pressurized water network expansion is accelerating compatible seeder adoption.
Tractors lead on scale; precision-compatible seeders lead on momentum.
Technology:
Control architectures differentiate equipment across cost tiers, with electronic integration levels determining operator skill requirements and total cost-of-ownership calculations.
- Precision Farming:GPS-guided autosteer and variable-rate application systems reduce input waste through real-time soil and crop monitoring, penetrating mid-size operations previously priced out of guidance technology. Telematics integration is compressing information gaps between operators and agronomic decision-makers.
- Conventional Farming:Mechanical-hydraulic control systems without electronic guidance dominate smallholder operations in southern states where FIRA collateral requirements constrain credit access. These platforms sustain largest installed base but face replacement pressure from SEMARNAT emissions restrictions.
- Automation:Autonomous navigation and implement control systems are piloting in large vegetable export operations seeking labor cost containment. Sinaloa greenhouse and packing facilities are testing battery-electric utility platforms.
- GPS:Satellite positioning modules enable field mapping, boundary documentation, and guidance correction for equipment operators. Bundled precision agriculture packages are expanding fastest among berry and avocado exporters.
Conventional farming retains volume dominance; precision farming climbs the fastest.
Application:
Functional use cases determine equipment specifications, with irrigation compatibility becoming decisive under CONAGUA water scarcity protocols.
- Crop Production:Planting, cultivation, and harvest operations for grains, vegetables, and specialty crops drive equipment specifications across Mexico's commercial farming belts. Export-oriented operations in Michoacán and Jalisco prioritize perishable loss reduction through mechanized handling.
- Livestock Management:Feed handling, manure management, and pasture maintenance equipment serves cattle and dairy operations concentrated in northern states. Compact utility tractors dominate this segment.
- Soil Preparation:Tillage, leveling, and amendment incorporation equipment prepares fields for planting across diverse topographies. Drip-compatible tractor configurations with narrow tire profiles are becoming default requirements for new credit approvals.
- Irrigation:Pressurized water distribution and field application systems integrate with equipment mobility requirements in water-stressed districts. CONAGUA mandates are compressing demand for flood-irrigation equipment in Chihuahua and Sonora.
Crop production anchors revenue; irrigation application gains share fastest.
End User:
Procurement scale and financing access differentiate customer segments, with collateral availability determining addressable market boundaries.
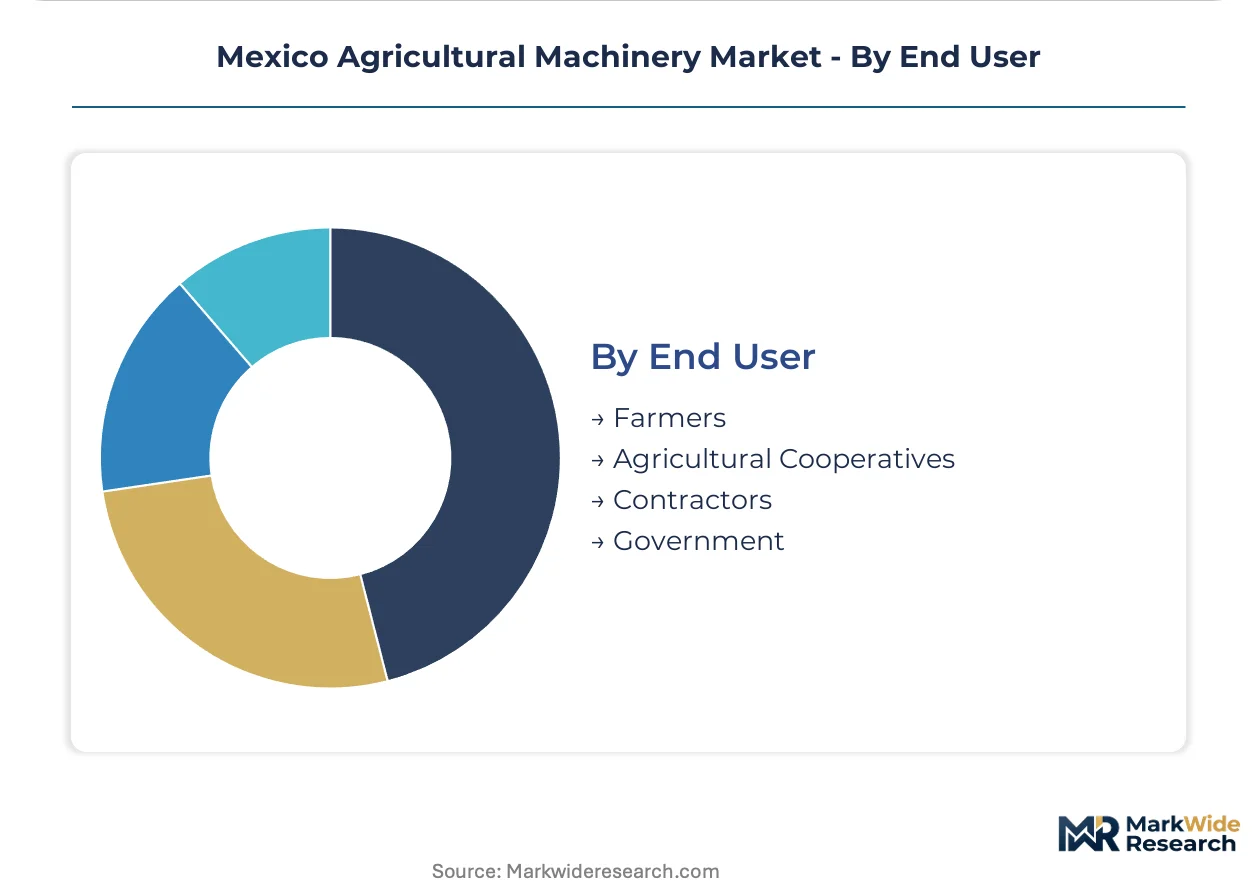
- Farmers:Individual owner-operators range from subsistence-scale producers to large commercial enterprises, with credit access fragmenting sharply across regional banking infrastructure. Southern state smallholders face collateral gaps for FIRA-backed instruments.
- Agricultural Cooperatives:Collective purchasing entities aggregate demand for shared equipment fleets, qualifying for preferential SADER local content incentives and accelerated depreciation benefits. These structures dominate vegetable and grain belt procurement.
- Contractors:Custom service providers offer tillage, planting, and harvest operations on per-hectare fee structures, reducing capital barriers for mid-scale operators. Leasing and managed service contracts are displacing outright ownership in Jalisco and Michoacán.
- Government:Public sector procurement supports research stations, demonstration farms, and subsidized equipment programs through SADER coordination. SEMARNAT environmental certifications govern engine emissions standards for these acquisitions.
Farmers represent the largest addressable base; contractors show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's agricultural machinery sector traces its mechanization lineage to the Green Revolution era, when international equipment manufacturers established distribution networks to serve the country's expanding irrigated wheat and vegetable production. The industry subsequently concentrated around northern commercial farming belts and the central Bajío region, with state-backed credit programs later democratizing access across distinct agroecological zones.
Bajío Region
Pressurized irrigation network expansion in Guanajuato and Querétaro is pulling demand for compatible tillage and precision seeding systems. SADER coordinates FIRA-backed machinery financing that channels procurement toward domestically assembled units meeting local content thresholds. The Irapuato-Silao corridor anchors high-value vegetable export operations where GPS-guided autosteer penetration runs highest.
Sinaloa
Large-scale commercial farms are expanding mechanized planting operations across the Culiacán-Navolato agricultural belt. CONAGUA water scarcity protocols are shifting equipment specifications toward drip-compatible tractor configurations with narrow tire profiles. Berry and tomato exporters pilot battery-electric utility tractors for greenhouse and packing facility operations.
Jalisco
Mid-scale berry and avocado producers are displacing outright ownership with leasing and managed service contracts bundling maintenance into per-hectare fee structures. FIRA financing instruments accelerate credit access for machinery purchases among operations with sufficient collateral. The Tepatitlán highlands concentrate precision agriculture adoption among export-oriented growers.
Nuevo León
Monterrey's distribution infrastructure anchors premium tractor segments serving northern commercial operations. SEMARNAT emissions standards under NOM-044-SEMARNAT-2014 govern engine configurations available through regional dealer networks. The Cadereyta-Allende corridor hosts localized assembly operations that reduce import duty exposure for harvester lines.
Yucatán Peninsula
Citrus and tropical fruit plantations remain under-mechanized relative to national averages, creating positioning opportunities for compact equipment specialists. Credit access gaps constrain addressable market expansion below 50-horsepower segments among smallholder operations. The Mérida-Tizimín axis shows early contractor-led mechanization through custom service providers offering tillage on fee structures.
Mexico Agricultural Machinery Market Competitive Landscape
Capital-heavy producers with integrated manufacturing footprints compete with asset-light distributors relying on regional assembly partnerships to satisfy domestic content requirements. The market structures around three tiers: premium international brands with established dealer networks, mid-market specialists in compact and utility segments, and emerging value-oriented players penetrating southern smallholder markets. Dominant competitive moves include strategic partnerships with FIRA-accredited financing channels and portfolio diversification into precision agriculture bundles.
Within the premium-tier international segment, Deere & Company and CNH Industrial N.V. occupy positions anchored by extensive distribution infrastructure. AGCO Corporation exemplifies the regional assembly archetype through operations qualifying for SADER local content incentives. Kubota Corporation represents mid-market compact equipment specialization targeting fruit and vegetable growers.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra Ltd. |
| Yanmar Co., Ltd. |
| SDF Group (Same Deutz-Fahr) |
| CLAAS KGaA mbH |
| International Tractors Ltd. |
| Others |
Supply & Pricing Matrix
FIRA-accredited commercial farm operators concentrate procurement volume in northern Mexico, anchoring a contract-based pricing structure that bundles equipment with financing terms and seasonal service commitments. This buyer concentration compresses transaction costs while amplifying price transparency across dealer networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by horsepower rating and telematics integration depth. Price differentiation hinges on SEMARNAT emissions certification tier and after-sales service bundling. Cost compression in economy segments is intensifying because steel price volatility feeds directly into chassis fabrication. Smallholder operations in southern states exhibit highest price sensitivity, while export-oriented berry and avocado growers absorb premium tiers for precision compatibility.
Supply Chain Analysis
NOM-044-SEMARNAT-2014 certification timelines gate product entry, forcing manufacturers to synchronize inventory cycles with emissions testing bottlenecks. Powertrain and hydraulic component supply draws from China, Japan, and South Korea, exposing assemblers to currency mismatch and extended lead times. Single-source vulnerability concentrates in electronic control module fabrication. Distribution runs through Monterrey-anchored dealer networks serving northern commercial belts, with secondary channels penetrating the Bajío via Guadalajara logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's agricultural machinery sector functions as a stable compounder, with FIRA-backed financing programs generating predictable replacement cycles that smooth revenue volatility across economic conditions.
For Market Incumbents: Lock in dealer network exclusivity across Sinaloa and Jalisco commercial corridors before compact equipment specialists establish service density. Invest in localized assembly capacity to capture SADER accelerated depreciation benefits. Battery-electric utility platforms represent the emerging substitute threat requiring R&D reallocation. For New Entrants and Emerging Players: Enter via contractor-led custom service models in Yucatán Peninsula citrus belts, where first-mover positioning in under-mechanized plantations avoids direct confrontation with established dealer networks. Target 50-horsepower compact segments among smallholders excluded from FIRA collateral requirements. Partner with regional banks to pioneer alternative credit instruments. For Investors and Strategic Acquirers: Precision agriculture technology vendors are the most active acquirer in this space, seeking equipment OEMs to complete bundled solution portfolios. The five-to-ten year viability window favors assembly operations with domestic value-add thresholds already satisfied. Watch for CONAGUA mandate acceleration as the inflection signal triggering precision equipment replacement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Assembly Expansion | Reduces import duty exposure and unlocks SADER preferential financing terms. |
| Precision Agriculture Bundling | Combines GPS autosteer with variable-rate application to penetrate mid-size operations. |
| Telematics Platform Integration | Compresses information gaps between operators and agronomic decision-makers. |
| Electric Powertrain Development | Positions portfolios for SEMARNAT's anticipated 2027 particulate limits. |
| Contractor Service Model Launch | Displaces ownership with per-hectare fee structures in Jalisco and Michoacán. |
Research Methodology
Coverage spans the Bajío region, Sinaloa, Jalisco, Nuevo León, and Yucatán Peninsula, with primary inputs from each territory informing demand calibration. Interviews with farm equipment dealers, FIRA credit officers, SADER procurement coordinators, and precision agriculture integrators combined with secondary validation from customs records, CONAGUA water-use databases, and SEC filings of listed manufacturers. Bottom-up equipment shipment tallies and top-down agricultural GDP allocations were triangulated to anchor volume estimates.
Rate-of-change decomposition separated replacement demand from net fleet expansion across horsepower segments and technology tiers. Segmentation dimensions modeled include product type, control architecture, functional application, and end-user procurement scale. CAGRs were derived from fitted trend extrapolation adjusted for policy intervention timing. Forecast inputs incorporated FIRA disbursement trajectories and SEMARNAT regulatory phase-in schedules.
Inputs from dealer inventory systems and agricultural cooperative procurement records were available through the study window; gaps in smallholder transaction data introduce uncertainty bands below 50-horsepower segments. Forecasts reflect documented assumptions regarding credit access expansion and emissions compliance timelines. A model refresh is warranted upon material change in CONAGUA water scarcity protocol enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
North America Agricultural Machinery Market