
 South America Agricultural Tractors Market | 2026-2036
South America Agricultural Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agricultural Tractors Market Analytics
Steel-to-aluminum chassis migration is rebalancing weight-to-power ratios across mid-horsepower platforms. Deere & Company leverages its Campo Grande assembly footprint to dominate premium 4-wheel drive lines in Brazil's cerrado belt. AGCO Corporation sustains dealer density across Argentina's Pampas region through its Valtra and Massey Ferguson brands. Kubota Corporation anchors the compact tractor segment for horticulture operators in Chile's Central Valley.
Agricultural tractors are self-propelled vehicles rated by engine horsepower, designed to deliver mechanical, hydraulic, and power-take-off force for tillage, planting, hauling, and implement operation across varied terrain and soil conditions. Four-wheel drive configurations now command the majority of new-unit value given their traction advantage on Brazil's tropical high-clay soils, while compact tractors represent the fastest-expanding product class as Chilean and Colombian fruit exporters mechanize vineyard and orchard tasks. Dealer networks remain the dominant distribution channel across the region, though rental services are gaining share among seasonal crop farmers seeking to avoid capital commitment.
Brazil's Ministry of Agriculture (MAPA) enforces emission standards aligned with CONAMA resolutions, while Argentina's INTA certification shapes equipment import eligibility and local assembly requirements. ANVISA, Brazil's national health regulatory agency, indirectly influences operator cabin safety specifications through occupational exposure rules. Stakeholders must monitor subsidy continuity under Brazil's Plano Safra and Argentina's evolving import-replacement mandates to calibrate production and inventory decisions.
Market Dynamics
Brazil's Plano Safra subsidy continuity debates are forcing fleet operators to accelerate replacement cycles ahead of potential funding reductions, while precision agriculture hardware penetration is compressing the viable lifespan of mechanically simple tractor platforms across the cerrado belt.
Growth Catalysts
- PROTRATOR subsidy program:Brazil's Ministry of Agriculture financing mechanism reduces capital barriers for mid-horsepower acquisitions among soybean cooperatives in Mato Grosso.
- Precision agriculture convergence:Telematics and auto-steering integration is pulling hardware upgrades across Paraná's corn-soy rotation zones.
- High-clay soil traction demands:Four-wheel drive configurations are becoming mandatory for tillage efficiency in Brazil's tropical agricultural frontier.
Market Restraints
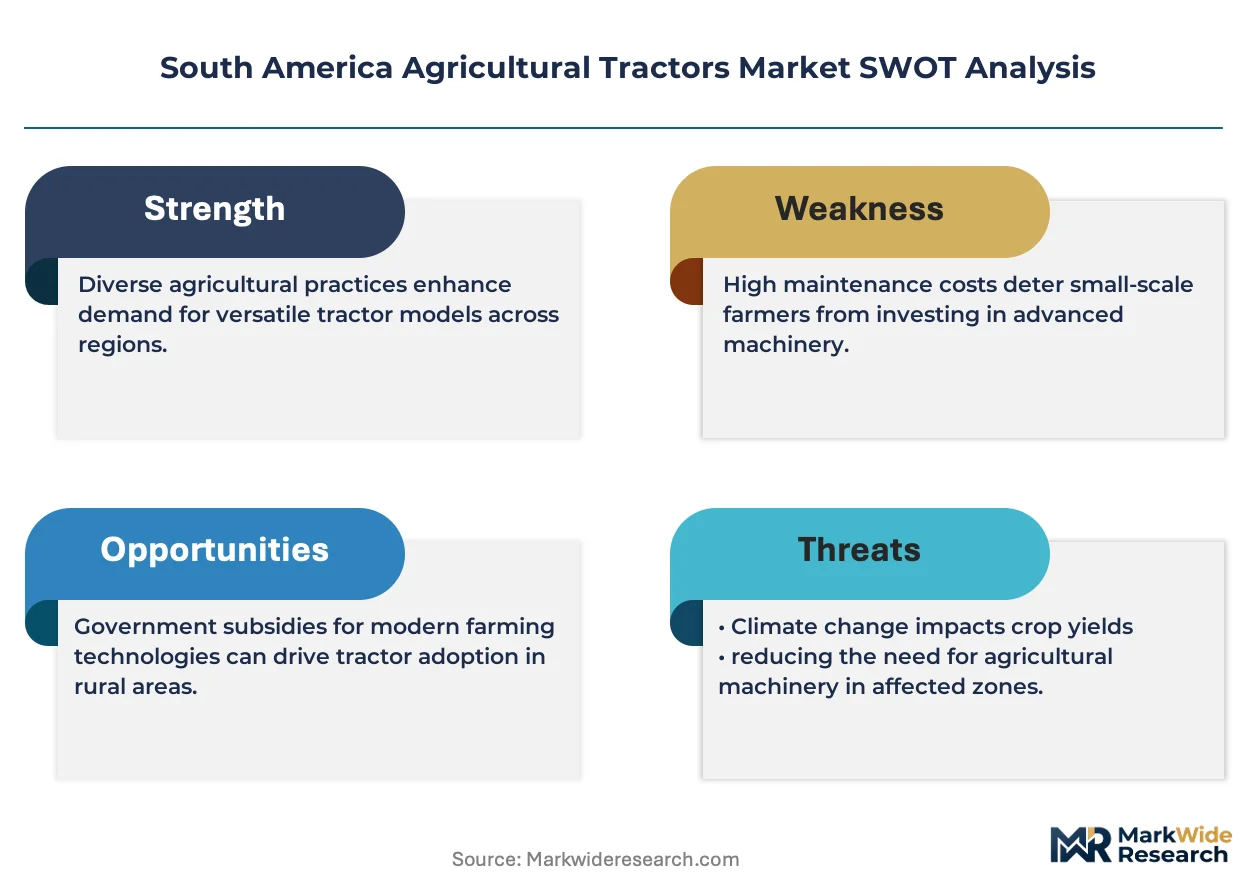
- Steel and aluminum input volatility:Chassis material cost swings compress margin visibility for regional assembly operations.
- Import dependency concentration:Powertrain component sourcing remains concentrated in external supply bases, exposing assemblers to currency fluctuation risk.
- Emission compliance friction:CONAMA resolution alignment timelines create certification bottlenecks for equipment arriving from non-Mercosur origins.
Strategic Opportunities
- Colombian coffee mechanization:Orchard-configured compact tractors face underpenetrated demand among Antioquia and Caldas hillside growers.
- Rental service channel expansion:Seasonal crop operators in Argentina's Pampas are migrating toward equipment-as-access models to avoid capital lockup.
- ANVISA cabin safety mandates:Operator exposure rule tightening creates retrofit and new-unit specification premiums for enclosed-cabin platforms.
Industry Challenges
- Precision agriculture technician scarcity:Diagnostic and calibration skill gaps constrain dealer service capacity across remote agricultural zones.
- Legacy hydraulic system integration:Older implement fleets require adapter engineering that delays smart-tractor deployment timelines.
- Plano Safra continuity uncertainty:Multi-year subsidy commitment ambiguity complicates fleet planning for large-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agricultural Tractors Market |
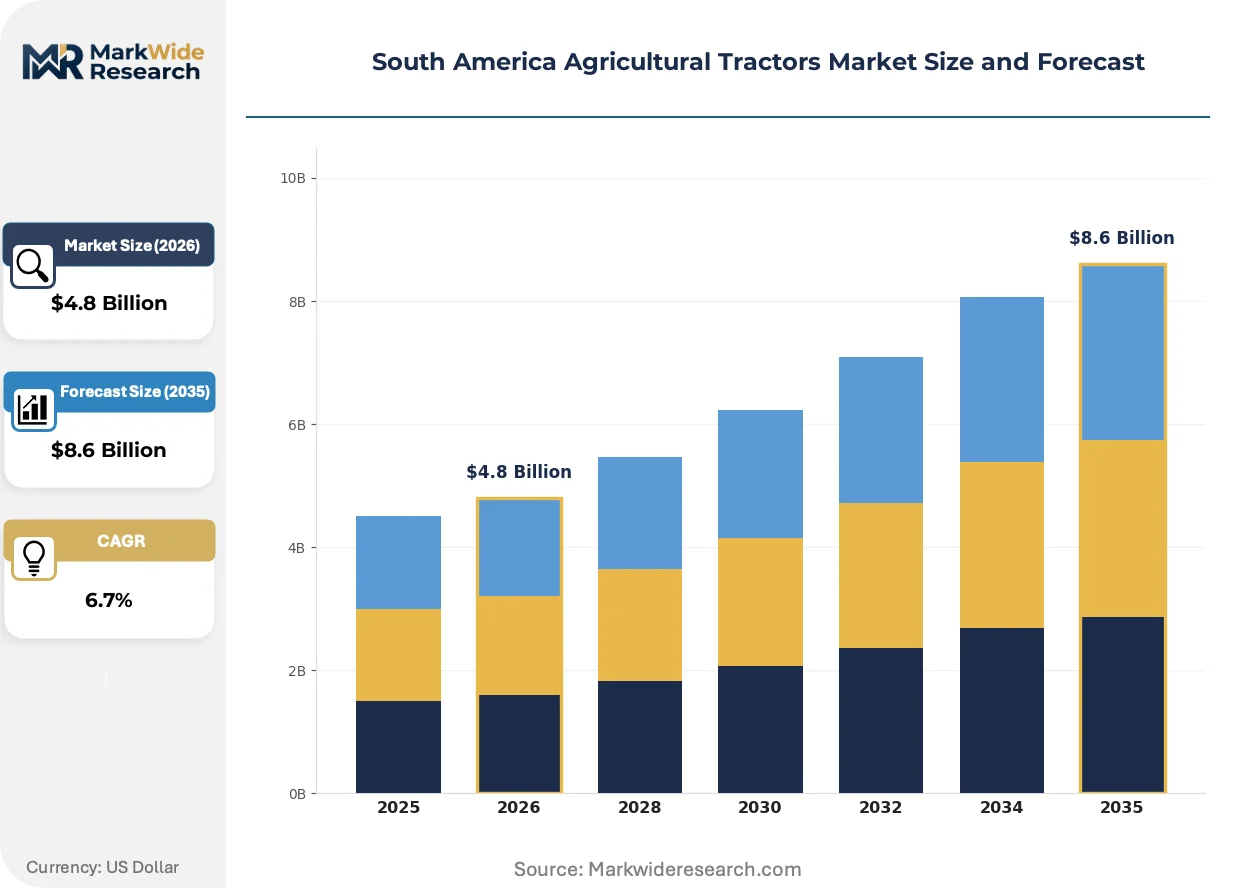
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Wheel Drive, 4-Wheel Drive, Compact, Utility End User: Farmers, Cooperatives, Agricultural Enterprises, Contractors Application: Crop Farming, Dairy Farming, Livestock Management, Horticulture Distribution Channel: Direct Sales, Dealers, Online Stores, Rental Services |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Kubota Corporation, Mahindra & Mahindra Ltd, CLAAS, Agrale, Zetor Tractors, Escorts, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agricultural Tractors Market Evolving Landscape
Telematics penetration is compressing the traditional depreciation curves for agricultural equipment, while steel-to-aluminum chassis migration rebalances power-to-weight ratios across mid-horsepower segments.
Autonomous guidance systems are automating tillage and planting operations across Brazil's large-scale soybean enterprises. Operators in Mato Grosso and Goiás are retrofitting existing fleets with RTK-GPS steering at accelerating rates. This automation is compressing labor cost structures and enabling 24-hour operational windows during narrow planting windows.
ANVISA occupational exposure regulations are mandating sealed-cabin air filtration and ergonomic control layouts for new tractor registrations. Assembly operations must reconfigure production lines to accommodate HEPA filtration and vibration damping specifications. Brazil's cerrado belt operators are prioritizing compliant platforms to avoid downtime penalties during inspection cycles.
Cooperative procurement consortia are consolidating equipment acquisitions among medium-scale soybean and corn producers. Dealer networks in Paraná and Rio Grande do Sul are responding with volume-tiered pricing and shared service depot arrangements. This consolidation is most visible among family-scale operations seeking to match the negotiating leverage of corporate farming enterprises.
South America Agricultural Tractors Market Segmentation
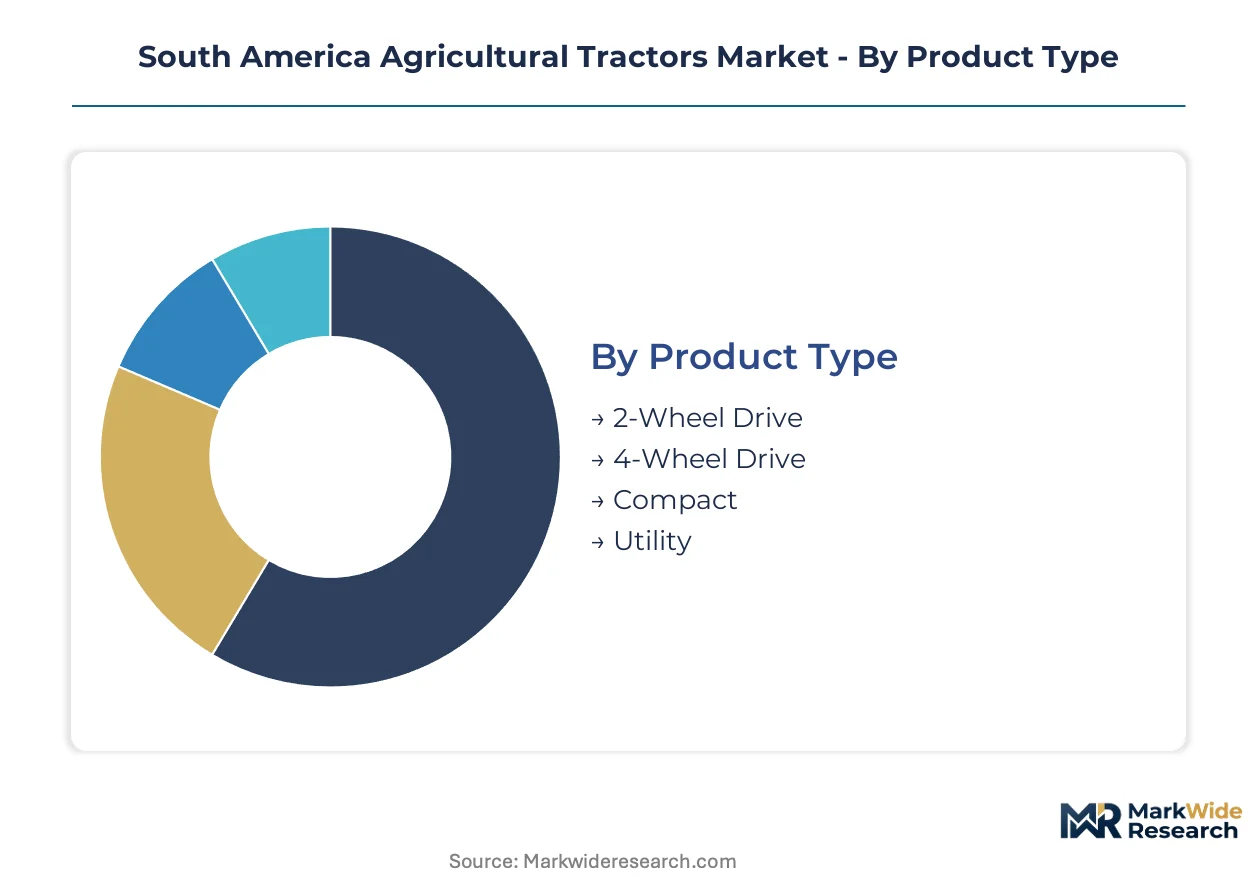
Tractor specification tiers align directly with soil conditions and operational scale across South American agricultural belts. Equipment selection varies sharply between Brazil's large-scale cerrado operations and Chile's compact orchard configurations.
Product Type:
Drive configuration and chassis scale determine traction performance on Brazil's high-clay tropical soils versus maneuverability in confined horticultural plots.
- 4-Wheel Drive:Dual-axle power delivery distributes torque across all wheels for tillage efficiency in Mato Grosso's high-clay soybean zones. Brazil's cerrado belt operators now treat this configuration as mandatory for primary tillage given traction demands on saturated tropical soils.
- Compact:Sub-50 horsepower platforms with tight turning radii serve Chile's Central Valley vineyard operators and Colombian coffee hillside plots. Mechanization of orchard tasks among Antioquia growers is pulling unit volumes upward as hand-labor availability tightens.
- 2-Wheel Drive:Single-axle traction suits dryland grain operations on lighter soils in Argentina's western Pampas fringe.
- Utility:Mid-range horsepower bridges primary fieldwork and transport duties for mixed-operation farms in Rio Grande do Sul.
Four-wheel drive configurations lead on scale; compact tractors lead on momentum.
End User:
Capital access and fleet sophistication separate procurement patterns across South American agricultural structures.
- Agricultural Enterprises:Corporate farming operations in Mato Grosso and Goiás deploy precision agriculture suites at scale, compressing replacement cycles for telematics-capable platforms. PROTRATOR subsidy capture requires documented production volume thresholds that favor these entities.
- Cooperatives:Consolidated procurement among Paraná soybean collectives generates volume-tiered pricing leverage unavailable to individual operators. Shared service depot arrangements reduce per-unit maintenance overhead across member farms.
- Farmers:Family-scale operations in Rio Grande do Sul rely on dealer financing and trade-in programs for mid-horsepower acquisitions.
- Contractors:Seasonal service providers in Argentina's Pampas are migrating toward rental channels to avoid capital lockup during weather-variable planting windows.
Agricultural enterprises dominate absolute unit absorption; cooperatives are expanding most quickly through consolidated procurement.
Application:
Task-specific implement compatibility shapes horsepower and hydraulic specification requirements across production systems.
- Crop Farming:Large-scale soybean and corn operations in Brazil's agricultural frontier demand high-horsepower platforms with integrated auto-steering and variable-rate application hardware. RTK-GPS retrofit penetration is compressing labor cost structures during narrow planting windows.
- Horticulture:Chilean fruit exporters and Colombian flower operations require narrow-profile tractors with enclosed cabs meeting ANVISA air filtration mandates for operator exposure compliance.
- Livestock Management:Pasture maintenance and feed handling in Uruguay's beef operations favor utility-class durability.
- Dairy Farming:Manure handling and forage harvesting in southern Brazil's dairy belt prioritize PTO consistency and hydraulic flow rates.
Crop farming commands the largest installed base; horticulture shows the steepest expansion trajectory as export-oriented mechanization accelerates.
Distribution Channel:
Capital commitment tolerance and service proximity determine channel selection across operator types.
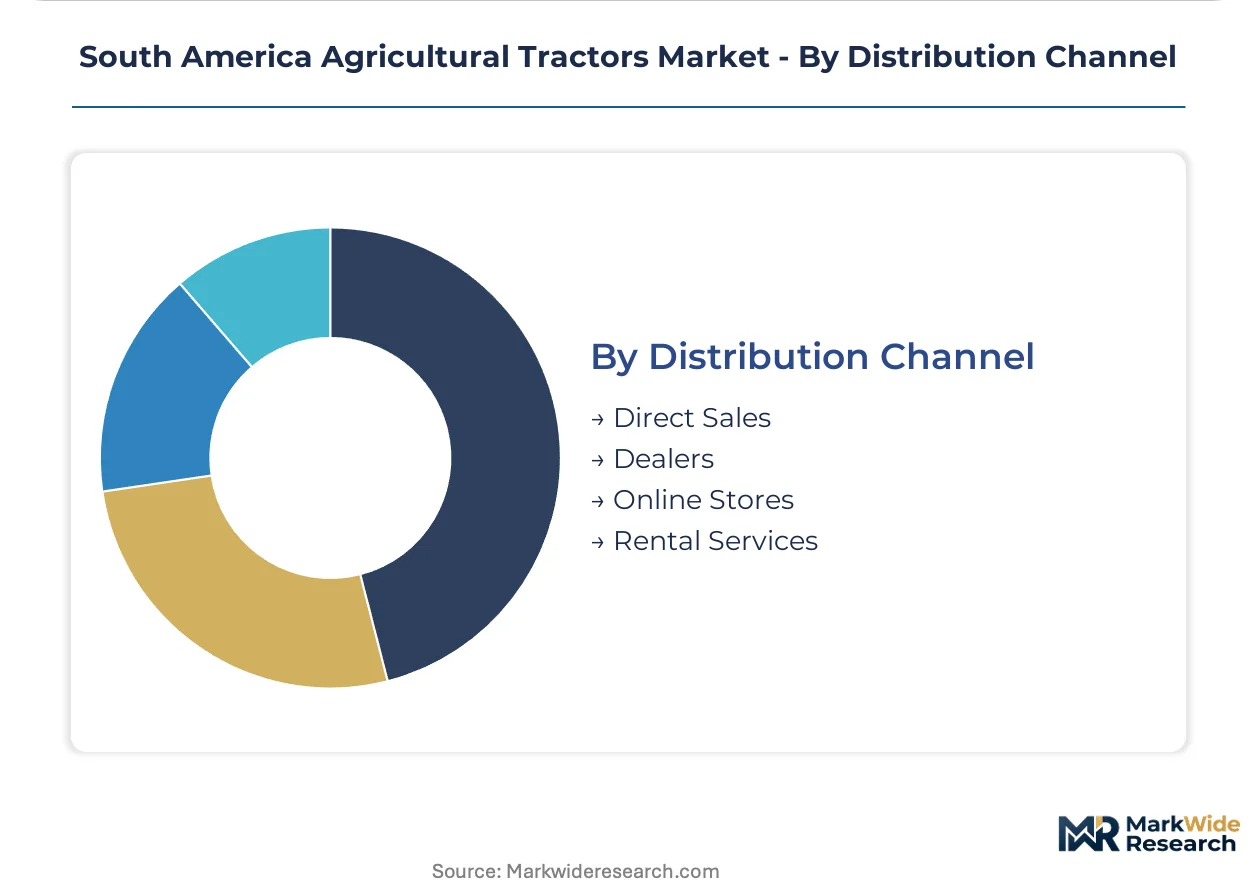
- Dealers:Physical service infrastructure and financing relationships dominate Brazilian and Argentine tractor commerce. AGCO and Deere networks maintain density across the Pampas and cerrado belts for warranty support and parts availability.
- Rental Services:Equipment-as-access models are gaining share among seasonal crop operators seeking to avoid depreciation risk during drought cycles. Argentine contractors particularly favor this channel given peso volatility and import restriction uncertainty.
- Direct Sales:Large enterprise accounts in Mato Grosso negotiate manufacturer-direct fleet packages with customized specification bundles.
- Online Stores:Digital channels serve parts and attachment commerce, though complete tractor transactions remain minimal due to financing complexity.
Dealer networks retain scale leadership; rental services are gaining share fastest among capital-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's cerrado belt anchors South American tractor demand through large-scale soybean and corn mechanization, with state-level subsidy programs and precision agriculture adoption driving fleet modernization across the continent's agricultural frontier.
Brazil
Mato Grosso, Paraná, and Rio Grande do Sul concentrate procurement for high-horsepower four-wheel drive platforms. MAPA's PROTRATOR subsidy program reduces capital barriers for soybean cooperatives meeting production volume thresholds. Campo Grande assembly operations serve the cerrado belt with premium 4-wheel drive configurations.
Argentina
The Pampas region sustains demand for utility-class tractors across mixed grain and livestock operations. INTA certification shapes equipment import eligibility and local assembly requirements for regional distributors. Buenos Aires province dealers maintain dense service networks for warranty support and parts availability.
Chile
The Central Valley drives compact tractor absorption for vineyard and orchard mechanization among fruit exporters. ANVISA-aligned cabin safety mandates for operator exposure compliance favor enclosed-cab platforms with HEPA filtration. Santiago-based distributors anchor horticulture-focused dealer networks.
Colombia
Antioquia and Caldas coffee zones present underpenetrated demand for orchard-configured compact tractors on hillside plots. Hand-labor availability tightening accelerates mechanization among flower and coffee growers. Bogotá procurement channels coordinate equipment financing for regional agricultural enterprises.
Uruguay
Southern pasturelands favor utility-class durability for beef operation feed handling and pasture maintenance. Seasonal contractor models gain traction among capital-constrained operators seeking rental alternatives. Montevideo distribution hubs coordinate cross-border service support with Argentine dealer networks.
South America Agricultural Tractors Market Competitive Landscape
Capacity expansion dominates the current landscape as assemblers calibrate production lines to ANVISA cabin safety mandates and telematics integration requirements. The vendor base organizes around three strategic archetypes: integrated multinational manufacturers with regional assembly footprints, specialist compact equipment providers serving horticulture segments, and emerging regional fabricators targeting subsidy-captured mid-horsepower tiers. Geographic expansion through dealer network densification and portfolio diversification into precision agriculture hardware represent the dominant competitive vectors.
Within the multinational tier, Deere & Company and AGCO Corporation exemplify integrated assembly and distribution scale across Brazil and Argentina. Kubota Corporation anchors the compact tractor segment for export-oriented horticulture operators. These three manufacturers occupy positions that reflect divergent strategic emphases: cerrado belt premium platforms, Pampas region dealer density, and Central Valley orchard specialization respectively.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Kubota Corporation |
| Mahindra & Mahindra Ltd |
| CLAAS |
| Agrale |
| Zetor Tractors |
| Escorts |
| Others |
Value Network & Pricing Analysis
Steel and aluminum price indices on the London Metal Exchange cascade through South American tractor manufacturing into three distinct pricing tiers for chassis and powertrain assemblies. Brazilian assemblers absorb volatility through contract hedging while passing tiered cost exposure downstream to cooperative buyers and enterprise fleets.
Pricing Analysis
Input-cost pass-through from steel and aluminum commodities stratifies final equipment pricing across premium, standard, and economy specification levels. Price differentiation hinges on telematics integration density and ANVISA cabin certification grade. Pricing pressure stems from currency fluctuation exposure on imported powertrain components. Cooperative buyers in Paraná exhibit highest price sensitivity due to volume-negotiation leverage, while Mato Grosso enterprises prioritize specification compliance over unit cost.
Supply Chain Analysis
Argentina's evolving import-replacement mandates and Brazil's local-content thresholds for PROTRATOR subsidy eligibility are reshaping component sourcing toward Mercosur-based suppliers. Powertrain manufacturing concentrates in Brazil, Argentina, and select Mexican assembly operations. Raw material dependencies center on steel sheet, aluminum extrusions, and hydraulic system castings. Supply chain risk concentrates in single-source vulnerability for precision agriculture sensor modules. Distribution runs through dealer networks with captive parts warehousing across the cerrado belt and Pampas region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Agricultural Tractors Market represents a late-cycle quality story as precision agriculture convergence pulls demand toward telematics-capable platforms with certified operator cabins.
For Market Incumbents: Deepen backward integration into hydraulic system casting and cabin assembly to offset currency exposure on imported components. Expand Campo Grande and Rosario production footprints to capture PROTRATOR and Argentine subsidy flows. Prioritize ANVISA certification pre-compliance to avoid registration bottlenecks. For New Entrants and Emerging Players: Launch via rental service partnerships targeting Argentine contractors seeking equipment-as-access models. Colombia's Antioquia coffee zones and Chilean vineyard operators present underpenetrated compact tractor demand. Position through orchard-specific implement compatibility and financing bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where dealer network density overlaps with precision agriculture service capability gaps. Long-term viability favors platforms with integrated telematics and regional assembly footprints. Target mid-horsepower specialists with Mercosur certification pathways. Watch for subsidy program continuity announcements as fleet replacement cycle inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Assembly Footprint Expansion | Campo Grande and Rosario facilities capture Brazilian PROTRATOR and Argentine subsidy eligibility. |
| Telematics Platform Integration | RTK-GPS and auto-steering retrofit kits compress labor costs for Mato Grosso soybean operators. |
| ANVISA Certification Pre-Compliance | HEPA filtration and ergonomic cabin layouts avoid registration delays under occupational exposure rules. |
| Dealer Network Densification | Shared service depots in Paraná reduce per-unit maintenance overhead for cooperative procurement consortia. |
| Compact Tractor Portfolio Diversification | Orchard-configured platforms address Colombian coffee mechanization and Chilean fruit export demand. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, Colombia, and Uruguay, with primary inputs from each market through structured interviews with agricultural equipment dealers, fleet procurement managers at soybean cooperatives, precision agriculture technicians, MAPA subsidy program administrators, and aftermarket service directors. Secondary validation draws from customs trade databases, CONAMA emission resolution filings, ANVISA equipment registration records, and agricultural census data. Bottom-up unit shipment tracking triangulates against top-down subsidy disbursement and financing flow analysis.
Rate-of-change decomposition separates volume growth from specification-mix shift and price-tier migration across the projection horizon. Segmentation dimensions include drive configuration, horsepower tier, end-user structure, application type, and distribution channel. CAGRs derive from fitted trend extrapolation adjusted for subsidy program continuity scenarios and precision agriculture penetration curves. Industry-specific inputs incorporate Plano Safra funding trajectories and cerrado belt fleet age distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt subsidy withdrawal or prolonged currency volatility. Assumptions reflect documented PROTRATOR commitment schedules and CONAMA resolution implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Hay Making Machinery Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
North America Haying and Forage Machinery Market