
 Agriculture and Farm Machinery Market | 2026-2036
Agriculture and Farm Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture and Farm Machinery Market Analysis
Modular equipment bundling is expanding as OEMs package tractors with precision agriculture sensors and IoT Solutions to lock in recurring service revenue. John Deere leverages its proprietary command platforms to control aftermarket data flows. CNH Industrial anchors its European position through in-house production of autonomous guidance systems. AGCO Corporation competes in the mid-horsepower segment with region-specific configurations for Brazilian and Indian buyers.
Agriculture and farm machinery encompasses powered and towed equipment engineered to specifications exceeding 40 horsepower for soil preparation, crop management, and harvest operations, typically fabricated from high-strength steel with hydraulic systems rated for continuous duty cycles. Its primary commercial purpose is to substitute mechanical energy for labor in crop production workflows, reducing per-acre input costs at scale. Tractors dominate installed base value across all geographies, while autonomous machinery represents the fastest-growing technology segment as regulatory frameworks mature for unmanned field operations. Precision agriculture generates the deepest margin pools through subscription-based agronomic data services layered over hardware sales.
EPA Tier 4 Final emissions standards and EU Stage V regulations are forcing engine architecture changes that add manufacturing cost but create compliance barriers for smaller competitors. Brazil's national agricultural regulator and India's Central Pollution Control Board are adopting harmonized test cycles that reshape export product planning for multinational OEMs. Stakeholders must monitor how carbon credit eligibility for precision application equipment alters replacement timing for conventional sprayers and plowing systems.
Market Dynamics
Precision agriculture platforms are fragmenting equipment procurement decisions as farm operators evaluate hardware through subscription economics rather than capital expenditure cycles.
Growth Catalysts
- EPA Tier 4 Final mandates:Emissions compliance requirements in the United States accelerate replacement demand for pre-compliant tractor fleets as retrofit costs exceed residual equipment value.
- Brazil's Mato Grosso soybean belt:Mechanization density gaps in this cluster create concentrated demand for mid-horsepower equipment configurations optimized for no-till planting systems.
- Autonomous guidance convergence:Sensor fusion between RTK-GNSS and machine vision lowers operator skill barriers while compressing field pass overlap rates below 2 percent.
Market Restraints
- High-strength steel input volatility:Hydraulic system fabricators face margin compression when alloy surcharges spike, forcing pass-through delays that strain OEM-assembler relationships.
- EU Stage V compliance costs:Selective catalytic reduction and diesel particulate filter integration adds manufacturing complexity that disadvantages sub-100 horsepower specialists lacking scale.
- Precision agriculture talent scarcity:Agronomic data interpretation skills concentrate in university extension programs, creating bottlenecks for dealer service network expansion.
Strategic Opportunities
- India's Central Pollution Control Board harmonization:Test cycle alignment with EU Stage V creates export pathway for compliant equipment platforms without redundant certification investment.
- Carbon credit eligibility for precision application:Variable-rate sprayers and section-controlled planters qualify for offset markets, embedding hardware into farm sustainability accounting.
- Telematics-enabled predictive maintenance:IoT sensor networks transform dealer relationships from transactional parts sales to recurring uptime guarantees.
Industry Challenges
- Legacy hydraulic architecture integration:Closed-center systems on existing tractor fleets resist retrofit with electrohydraulic implements, forcing parallel inventory maintenance.
- Dealer technician certification timelines:Proprietary diagnostic tool training creates service coverage gaps in rural territories distant from OEM technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture and Farm Machinery Market |
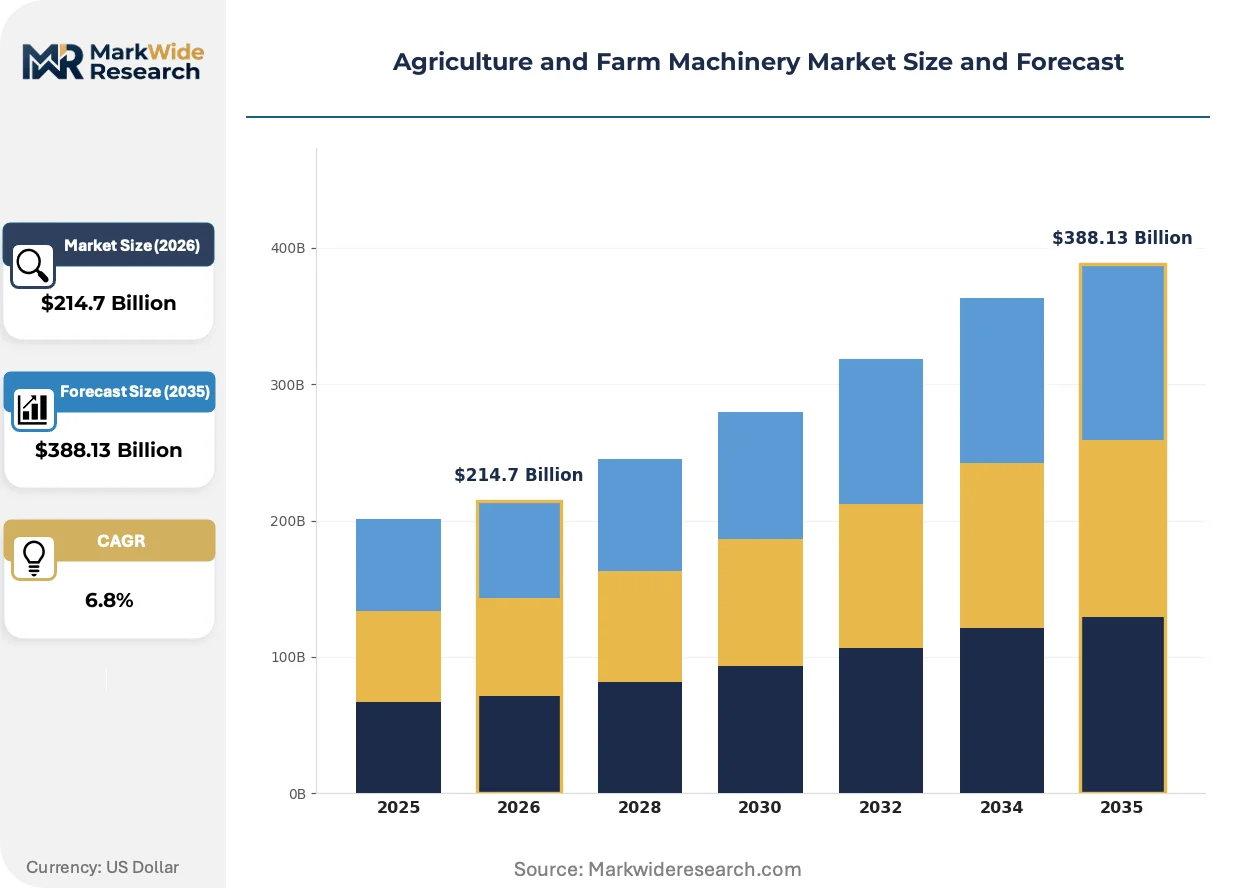
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plowing Equipment, Spraying Equipment Application: Crop Production, Soil Preparation, Irrigation Management, Pest Control End Use Industry: Farming, Agribusiness, Agricultural Cooperatives, Horticulture Technology: Precision Agriculture, Autonomous Machinery, IoT Solutions, Drones |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Claas, SDF Group, Caterpillar, FMWORLD Agricultural Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture and Farm Machinery Market Emerging Trajectories
Equipment intelligence is migrating from centralized cab displays to distributed implement-mounted controllers, altering how OEMs capture value from farm operation data.
Edge computing architectures on planters and sprayers are decentralizing agronomic decision authority from tractor cab terminals to implement-level processors. Large-scale corn and soybean operators in Iowa and Illinois deploy these systems to execute sub-inch accuracy corrections without latency from cloud round-trips. This topology compresses reaction times for real-time seed placement adjustments while fragmenting data ownership between tractor OEMs and implement manufacturers.
EU Stage V regulations and Brazil's national agricultural regulator harmonization are forcing synchronized product architecture planning across Atlantic supply chains. Engine manufacturers must validate aftertreatment durability under tropical humidity cycles and temperate freeze-thaw conditions simultaneously. Multinational OEMs respond by consolidating powertrain sourcing to platforms with dual-certification documentation, squeezing regional engine suppliers lacking validation breadth.
Service contract unbundling from equipment finance packages lets farm operators compare aftermarket parts and independent repair against captive dealer networks. Midwest grain operations increasingly separate maintenance spend from capital leases, pressuring OEMs to demonstrate hourly cost advantages. This procurement pattern concentrates in corn-soybean rotations where equipment utilization rates justify dedicated in-house technician staffing.
Agriculture and Farm Machinery Market Segmentation
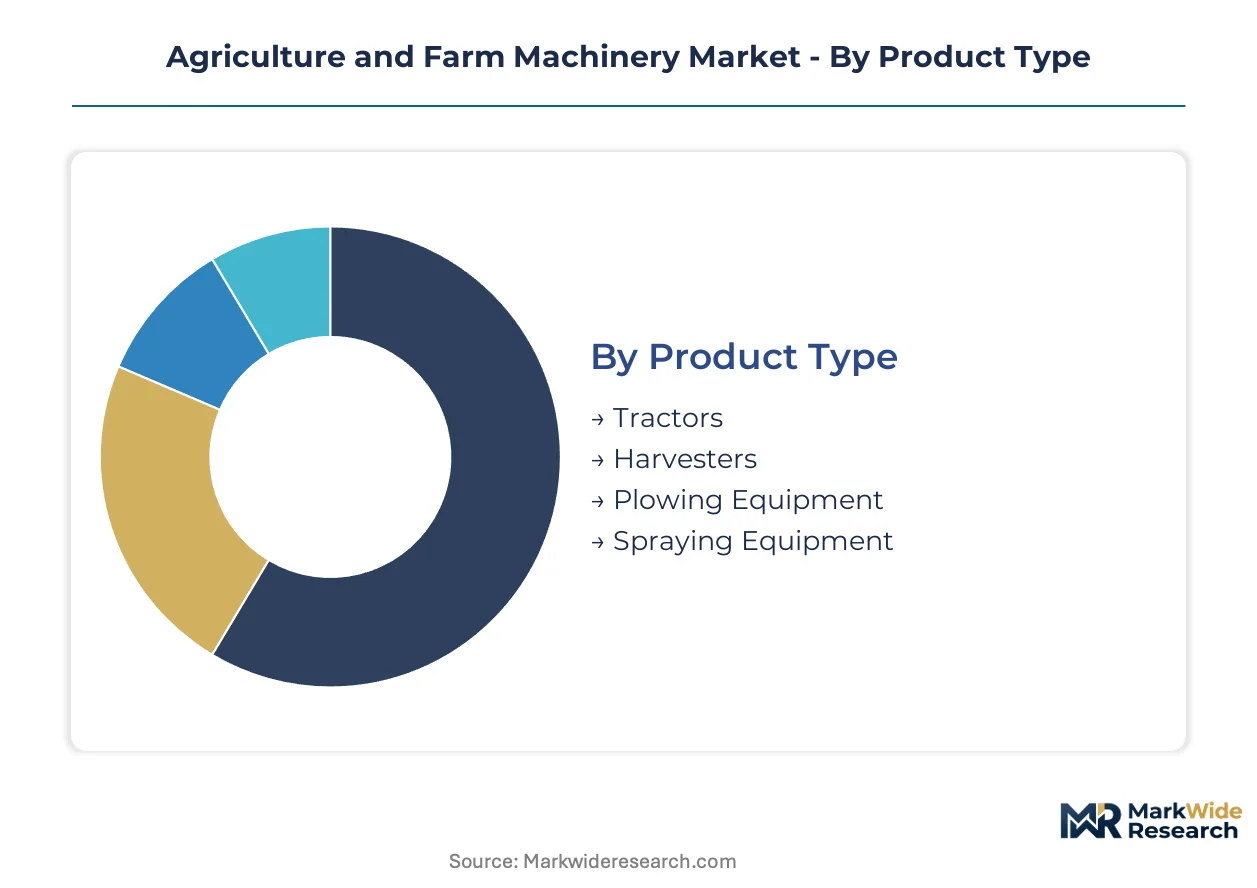
Segmentation in agriculture machinery reveals how purchasing decisions split between capital-intensive fleet operators and technology-focused precision adopters. Equipment specifications vary sharply across crop types, farm scale, and regulatory environments, forcing OEMs to maintain parallel product architectures.
Product Type:
Buyers differentiate primarily by horsepower requirements and attachment compatibility rather than brand loyalty alone.
- Tractors:High-strength steel chassis with hydraulic systems rated above 40 horsepower dominate installed base value. Demand concentrates in Brazil's Mato Grosso soybean belt as mechanization accelerates for no-till planting systems.
- Harvesters:Self-propelled combines with threshing and cleaning modules engineered for continuous duty cycles. Large-scale corn and soybean operators in Iowa and Illinois drive replacement cycles as EPA Tier 4 Final mandates phase out pre-compliant fleets.
- Plowing Equipment:Towed implements for soil preparation with hardened blade configurations. Regional specialization dominates as Brazilian cerrado soils require distinct metallurgy from US Midwest clay compositions.
- Spraying Equipment:Boom-mounted liquid application systems with variable-rate controllers. Carbon credit eligibility for precision application is embedding hardware into farm sustainability accounting.
Tractors lead volumes today; autonomous guidance retrofits on harvesters are gaining share fastest.
Application:
Workflow sequencing determines equipment bundling patterns and dealer service contract structures.
- Crop Production:Seeding through harvest operations requiring seasonal equipment deployment. Midwest grain operations increasingly separate maintenance spend from capital leases, pressuring hourly cost demonstrations.
- Soil Preparation:Tillage and residue management preceding planting windows. EU Stage V compliance costs disadvantage sub-100 horsepower specialists lacking scale for aftertreatment integration.
- Irrigation Management:Water delivery system installation and maintenance equipment. Edge computing architectures on field sensors are decentralizing control from centralized cab displays.
- Pest Control:Chemical and biological intervention application systems. Section-controlled planters qualify for offset markets, embedding hardware into sustainability accounting.
Crop production commands the largest equipment allocation; irrigation management is expanding most quickly as water stress intensifies.
End Use Industry:
Ownership structure shapes financing preferences and technician staffing decisions.
- Farming:Owner-operated enterprises with mixed fleet ages and repair capabilities. Dealer technician certification timelines create service coverage gaps in rural territories distant from OEM technical centers.
- Agribusiness:Corporate farming entities with centralized procurement and dedicated maintenance staff. Telematics-enabled predictive maintenance transforms dealer relationships from transactional parts sales to recurring uptime guarantees.
- Agricultural Cooperatives:Member-owned purchasing consortia negotiating volume discounts. Shared equipment pools demand standardized diagnostic interfaces across mixed OEM fleets.
- Horticulture:Specialty crop producers with compact equipment requirements and high-value per-acre inputs. Greenhouse automation systems require distinct hydraulic architectures from field machinery.
Farming retains the broadest installed base; agribusiness is climbing the fastest as consolidation accelerates.
Technology:
Data ownership and subscription economics are fragmenting traditional hardware procurement cycles.
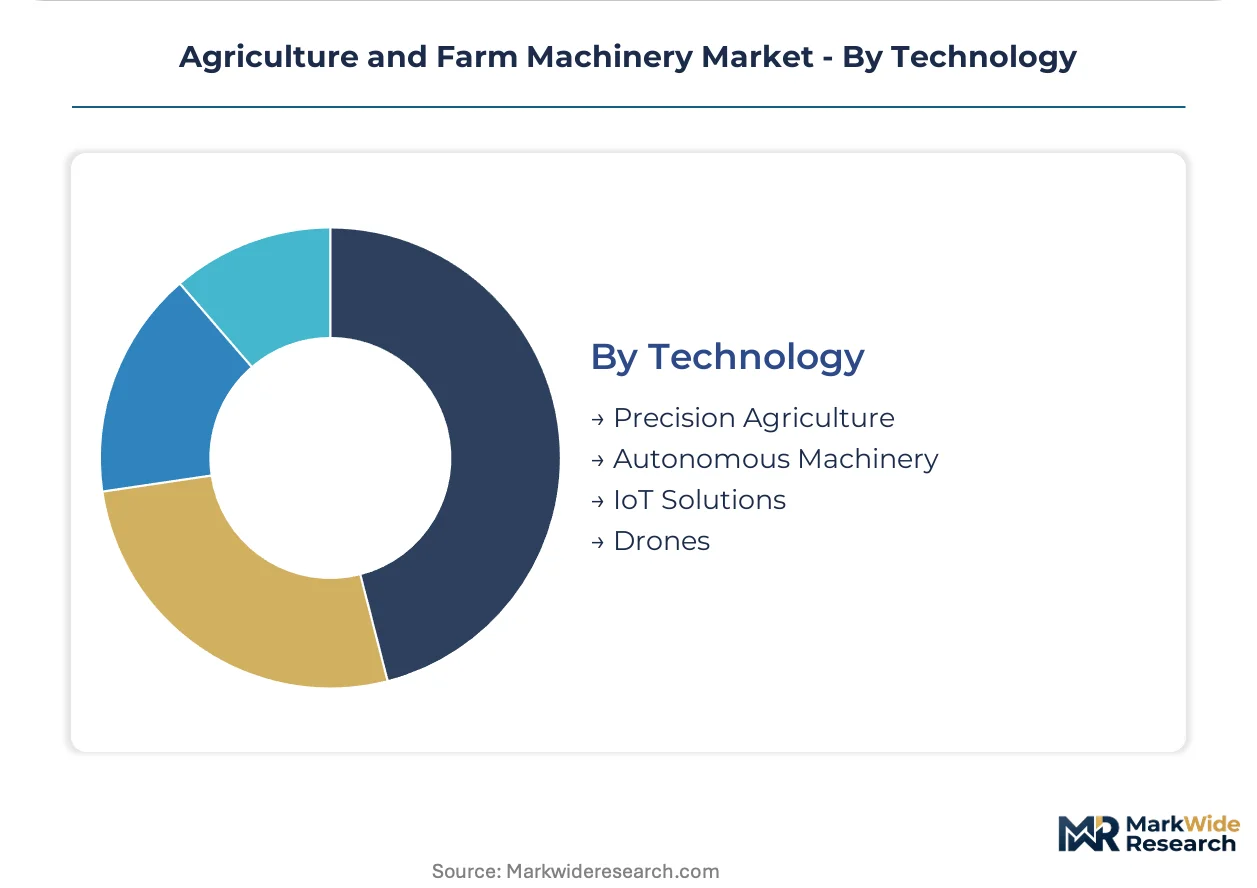
- Precision Agriculture:GNSS-guided variable-rate input application with agronomic data layering. Subscription-based services generate the deepest margin pools beyond initial hardware sales.
- Autonomous Machinery:Unmanned field operations using sensor fusion between RTK-GNSS and machine vision. Regulatory frameworks are maturing for unmanned operations as overlap rates compress below 2 percent.
- IoT Solutions:Connected equipment networks transmitting operational telemetry to cloud platforms. Proprietary command platforms control aftermarket data flows, locking in recurring service revenue.
- Drones:Aerial imaging and targeted application systems for crop monitoring. India's Central Pollution Control Board harmonization with EU Stage V creates export pathways without redundant certification.
Precision agriculture dominates current revenue; autonomous machinery shows the steepest expansion trajectory as labor constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechanized agriculture first achieved industrial scale in the United States during the early twentieth century, with the Midwest corn belt establishing the template for large-scale tractor deployment that later diffused to Brazil, India, and China.
United States
Large-scale corn and soybean operators in Iowa and Illinois drive replacement demand as EPA Tier 4 Final mandates phase out pre-compliant fleets. The USDA administers conservation programs that subsidize precision application equipment adoption. Equipment intelligence clusters concentrate around Moline, Illinois, and Waterloo, Iowa, where OEM technical centers anchor dealer certification networks.
Brazil
Mechanization density gaps in Mato Grosso's soybean belt create concentrated demand for mid-horsepower configurations optimized for no-till systems. ANVISA harmonizes agricultural equipment regulations with EU test cycles, streamlining import certification for multinational OEMs. São Paulo state's manufacturing corridor hosts assembly operations serving both domestic demand and Mercosur export markets.
Germany
EU Stage V compliance requirements accelerate fleet turnover among specialized crop producers in Lower Saxony and Bavaria. The KBA enforces diesel aftertreatment validation protocols that disadvantage smaller engine suppliers lacking tropical climate testing capabilities. Stuttgart's industrial region concentrates autonomous guidance system development for export to Atlantic supply chains.
India
Smallholder consolidation in Punjab and Haryana drives demand for compact tractors under 40 horsepower for paddy-wheat rotations. The Central Pollution Control Board's harmonization with EU Stage V creates export pathways for compliant equipment platforms. Gujarat's engineering corridor hosts fabrication clusters supplying hydraulic components to domestic OEMs and Southeast Asian markets.
China
State-backed agricultural modernization programs in Heilongjiang and Inner Mongolia prioritize high-horsepower equipment for mechanized grain production. The Ministry of Ecology and Environment enforces GB standards for non-road diesel engines that increasingly align with EU emission tiers. Shandong Province's manufacturing belt concentrates tractor assembly serving domestic replacement cycles and Belt and Road export destinations.
Agriculture and Farm Machinery Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive powertrain capabilities. Consolidation pressure intensifies as emissions compliance costs squeeze sub-scale specialists lacking aftertreatment integration expertise. Three archetypes dominate: full-line OEMs with proprietary telematics platforms, regional specialists with cost-optimized configurations for emerging markets, and component suppliers backward-integrating into complete equipment assembly. Capacity consolidation and strategic technology licensing represent the primary competitive vectors as firms seek to spread validation costs across broader production volumes.
Among diversified machinery manufacturers, Deere & Company, CNH Industrial, and AGCO Corporation exemplify the full-line archetype with integrated precision agriculture service layers. These firms anchor competitive positioning through proprietary data platforms that transform hardware sales into recurring subscription relationships. Kubota Corporation and Mahindra & Mahindra occupy positions as regional scale specialists with manufacturing footprints optimized for Asia-Pacific cost structures and distribution density.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Claas |
| SDF Group |
| Caterpillar |
| FMWORLD Agricultural Machinery |
| Others |
Supply Flow & Price Mechanics
High-strength steel index volatility cascades through hydraulic system fabricators into equipment pricing tiers, compressing margins for mid-horsepower specialists while full-line OEMs absorb alloy surcharges through captive foundry operations and long-term offtake agreements with Brazilian and Indian mills.
Pricing Analysis
Equipment-plus-subscription bundling dominates transaction structures, separating hardware capital cycles from recurring agronomic data service fees. Price differentiation hinges on precision agriculture sensor integration density and EPA Tier 4 Final certification tier. Cost compression in the sub-100 horsepower segment intensifies as EU Stage V aftertreatment integration disadvantages smaller competitors lacking scale. Agribusiness buyers with dedicated maintenance staffs exhibit lowest price sensitivity; smallholder cooperatives in India's Punjab belt face acute budget constraints.
Supply Chain Analysis
Remanufactured component flows from Midwest dealer networks back to OEM technical centers in Moline and Waterloo create secondary parts markets that undercut new hydraulic assembly pricing. Engine production concentrates in Germany, the United States, and China, with aftertreatment validation tethered to tropical humidity and temperate freeze-thaw testing protocols. High-strength steel sourcing rests on Brazilian and Indian mill capacity, exposing fabricators to alloy surcharge volatility. Single-source vulnerability concentrates in RTK-GNSS receiver modules. Distribution runs through captive dealer networks and independent agricultural equipment consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Stage V compliance investments in Germany and the United States create export-ready platforms for India's Central Pollution Control Board harmonization without redundant certification spend.
For Market Incumbents: Cement proprietary telematics platform control by integrating edge-computing controllers directly onto implement-mounted architectures, fragmenting data ownership away from tractor OEMs. Lock in recurring service revenue through predictive maintenance contracts that transform dealer relationships from transactional parts sales to uptime guarantees. Defend against autonomous machinery entrants by accelerating RTK-GNSS and machine vision sensor fusion validation. For New Entrants and Emerging Players: Dealer service networks in Brazil's Mato Grosso soybean belt offer the most penetrable channel infrastructure, as technician certification gaps in rural territories distant from OEM technical centers create coverage voids. Target mid-horsepower no-till configurations for Brazilian cerrado soils, where regional metallurgy specialization exceeds multinational platform adaptation speed. Pursue white-label precision agriculture sensor partnerships with established hydraulic fabricators in Gujarat's engineering corridor. For Investors and Strategic Acquirers: Consolidation pressure builds where emissions compliance costs exceed residual equipment value for sub-100 horsepower specialists lacking aftertreatment integration scale. Long-term viability favors diversified industrial conglomerates with captive powertrain capabilities and proprietary data platforms. Monitor carbon credit eligibility rulemaking for precision application equipment as the inflection signal for conventional sprayer and plowing system replacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Guidance System Development | Sensor fusion between RTK-GNSS and machine vision compresses field pass overlap below 2 percent for Iowa and Illinois operators. |
| Precision Agriculture Platform Integration | Subscription-based agronomic data services layered over hardware sales generate the deepest margin pools beyond initial equipment transactions. |
| EU Stage V Dual-Certification Investment | Aftertreatment validation under tropical humidity and temperate freeze-thaw conditions streamlines Atlantic supply chain product architecture planning. |
| Telematics-Enabled Predictive Maintenance | IoT sensor networks transform dealer relationships from transactional parts sales to recurring uptime guarantees for agribusiness fleets. |
| Carbon Credit Eligibility Positioning | Variable-rate sprayers and section-controlled planters embedded in farm sustainability accounting qualify for offset market participation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with OEM procurement teams, aftermarket service directors, agricultural cooperative purchasing managers, and precision agriculture platform engineers with secondary validation against EPA regulatory filings, ANVISA harmonization documentation, EU Stage V technical bulletins, and customs trade data for high-strength steel alloy shipments. Bottom-up equipment shipment tallies and top-down agricultural mechanization penetration rates were cross-referenced for triangulation.
Segment-weighting approaches distributed value projections across product type, application workflow, end-use ownership structure, and technology adoption tier, with CAGRs derived from replacement cycle timing and regulatory phase-out schedules across the analysis window. Forecast inputs incorporated EPA Tier 4 Final fleet turnover velocity, Brazil's Mato Grosso mechanization density gaps, and India's Central Pollution Control Board test cycle alignment progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon credit market development, autonomous machinery regulatory maturation, and high-strength steel alloy surcharge volatility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Agricultural Unit Heaters Market