
 Farm Tractor Market | 2026-2036
Farm Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Tractor Market Intelligence
The expansion of asset-light leasing options for high-horsepower equipment is reshaping market access for agricultural contractors and smaller farm cooperatives. Deere & Company leverages its extensive dealer network and integrated technology stack to maintain a premium position. CNH Industrial N.V. competes through a multi-brand strategy targeting diverse farming scales across different regions. Mahindra & Mahindra Limited dominates the high-volume, small-horsepower segment in South Asia through its focus on durability.
A farm tractor is a self-propelled vehicle engineered to pull or push agricultural implements for farm mechanization. Key functional components include a power take-off (PTO) shaft to transfer engine power and hydraulic systems to operate attached machinery. The 40-80 HP power output segment, primarily comprising utility tractors, commands substantial market volume for applications like fertilizer application. Conversely, row crop tractors above 120 HP represent a growing value segment, driven by demand from large farm cooperatives for land preparation.
Emissions standards, including the EPA's Tier 4 Final in the United States and the EU's Stage V regulations, dictate engine technology and after-treatment system design. In parallel, safety mandates from bodies like India's Bureau of Indian Standards (BIS) for rollover protection structures influence chassis and cab manufacturing requirements. Future investment decisions for manufacturers will hinge on balancing these compliance costs with the development of autonomous and electric tractor platforms.
Market Dynamics
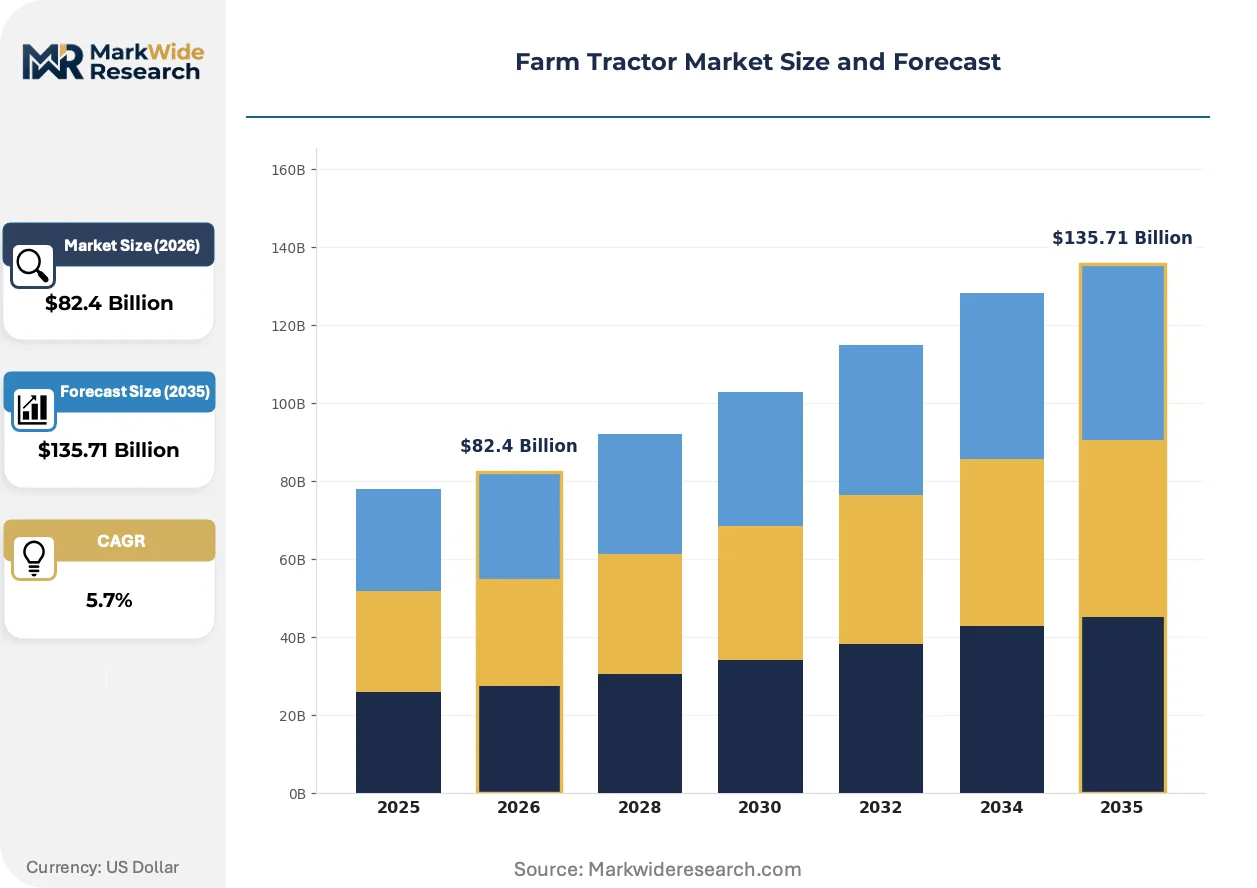
The dual pressure from stringent emissions regulations and large-scale farm demand for higher horsepower equipment defines the central dynamic in the farm tractor market. This forces manufacturers to balance complex engine after-treatment system development with performance expectations from agricultural cooperatives.
Growth Catalysts
- Government Mechanization Subsidies:Financial incentives in countries like India and across Southeast Asia accelerate the adoption of utility and compact tractors, supporting smallholder farm productivity and expanding the addressable market for lower-horsepower segments.
- Precision Agriculture Integration:The adoption of telematics and GPS-guided steering systems drives demand for new tractors, as large farm cooperatives seek to optimize fuel usage, seed placement, and fertilizer application for improved crop yields.
- Farm Consolidation:The trend towards larger farm holdings and cooperative farming models, particularly in the Americas, fuels demand for high-horsepower row crop tractors capable of covering vast acreages efficiently during planting and harvesting.
Market Restraints
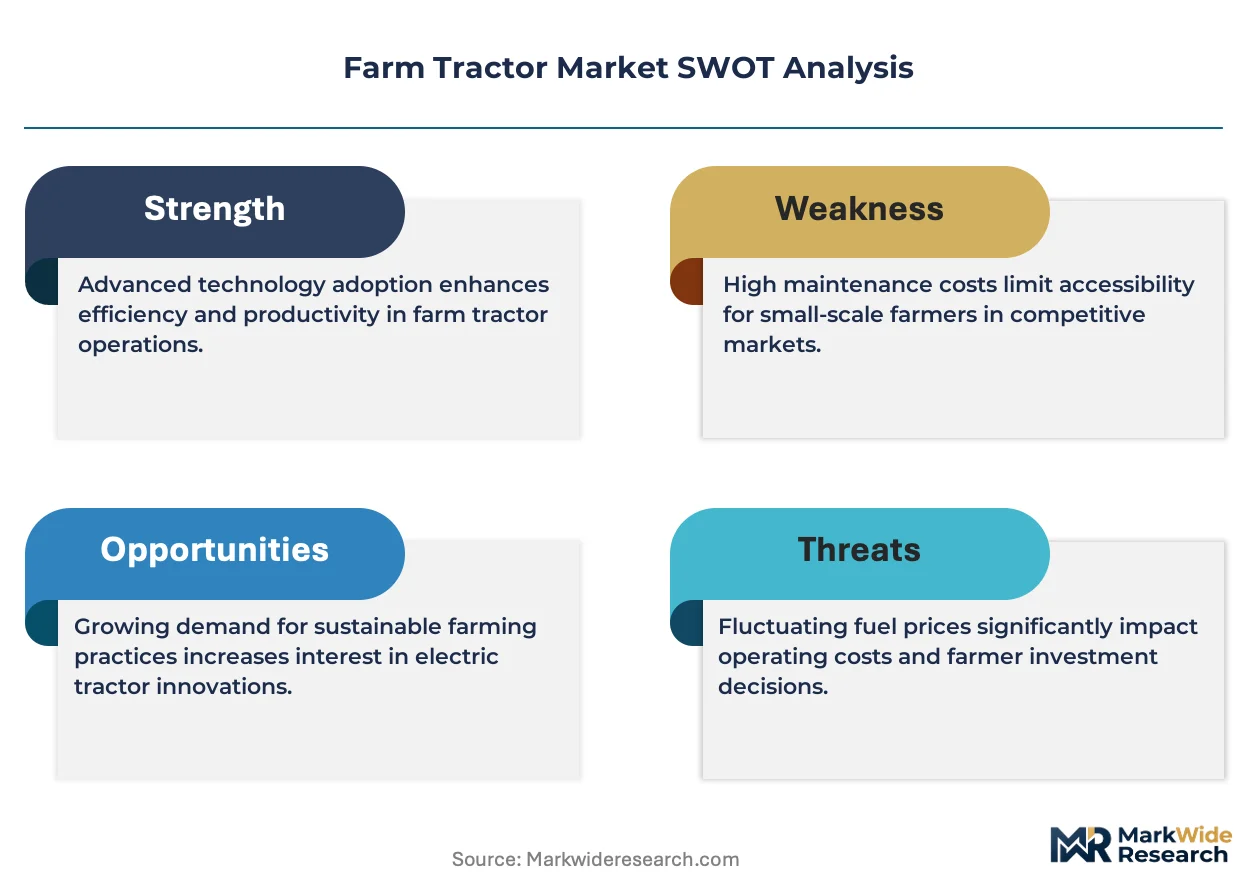
- High Ownership Costs:The substantial capital investment required for high-horsepower tractors, compounded by volatile fuel prices and maintenance expenses, limits purchasing power for smaller independent farms and agricultural contractors.
- Emissions Compliance Costs:Escalating engineering and material costs associated with meeting Tier 4 Final in the United States and Stage V standards in the European Union are passed on to buyers, constricting affordability.
- Semiconductor Dependency:A constrained supply of specialized microchips for engine control units and telematics systems creates production bottlenecks, delaying deliveries and inflating component costs for manufacturers.
Strategic Opportunities
- Electric and Autonomous Platforms:The development of battery-electric compact tractors for specialty farms and autonomous systems for large-scale row crop operations presents a major avenue for value creation and differentiation.
- Equipment-as-a-Service Models:Expanding asset-light leasing and pay-per-use models for high-horsepower equipment can unlock demand from smaller cooperatives and contractors who cannot afford outright purchases.
- African Market Penetration:Under-mechanized agricultural sectors in Sub-Saharan African nations represent a significant long-term growth frontier for durable, low-maintenance utility tractors as food security initiatives expand.
Industry Challenges
- Technician Skill Gaps:A shortage of service technicians qualified to diagnose and repair complex electronic systems, hydraulics, and after-treatment components on modern tractors strains dealer networks and increases equipment downtime for farmers.
- Multi-Jurisdictional Compliance:Manufacturers face significant operational complexity in managing distinct engine, safety, and data privacy regulations across the US, EU, and India, increasing R&D and administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Tractor Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $135.71 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Utility Tractors, Row Crop Tractors, Orchard Tractors, Garden Tractors, Compact Tractors Power Output: Below 40 HP, 40-80 HP, 81-120 HP, Above 120 HP Application: Land Preparation, Crop Planting, Harvesting Support, Fertilizer Application End User: Farm Cooperatives, Individual Farmers, Agricultural Contractors, Agricultural Research Centers |
| Companies Covered | Deere & Company, Mahindra & Mahindra Limited, CNH Industrial N.V., AGCO Corporation, Kubota Corporation, CLAAS KGaA mbH, Escorts Kubota Ltd., TAFE Ltd., Yanmar Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Tractor Market Strategic Shifts & Innovations
Data-centric operational models and the pursuit of autonomous functionality are fundamentally altering tractor design and utility. The vehicle is evolving from a purely mechanical asset into an intelligent, connected node within a larger farm management ecosystem.
Onboard telematics systems integrate GPS, engine diagnostics, and implement data into a single stream. Large-scale farm cooperatives are rapidly adopting these platforms to monitor fleet performance and automate record-keeping. This integration of operational data is collapsing the traditional separation between machine management and agronomic decision-making, creating a unified farm intelligence loop.
India's Bureau of Indian Standards (BIS) has mandated the implementation of rollover protection structures (ROPS) on new tractors to enhance operator safety. This regulation forces significant changes in chassis and cab design, adding weight and cost to tractors sold in the high-volume Indian market. The small-horsepower segment is most affected, requiring manufacturers to re-engineer cost-sensitive models to meet new structural integrity requirements.
Farmers are increasingly favoring short-term rental and long-term leasing agreements over outright ownership for specialized, high-horsepower equipment. This shift disrupts the traditional dealer-centric sales model, creating an opening for manufacturer-backed financing arms and independent rental fleet operators. The trend is most pronounced in North American and European markets for tasks like land preparation, where equipment utilization is seasonal.
Farm Tractor Market Segmentation
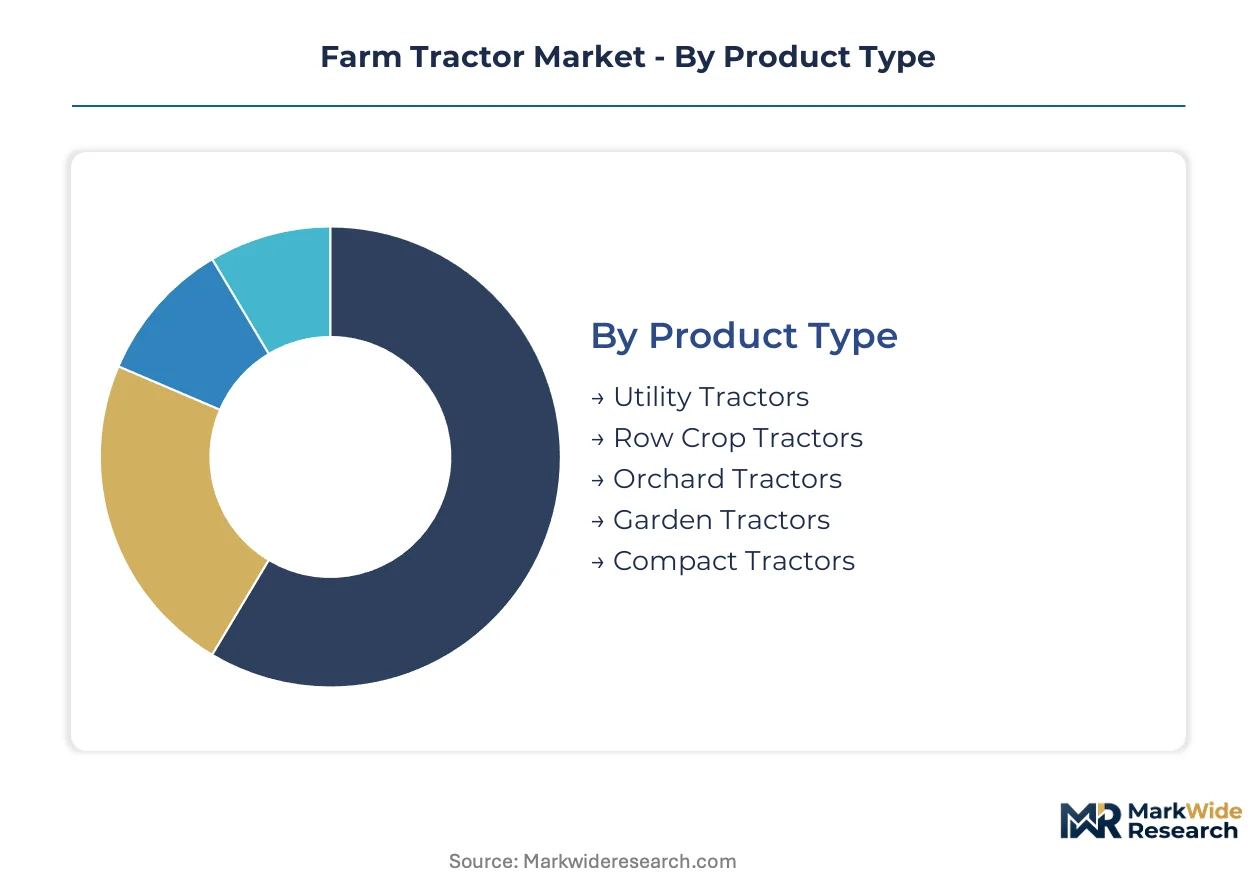
Understanding the farm tractor market through its segmentation highlights the specialized equipment demands across different agricultural applications and farm sizes. This granular view reveals distinct product preferences and technological requirements, from small-scale utility tasks to large-acreage crop production.
Product Type:
The product type segmentation delineates the farm tractor market based on the primary agricultural tasks and operational environments they are designed to address.
- Utility Tractors:These versatile machines typically range from 40-100 HP, designed for general farm tasks like tilling, hauling, and loader work. Demand concentrates in India and Southeast Asia, supporting diverse small to medium-scale farming operations.
- Row Crop Tractors:Characterized by high ground clearance and adjustable wheel spacing, these tractors exceed 120 HP, engineered for cultivating crops planted in rows. Large farm cooperatives in the Americas drive demand for their efficiency in extensive land preparation and planting.
- Orchard Tractors:Compact and low-profile, these tractors navigate narrow rows in orchards and vineyards, preventing damage to trees and vines.
- Garden Tractors:Smaller units, often below 20 HP, are used for residential landscaping and light-duty gardening tasks.
- Compact Tractors:These tractors, typically under 40 HP, offer versatility for small farms and specialty agriculture, with strong demand in developing markets.
The dominant share belongs to Utility Tractors, while Row Crop Tractors represents the fastest-growing trajectory.
Power Output:
Power output segmentation in the farm tractor market directly correlates with the volume and intensity of agricultural work performed, influencing equipment selection for diverse farm operations.
- 40-80 HP:This segment primarily comprises utility tractors, offering a balance of power and maneuverability for diverse tasks including fertilizer application and light tillage. This power range commands substantial market volume in developing economies like India, where mechanization is expanding.
- Above 120 HP:These high-horsepower tractors are essential for large-scale operations, powering heavy implements for deep tillage and rapid harvesting across vast acreages. Large farm cooperatives in North America and Europe are significant consumers, seeking efficiency gains.
- Below 40 HP:This segment includes compact and garden tractors, serving small farms and specialty agriculture with basic mechanization needs.
- 81-120 HP:Mid-range tractors in this category support medium-sized farms with tasks requiring more power than utility models but less than heavy row crop units.
The 40-80 HP segment holds the largest market share, with the Above 120 HP category demonstrating significant expansion.
Application:
The application segmentation illustrates how farm tractors are specialized for distinct stages of the crop cycle, optimizing efficiency for specific agricultural processes.
- Land Preparation:This application involves primary and secondary tillage, plowing, and harrowing, requiring robust tractors with significant pulling power. Demand from large farm cooperatives for high-horsepower row crop tractors is substantial for efficient field readiness.
- Harvesting Support:Tractors in this segment assist combine harvesters, transport crops, and manage post-harvest residue, requiring reliability and adequate power. Telematics integration is increasingly critical for fleet coordination during peak harvest seasons.
- Crop Planting:Tractors are utilized with planters and seed drills for precise seed placement, often integrating GPS-guided steering for optimal yields.
- Fertilizer Application:This involves spreading granular or liquid fertilizers, with utility tractors in the 40-80 HP range commonly used for these tasks.
Land Preparation tasks represent a foundational demand, while Fertilizer Application continues to expand its technological integration.
End User:
End user segmentation reflects the diverse organizational structures and operational scales driving demand for farm tractors across the agricultural ecosystem.
- Farm Cooperatives:These organizations pool resources, driving demand for high-horsepower, technologically advanced tractors and often utilizing asset-light leasing models. Their focus on efficiency and precision agriculture influences equipment choices significantly.
- Individual Farmers:Comprising a vast and diverse group, individual farmers often prioritize durability and cost-effectiveness, with demand concentrated in utility and compact tractor segments. Government subsidies in countries like India directly impact their purchasing power.
- Agricultural Contractors:These service providers operate specialized equipment for multiple farms, often favoring high-horsepower machines and leasing options to manage capital costs.
- Agricultural Research Centers:These institutions use tractors for experimental farming, requiring versatile models to test new agricultural practices and technologies.
Individual Farmers constitute a broad customer base, whereas Farm Cooperatives drive demand for advanced, high-horsepower machinery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry characterizes the farm tractor market, with high-volume, cost-sensitive demand in India contrasting sharply with premium, high-horsepower segment expectations in North America. This bifurcation influences manufacturing strategies and product development across different geographies. Manufacturers adapt product portfolios to meet distinct regional agricultural practices and economic conditions.
India
Government mechanization subsidies accelerate the adoption of utility and compact tractors, supporting smallholder farm productivity. The Bureau of Indian Standards (BIS) mandates rollover protection structures, influencing chassis and cab design for local manufacturers. Delhi and Chennai serve as key manufacturing hubs, concentrating production for the domestic and export markets.
United States
Farm consolidation drives demand for high-horsepower row crop tractors, enabling efficient coverage of vast acreages. The Environmental Protection Agency's (EPA) Tier 4 Final regulations dictate engine technology and after-treatment systems for all equipment. The Midwest, particularly states like Iowa and Illinois, represents a significant market for large-scale agricultural machinery.
Germany
Precision agriculture integration, including telematics and GPS-guided steering, drives demand for technologically advanced tractors. The European Union's (EU) Stage V emissions regulations impose stringent requirements on engine design and after-treatment systems. Bavaria and Baden-Württemberg host significant agricultural machinery manufacturers and research centers.
Brazil
Large-scale farming operations and expanding agricultural land fuel demand for robust, high-horsepower equipment. Government programs promote agricultural modernization and provide financing for tractor purchases. The southern states, including Rio Grande do Sul and Paraná, are major agricultural regions and centers for tractor sales.
France
Demand for high-horsepower tractors stems from large farm cooperatives and extensive grain and sugar beet cultivation. Strict EU safety and environmental standards apply to all agricultural machinery sold within the country. The regions of Nouvelle-Aquitaine and Grand Est are important agricultural areas, driving equipment sales and service.
Farm Tractor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical sub-assemblies. The market exhibits a tiered structure, with a few global full-line manufacturers dominating the high-horsepower segments and numerous regional players specializing in compact and utility tractors. Strategic partnerships for technology development and geographic expansion into emerging markets are dominant competitive moves.
Global multi-brand strategists like CNH Industrial N.V. occupy a position serving diverse farming scales across various regions. Deere & Company exemplifies a premium full-line manufacturer, leveraging an extensive dealer network and integrated technology stack. Mahindra & Mahindra Limited, meanwhile, represents a high-volume, small-horsepower segment specialist, primarily focusing on durability for South Asian markets.
| Leading Market Players |
|---|
| Deere & Company |
| Mahindra & Mahindra Limited |
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| CLAAS KGaA mbH |
| Escorts Kubota Ltd. |
| TAFE Ltd. |
| Yanmar Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Emissions compliance costs determine both pricing tier spreads and the supply chain shape for engine technology components. This risk influences manufacturers' investment in after-treatment systems and their ability to differentiate product offerings.
Pricing Analysis
Industrial OEM buyers anchor pricing structures for specialized components, often through long-term supply agreements. The dominant pricing model is per-unit transactional, influenced by volume commitments. Brand premium and after-sales service bundling are key differentiation drivers, especially for high-horsepower equipment. Pricing softness stems from intense competition in the utility tractor segment, driven by high-volume demand in India. Individual farmers are highly price-sensitive, while large farm cooperatives prioritize value-based pricing for advanced features and efficiency gains.
Supply Chain Analysis
Specialized microchips for engine control units and telematics systems represent a critical upstream feedstock dependency. Supply concentrates in Taiwan, South Korea, and China for these electronic components. Steel, specialized plastics, and advanced electronic components are critical inputs for tractor manufacturing. Semiconductor dependency creates a structural risk of production bottlenecks and inflated component costs. Downstream distribution runs primarily through extensive dealer networks, supplemented by direct sales for large fleet purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The farm tractor market is at a platform-economics inflection, transforming from mechanical assets to intelligent, connected nodes. This shift is driven by the integration of telematics and precision agriculture data into unified farm intelligence ecosystems.
For Market Incumbents: Build a proprietary data ecosystem moat by integrating telematics, GPS, and implement data across their extensive dealer networks. This defends against emerging autonomous farming solution providers and margin pressure from component specialists. Investment in advanced hydraulics and after-treatment systems strengthens their core offering.
For New Entrants and Emerging Players: Battery-electric compact tractors for specialty farms represent the most penetrable entry point, capitalizing on niche demand for low-emission, quiet operations. Focus on developing autonomous systems for specific tasks like orchard spraying offers a distinct go-to-market angle. This approach avoids direct competition with high-horsepower incumbents.
For Investors and Strategic Acquirers: The market sits at a modernization phase that favors technology-forward integrators capable of delivering full-stack precision agriculture solutions. Long-term viability over the next 5-10 years rests on adopting electric and autonomous platforms. Acquisition targets should be specialized software firms or compact electric tractor developers. The signal to watch is accelerating regulatory approval for autonomous field operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies machine management and agronomic decision-making for large farm cooperatives. |
| Electric Tractor Development | Addresses emissions standards and specialty farm demand for sustainable solutions. |
| Asset-Light Leasing Expansion | Unlocks market access for smaller cooperatives and agricultural contractors. |
| African Market Penetration | Capitalizes on under-mechanized agricultural sectors for durable utility tractors. |
| Autonomous System Investment | Enhances efficiency and reduces labor costs for large-scale row crop operations. |
Research Approach
The analysis maps utility tractors, row crop tractors, and compact tractors, each validated through extensive primary interviews with agricultural engineers, farm cooperative managers, and dealer network executives. Secondary data sources included government agricultural reports, industry association publications, and company financial filings. This involved bottom-up data aggregation and top-down market sizing.
Assumptions regarding regulatory stability and technological adoption rates were held fixed across the analysis window, while variations in commodity prices and mechanization subsidy levels were modeled. Segmentation dimensions included product type, power output, application, and end user, alongside regional market dynamics. Compound annual growth rates were derived from historical trends and projected demand drivers. Key forecast inputs included agricultural land utilization.
Stress conditions across semiconductor supply availability and global fuel price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions, acknowledging that unforeseen geopolitical events could revise projections. Cross-checking against national agricultural statistics bureaus is advised.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Garden and Orchard Tractors Market