
 United States Haying and Forage Machinery Market | 2026-2036
United States Haying and Forage Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Haying and Forage Machinery Market Analytics
Dairy farm consolidation across the Upper Midwest is repositioning demand toward high-capacity balers and self-propelled forage harvesters. Deere & Company leverages its integrated precision agriculture platform to anchor premium segment positioning in automated haying systems. AGCO Corporation competes through specialized Fendt and Massey Ferguson product lines tailored to regional crop conditions. CNH Industrial sustains manufacturing scale via its Grand Island, Nebraska production footprint for large square balers.
United States haying and forage machinery encompasses field equipment engineered to cut, condition, rake, bale, and harvest hay, silage, and forage crops with working widths ranging from six to forty feet and throughput capacities exceeding one hundred tons per hour. These machines serve livestock producers by preserving nutritional value in stored feed while minimizing field losses and labor requirements. Forage harvesters and large square balers command the deepest margin pools as dairy operations prioritize speed and density for silage preservation and transport efficiency. Mowers and rakes maintain steadier replacement cycles but face pressure from integrated mower-conditioner combinations that reduce pass counts. Automated technology segments attract disproportionate R&D investment as labor scarcity intensifies across the Great Plains and Mountain West.
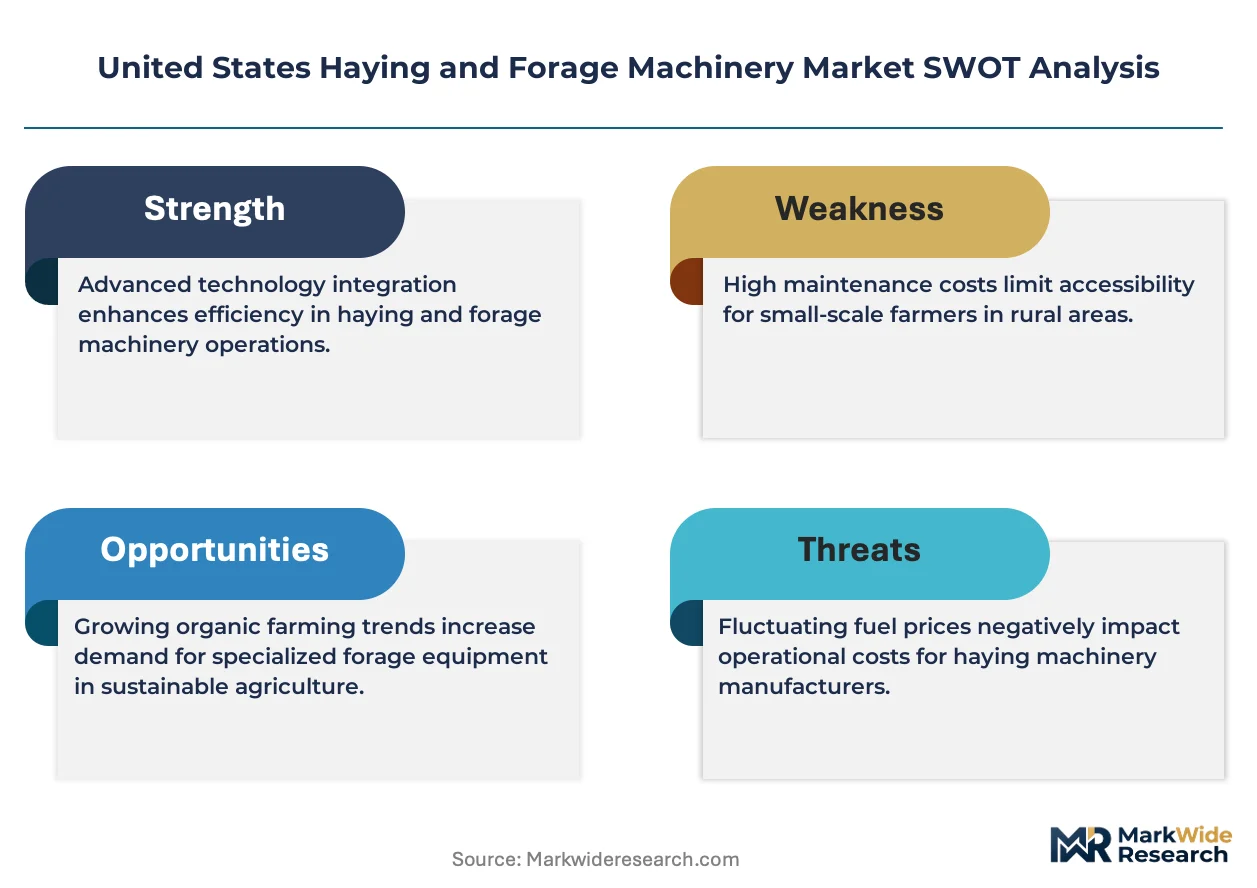
Federal EPA Tier 4 Final emission standards constrain engine design choices and compliance costs for diesel-powered harvesters and self-propelled equipment. USDA conservation programs and state-level nutrient management regulations in Wisconsin, California, and New York influence timing of equipment purchases tied to cover cropping and manure handling integration. OSHA agricultural machinery safety standards affect guarding, PTO shielding, and operator training requirements that manufacturers must incorporate. Stakeholders should monitor how precision fermentation and alternative protein investments reshape long-term forage acreage commitments and equipment replacement cycles.
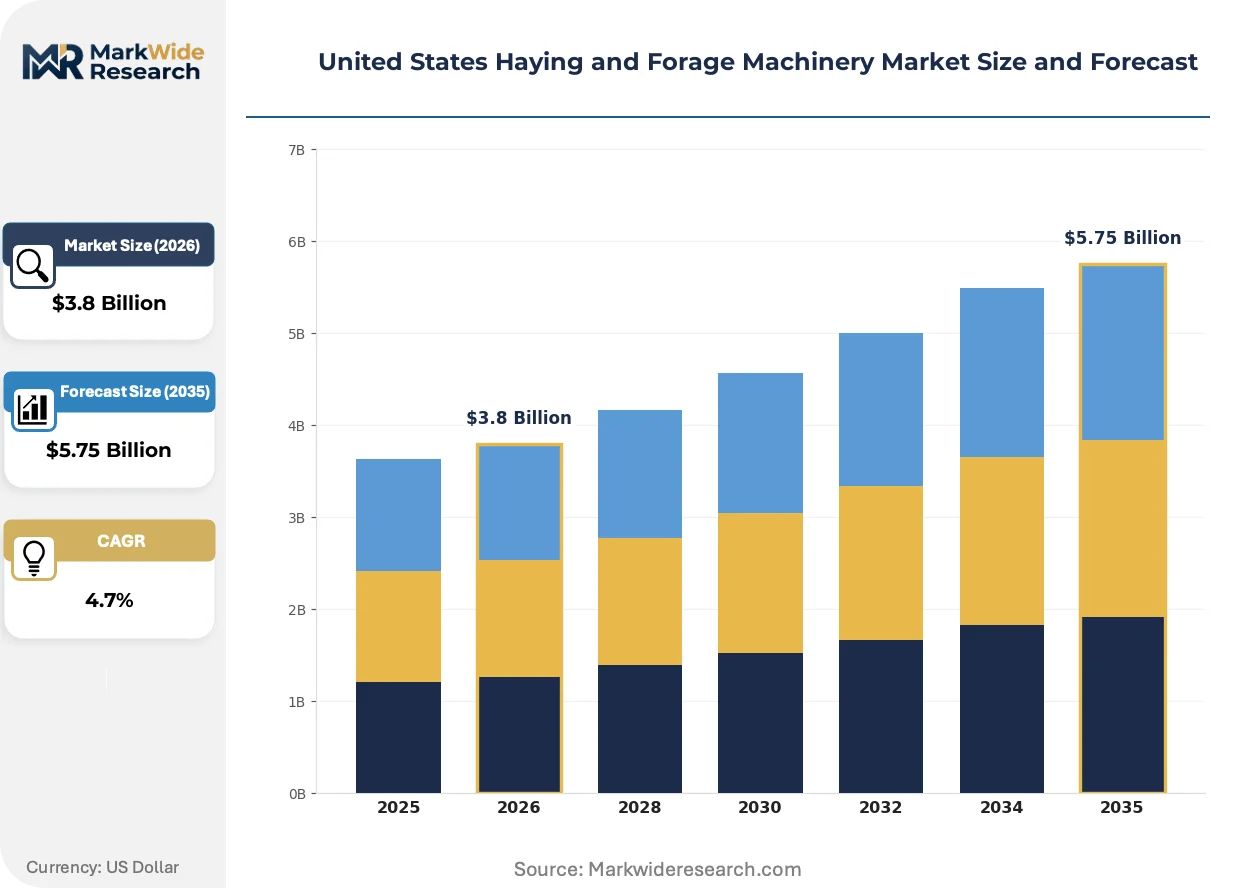
Market Dynamics
Dairy herd consolidation across Wisconsin, Minnesota, and Iowa is compressing equipment replacement cycles while elevating specifications for throughput density and autonomous operation. This structural concentration favors machinery capable of sustained high-volume output across fewer but larger acreage footprints.
Growth Catalysts
- USDA Conservation Reserve Program incentives:Cover cropping mandates in the Corn Belt are accelerating mower-conditioner upgrades to handle diverse biomass mixes within shortened planting windows.
- Autonomous guidance systems:GPS-RTK steering is reducing operator fatigue during extended harvest windows across Montana and Idaho hay operations.
- Nebraska dairy cooperatives:These consolidated buyers are specifying large square balers with automated twine-wrapping and moisture-sensing capabilities.
Market Restraints
- EPA Tier 4 Final compliance costs:Diesel exhaust fluid systems and selective catalytic reduction hardware add substantial capital burden to self-propelled harvester platforms.
- Steel and hydraulic component volatility:Input cost swings compress manufacturer margins on mid-range equipment lines.
- Precision fermentation feed alternatives:Laboratory-cultured protein sources threaten long-term forage acreage commitments in California and New York dairy regions.
Strategic Opportunities
- Mountain West hay exporters:Underpenetrated demand in Utah and Colorado alfalfa operations serving Asian dairy markets offers expansion vectors for high-density baler systems.
- OSHA agricultural safety mandates:Enhanced PTO guarding and operator-presence sensor requirements create retrofit and replacement revenue streams.
- Telematics-to-blockchain integration:Converging fleet data platforms with supply chain traceability tools enables premium pricing for verified sustainable hay sourcing.
Industry Challenges
- Certified diesel technician scarcity:EPA-mandated aftertreatment complexity outpaces vocational training pipeline capacity across rural service territories.
- Legacy fleet integration friction:Retrofitting older tractors with ISOBUS-compatible implements requires costly adapter modules and dealer reprogramming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Haying and Forage Machinery Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balers, Mowers, Rakes, Forage Harvesters Application: Dairy Farms, Livestock Farms, Commercial Operations, Personal Use Technology: Machine-Driven, Manual, Semi-Automatic, Automated End User: Agricultural Producers, Agricultural Cooperatives, Contractors, Hobby Farmers |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, CLAAS KGaA mbH, Kubota Corporation, KUHN Group, PÖTTINGER Landtechnik GmbH, Vermeer Corporation, Krone North America Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Haying and Forage Machinery Market Evolving Landscape
Automation density is accelerating across haying workflows as labor availability tightens and dairy margins compress operational tolerance for inefficiency. Three distinct vectors are reshaping equipment specifications and procurement priorities.
Variable-chamber baling technology is overtaking fixed-chamber designs in large-scale dairy operations. These systems adjust bale density in real-time based on crop moisture and transport distance requirements. Upper Midwest cooperatives are specifying this capability as standard equipment. The shift is compressing residual value for older fixed-chamber fleets and forcing faster depreciation schedules.
EPA Tier 4 Final emission standards are constraining engine architecture choices for self-propelled forage harvesters. Manufacturers must integrate selective catalytic reduction and diesel particulate filters while maintaining power-to-weight ratios. The Corn Belt states of Iowa, Illinois, and Nebraska face the steepest compliance cost absorption as they host the densest concentration of high-horsepower harvesting equipment.
Equipment-as-a-service contracting is displacing traditional ownership models among mid-scale hay producers. Leasing arrangements bundle maintenance, telemetry, and seasonal optimization into per-acre pricing. This pattern concentrates most visibly across Kansas and Oklahoma where weather volatility makes capital commitment riskier for independent operators.
United States Haying and Forage Machinery Market Segmentation
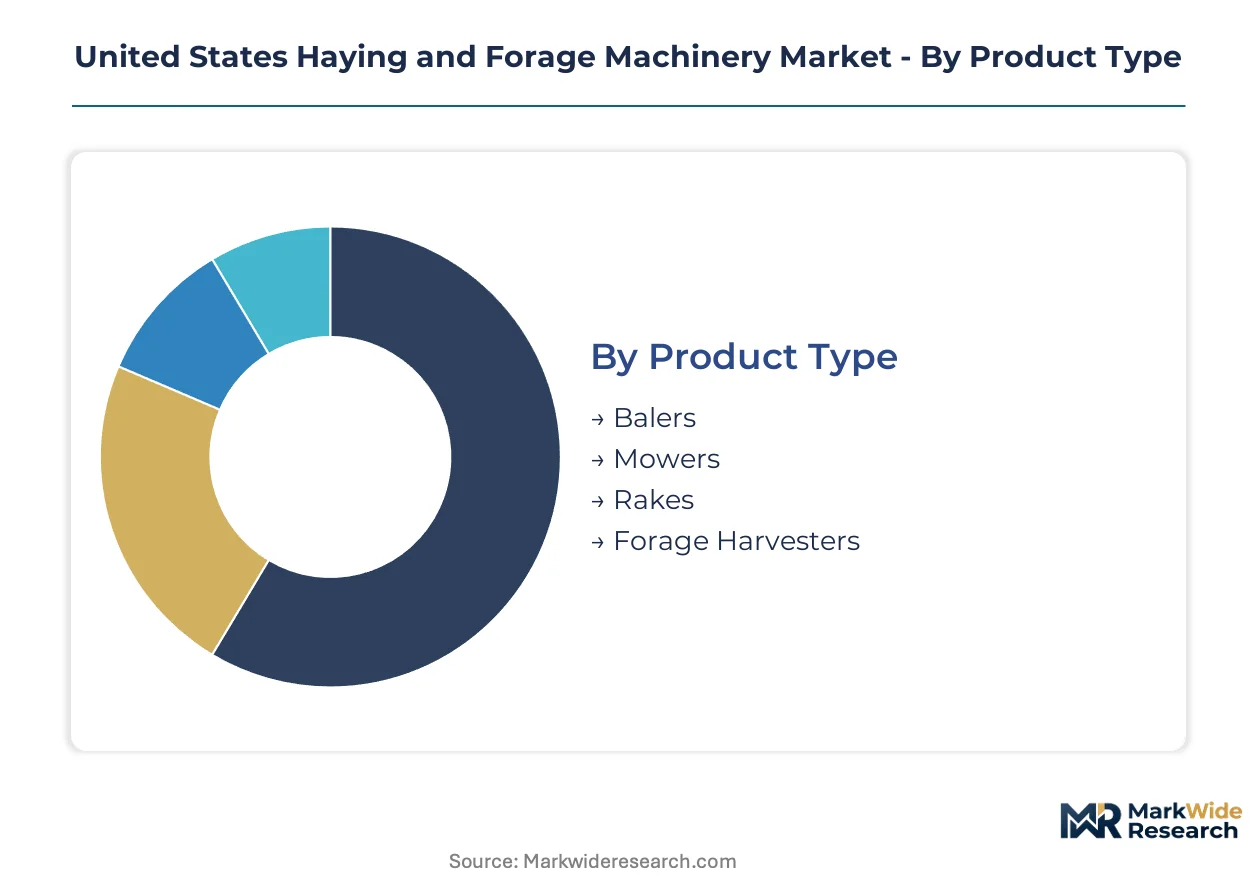
Equipment specification tiers in United States haying and forage machinery diverge sharply between consolidated dairy operations and fragmented livestock holdings. Procurement patterns across these segments determine manufacturer R&D allocation and dealer inventory positioning throughout the Corn Belt and Mountain West.
Product Type:
Cutting width, throughput capacity, and bale density specifications define the technology hierarchy across haying workflows.
- Balers:Large square balers with variable-chamber density control dominate dairy cooperative procurement in Iowa and Nebraska. Upper Midwest operations specify automated twine-wrapping and moisture-sensing as standard features to minimize field losses during compressed harvest windows.
- Forage Harvesters:Self-propelled platforms with working widths exceeding thirty feet command premium positioning among consolidated dairy herds. EPA Tier 4 Final aftertreatment requirements constrain engine architecture choices while elevating capital burden for Wisconsin and Minnesota operators.
- Mowers:Disc mower-conditioner combinations reduce pass counts across Kansas and Oklahoma hay operations. Integrated conditioning accelerates dry-down in humid Corn Belt summers.
- Rakes:Rotary and wheel rakes maintain steadier replacement cycles but face displacement from mower-conditioner integration. Mountain West alfalfa exporters in Utah and Colorado prioritize gentle crop handling for premium dairy markets.
Mature deployment sits with mowers and rakes. Newer deployment is concentrated in large square balers with automated density management.
Application:
Operational scale and feed preservation requirements determine equipment specification intensity across end-use contexts.
- Dairy Farms:Consolidated herds across Wisconsin, Minnesota, and Iowa compress replacement cycles while demanding autonomous guidance and real-time moisture monitoring. Speed and density specifications prioritize silage preservation efficiency.
- Commercial Operations:Custom harvesters serving multiple farm clients specify versatile platforms with rapid implement changeover. Equipment-as-a-service contracting concentrates among these operators in Kansas and Oklahoma where weather volatility elevates capital risk.
- Livestock Farms:Beef cattle operations in the Great Plains maintain longer depreciation schedules on fixed-chamber balers. Labor availability constraints lag behind dairy sector pressures.
- Personal Use:Hobby farmers and small acreage holders in the Mountain West sustain demand for compact tractor-mounted implements. Price sensitivity elevates used equipment procurement through dealer networks.
Technology leadership concentrates in dairy farm procurement. Volume expansion is climbing the fastest among commercial custom harvesters adopting fleet telematics.
Technology:
Automation density correlates directly with labor scarcity severity and operational scale across regional hay production zones.
- Automated:GPS-RTK steering, automated bale ejection, and integrated moisture sensing define premium tier specifications. Nebraska dairy cooperatives mandate these capabilities for new equipment procurement.
- Semi-Automatic:Partial automation with operator-supervised guidance reduces fatigue during extended Montana and Idaho harvest windows. This tier captures mid-scale operators transitioning from manual platforms.
- Machine-Driven:Conventional PTO-powered implements without electronic control systems dominate legacy fleet composition. ISOBUS compatibility friction complicates retrofitting across older tractor populations.
- Manual:Minimal automation persists in small-scale and hobby farm segments where capital constraints outweigh labor cost pressures. Replacement demand concentrates in equipment failure scenarios rather than upgrade cycles.
Margin concentration aligns with automated platforms. Adoption velocity is expanding most quickly in semi-automatic systems bridging capability and cost constraints.
End User:
Purchasing power and fleet standardization requirements segment procurement behavior across buyer categories.
- Agricultural Cooperatives:Consolidated buying power across Iowa, Illinois, and Nebraska enables volume discounts and specification customization. These entities drive adoption of variable-chamber balers and telemetry-integrated harvesters.
- Contractors:Custom operators prioritize equipment utilization rates and rapid serviceability across dispersed rural territories. Telematics-to-blockchain integration enables premium pricing for verified sustainable hay sourcing.
- Agricultural Producers:Independent commercial farms balance ownership economics against leasing alternatives. Equipment-as-a-service penetration varies by regional dealer network sophistication.
- Hobby Farmers:Small-scale operators exhibit price elasticity and extended replacement cycles. Secondary market activity concentrates in this segment throughout the Mountain West.
Procurement volume leadership rests with agricultural cooperatives. Structural growth is gaining share fastest among contractors responding to dairy herd consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Upper Midwest's machinery demand concentrates around USDA-designated dairy production zones spanning Wisconsin, Minnesota, and Iowa. Equipment procurement in these zones accelerates replacement cycles for high-capacity automated systems.
California
Precision fermentation investments in the Central Valley are compressing long-term forage acreage commitments among dairy operators. State-level nutrient management regulations under California's Central Valley Regional Water Quality Control Board mandate manure handling integration with haying equipment purchases. The San Joaquin Valley dairy corridor sustains demand for large square balers with moisture-sensing capabilities serving export markets.
Wisconsin
Dairy herd consolidation across Dane and Brown counties is elevating specifications for autonomous guidance and real-time density monitoring. OSHA agricultural machinery safety standards drive retrofit demand for PTO guarding and operator-presence sensors. The Fox Valley manufacturing cluster anchors regional dealer networks for precision haying platforms.
Iowa
USDA Conservation Reserve Program incentives accelerate mower-conditioner upgrades for cover cropping mandates across the Corn Belt. EPA Tier 4 Final emission standards constrain engine architecture choices for self-propelled harvesters operating statewide. The Des Moines-Ames corridor hosts dense concentrations of agricultural cooperatives specifying variable-chamber balers.
Nebraska
Consolidated dairy cooperatives in the Platte River Valley mandate automated twine-wrapping and telemetry-integrated harvesters for new equipment procurement. Federal conservation compliance requirements influence timing of purchases tied to residue management. The Grand Island production footprint sustains manufacturing scale for large square baler systems serving regional export demand.
Colorado
Mountain West alfalfa exporters in the Arkansas River Valley prioritize gentle crop handling for premium Asian dairy markets. Labor scarcity across the Eastern Plains accelerates adoption of GPS-RTK steering systems. The Greeley-Windsor corridor concentrates custom harvester operations adopting equipment-as-a-service contracting models.
United States Haying and Forage Machinery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated full-line producers commanding premium positioning in automated systems while regional fabricators capture mid-tier replacement demand. The market structure tilts toward consolidation among three domestic manufacturers with Corn Belt production footprints. Strategic archetypes include precision-technology integrators, specialized haying equipment pure-plays, and diversified agricultural machinery conglomerates. Dominant competitive moves center on precision agriculture platform integration and geographic expansion through dealer network consolidation.
Within the integrated-technology tier, Deere & Company exemplifies the precision-platform anchor archetype through its dominance in automated haying workflows. AGCO Corporation occupies a position bridging specialized regional adaptation with multi-brand portfolio breadth. CNH Industrial anchors manufacturing scale advantages through its Nebraska production concentration for high-capacity baler systems.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| CLAAS KGaA mbH |
| Kubota Corporation |
| KUHN Group |
| PÖTTINGER Landtechnik GmbH |
| Vermeer Corporation |
| Krone North America Inc. |
| Others |
Value Network & Pricing Analysis
Steel and hydraulic component volatility propagates through tiered equipment pricing as Corn Belt manufacturers absorb input cost swings into margin compression rather than list price escalation. EPA Tier 4 Final aftertreatment hardware elevates baseline production costs for self-propelled harvesters, forcing three-tier pricing stratification across premium automated platforms, standard PTO-driven implements, and economy compact lines.
Pricing Analysis
Lead-time premiums compress as Nebraska dairy cooperatives demand immediate availability of telemetry-integrated large square balers during compressed harvest windows. Three-tier pricing structure across premium, standard, and economy levels separates ISOBUS-compatible automated systems from semi-automatic platforms and legacy PTO implements. Pricing pressure stems from certified diesel technician scarcity elevating service contract bundling costs. Hobby farmers in the Mountain West exhibit highest price sensitivity, while consolidated Iowa agricultural cooperatives prioritize specification compliance over unit economics.
Supply Chain Analysis
Freight cost elevation from German and Austrian component suppliers compresses margins on precision guidance systems imported for Upper Midwest assembly. Domestic manufacturing draws from Corn Belt steel mills, Nebraska hydraulic component fabricators, and Tennessee engine production for EPA-compliant powertrains. Single-source vulnerability concentrates in selective catalytic reduction catalyst supply from German specialty chemical producers. Distribution runs through John Deere and AGCO dealer networks anchoring parts availability across rural Wisconsin and Minnesota service territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final emission standards construct a cost-of-compliance moat that favors incumbent manufacturers with captive aftertreatment engineering capabilities and burdens prospective entrants with capital-intensive certification barriers.
For Market Incumbents: Extend precision agriculture platform integration into telemetry-to-blockchain hay sourcing verification, capturing premium pricing from California and New York dairy export corridors. Defend against precision fermentation feed alternatives by anchoring equipment financing to long-term forage acreage commitments. Capacity addition in Nebraska sustains manufacturing scale advantages for large square baler production serving Asian dairy markets. For New Entrants and Emerging Players: Launch via equipment-as-a-service contracting models targeting Kansas and Oklahoma custom harvesters weather-volatility-averse to capital commitment. White-space concentration sits with retrofit ISOBUS adapter modules for legacy tractor fleets across the Great Plains. Mountain West alfalfa exporters in Utah and Colorado represent the most penetrable geography for high-density baler systems with gentle crop handling specifications. For Investors and Strategic Acquirers: Consolidation of dairy cooperatives in the Platte River Valley is the leading indicator that automated twine-wrapping and moisture-sensing capability mandates will accelerate replacement cycle compression across the Corn Belt. Five-to-ten-year viability favors manufacturers with integrated precision agriculture platforms over specialized haying equipment pure-plays. Acquisition targets should demonstrate EPA certification completion and established dealer service networks in rural territories.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Deere's automated haying workflows anchor premium segment positioning against AGCO's regional adaptation. |
| Telematics-to-Blockchain Convergence | Fleet data platforms enable verified sustainable hay sourcing premiums from California dairy exporters. |
| Equipment-as-a-Service Contracting | Per-acre pricing models reduce capital risk for Kansas and Oklahoma custom harvesters facing weather volatility. |
| EPA Tier 4 Final Compliance Completion | Aftertreatment certification barriers protect incumbent manufacturers from emerging competitor entry. |
| Dealer Network Consolidation | Service territory density in Wisconsin and Minnesota determines aftermarket parts capture rates. |
Research Methodology
USDA NASS machinery sales reports, EPA certification filings, and agricultural cooperative procurement records formed the secondary backbone validating shipment volumes and specification trends. Primary interviews with haying equipment product managers, Corn Belt dealer service heads, dairy farm operations directors, and hydraulic component procurement leads at Nebraska manufacturing facilities triangulated demand drivers against secondary trade flow data. Bottom-up equipment unit economics and top-down agricultural machinery sector aggregates were reconciled across the analysis window.
Historical trendline analysis of replacement cycle compression and technology adoption curves informed projection modeling across product type, application, technology tier, and end-user segmentation. CAGRs were derived from equipment shipment trajectories, dairy herd consolidation rates, and regulatory compliance cost absorption patterns. Forecast inputs incorporated EPA Tier 4 Final penetration timelines, autonomous guidance system adoption velocity, and precision fermentation feed alternative threat assessment throughout the projection horizon.
Commodity price volatility in steel and hydraulic components, dairy margin compression accelerating or delaying capital expenditure, and alternative protein investment flows disrupting long-term forage acreage commitments are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Rotary Tiller Market