
 Power Tiller Market | 2026-2036
Power Tiller Market Size, Share, and Industry Trends Forecast 2026-2036
Power Tiller Market Outlook
Dealer networks across rural South Asia are reshaping how power tillers reach end users, with farm equipment cooperatives and agri-input retailers now handling last-mile distribution alongside traditional outlets. Kubota Corporation leverages its established parts-and-service infrastructure to sustain loyalty among rice-cultivating regions. V.S.T. Tillers Tractors Ltd. anchors the Indian domestic market through cost-engineered designs purpose-built for sub-acre plots. Greaves Cotton Limited competes on diesel engine reliability for rental contractors operating across multiple villages.
A power tiller is a walk-behind, two-wheel tractor unit typically powered by single-cylinder engines in the 3–12 horsepower range, designed to pull rotary tillers, plows, seeders, and trailers through narrow field corridors inaccessible to four-wheel tractors. Its primary commercial purpose is mechanized soil preparation and intercrop cultivation on holdings below two hectares. Mini tillers lead unit shipments across terraced and greenhouse applications where maneuverability limits equipment size. Diesel variants still dominate revenue pools in commercial farming, though electric fuel types are gaining fastest among landscapers and suburban homeowners facing noise and emissions restrictions. Paddy tillers occupy a specialized niche with flooded-field transmissions and rust-resistant hardware that command premium pricing over standard garden configurations.
India's Central Pollution Control Board enforces Bharat Stage emission norms that push manufacturers toward cleaner combustion architectures, while the Bureau of Indian Standards certifies safety and performance benchmarks for agricultural power tillers sold domestically. The EU F-Gas Regulation and REACH chemical standards constrain export-oriented producers sourcing certain gasket materials and refrigerants for related equipment lines. Stakeholders must monitor how subsidy eligibility criteria evolve for electric farm machinery, as qualification thresholds will determine which product architectures warrant R&D allocation versus incremental improvement of fossil-fuel platforms.
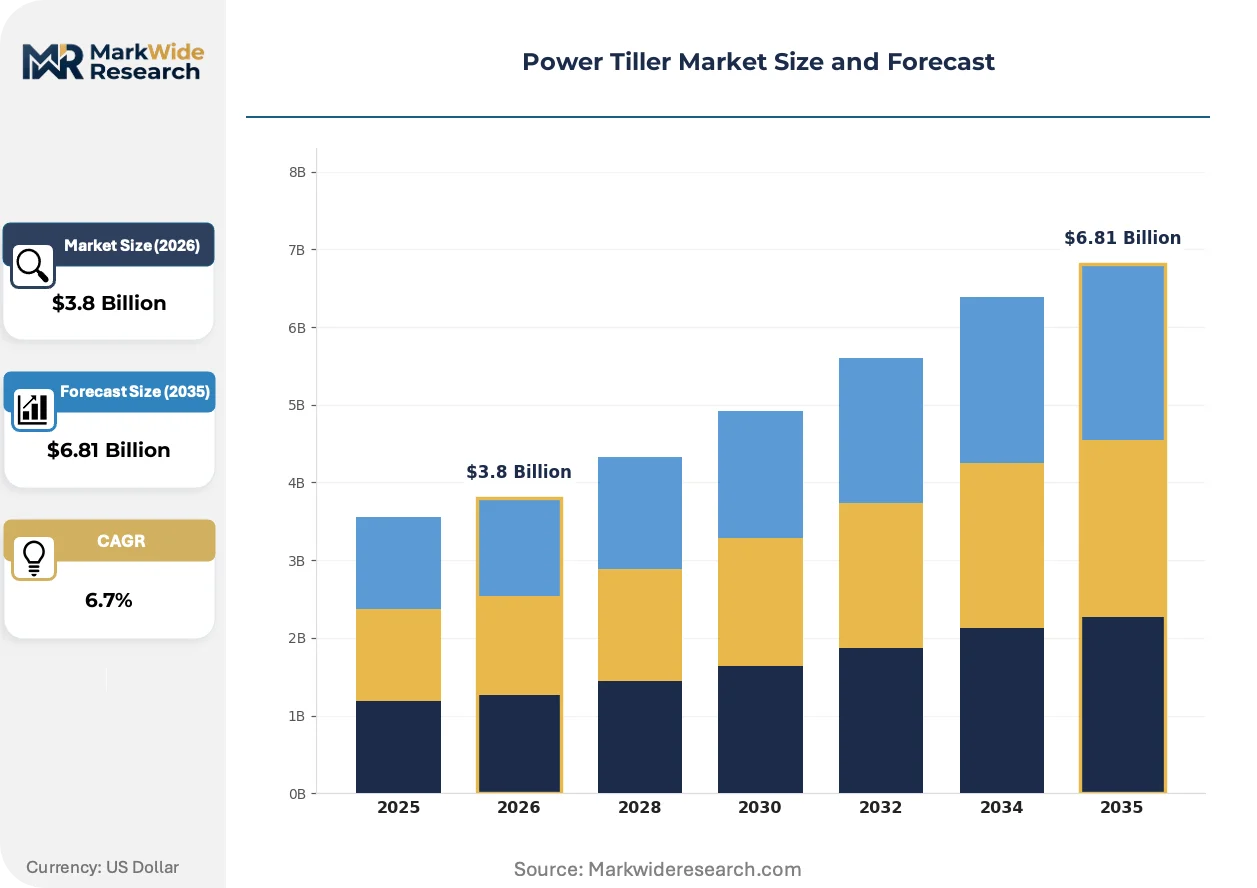
Market Dynamics
India's PLI scheme for farm machinery and tightening Bharat Stage emission norms are compressing diesel tinker margins while accelerating electric platform development across South Asian manufacturing corridors.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for farm machinery manufacturing draw component suppliers toward domestic electric drivetrain assembly, reducing import dependency for battery packs and controllers.
- Smallholder mechanization:Fragmented land holdings across Bangladesh and Vietnam favor walk-behind equipment over four-wheel tractors, concentrating demand for sub-10 horsepower units in rice-cultivating belts.
- Emissions standard convergence:Bharat Stage norms and EU F-Gas Regulation jointly pressure manufacturers to re-engineer combustion architectures and gasket materials for cleaner export eligibility.
Market Restraints
- Steel and aluminum input volatility:Chassis and engine block fabrication costs fluctuate with commodity pricing, squeezing margin buffers for price-sensitive domestic Indian producers.
- Component supply concentration:Precision gearboxes and hydrostatic transmissions concentrate among Japanese and Korean tier-one suppliers, exposing assemblers to lead time variability.
- Lead-acid battery substitution ceiling:Lithium-ion energy density advantages in electric tillers face cost barriers for rental contractors operating thin-margin equipment pools across multiple villages.
Strategic Opportunities
- Greenhouse and horticulture penetration:Mini tiller configurations for protected cultivation in Vietnam and Bangladesh command premium positioning against manual labor in high-value vegetable supply chains.
- Agri-input retailer channel expansion:Seed and fertilizer cooperatives in rural India now stock tillers alongside inputs, collapsing traditional dealer network layers for faster rural reach.
- Subsidized electric farm machinery eligibility:Evolving qualification thresholds for state-level clean equipment incentives will determine which battery architectures warrant dedicated R&D allocation versus fossil-fuel platform refinement.
Industry Challenges
- Field technician scarcity:Diagnostic and repair capabilities for electronic fuel injection and battery management systems lag behind mechanical engine expertise in India's rural service infrastructure.
- BIS certification timelines:Bureau of Indian Standards safety and performance benchmarking creates product launch delays for redesigned models targeting seasonal agricultural windows.
- After-sales parts inventory:Maintaining stocked depots for rust-resistant paddy transmission components across dispersed rice-cultivating districts strains working capital for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Tiller Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Tiller, Handheld Tiller, Garden Tiller, Paddy Tiller Fuel Type: Gasoline, Diesel, Electric, Propane End User: Farmers, Landscapers, Homeowners, Agricultural Contractors Application: Intercropping, Soil Preparation, Weeding, Garden Maintenance |
| Companies Covered | V.S.T. Tillers Tractors Ltd., Kubota Corporation, Honda Motor Co., Ltd., Yanmar Co., Ltd., Deere & Company, TAFE, Mahindra & Mahindra, Greaves Cotton Limited, Kirloskar Oil Engines Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Tiller Market Strategic Shifts
Electrification of walk-behind tractors is compressing the traditional diesel-gasoline duopoly while precision agriculture interfaces and rental contractor business models reshape how smallholders access mechanized tillage.
Brushless DC motor systems paired with lithium-iron-phosphate battery packs are rendering obsolete the recoil-start gasoline engines that dominated greenhouse and terraced applications. Landscape maintenance contractors in noise-restricted suburban zones across India and Vietnam now specify electric units for municipal contracts. This powertrain shift is compressing the addressable market for small-displacement internal combustion engines below 6 horsepower.
REACH chemical standards and EU F-Gas Regulation constrain gasket material selection and refrigerant use in related equipment lines exported from Indian manufacturing hubs. Producers serving European markets must reformulate seal compounds and validate alternative cooling chemistries. Paddy tiller configurations with flooded-field transmissions face extended compliance testing cycles, delaying model year refreshes.
Rental contractors operating equipment pools across multiple villages now unbundle after-sales service from original equipment purchase, sourcing maintenance through independent technicians rather than authorized dealer networks. This channel fragmentation in India's rice-cultivating belts reduces manufacturer control over parts revenue streams. Bangladesh and Vietnam exhibit similar contractor-led procurement consolidation, compressing traditional distribution hierarchies.
Power Tiller Market Segmentation
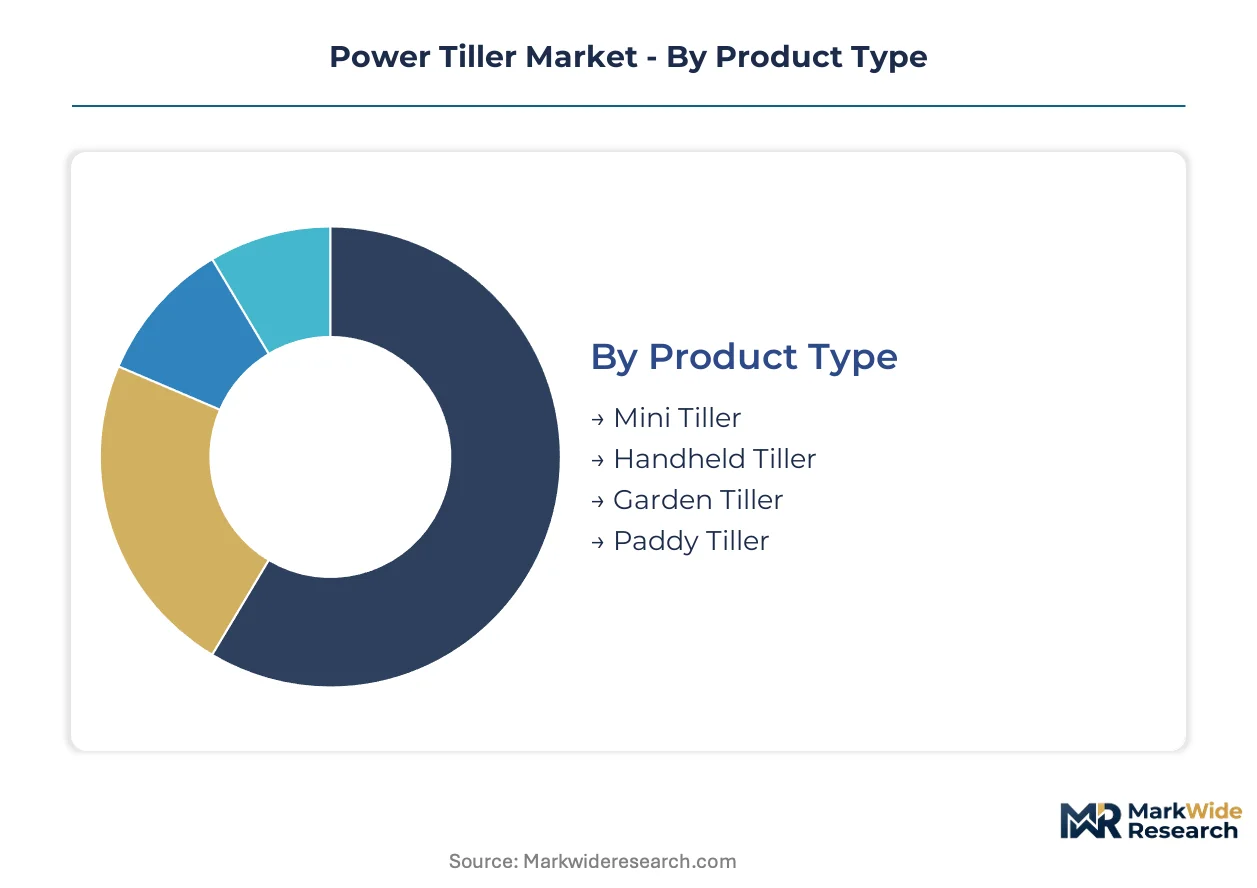
Power tiller segmentation reflects divergent equipment requirements across South Asian rice belts, protected cultivation zones, and suburban maintenance corridors. Fragmented land holdings and emissions regulations are compressing demand into specific horsepower brackets and fuel architectures.
Product Type:
Mini tillers and paddy configurations anchor opposite ends of the use-case spectrum, from terraced vegetable plots to flooded-field rice cultivation.
- Mini Tiller:Compact walk-behind units with sub-5 horsepower ratings and narrow tilling widths navigate greenhouse aisles and terrace contours inaccessible to larger equipment. Vietnamese vegetable cooperatives in Da Lat's highland belts specify these for year-round protected cultivation cycles. Demand concentrates in Bangladesh's riverine char lands where plot fragmentation limits equipment scale.
- Paddy Tiller:Sealed transmissions, rust-resistant hardware, and extended air intakes enable operation in flooded rice paddies without hydrolock or corrosion failure. India's eastern Gangetic plains generate concentrated procurement from rental contractors serving smallholders during kharif season planting windows. Premium pricing over standard garden configurations reflects specialized metallurgy and extended warranty terms.
- Handheld Tiller:Single-operator units weighing under 15 kilograms target raised-bed vegetable plots and orchard interrows.
- Garden Tiller:Mid-range configurations balance residential lawn maintenance with light commercial landscaping duties.
The dominant share belongs to mini tillers in terraced and greenhouse applications, while paddy tillers are closing the gap fastest through rental contractor fleet expansion.
Fuel Type:
Cost tier stratification separates subsidized electric pilots from diesel workhorses serving commercial rental pools.
- Diesel:Single-cylinder compression-ignition engines in the 6-12 horsepower range deliver torque density for primary tillage in clay-heavy soils. Bharat Stage emission norms are forcing injector redesign and exhaust aftertreatment that inflate unit costs for Indian domestic producers. Bangladeshi rental contractors favor diesel reliability for multi-village equipment pools operating on thin maintenance margins.
- Electric:Brushless DC motors paired with lithium-iron-phosphate battery packs eliminate recoil-start maintenance and noise restrictions. Indian municipal landscaping contracts in noise-restricted urban zones specify electric units for compliance with local pollution control board ordinances. Battery replacement cost barriers limit penetration in pure rental models.
- Gasoline:Lightweight spark-ignition engines dominate homeowner and light landscaper segments.
- Propane:Alternative fuel conversions target indoor greenhouse operations with ventilation constraints.
Diesel retains the dominant share in commercial farming revenue, though electric variants are expanding most quickly through subsidy-eligible municipal procurement.
End User:
Customer type determines equipment specification intensity, from price-sensitive owner-operators to fleet-optimized rental contractors.
- Farmers:Owner-operators of sub-hectare holdings prioritize purchase price and spare parts availability over advanced features. India's PLI scheme eligibility criteria are redirecting some procurement toward domestically assembled electric platforms. Seasonal cash flow constraints favor financing arrangements through agri-input retailer channels.
- Agricultural Contractors:Rental fleet operators unbundle equipment ownership from maintenance service, sourcing repairs through independent technicians rather than authorized dealers. Equipment utilization rates across multiple villages justify premium diesel configurations with extended service intervals.
- Landscapers:Commercial grounds maintenance contractors specify mid-range gasoline or electric units.
- Homeowners:Residential purchasers drive seasonal demand spikes during pre-monsoon garden preparation windows.
The dominant share belongs to farmers as owner-operators, while agricultural contractors are gaining share fastest through fleet consolidation across India's rice-cultivating districts.
Application:
Volume concentration in soil preparation contrasts with margin opportunities in specialized intercropping services.
- Soil Preparation:Primary tillage for seedbed formation consumes the majority of power tiller operating hours across South Asian rice-wheat systems. Deep ripping and puddling operations in India's Indo-Gangetic plains stress transmission durability and drive replacement parts demand. Rental contractors schedule equipment around narrow planting windows that compress annual utilization into concentrated seasonal peaks.
- Intercropping:Between-row cultivation in standing crops demands precise depth control and narrow working widths to avoid root damage. Vietnamese coffee and pepper plantations in the Central Highlands specify specialized tiller configurations for mechanized weeding that reduces labor dependency. Premium service pricing supports equipment amortization across lower annual hour totals.
- Weeding:Secondary tillage for weed suppression targets labor substitution in vegetable supply chains.
- Garden Maintenance:Residential and municipal ornamental applications favor lighter equipment specifications.
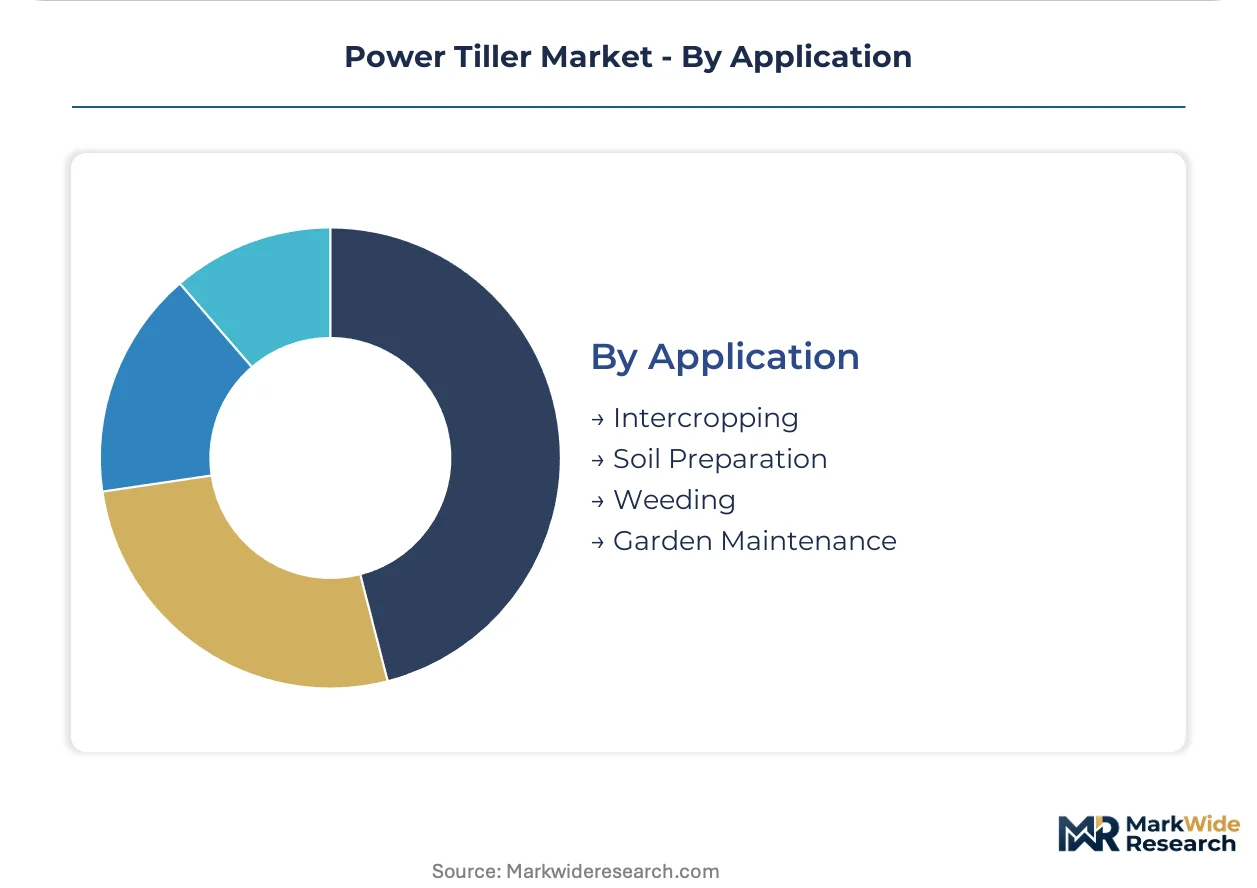
The dominant share belongs to soil preparation as the foundational use case, while intercropping is climbing the fastest through plantation sector mechanization in Vietnam.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Central Pollution Control Board anchors the regulatory framework reshaping power tiller procurement across South Asia. Bharat Stage emission norms and the PLI scheme for farm machinery are compressing diesel margins while accelerating electric platform development. Fragmented land holdings and mechanization subsidies are redirecting demand toward walk-behind equipment.
India
Smallholder mechanization in sub-hectare plots drives diesel and electric tiller procurement across the Indo-Gangetic plains. The Bureau of Indian Standards certifies safety benchmarks that delay product launches for redesigned models. Tamil Nadu and Karnataka host manufacturing clusters where domestic assemblers source precision gearboxes from tier-one suppliers.
Bangladesh
Rental contractors operating multi-village equipment pools favor diesel reliability for rice-cultivating belts during narrow planting windows. The country's agricultural extension programs subsidize mechanization for riverine char lands with extreme plot fragmentation. Dhaka-centered distribution networks channel tillers through agri-input cooperatives alongside seed and fertilizer sales.
Vietnam
Greenhouse vegetable cooperatives in Da Lat's Central Highlands specify mini tillers for year-round protected cultivation. Provincial pollution control ordinances in urban zones restrict gasoline engine noise for municipal landscaping contracts. Ho Chi Minh City serves as the import hub for brushless DC motor systems displacing recoil-start engines.
Japan
Precision gearbox and hydrostatic transmission suppliers concentrate manufacturing for export to South Asian assemblers. METI standards influence corrosion-resistant metallurgy specifications for flooded-field paddy configurations. Osaka-based component producers face extended lead times as Indian manufacturers scale electric drivetrain assembly.
Italy
Specialized gasket material producers reformulate seal compounds to satisfy REACH chemical standards for export eligibility. Rust-resistant hardware specifications for paddy transmissions drive premium component sourcing from Emilia-Romagna fabricators. Milan-area engineering firms validate alternative cooling chemistries constrained by EU F-Gas Regulation.
Power Tiller Market Competitive Environment
Scale-driven manufacturers and regional specialists split the market across distinct procurement channels. Consolidation pressures concentrate among diesel engine assemblers facing Bharat Stage compliance costs, while electric platform entrants fragment the sub-10 horsepower segment. Two archetypes dominate: integrated engine-and-chassis producers serving rental contractors, and component-assembly specialists leveraging agri-input retail distribution. Competitive moves center on backward integration into battery pack assembly and geographic expansion through farm equipment cooperatives.
Among integrated producers, Kubota Corporation and V.S.T. Tillers Tractors Ltd. exemplify contrasting scale positions within the market structure. Kubota represents the established parts-and-service infrastructure archetype sustaining loyalty in rice-cultivating regions, while V.S.T. occupies a cost-engineered position purpose-built for Indian domestic sub-acre applications. Greaves Cotton Limited sits within the engine reliability tier competing for rental contractor procurement across dispersed village operations.
| Leading Market Players |
|---|
| V.S.T. Tillers Tractors Ltd. |
| Kubota Corporation |
| Honda Motor Co., Ltd. |
| Yanmar Co., Ltd. |
| Deere & Company |
| TAFE |
| Mahindra & Mahindra |
| Greaves Cotton Limited |
| Kirloskar Oil Engines Limited |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese precision gearbox manufacturing is compressing lead times for Indian assemblers while simultaneously inflating component premiums that cascade into finished-equipment pricing. This utilization squeeze forces domestic producers to absorb margin erosion or pass through costs to price-sensitive smallholder segments.
Pricing Analysis
Price spreads between diesel and electric configurations in India and Bangladesh exceed component cost differentials due to subsidy eligibility asymmetries. Three-tier pricing structure across premium paddy configurations, standard mini tillers, and economy handheld units stratifies by transmission complexity and corrosion-resistant metallurgy. Pricing pressure stems from Bharat Stage compliance costs inflating diesel engine bills-of-material. Rental contractors exhibit lowest price sensitivity due to equipment utilization rates across multiple villages, while owner-operator farmers prioritize upfront acquisition cost over total cost of ownership.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese and Korean tier-one transmission producers are tightening working capital constraints for Indian assemblers lacking equivalent leverage. Manufacturing concentrates in India, Japan, and Italy for distinct component categories: chassis fabrication, precision gearing, and specialized gasket materials respectively. Supply chains draw from steel and aluminum commodity markets, lithium-iron-phosphate battery cell imports, and REACH-compliant seal compounds. Single-source vulnerability concentrates in hydrostatic transmission sourcing from Osaka-based producers. Distribution runs through agri-input cooperatives and farm equipment retailers alongside traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power tiller procurement is shifting toward platform economics as battery-swapping interoperability and shared-service contractor models decouple equipment ownership from field access. This ecosystem inflection rewards stakeholders who control charging infrastructure and technician certification networks rather than pure manufacturing scale.
For Market Incumbents: Entrench parts-and-service loyalty by captive supply of lithium-ion battery pack assembly within Indian manufacturing corridors. Deepen backward integration into brushless DC motor production to offset Japanese supplier lead time variability. Defend against electric platform entrants by locking agri-input retailer shelf space through exclusive co-financing arrangements.
For New Entrants and Emerging Players: Establish a beachhead in subsidized municipal landscaping procurement across Vietnamese and Indian urban zones where noise ordinances displace gasoline configurations. Target greenhouse vegetable cooperatives in Da Lat and Bangladesh's riverine char lands with mini tiller configurations optimized for terraced maneuverability. Pursue battery-as-a-service subscription models that unbundle energy cost from equipment acquisition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rental contractor fleet operators who bundle equipment access with maintenance service. Long-term viability favors acquisition targets with established technician training networks and agri-input retail channel relationships. Watch subsidy qualification threshold revisions as the signal indicating which battery architectures warrant scaled R&D commitment versus fossil-fuel platform harvesting.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Reduces import dependency for lithium-ion cells under India's PLI scheme incentives. |
| Agri-Input Retailer Channel Expansion | Collapses distribution layers by stocking tillers alongside seed and fertilizer cooperatives. |
| Technician Certification Network Buildout | Addresses field repair capability gaps for electronic fuel injection and battery management systems. |
| Paddy Tiller Metallurgy Investment | Captures premium pricing through rust-resistant transmissions for flooded-field applications. |
| Interoperable Battery Swapping Infrastructure | Enables rental contractor fleet optimization across dispersed village operations. |
Study Parameters
Desk research of customs trade records, BIS certification filings, and state-level subsidy program documentation preceded structured interviews with rental contractor fleet operators, agri-input cooperative procurement managers, and aftermarket service technicians. Primary fieldwork across India's Indo-Gangetic plains, Bangladesh's rice-cultivating belts, and Vietnam's Central Highlands validated secondary data on equipment utilization patterns and channel economics. Bottom-up triangulation of unit shipment estimates with top-down revenue aggregation cross-checked segmentation splits.
Assumptions held fixed across the modeling period include prevailing Bharat Stage emission norm stringency, PLI scheme eligibility criteria, and lithium-ion cell import tariff structures. Variables stress-tested encompass steel and aluminum commodity price bands, precision gearbox lead time ranges, and subsidy qualification threshold revisions. Segmentation dimensions modeled span product type, fuel architecture, end-user archetype, and application intensity across soil preparation and intercropping use cases. CAGRs derived from logistic growth curve fitting anchored by named capacity expansion announcements and regulatory phase-in schedules.
Stress conditions across battery replacement cost trajectories, field technician training throughput, and agri-input retailer credit availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy continuity and emission norm enforcement intensity. Macroeconomic contraction in smallholder agricultural income, abrupt subsidy program suspension, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Orchard Type Tractors Market