
 Europe Agricultural Irrigation Machinery Market | 2026-2036
Europe Agricultural Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Irrigation Machinery Market Foresight
The capital-intensity divergence between precision-engineered system manufacturers and commodity component suppliers is unwinding competitive hierarchies across the European irrigation landscape. Lindsay Corporation leverages its center pivot manufacturing scale to dominate large-scale arable contracts in Eastern Europe. Netafim anchors its position through drip irrigation specialization, sustaining R&D intensity in pressure-compensating emitter technology that reduces water waste. Irritec S.p.A. differentiates through geographic proximity to Mediterranean horticulture clusters, controlling distribution channels across Italy, Spain, and Portugal.
Europe agricultural irrigation machinery encompasses mechanized systems designed to distribute water to crops through pressurized networks, incorporating specifications such as flow rates measured in liters per hour, filtration grades down to 120 mesh, and automation protocols enabling soil-moisture-responsive activation. These systems serve the primary commercial purpose of optimizing yield stability while reducing labor dependency and water consumption in commercial agriculture. Drip irrigation leads technology adoption where water scarcity and high-value cropping coincide, while center pivot systems occupy the extensive cereal belt of France and Germany. Pipe systems and pumps capture the bulk of product-type revenue, though controllers represent the fastest-expanding margin pool as telemetry and variable-rate programming penetrate farm operations.
The EU Green Deal and F-Gas Regulation shape equipment efficiency mandates, while CE marking and national agricultural ministries enforce installation standards and water-use compliance across member states. ECHA's REACH framework restricts certain polymer chemistries in drip line manufacturing, redirecting formulation strategies toward compliant materials. Stakeholders must monitor the divergence between subsidy availability for precision irrigation retrofits and the accelerating stringency of water abstraction permits in drought-declared basins.
Market Dynamics
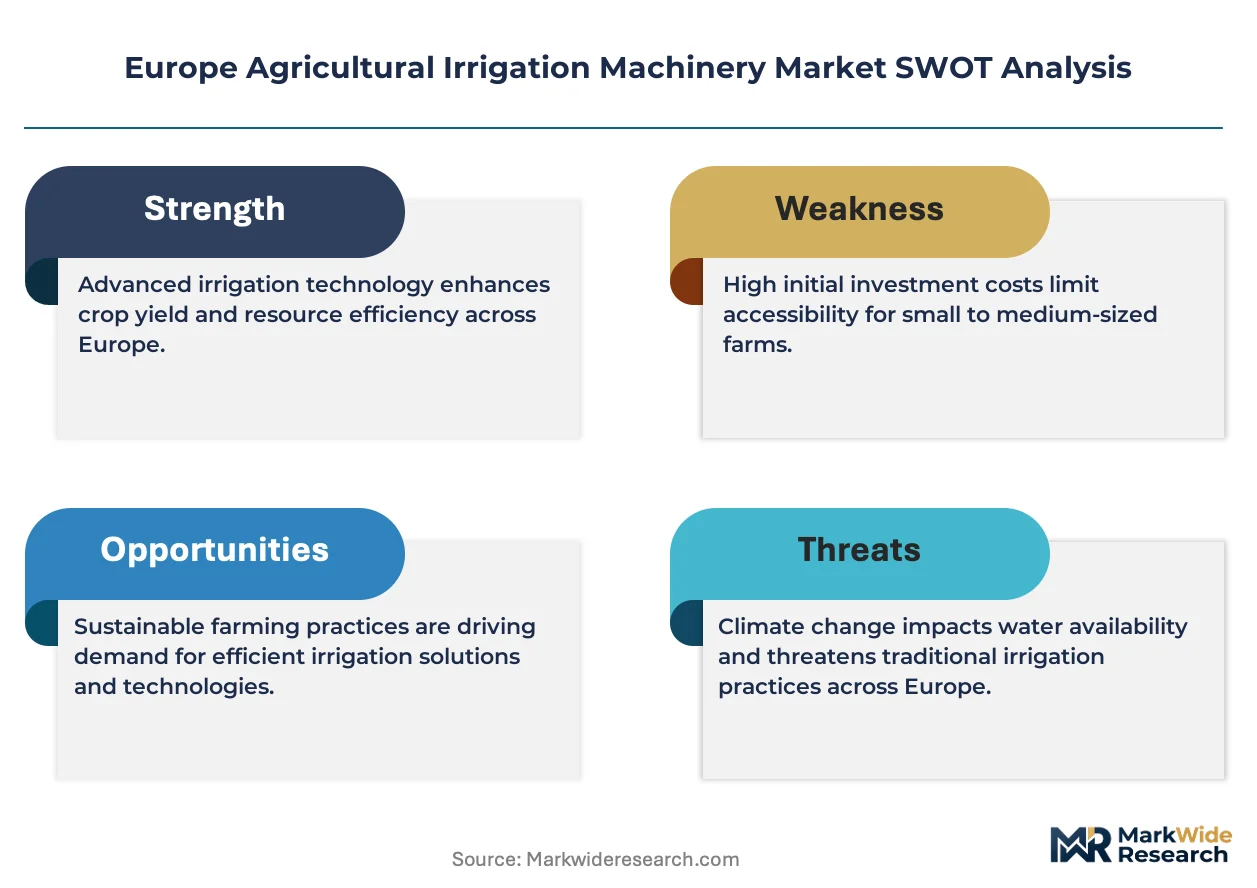
The EU Green Deal's Farm to Fork strategy is compressing equipment replacement cycles across Mediterranean horticulture zones. Water abstraction permits now mandate telemetry-enabled flow monitoring, forcing retrofits on installed base machinery ahead of mechanical end-of-life.
Growth Catalysts
- EU Green Deal efficiency mandates:The Farm to Fork strategy tightens water-use standards for agricultural equipment, compelling farm operators to upgrade to precision distribution systems.
- Drip irrigation technology:Pressure-compensating emitter advances reduce water waste in high-value cropping systems, aligning with tightening abstraction limits in drought-stressed basins.
- Spain's specialty crop expansion:Almond and olive producers in Andalusia and Valencia are mechanizing irrigation coverage as sustained aridity threatens yield stability.
Market Restraints
- Polymer input cost volatility:ECHA REACH restrictions on certain chemistries in drip line manufacturing have redirected formulation strategies toward costlier compliant materials.
- Component supply concentration:Precision pump and filtration subassembly production clusters in Northern Italy create vulnerability for system integrators dependent on just-in-time delivery.
- Technical limitation of legacy compatibility:Retrofitting telemetry controllers onto 15-20 year old center pivot infrastructure requires custom interface engineering that extends project timelines.
Strategic Opportunities
- Portugal's underpenetrated horticulture belt:The Alentejo and Ribatejo regions show low mechanized irrigation density relative to water stress levels, creating first-mover positioning for turnkey system providers.
- Subsidy convergence with precision mandates:National agricultural ministries in Spain and Italy are expanding cost-share programs for soil-moisture-responsive activation retrofits.
- Telemetry-Variable Rate Programming convergence:Integration of satellite-derived crop health data with zone-specific water application is opening service revenue streams beyond hardware sales.
Industry Challenges
- Certification timeline compression:CE marking requirements for electromagnetic compatibility in automated controllers have extended product launch cycles by 8-14 months.
- Integration complexity with legacy infrastructure:Farm operators in France's cereal belt operate mixed fleets of mechanical and electronic systems, complicating unified fleet management software deployment.
- Capex intensity for filtration upgrades:120-mesh filtration grades required for drip emitter protection demand capital outlays that strain smallholder financing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Irrigation Machinery Market |
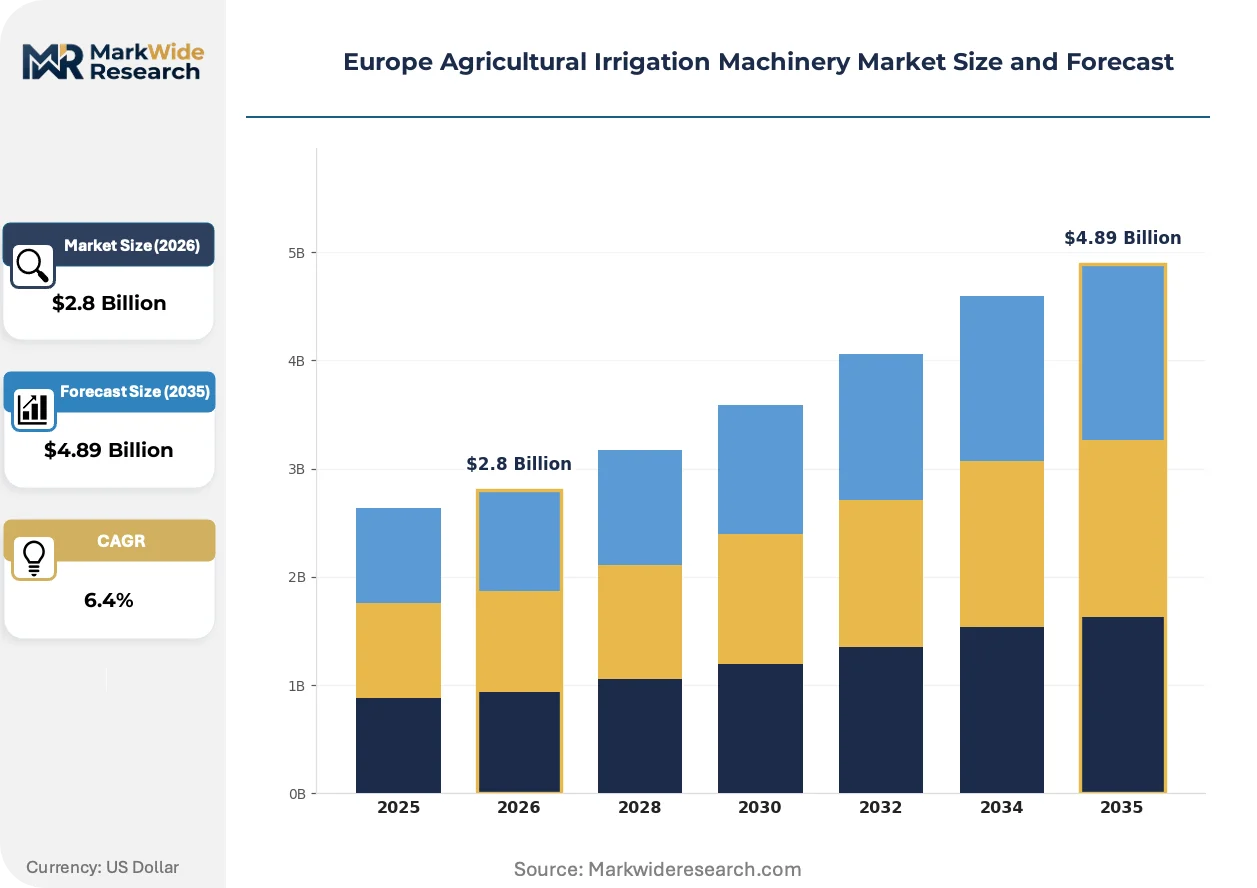
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drip Irrigation, Center Pivot, Sprinkler, Surface Irrigation Product Type: Pipe Systems, Pumps, Valves, Controllers End User: Farms, Greenhouses, Landscapers, Agricultural Contractors Application: Crop Irrigation, Landscape Irrigation, Turf Management, Others |
| Companies Covered | Lindsay Corporation, Rain Bird Corporation, Netafim, Deere & Company, Rivulis Irrigation Ltd, Irritec S.p.A., The Toro Company, Valmont Industries, Teco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Irrigation Machinery Market Shifts & Advancements
Telemetry-enabled automation is reconfiguring how irrigation systems are specified, sold, and serviced across European agriculture. Three interconnected developments are compressing the gap between hardware deployment and data-driven water management.
Soil-moisture-responsive activation hardware is displacing timer-based scheduling across Mediterranean horticulture operations. Spanish almond and olive producers in Andalusia are retrofitting capacitance probe networks to existing drip systems at accelerating pace. This sensor-to-valve automation is displacing manual field inspection routines and compressing labor requirements per hectare.
The EU F-Gas Regulation is restricting refrigerant choices in cooling systems paired with irrigation infrastructure, indirectly pressuring pump motor efficiency standards. Equipment manufacturers must now certify compatibility with lower-global-warming-potential cooling chemistries. Center pivot system suppliers in Eastern Europe are responding by accelerating permanent magnet motor adoption ahead of the 2027 phase-down deadlines.
Cooperative procurement consortia are consolidating equipment specification power among medium-scale farm operators in Italy's Emilia-Romagna and Spain's Murcia regions. These buyer groups are unbundling after-sales service contracts from hardware purchases, forcing manufacturers to price maintenance separately. The shift is most visible in drip irrigation system tenders where technical support packages are now negotiated independently of emitter and mainline component pricing.
Europe Agricultural Irrigation Machinery Market Segmentation
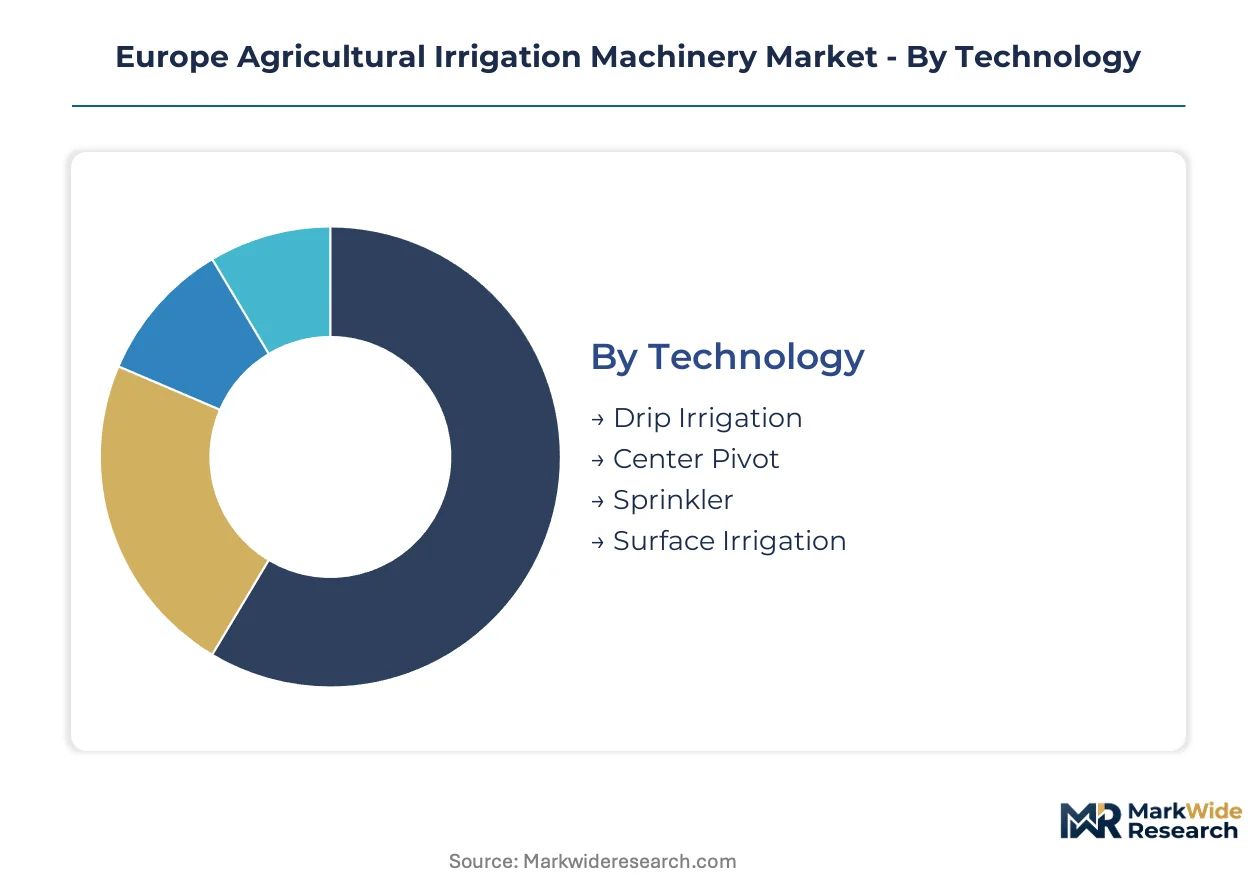
Segmentation in Europe's agricultural irrigation machinery market reveals how regulatory pressure and water scarcity reshape equipment procurement patterns. Distinct technology and product configurations align with specific cropping systems and abstraction permit conditions across Mediterranean and continental farming zones.
Technology:
EU Green Deal efficiency mandates and F-Gas Regulation phase-downs differentiate equipment eligibility for subsidy programs and water abstraction licenses.
- Drip Irrigation:Pressure-compensating emitter networks deliver water directly to root zones through polyethylene laterals with 16-20mm diameters. Spanish almond and olive producers in Andalusia and Valencia are retrofitting capacitance probe networks to existing drip systems as sustained aridity threatens yield stability.
- Center Pivot:Self-propelled rotating booms span 400-800 meters, distributing water through overhead sprinklers across extensive arable parcels. Eastern European cereal producers deploy Lindsay Corporation systems for large-scale wheat and maize operations where field geometry permits circular coverage patterns.
- Sprinkler:Portable or solid-set systems serve irregular field boundaries and orchards with overhead distribution.
- Surface Irrigation:Gravity-fed flood and furrow methods persist in water-abundant zones and legacy rice cultivation.
Drip irrigation handles the majority of throughput in high-value horticulture zones; center pivot systems are gaining share fastest among extensive arable operators seeking labor reduction.
Product Type:
Cost tier differentiation separates commodity hardware from precision-engineered components commanding premium positioning.
- Pipe Systems:PVC and polyethylene mainlines, laterals, and fittings form the pressurized distribution backbone. Italian system integrators source 120-mesh filtration-grade pipe from Northern Italian manufacturing clusters, creating just-in-time delivery vulnerability for Mediterranean turnkey providers.
- Controllers:Telemetry-enabled automation hardware with soil-moisture-responsive programming and satellite-derived crop health integration. Spanish and Italian national agricultural ministries are expanding cost-share programs for these retrofits, accelerating displacement of timer-based scheduling.
- Pumps:Centrifugal and turbine units provide pressurization for distribution networks.
- Valves:Hydraulic and electric actuation devices regulate zone-specific flow rates.
Pipe systems and pumps dominate installed base volume; controllers are expanding most quickly as telemetry mandates compress replacement cycles ahead of mechanical end-of-life.
End User:
Customer type determines specification complexity and service contract bundling preferences across procurement patterns.
- Farms:Owner-operated agricultural enterprises ranging from smallholder horticulture to extensive cereal production. Cooperative procurement consortia in Italy's Emilia-Romagna and Spain's Murcia regions are unbundling after-sales service contracts from hardware purchases, forcing manufacturers to price maintenance separately.
- Greenhouses:Controlled-environment horticulture operations requiring precision humidity and irrigation management. Dutch and Belgian glasshouse operators specify ultra-fine filtration and fertigation integration for substrate-grown vegetables.
- Landscapers:Commercial turf and ornamental maintenance contractors.
- Agricultural Contractors:Third-party service providers offering seasonal irrigation deployment and system maintenance.
Farms account for the dominant share of equipment procurement; greenhouses are climbing the fastest on precision automation intensity.
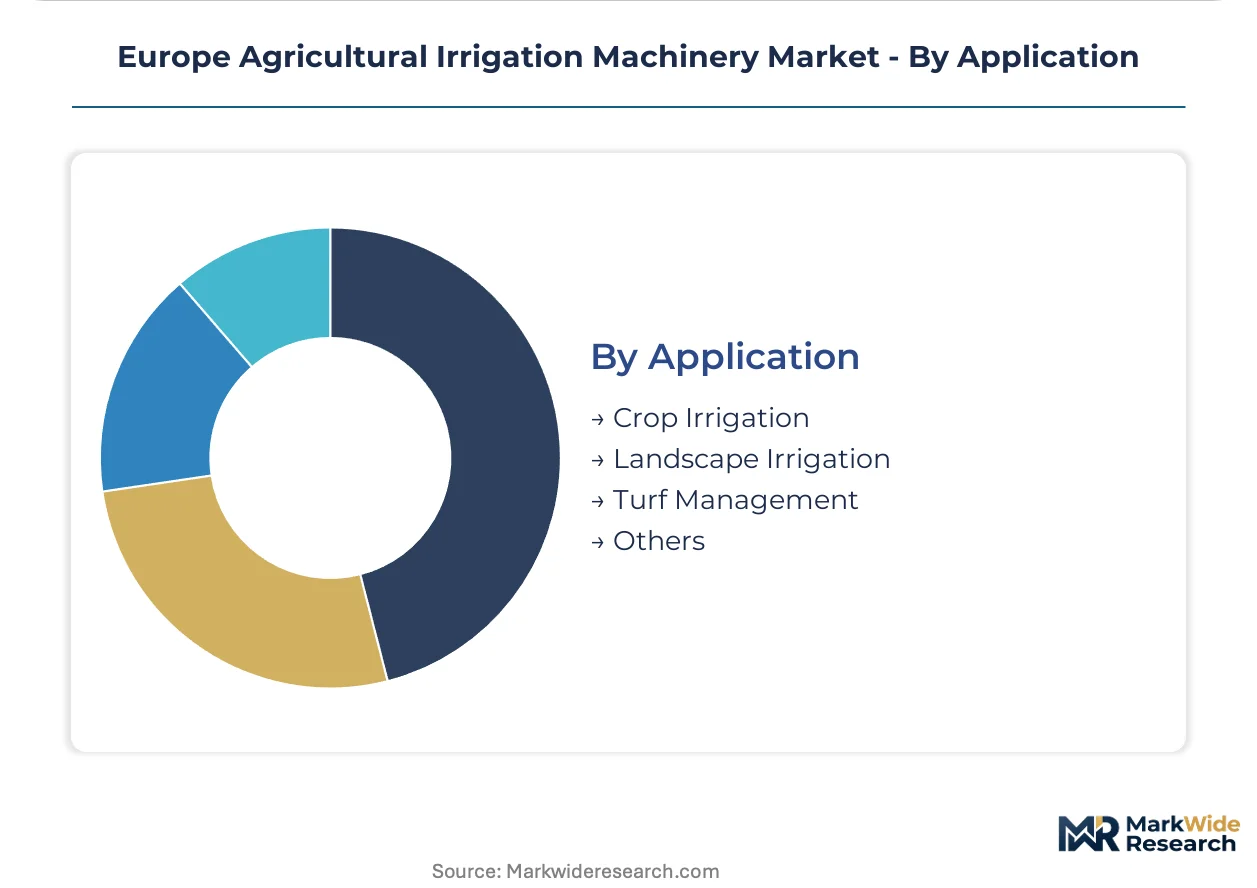
Application:
Geography within Europe determines which application segments concentrate demand based on aridity patterns and cropping intensity.
- Crop Irrigation:Commercial agricultural water application for yield stabilization and quality optimization. Portugal's Alentejo and Ribatejo regions show low mechanized irrigation density relative to water stress levels, creating first-mover positioning for turnkey system providers targeting specialty crop expansion.
- Turf Management:Sports field, golf course, and municipal park irrigation with uniform coverage requirements. French and German municipalities face tightening abstraction permits that mandate telemetry-enabled flow monitoring for non-agricultural water use.
- Landscape Irrigation:Ornamental and environmental planting water management.
- Others:Niche applications including nursery propagation and research station operations.
Crop irrigation commands the bulk of system deployments; turf management is gaining share fastest under municipal efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Mediterranean horticulture zones while Eastern European cereal operations compete on equipment cost efficiency. Spanish and Italian buyers absorb higher technology premiums for precision irrigation, whereas Polish and Romanian farms prioritize capital-light mechanization. This geographic asymmetry shapes manufacturer portfolio priorities across the continent.
Spain
Andalusian almond and olive producers are retrofitting capacitance probe networks to existing drip systems as sustained aridity threatens yield stability. The EU Green Deal's Farm to Fork strategy tightens water-use standards for agricultural equipment, compelling upgrades to precision distribution systems. Valencia's horticulture belt shows accelerating mechanized irrigation coverage as water stress intensifies.
Italy
Emilia-Romagna cooperative procurement consortia are unbundling after-sales service contracts from hardware purchases, forcing manufacturers to price maintenance separately. ECHA REACH restrictions on certain polymer chemistries in drip line manufacturing have redirected formulation strategies toward compliant materials. Northern Italian manufacturing clusters supply 120-mesh filtration-grade pipe, creating just-in-time delivery vulnerability for Mediterranean turnkey providers.
France
The cereal belt operates mixed fleets of mechanical and electronic systems, complicating unified fleet management software deployment. CE marking requirements for electromagnetic compatibility in automated controllers have extended product launch cycles by 8-14 months. French municipalities face tightening abstraction permits that mandate telemetry-enabled flow monitoring for non-agricultural water use.
Germany
Extensive arable operators seek labor reduction through center pivot system deployment where field geometry permits circular coverage patterns. The EU F-Gas Regulation restricts refrigerant choices in cooling systems paired with irrigation infrastructure, indirectly pressuring pump motor efficiency standards. Precision pump and filtration subassembly production clusters create supply concentration for system integrators.
Portugal
The Alentejo and Ribatejo regions show low mechanized irrigation density relative to water stress levels, creating first-mover positioning for turnkey system providers. National agricultural ministries are expanding cost-share programs for soil-moisture-responsive activation retrofits. Specialty crop producers are mechanizing irrigation coverage ahead of drought-declared basin designations.
Europe Agricultural Irrigation Machinery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European irrigation machinery landscape. The market structures around a consolidated tier of precision-system specialists and a fragmented base of component fabricators serving price-sensitive retrofit demand. Three archetypes dominate: scale-driven pivot manufacturers, drip-irrigation technology specialists, and regionally anchored turnkey integrators. Competitive moves concentrate on M&A for telemetry capability acquisition and geographic expansion into underpenetrated Mediterranean horticulture zones.
Among precision-irrigation specialists, Netafim anchors the drip-technology tier through pressure-compensating emitter specialization, while Lindsay Corporation exemplifies scale-driven manufacturing for extensive arable applications. Irritec S.p.A. occupies a position within the regionally integrated archetype, leveraging proximity to Mediterranean horticulture clusters. These three represent the dominant competitive positioning vectors—technology depth, manufacturing scale, and geographic anchoring—that structure rivalry across European farm equipment procurement.
| Leading Market Players |
|---|
| Lindsay Corporation |
| Rain Bird Corporation |
| Netafim |
| Deere & Company |
| Rivulis Irrigation Ltd |
| Irritec S.p.A. |
| The Toro Company |
| Valmont Industries |
| Teco |
| Others |
Supply & Pricing Matrix
Pressure-compensating emitter substitution for conventional drip technology is simultaneously shifting procurement geography toward Mediterranean manufacturing clusters and compressing margin structures for commodity pipe suppliers. This material transition tightens specification requirements while rewarding system integrators capable of compliant formulation sourcing.
Pricing Analysis
The customization-premium spread in European irrigation machinery spans configured-to-order telemetry systems against standard mechanical center pivot packages. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier, after-sales service bundling, and geographic delivery cost. Cost compression in standard pipe and pump tiers is intensifying because ECHA REACH compliance redirects formulation toward costlier polymer inputs. Smallholder horticulture operators in Portugal and Spain exhibit highest price sensitivity, while Dutch greenhouse specialists absorb premium positioning for fertigation-integrated controllers.
Supply Chain Analysis
The Brenner Pass corridor chokepoint underwrites just-in-time vulnerability for precision pump and filtration subassemblies destined for Mediterranean turnkey providers. Manufacturing gravity centers on Germany for precision controllers, Northern Italy for 120-mesh filtration-grade pipe, and Spain for emitter assembly. Raw material flows draw from Saudi Arabian polyethylene resin, Belgian specialty polymer additives, and Romanian steel for structural components. Single-source vulnerability concentrates in Northern Italian precision machining clusters. Distribution runs through cooperative procurement consortia in Emilia-Romagna and Murcia unbundling hardware from service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European agricultural irrigation machinery represents early-cycle expansion as telemetry mandates force replacement ahead of mechanical end-of-life across Spain and Italy. Water abstraction permit tightening creates irreversible upgrade pressure irrespective of commodity price cycles.
For Market Incumbents: Secure backward integration into REACH-compliant polymer formulation to defend margin position against input cost volatility. Anchor channel control through exclusive service partnerships with cooperative procurement consortia in Italy's Emilia-Romagna and Spain's Murcia regions. The priority lever centers on telemetry capability acquisition through specialist M&A before CE marking timelines extend further. For New Entrants and Emerging Players: After-sales service unbundling by Mediterranean buyer groups creates white-space positioning for independent maintenance providers. Portugal's Alentejo and Ribatejo regions offer lowest mechanized irrigation density relative to water stress severity. Target turnkey system deployment with soil-moisture-responsive activation as the entry wedge, pricing hardware at cost and capturing margin through multi-year telemetry service contracts. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors precision-irrigation technology specialists over commodity component fabricators. Long-term viability across the five-to-ten year window rests on telemetry software recurring revenue attachment rates rather than hardware shipment volumes. The acquisition target archetype combines pressure-compensating emitter IP with established CE marking pathways. The signal to watch is subsidy convergence timing between national agricultural ministries and drought-declared basin designations.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Capability Acquisition | CE marking compression for automated controllers rewards pre-certified electromagnetic compatibility assets. |
| REACH-Compliant Polymer Backward Integration | ECHA formulation restrictions redirect margin capture from resin suppliers to integrated system manufacturers. |
| Cooperative Procurement Consortium Partnerships | Emilia-Romagna and Murcia buyer groups consolidate specification power and unbundle service pricing. |
| Portugal First-Mover Deployment | Alentejo and Ribatejo water stress exceeds mechanized irrigation density, creating penetration arbitrage. |
| Satellite-Derived Crop Health Integration | Variable-rate programming convergence opens service revenue streams beyond hardware transaction economics. |
Research Methodology
A standing panel of irrigation system procurement managers at Spanish and Italian agricultural cooperatives, Dutch greenhouse operations directors, and German cereal belt maintenance supervisors provided ongoing calibration against field-level adoption patterns. Primary interviews with precision emitter R&D leads and filtration subassembly plant engineers in Northern Italy supplemented secondary validation through EU Farm to Fork strategy documentation, ECHA REACH substance restriction updates, national agricultural ministry subsidy program filings, and CE marking electromagnetic compatibility directive texts. Bottom-up equipment shipment aggregation and top-down water abstraction permit analysis enabled cross-verification.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler agricultural telemetry capex disclosures and cooperative procurement consortium tender databases. Segmentation modeling across technology type, product tier, end-user category, and application geography structured the analytical framework. CAGRs were derived from equipment replacement cycle compression under telemetry mandate pressure and specialty crop expansion trajectories in drought-stressed basins. Forecast inputs incorporated EU F-Gas Regulation phase-down timelines and national cost-share program expansion announcements.
Forecasts assume regulatory continuity in EU Green Deal implementation and ECHA REACH enforcement; material policy shifts would require re-modeling. Specific risk factors include polymer input cost volatility from energy price shocks and certification timeline extension beyond current electromagnetic compatibility standards. Practitioners should keep alternative scenarios live as drought-declared basin designations and subsidy convergence timing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Cambodia Agricultural Machinery Market