
 North America Fertilizers Market | 2026-2036
North America Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fertilizers Market Analytics
Urea-ammonium nitrate solutions are recalibrating nitrogen economics across North American row-crop operations. CF Industries Holdings, Inc. leverages its Donaldsonville complex to dominate domestic ammonia production. Nutrien Ltd. anchors its position through integrated potash mining in Saskatchewan and retail distribution networks. The Mosaic Company differentiates via phosphate rock reserves in Florida and vertical integration into finished fertilizer grades.
North America fertilizers encompass chemically or organically derived nutrient formulations—typically quantified by N-P-K ratios, particle size distribution, and water solubility percentages—applied to soils or foliage to correct nutrient deficiencies and optimize plant metabolic function. Nitrogenous products command the largest volume share due to corn and wheat intensity, while slow-release formulations capture expanding margin pools as environmental compliance tightens. Liquid fertilizers gain share in irrigated horticulture across California's Central Valley, though granular phosphate maintains structural importance in no-till systems across the US Plains.
The US EPA enforces Clean Water Act provisions that restrict nutrient runoff from agricultural operations, compelling manufacturers toward enhanced-efficiency coatings and stabilized nitrogen products. Canada's PMRA evaluates fertilizer-pesticide combination products under integrated regulatory frameworks, while state-level programs in Iowa and Minnesota mandate nutrient reduction strategies for watershed protection. Stakeholders must monitor evolving carbon intensity scoring for ammonia production, as low-carbon certification thresholds reshape procurement criteria across North American supply chains.
Market Dynamics
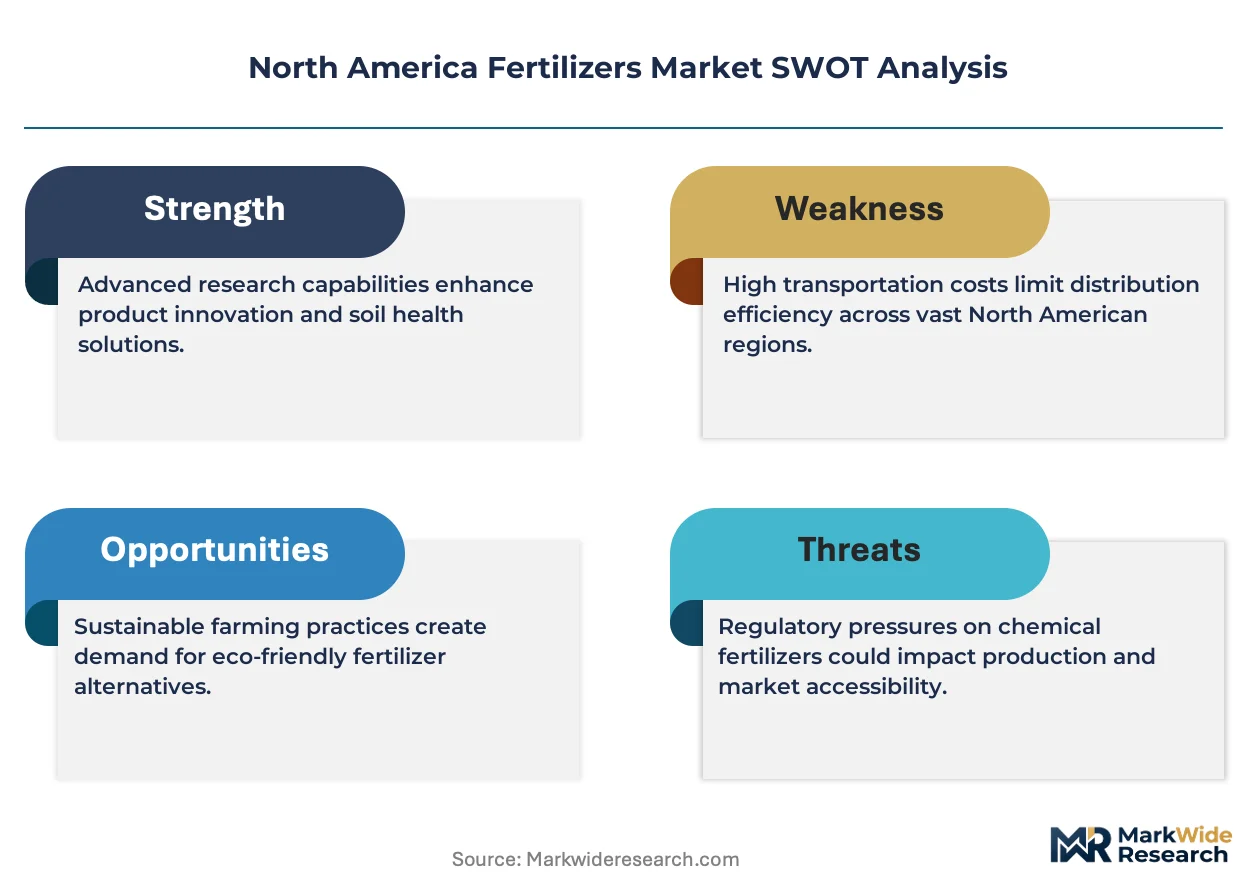
The US EPA's tightening nutrient runoff controls under Clean Water Act provisions are forcing fertilizer manufacturers toward enhanced-efficiency formulations. This regulatory compression is restructuring product portfolios across the Corn Belt and specialty crop regions.
Growth Catalysts
- Precision Agriculture Adoption:Variable-rate fertilization technology spreads across Iowa and Illinois row-crop operations, optimizing nitrogen placement and reducing waste.
- Enhanced-Efficiency Coatings:The US EPA's Nutrient Management Regulations mandate runoff reductions, pulling specialty crop producers in California and Florida toward stabilized nitrogen products.
- Saskatchewan Potash Expansion:Integrated mining and distribution networks anchor supply security for North American potassium demand.
Market Restraints
- Natural Gas Price Volatility:Ammonia production economics swing with Henry Hub pricing, compressing margins at US Gulf Coast nitrogen facilities.
- Phosphate Rock Concentration:Florida's Bone Valley formation supplies concentrated feedstock, creating geographic vulnerability to hurricane disruptions and water access disputes.
- Legacy Equipment Compatibility:Slow-release formulations require recalibrated application machinery, frictioning adoption among smaller Plains operators.
Strategic Opportunities
- Carbon-Intensity Certification:Low-carbon ammonia scoring thresholds reshape procurement criteria, creating first-mover advantage for producers with renewable hydrogen integration.
- Micronutrient Expansion:California specialty crop producers widen adoption of boron, zinc, and manganese formulations as yield optimization intensifies.
- Liquid Fertilizer Channels:California's Central Valley irrigation infrastructure supports direct-injection systems, bypassing traditional granular distribution.
Industry Challenges
- Agronomic Data Integration:Variable-rate systems demand cross-functional expertise spanning soil science, telemetry, and equipment calibration, talent scarcity constrains deployment.
- Dual-Use Registration Complexity:Canada's PMRA evaluates fertilizer-pesticide combinations under integrated frameworks, extending compliance timelines for combination product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fertilizers Market |
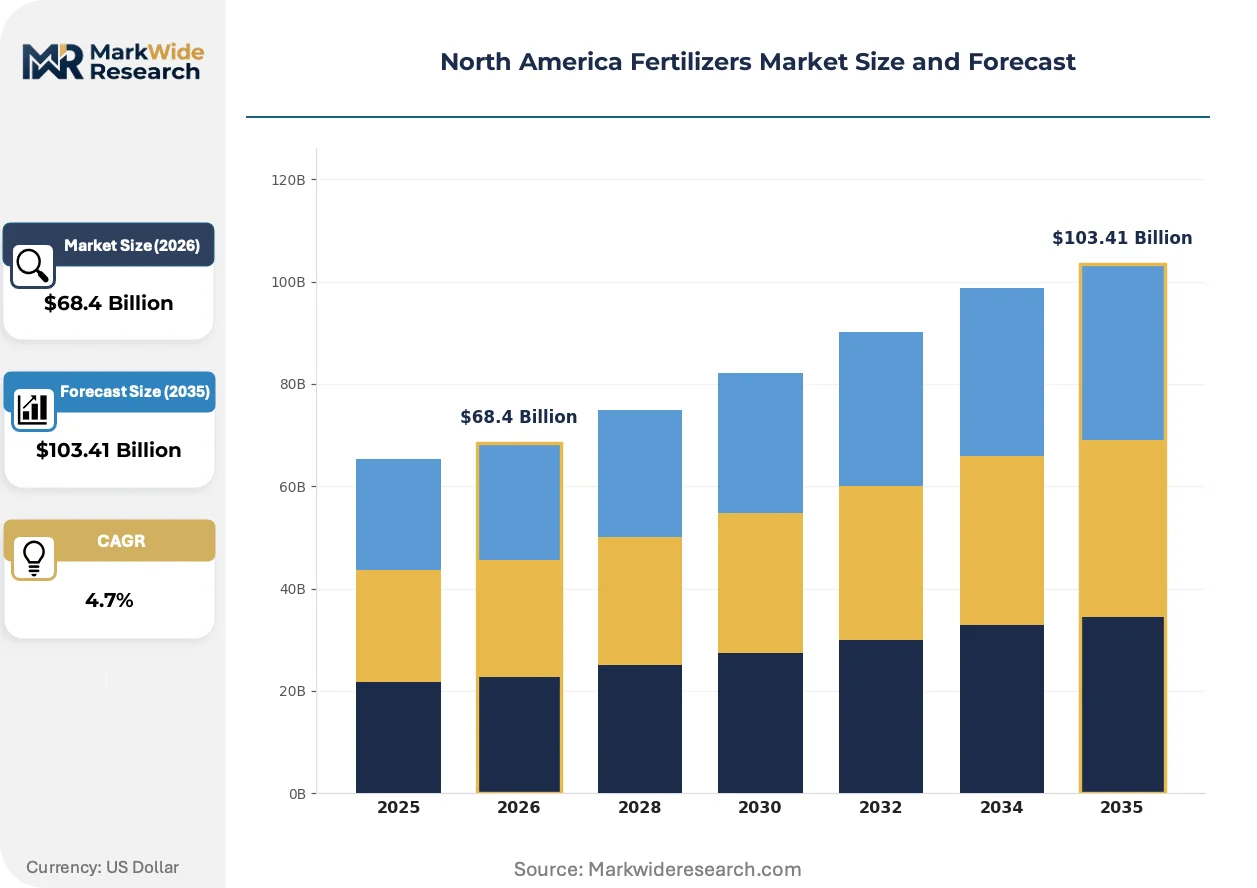
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphate, Potash, Compound Application: Crops, Horticulture, Turf, Ornamental Form: Granular, Liquid, Powder, Slow-Release Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | CF Industries Holdings, Inc., Nutrien Ltd., The Mosaic Company, The Andersons Inc., Yara International ASA, Koch Industries Inc., CVR Partners, LP, Archer Daniels Midland Company, EuroChem Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fertilizers Market Evolving Landscape
Biological amendment integration and digital soil mapping are restructuring how nutrients reach plant root zones. These shifts compress traditional input categories and open margin pools for precision service providers.
Controlled-release polymer coatings are modularizing nitrogen delivery across North American corn operations. Large-scale Iowa and Illinois producers adopt these formulations to meet watershed reduction mandates while maintaining yield targets. The technology is modularizing application timing, compressing the traditional split-application window into single-pass operations.
The US EPA enforces state-level nutrient reduction strategies across Iowa and Minnesota watersheds, compelling manufacturers to reformulate standard grades. This regulatory pressure elevates enhanced-efficiency products from niche to baseline specifications. Corn Belt distributors now stock stabilized nitrogen as default inventory, displacing conventional urea in contracted acreage.
Soil health service contracts are restructuring buyer-supplier relationships across the Corn Belt. Agronomy retailers bundle testing, prescription mapping, and product fulfillment into annual agreements, displacing transaction-based input purchases. This consolidation is most visible in Illinois, where co-op networks capture acreage through outcome-guaranteed programs.
North America Fertilizers Market Segmentation
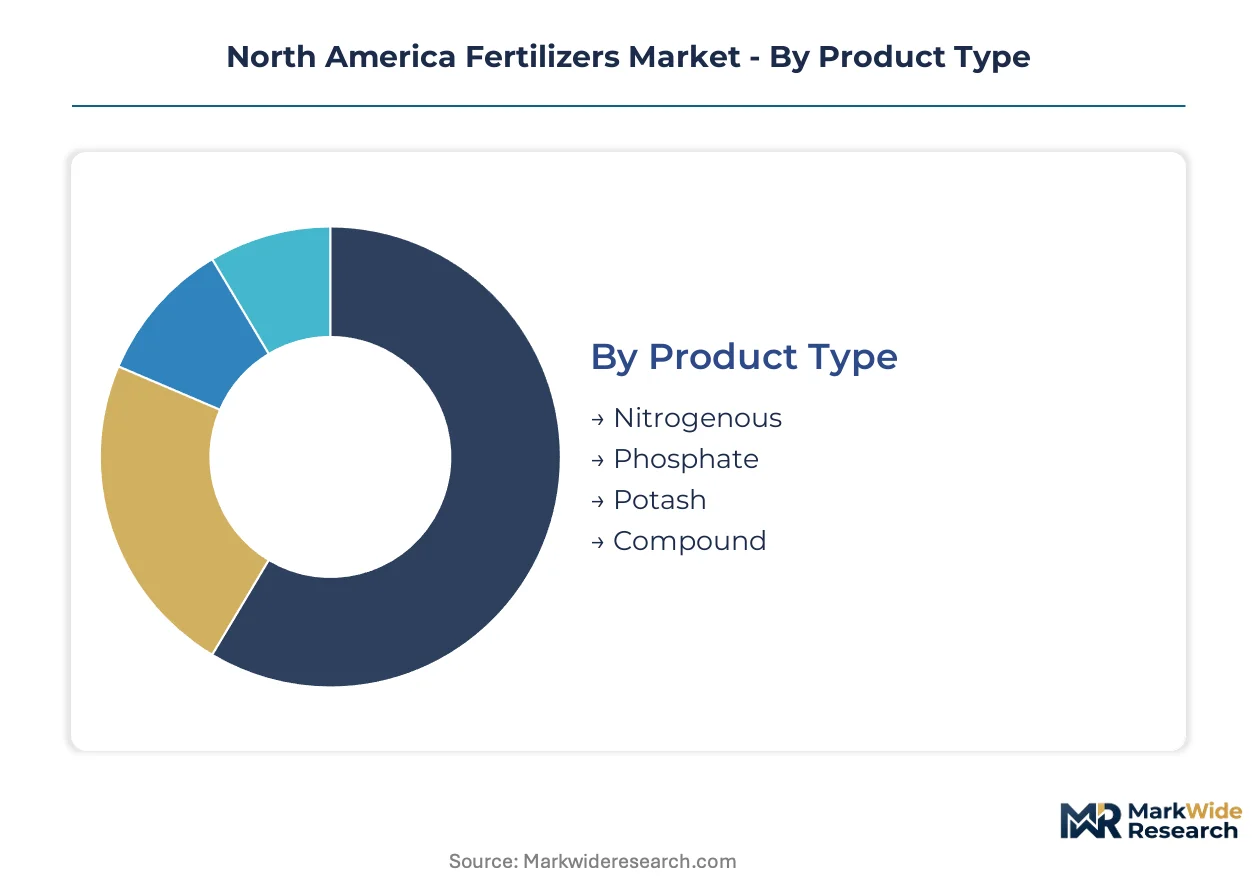
North American fertilizer procurement splits between commodity bulk and precision-formulated solutions. Segmentation discipline reveals where margin pools concentrate versus where volume flows undifferentiated. Each dimension carries distinct regulatory and agronomic implications across the Corn Belt and specialty crop regions.
Product Type:
Standardization dominates nitrogen and phosphate production, while potash and compound fertilizers offer customization through grade blending and micronutrient fortification.
- Nitrogenous:Ammonia, urea, and urea-ammonium nitrate solutions supply the metabolic foundation for corn and wheat protein synthesis. Demand concentrates across Iowa and Illinois row-crop operations where the US EPA's runoff mandates push adoption toward stabilized and enhanced-efficiency formulations.
- Phosphate:Diammonium phosphate and monoammonium phosphate deliver phosphorus for root development and energy transfer. Florida's Bone Valley formation anchors domestic supply, though hurricane exposure and water access disputes create intermittent supply security concerns for Plains distributors.
- Potash:Saskatchewan's integrated mining complexes supply muriate and sulfate of potash for potassium-deficient soils across the northern Plains and specialty crop regions.
- Compound:N-P-K blends and custom-mixed grades allow precise ratio matching to soil test results, capturing margin in high-value horticulture and precision agriculture contracts.
Most installed capacity flows through Nitrogenous. Expansion is steepest in Compound.
Application:
Volume scales inversely with customization intensity—broadacre crops drive tonnage while horticulture and turf command premium pricing per nutrient unit.
- Crops:Corn, soybean, and wheat operations across the US Corn Belt absorb the majority of nitrogen and phosphate volume. Iowa and Illinois distributors stock bulk grades as default inventory, with variable-rate application technology optimizing placement and reducing waste per acre.
- Horticulture:California's Central Valley specialty crop producers—almond, citrus, and vegetable operations—drive demand for micronutrient-fortified formulations and liquid injection systems compatible with drip irrigation infrastructure.
- Turf:Golf courses and municipal parks across Florida and the Sun Belt require controlled-release nitrogen to maintain aesthetic standards while complying with local watershed protection ordinances.
- Ornamental:Nursery and greenhouse operations in Oregon, Washington, and British Columbia utilize water-soluble powders and precision-fed liquid systems for container production.
Crops segment carries the heaviest tonnage. Horticulture climbs fastest on margin per acre expansion.
Form:
Application equipment legacy and irrigation infrastructure determine form selection across customer tiers, with slow-release formulations disrupting traditional timing windows.
- Granular:Diammonium phosphate and potash granules remain standard for no-till and minimum-till systems across the US Plains, compatible with existing spreader fleets and aerial application contracts.
- Liquid:Urea-ammonium nitrate solutions and micronutrient suspensions integrate with California's Central Valley drip and pivot irrigation systems, enabling direct-injection fertility management.
- Powder:Water-soluble formulations serve greenhouse and hydroponic operations requiring rapid dissolution and tank-mix compatibility with crop protection chemistries.
- Slow-Release:Polymer-coated urea and stabilized nitrogen products compress traditional split-application schedules into single-pass operations, meeting Iowa and Minnesota watershed reduction mandates.
Granular form retains the largest equipment-installed base. Slow-Release gains share fastest under regulatory pressure.
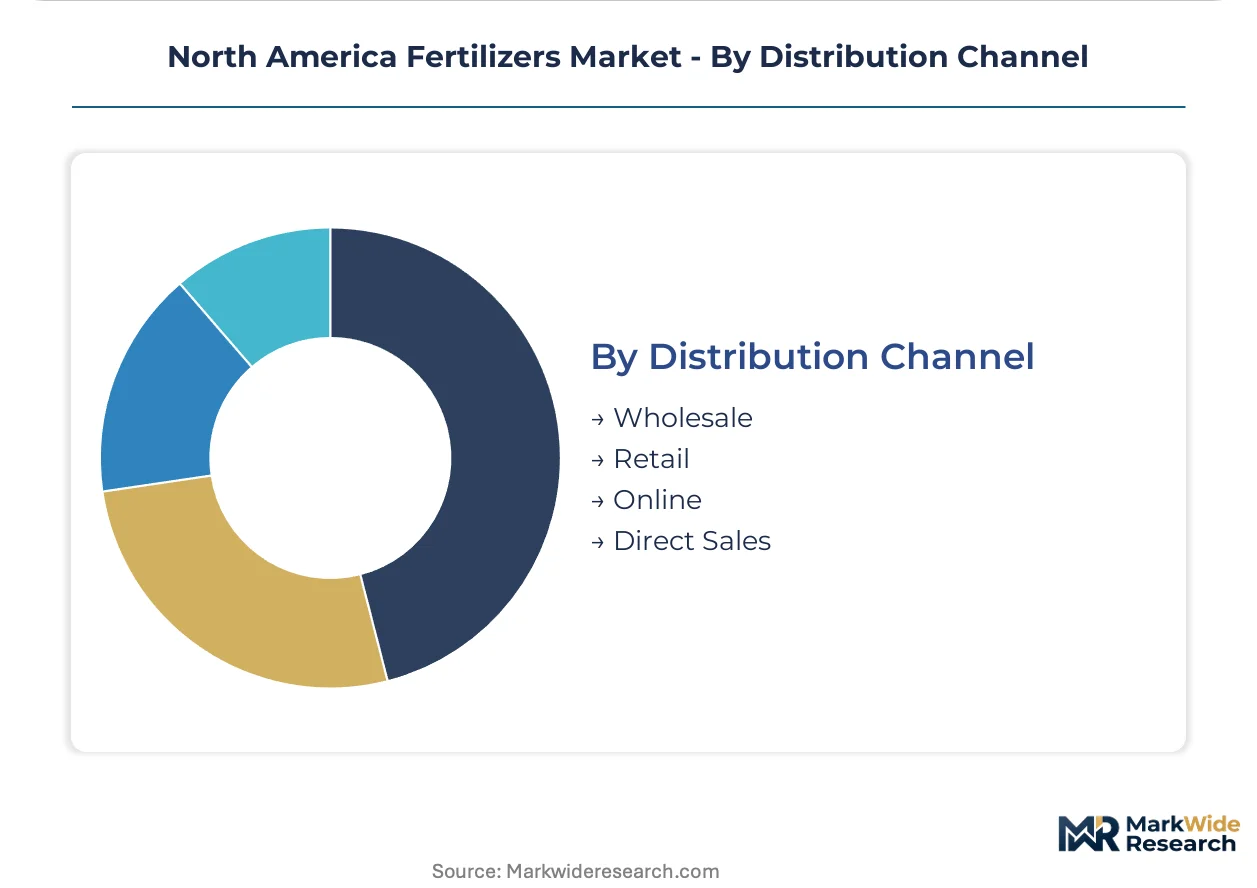
Distribution Channel:
Customer scale and agronomic service requirements stratify channel selection, with co-op networks and integrated retailers capturing acreage through bundled service contracts.
- Wholesale:Terminal and barge movements supply volume to blender and retailer networks across the Mississippi River corridor and Great Lakes distribution hubs.
- Retail:Local agronomy centers across Illinois and Iowa bundle soil testing, prescription mapping, and product fulfillment into annual service agreements, displacing transaction-based purchases.
- Online:Direct-to-farm platforms emerge for standardized commodity grades in regions with transparent pricing and established logistics infrastructure.
- Direct Sales:Large-scale corn and specialty crop operations contract directly with manufacturers for delivered-price tonnage, bypassing distributor markups on volume commitments.
Retail channel carries the deepest agronomic service integration. Direct Sales expands most quickly among operations exceeding 5,000 acres.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Corn Belt anchors North American fertilizer demand through intensive corn and soybean rotation systems spanning Iowa and Illinois.
United States
Corn Belt operations in Iowa and Illinois drive nitrogen volume through variable-rate application systems. The EPA enforces Clean Water Act nutrient runoff provisions across Midwest watersheds. Donaldsonville, Louisiana hosts the largest domestic ammonia production complex, supplying Gulf Coast terminals and barge networks.
Canada
Saskatchewan potash mines supply muriate of potash for potassium-deficient Plains soils and specialty crop regions. Health Canada's PMRA evaluates fertilizer-pesticide combination products under integrated regulatory frameworks. Integrated mining and distribution networks in Saskatchewan anchor supply security for North American potassium demand.
Mexico
Sinaloa and Sonora vegetable producers import nitrogen and phosphate formulations for winter vegetable exports to US markets. The country's national agricultural regulator oversees fertilizer quality standards and import licensing. Guadalajara distribution hubs channel imported urea and compound grades to central plateau grain operations.
California
Central Valley almond, citrus, and vegetable operations drive micronutrient-fortified formulation demand through drip irrigation injection systems. State Water Resources Control Board mandates nitrate reduction in groundwater basins. Fresno County fertilizer terminals stock liquid suspension products compatible with micro-irrigation infrastructure.
Florida
Specialty crop producers in the Lake Wales Ridge and Everglades Agricultural Area expand controlled-release nitrogen adoption for citrus and sugarcane. State watershed protection ordinances restrict nutrient application timing and rates near sensitive water bodies. Bone Valley phosphate mining and processing complexes supply domestic phosphate rock feedstock.
North America Fertilizers Market Competitive Landscape
Global majors compete with regional champions across production scale and distribution reach in North American fertilizer supply. The market structure concentrates upstream around integrated nitrogen and potash producers while fragmenting downstream through localized retail agronomy networks. Three archetypes dominate: integrated miners with captive raw material access, Gulf Coast ammonia specialists with pipeline and terminal infrastructure, and retail cooperatives bundling soil services with product fulfillment. Capacity expansion and backward integration into ammonia production represent the dominant competitive moves.
Within the integrated mining tier, Nutrien Ltd. and The Mosaic Company exemplify archetypes of geographic specialization—Nutrien through Saskatchewan potash integration and Mosaic through Florida phosphate rock reserves. CF Industries Holdings, Inc. anchors the nitrogen-specialist position with Gulf Coast ammonia infrastructure. These three occupy positions that define competitive boundaries around raw material access, production scale, and distribution density across the Corn Belt and specialty crop regions.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| Nutrien Ltd. |
| The Mosaic Company |
| The Andersons Inc. |
| Yara International ASA |
| Koch Industries Inc. |
| CVR Partners, LP |
| Archer Daniels Midland Company |
| EuroChem Group AG |
| Others |
Value Network & Pricing Analysis
Henry Hub natural gas pricing cascades through North American fertilizer supply chains, compressing margins at Gulf Coast ammonia facilities and forcing tiered pricing stratification across commodity nitrogen, enhanced-efficiency formulations, and micronutrient-fortified specialty grades.
Pricing Analysis
Input-cost pass-through from natural gas feedstock dominates nitrogen pricing dynamics, with Henry Hub volatility transmitting directly to urea and ammonia quotations. Three-tier pricing structure across premium enhanced-efficiency coatings, standard granular grades, and economy bulk urea reflects certification tier and volume scale differentiation. Pricing pressure stems from compressed margins at US Gulf Coast facilities when gas costs spike, forcing spot market softness. Large-scale Corn Belt cooperatives exhibit lowest price sensitivity due to contracted offtake agreements, while smaller Plains operators remain exposed to spot market swings.
Supply Chain Analysis
Direct-to-farm channels handle bulk nitrogen demand across Iowa and Illinois, while wholesale terminal networks supply California specialty crop regions and Florida phosphate processing complexes. Geographic supply concentration centers on the United States, Canada, and Trinidad and Tobago for ammonia feedstock. Raw material dependencies include natural gas, phosphate rock from Florida's Bone Valley, and Saskatchewan potash ore. Single-source vulnerability around Florida phosphate mining creates hurricane-related disruption risk. Distribution runs through Mississippi River barge corridors, Great Lakes terminals, and rail-fed inland depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Fertilizers Market functions as a stable compounder anchored by non-discretionary nutrient replacement cycles in corn-soybean rotations, with regulatory tightening on runoff controls ensuring sustained demand for premium formulations.
For Market Incumbents: To counter margin compression from Henry Hub volatility, deploy backward integration into low-carbon ammonia production using renewable hydrogen feedstocks. Lock in long-term offtake agreements with Corn Belt cooperatives to secure volume commitments against spot market exposure. Invest in polymer-coating capacity to capture enhanced-efficiency premium pools as Iowa and Minnesota watershed mandates tighten.
For New Entrants and Emerging Players: Mid-scale specialty crop operators in California's Central Valley represent an underserved buyer archetype seeking micronutrient-fortified liquid formulations compatible with drip irrigation infrastructure. Target direct-injection system integration as the go-to-market angle, bypassing established granular distribution networks. Focus initial penetration on almond and citrus operations where yield optimization justifies premium pricing.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated potash-phosphate producers possessing captive ore reserves and Corn Belt distribution density. Five-to-ten-year viability hinges on carbon-intensity certification thresholds reshaping procurement criteria. Monitor EPA nutrient reduction strategy enforcement velocity across Midwest watersheds as the inflection indicator for enhanced-efficiency product mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Hydrogen Integration | Low-carbon ammonia certification opens premium procurement channels across EPA-regulated watersheds. |
| Polymer-Coating Capacity Expansion | Controlled-release nitrogen captures margin pools as Iowa and Minnesota mandate runoff reductions. |
| Direct-to-Farm Platform Development | Bypassing retail markups attracts operations exceeding 5,000 acres in Illinois and Iowa. |
| Micronutrient Formulation Diversification | Boron and zinc fortification serves California almond and citrus yield optimization demand. |
| Saskatchewan Potash Mining Expansion | Captive ore reserves anchor supply security for potassium-deficient northern Plains soils. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with agronomy retail managers, fertilizer procurement leads at large-scale corn operations, potash mining executives, and EPA regulatory affairs specialists informed demand-side and supply-side dynamics. Secondary sources include USDA crop production reports, EPA Clean Water Act enforcement databases, SEC 10-K filings from integrated producers, and Canadian customs trade statistics. Bottom-up acreage-by-acreage demand modeling and top-down macroeconomic calibration ensure cross-verified output reliability.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include product type, application crop category, physical form, and distribution channel, with additional granularity on enhanced-efficiency coating penetration rates. CAGRs derive from regression analysis against planted acreage trends, yield improvement trajectories, and regulatory compliance cost pass-through assumptions. Forecast inputs incorporate natural gas price scenario modeling and watershed reduction mandate implementation schedules.
Underlying measurement precision varies by segment; nitrogenous and potash categories carry tighter precision than emerging biological amendment segments due to established reporting infrastructure. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and crop commodity price cycles. Fertilizer-pesticide combination product approval timelines under Canada's PMRA framework represent a specific revision risk. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Single Superphosphate (SSP) Market