
 Asia-Pacific Agricultural Machinery Market | 2026-2036
Asia-Pacific Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Machinery Market Outlook
Precision-grade automation is redrawing competitive boundaries in Asia-Pacific agricultural equipment. KUBOTA Corporation leverages its dominance in compact tractor engineering to anchor Japan's premium machinery segment. Mahindra & Mahindra Ltd sustains formidable channel control across India's rural distribution networks. Yanmar Co. Ltd. specializes in diesel-electric hybrid powertrains for rice cultivation systems, competing intensely with domestic Chinese manufacturers in Southeast Asian export markets.
Asia-Pacific agricultural machinery encompasses powered and towed equipment designed for soil preparation, planting, cultivation, harvesting, and post-harvest processing, typically featuring engine outputs ranging from 15 horsepower for walk-behind units to over 300 horsepower for articulated four-wheel-drive tractors. These machines serve to replace manual and animal traction labor, reduce crop cycle times, and enable scale economies across fragmented landholdings. Tractors occupy the largest revenue pool given their universal deployment across all farming operations, while harvesters represent the fastest-growing product category as contract farming expands in Vietnam and Thailand. GPS-enabled technology commands premium pricing but IoT integration is gaining traction fastest among cooperative societies seeking fleet optimization across dispersed holdings.
India's BIS certification mandates and Australia's ACCC consumer safety standards shape equipment specifications for regional market access, while Japan's METI energy-efficiency regulations drive R&D investment in electric drivetrains. China's MIIT equipment subsidy program and GB standards compliance requirements determine which foreign manufacturers qualify for provincial procurement tenders. Stakeholders must monitor evolving carbon-accounting rules under the EU Green Deal's extraterritorial supply chain provisions, as European import standards increasingly condition Asian farm machinery export competitiveness.
Market Dynamics
Commercial farm consolidation across Southeast Asia is compressing equipment replacement cycles while forcing precision technology integration into mid-tier machinery specifications previously reserved for premium segments.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for farm equipment manufacturing are accelerating localized component sourcing and reducing import dependency for critical drivetrain assemblies.
- Contract farming expansion:Vietnam and Thailand's agribusiness operators are mandating GPS-enabled fleet tracking to coordinate harvest logistics across dispersed supplier networks.
- Soil compaction sensors:Variable-pressure tire systems are penetrating Australia's Murray-Darling Basin operations as water-stressed growers optimize traction efficiency.
Market Restraints
- Steel and rare earth input volatility:Permanent magnet motor costs fluctuate with Chinese export quota adjustments, squeezing margin structures for electric drivetrain manufacturers.
- Technical limitation of battery energy density:Current lithium-ion configurations cannot sustain full-day field operations for 200+ horsepower equipment without mid-cycle charging infrastructure.
- Japan's METI energy-efficiency regulations:Tier 4 Final compliance requirements for imported diesel engines create certification bottlenecks for European and North American suppliers.
Strategic Opportunities
- Indonesia's outer island plantation belt:Palm oil and rubber estates in Sumatra and Kalimantan remain underserved by precision agriculture service providers.
- Drone-sprayer convergence:Unmanned aerial application systems are integrating with ground-based variable-rate equipment for hybrid crop protection protocols.
- Australia's ACCC farm machinery safety mandates:Rollover protection and guarding standards are forcing fleet upgrades among aging owner-operator holdings.
Industry Challenges
- Mechatronics technician scarcity:Hydraulic-electronic system integration expertise lags equipment complexity across India's service network.
- China's MIIT subsidy qualification timelines:Provincial tender documentation requirements extend sales-to-delivery cycles by 4-8 months for foreign manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Machinery Market |
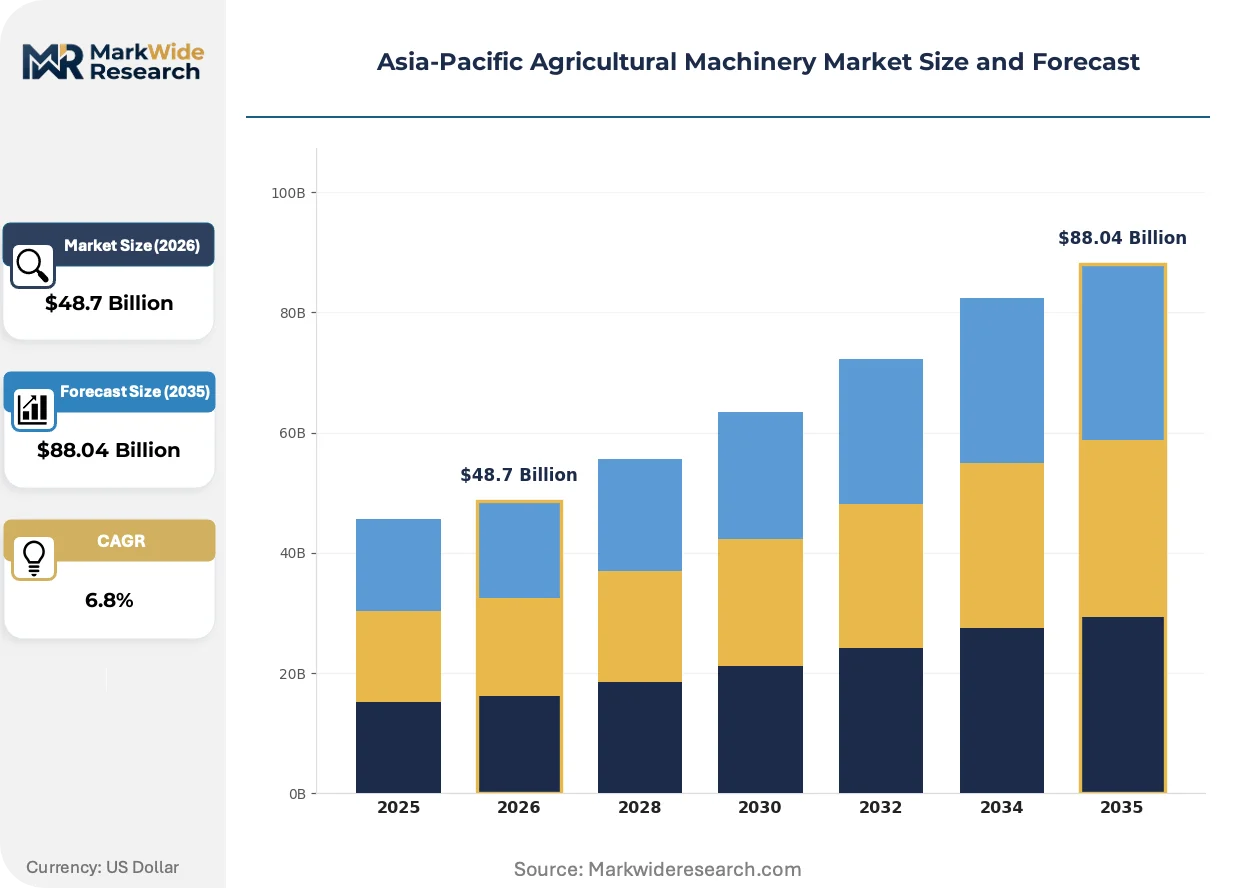
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harvesters, Seeders Application: Crop Farming, Livestock Farming, Forestry, Aquaculture End User: Commercial Farms, Cooperative Societies, Individual Farmers, Agricultural Enterprises Technology: GPS, Automation, IoT, Electric |
| Companies Covered | KUBOTA Corporation, Yanmar Co. Ltd., Deere & Company, International Tractors Ltd., CLAAS KGaA mbH, AGCO Corporation, CNH Industrial N.V., Zoomlion Heavy Industry Science & Technology Co., Ltd., Mahindra & Mahindra Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Machinery Market Strategic Shifts
Electrification architectures and autonomous navigation stacks are converging to redefine equipment value propositions beyond horsepower metrics toward total cost of ownership optimization.
Sensor fusion systems combining LiDAR, radar, and computer vision are miniaturizing from research platforms into production harvester guidance packages. Japanese rice farming cooperatives are adopting these configurations faster than wheat belt operators due to smaller field geometries requiring centimeter-level accuracy. Component cost curves are compressing entry thresholds for mid-scale equipment buyers previously excluded from automation tiers.
China's GB standards compliance framework for agricultural drones is mandating encrypted flight data logging and geofencing capabilities for all commercial units. Equipment manufacturers must embed domestic satellite navigation chipsets to qualify for provincial subsidy pools. Foreign suppliers are responding through joint venture structures with local avionics integrators rather than direct certification attempts.
Service contract unbundling is separating hardware ownership from maintenance and software update obligations across Australian broadacre operations. Dealer networks are repositioning as fleet optimization consultants rather than transactional sales channels. This restructuring concentrates most visibly in Western Australia's wheatbelt, where corporate farming entities negotiate enterprise-level uptime guarantees spanning mixed-brand equipment portfolios.
Asia-Pacific Agricultural Machinery Market Segmentation
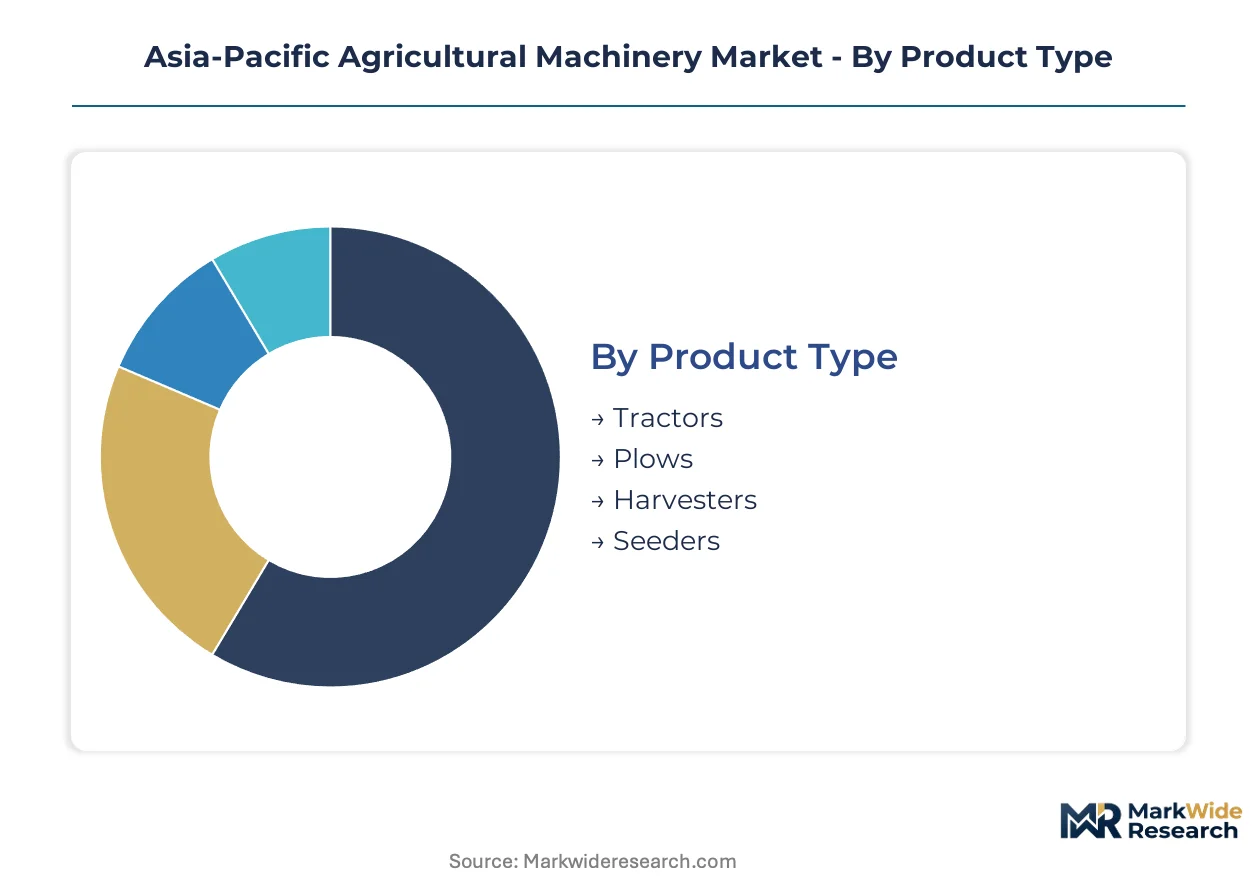
Segmentation in Asia-Pacific agricultural machinery reveals how regulatory frameworks and operational scale dictate technology adoption patterns across heterogeneous farming systems. Equipment specifications diverge sharply between India's subsidy-driven smallholder markets and Australia's corporate broadacre operations.
Product Type:
Japan's METI energy-efficiency regulations and India's BIS certification mandates create divergent compliance pathways that reshape equipment specifications across each product category.
- Tractors:Engine outputs span 15-300 horsepower configurations, with compact diesel-electric hybrids dominating Japan's rice paddy operations. Australia's Murray-Darling Basin operators are specifying variable-pressure tire systems to reduce soil compaction under water-stressed conditions.
- Harvesters:Combine harvesters integrate LiDAR-guided navigation stacks for centimeter-level accuracy in fragmented field geometries. Vietnam and Thailand's contract farming operators are mandating GPS-enabled fleet tracking to coordinate harvest logistics across dispersed supplier networks, making this category expand most quickly.
- Plows:Disc and moldboard configurations adapt to Indo-Gangetic Plain alluvial soils versus Australia's heavy clay duplex profiles. China's GB standards compliance determines foreign manufacturer access to provincial subsidy pools.
- Seeders:Precision planting equipment with variable-rate capability penetrates commercial farm segments while manual broadcast seeders persist among India's individual farmer tier.
Established volume favors tractors; emerging adoption favors harvesters.
Application:
Operational intensity and labor substitution economics vary dramatically across farming system types, driving divergent mechanization priorities.
- Crop Farming:Rice-wheat rotation systems in India's Indo-Gangetic Plain demand specialized transplanting and threshing equipment. Soil compaction sensors are penetrating Australia's Murray-Darling Basin as water-stressed growers optimize traction efficiency.
- Livestock Farming:Automated feeding systems and manure handling equipment address labor scarcity in Australia's dairy corridors. Indonesia's outer island plantation belt remains underserved by precision agriculture service providers for forage production.
- Forestry:Harvester-forwarder combinations face Australia's ACCC safety mandates for rollover protection and guarding standards. China's MIIT equipment subsidy program shapes domestic versus import equipment mix.
- Aquaculture:Automated feeding barges and water quality monitoring platforms serve intensive shrimp operations across Vietnam's Mekong Delta. Regulatory frameworks for aquaculture equipment remain less codified than terrestrial machinery standards.
Revenue concentration sits with crop farming; technology upgrade intensity peaks in livestock farming.
End User:
Purchasing power and fleet management sophistication create distinct customer tiers with divergent service expectations and financing requirements.
- Commercial Farms:Corporate operators in Western Australia's wheatbelt negotiate enterprise-level uptime guarantees spanning mixed-brand equipment portfolios. Service contract unbundling separates hardware ownership from maintenance obligations.
- Cooperative Societies:Fleet optimization across dispersed holdings drives IoT integration faster than among individual operators. Shared machinery pools require standardized telemetry platforms for coordination.
- Individual Farmers:India's PLI scheme accelerates localized production for price-sensitive smallholders. Financing constraints limit specification upgrades despite subsidy availability.
- Agricultural Enterprises:Plantation operators in Sumatra and Kalimantan source heavy equipment through integrated service contracts rather than transactional purchases.
Unit economics favor commercial farms; subsidy leverage favors individual farmers.
Technology:
Energy transition mandates and data sovereignty requirements are restructuring technology adoption pathways across the region.
- GPS:Premium positioning for precision agriculture commands higher equipment pricing. China's GB standards mandate encrypted flight data logging and geofencing capabilities, requiring domestic satellite navigation chipsets for subsidy qualification.
- Automation:Sensor fusion systems combining LiDAR, radar, and computer vision miniaturize into production harvester guidance packages. Japanese rice farming cooperatives adopt these faster than wheat belt operators due to smaller field geometries.
- IoT:Fleet optimization platforms penetrate cooperative societies seeking coordination across dispersed holdings. Component cost curves compress entry thresholds for mid-scale equipment buyers.
- Electric:Battery energy density limitations constrain full-day field operations for 200+ horsepower equipment without mid-cycle charging infrastructure. Japan's METI regulations drive R&D investment in electric drivetrains.
Near-term deployment favors GPS; regulatory tailwinds favor electric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for critical drivetrain assemblies tilts the Asia-Pacific agricultural machinery trade balance toward net-importing economies, while localized production incentives in India and subsidy-driven procurement in China reshape regional supply flows.
India
Commercial farm consolidation across the Indo-Gangetic Plain accelerates precision technology uptake among large-scale wheat and rice operators. India's PLI scheme for farm equipment manufacturing mandates localized component sourcing, reducing import dependency for transmission assemblies. Haryana and Punjab manufacturing clusters now host expanded tractor assembly capacity serving domestic demand and Southeast Asian export markets.
China
Provincial procurement tenders for mechanized farming equipment concentrate demand in the Yangtze River Delta and North China Plain grain belts. China's MIIT equipment subsidy program requires GB standards compliance and domestic satellite navigation chipsets for qualification, favoring joint venture structures over direct foreign certification. Shandong and Henan provinces dominate domestic harvester production for corn and wheat operations.
Japan
Compact diesel-electric hybrid tractors for rice paddy operations anchor domestic manufacturing output, with METI energy-efficiency regulations driving R&D investment in electric drivetrains. Tier 4 Final compliance requirements for imported diesel engines create certification bottlenecks for European and North American suppliers. Nagoya and Osaka industrial corridors concentrate precision component fabrication for regional export.
Australia
Broadacre wheat and cotton operations across the Murray-Darling Basin specify variable-pressure tire systems to reduce soil compaction under water-stressed conditions. ACCC farm machinery safety mandates for rollover protection and guarding standards force fleet upgrades among aging owner-operator holdings. Western Australia's wheatbelt hosts corporate farming entities negotiating enterprise-level uptime guarantees across mixed-brand equipment portfolios.
Vietnam
Contract farming expansion across the Mekong Delta mandates GPS-enabled fleet tracking to coordinate harvest logistics across dispersed rice and aquaculture supplier networks. Technical limitation of battery energy density constrains full-day field operations for larger equipment without mid-cycle charging infrastructure. Can Tho and An Giang provinces concentrate mechanized rice transplanting and threshing equipment demand.
Asia-Pacific Agricultural Machinery Market Competitive Environment
Concentration sits with diversified industrial conglomerates possessing captive distribution networks across fragmented rural markets. Japanese and Indian manufacturers anchor premium and mid-tier segments respectively, while European and North American suppliers compete through technology licensing arrangements. Three strategic archetypes dominate: compact equipment specialists, full-line diversified manufacturers, and precision technology integrators. Competitive moves center on backward integration into critical component production and strategic partnerships for localized assembly qualification.
Within the diversified manufacturing tier, Mahindra & Mahindra Ltd and KUBOTA Corporation exemplify contrasting geographic anchoring strategies, while Yanmar Co. Ltd occupies a specialist position in hybrid powertrain engineering for rice cultivation systems. These three entities represent distinct competitive postures—Indian rural distribution density, Japanese precision engineering heritage, and diesel-electric hybrid specialization—each responding differently to regional regulatory fragmentation.
| Leading Market Players |
|---|
| KUBOTA Corporation |
| Yanmar Co. Ltd. |
| Deere & Company |
| International Tractors Ltd. |
| CLAAS KGaA mbH |
| AGCO Corporation |
| CNH Industrial N.V. |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Mahindra & Mahindra Ltd |
| Others |
Value Chain & Pricing Dynamics
China's MIIT equipment subsidy program and GB standards compliance gates both supply qualification and price differentiation simultaneously, as provincial tender access requires domestic satellite navigation chipsets that foreign manufacturers can only source through joint ventures, compressing margin structures for direct exporters while elevating qualified domestic-assembled equipment.
Pricing Analysis
Commercial farms anchor pricing structures across the Asia-Pacific agricultural machinery market. Three-tier pricing stratification separates GPS-enabled precision systems from mid-tier automation packages and basic mechanical equipment. Price differentiation rests on certification grade under Japan's METI energy-efficiency regulations and India's BIS mandates, plus after-sales service bundling. Cost compression in electric drivetrain tiers is intensifying because permanent magnet motor costs fluctuate with Chinese rare earth export quotas. Individual farmers in India's subsidy-driven smallholder segment exhibit highest price sensitivity, while Australian corporate broadacre operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of critical drivetrain assemblies dominates inventory strategy among regional manufacturers, buffering against Chinese export quota volatility. Component sourcing concentrates in China, India, and Japan. Supply chains draw from permanent magnet motors, lithium-ion battery cells, and precision hydraulic systems. Single-source vulnerability in rare earth processing creates structural exposure. Distribution runs through captive dealer networks and cooperative society procurement channels across fragmented rural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
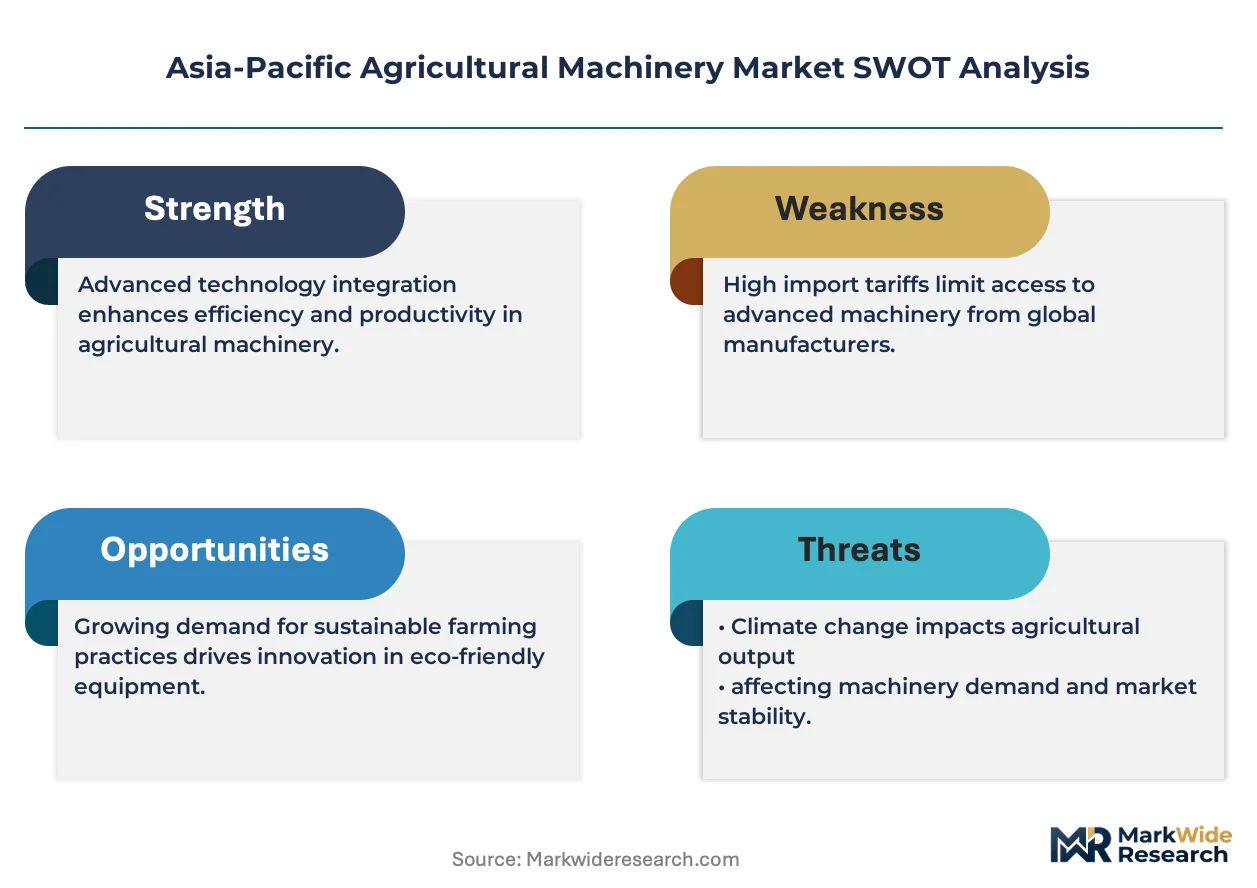
The Asia-Pacific agricultural machinery market represents a high-growth electrification disruption, with Japan's METI energy-efficiency regulations and battery energy density limitations creating a narrow window for first-mover advantage in electric drivetrain segments.
For Market Incumbents: Fortify backward integration into permanent magnet motor production to offset Chinese rare earth quota exposure. Deepen channel control across India's rural distribution networks before PLI scheme localization matures. Prioritize R&D investment in battery-swapping infrastructure to circumvent energy density constraints in 200+ horsepower equipment segments. For New Entrants and Emerging Players: Lead with drone-sprayer convergence systems targeting Indonesia's outer island plantation belt in Sumatra and Kalimantan, where precision agriculture service providers remain underserved. Penetrate Vietnam's Mekong Delta contract farming networks through GPS-enabled fleet tracking as a service rather than equipment sales. Pursue joint venture structures with local avionics integrators to satisfy China's GB standards compliance without direct certification attempts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric drivetrain manufacturing as battery cell production scales. Long-term viability over the coming decade favors vertically integrated manufacturers with captive component supply. Target acquisition candidates possess established provincial tender qualification in China and India's PLI scheme certification. Watch for inflection when battery energy density improvements enable full-day field operations without mid-cycle charging infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Reduces exposure to Chinese rare earth export quota volatility for electric drivetrain manufacturers. |
| Joint Venture with Local Avionics Integrators | Enables GB standards compliance and provincial subsidy access without direct foreign certification. |
| Drone-Sprayer Convergence Platform Launch | Captures hybrid crop protection protocols across Indonesia's underserved plantation belt. |
| Service Contract Unbundling | Positions dealer networks as fleet optimization consultants across Australia's corporate wheatbelt. |
| Battery-Swapping Infrastructure Deployment | Circumvents lithium-ion energy density constraints for large-horsepower field operations. |
Study Parameters
A standing panel of agricultural equipment procurement managers, cooperative society fleet coordinators, aftermarket service technicians, and provincial tender documentation specialists provided ongoing calibration throughout the study. Primary interview insights combined with secondary validation from customs and trade data, MIIT subsidy disbursement records, BIS certification registries, and METI energy-efficiency compliance filings. Bottom-up equipment shipment tracking and top-down macroeconomic indicators underwent triangulation to ensure convergence.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application, end user, and technology tier alongside regional regulatory cluster variations. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-referencing to agricultural GDP elasticity and mechanization penetration rates as industry-specific forecast inputs.
Forecasts assume regulatory continuity in China's MIIT subsidy regime, India's PLI scheme, and Japan's METI energy-efficiency standards; material policy shifts would require re-modeling. Revision becomes warranted when battery energy density improvements or rare earth supply disruptions cross thresholds that fundamentally alter equipment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Australia Agricultural Machinery Market