
 United Kingdom Agricultural Machinery Market | 2026-2036
United Kingdom Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Agricultural Machinery Market Analytics
Tier-four emissions compliance is rotating the United Kingdom agricultural machinery market toward higher-specification powertrain platforms. Deere & Company leverages its integrated precision agriculture stack to dominate premium tractor configurations. J.C. Bamford Excavators Ltd. sustains British manufacturing heritage through specialized loader and handler production at its Staffordshire base. Kubota Corporation anchors compact utility segments where smaller farm holdings require maneuverable, fuel-efficient platforms.
United Kingdom agricultural machinery encompasses self-propelled and trailed equipment engineered for soil cultivation, crop establishment, harvesting, and livestock support, typically featuring power outputs from 25 hp to 600 hp and compliance with Stage V exhaust emission thresholds. Tractors and harvesters constitute the mature volume core where replacement cycles drive steady revenue, while precision farming technology captures expanding margin pools as subscription-based telemetry and variable-rate application systems penetrate arable operations. Soil sensors and autonomous machinery represent the fastest-advancing technology categories, though full autonomous deployment remains constrained by field topology variability and operator trust gaps.
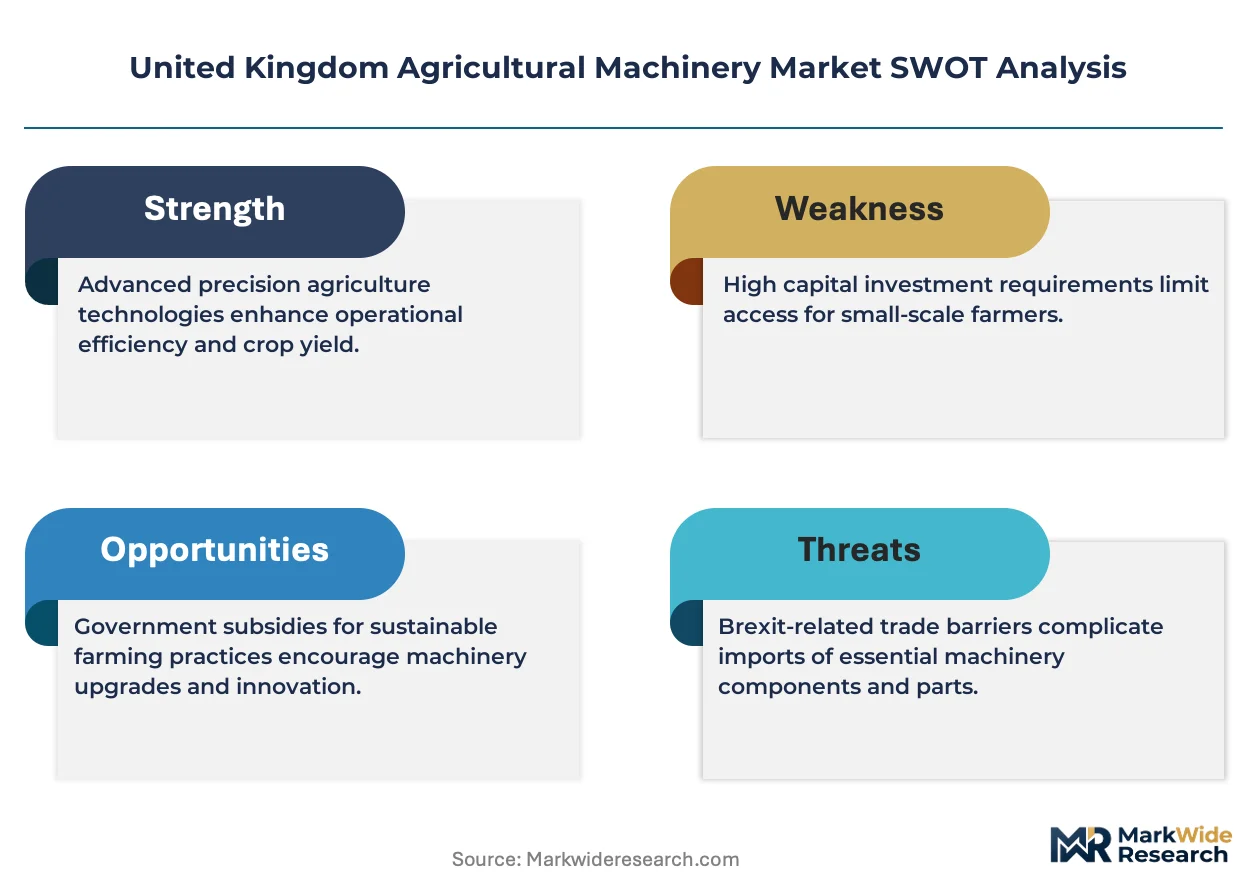
DEFRA's farming subsidy restructuring and the Environment Agency's water quality regulations are reshaping equipment specification requirements, particularly around nutrient application precision and soil disturbance minimization. The Health and Safety Executive's machinery guarding standards further constrain market access for non-compliant imports. Stakeholders must weigh the capital allocation trade-off between proven mechanical platforms and emerging autonomous systems whose total cost of ownership remains unproven at commercial scale.
Market Dynamics
DEFRA's Sustainable Farming Incentive is redirecting capital flows toward precision-enabled equipment platforms, compressing replacement cycles for conventional mechanical systems across England's arable belt.
Growth Catalysts
- Stage V emission thresholds:The Environment Agency's exhaust standards are mandating powertrain upgrades across the tractor fleet, forcing equipment turnover that benefits Tier-four compliant manufacturers.
- Soil sensor telemetry:Variable-rate application systems are penetrating East Anglia's cereal operations as farmers optimize nitrogen placement to meet water quality regulations.
- East Anglia cluster:Intensive acreage management in this region is concentrating demand for high-horsepower tractors and combine harvesters with integrated guidance systems.
Market Restraints
- Steel input volatility:Chassis and implement fabrication costs fluctuate with commodity metal pricing, compressing margins for domestic manufacturers dependent on imported sheet steel.
- Powertrain supply concentration:Engine block sourcing clusters in Germany and Italy, exposing assemblers to extended lead times during continental production disruptions.
- Autonomous deployment gap:Field topology variability across the Scottish Highlands and Welsh uplands constrains GPS-dependent self-driving systems from achieving commercial scale.
Strategic Opportunities
- Livestock sector penetration:Dairy and beef operations in the West Midlands remain under-mechanized for precision feeding and manure management, offering whitespace for compact automated platforms.
- Technology convergence:Drone-based crop scouting fused with tractor-mounted variable-rate controllers is enabling real-time prescription maps without separate service contracts.
- Rental channel expansion:Short-term equipment leasing through agricultural cooperatives is lowering capital barriers for tenant farmers in Yorkshire's fragmented land tenure system.
Industry Challenges
- Telematics integration complexity:Legacy mechanical fleets lack CAN bus architecture, forcing costly retrofits to connect older tractors to farm management software platforms.
- Certification timeline compression:The Health and Safety Executive's machinery guarding standards require extended validation periods for imported equipment, delaying market entry for non-EU manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Agricultural Machinery Market |
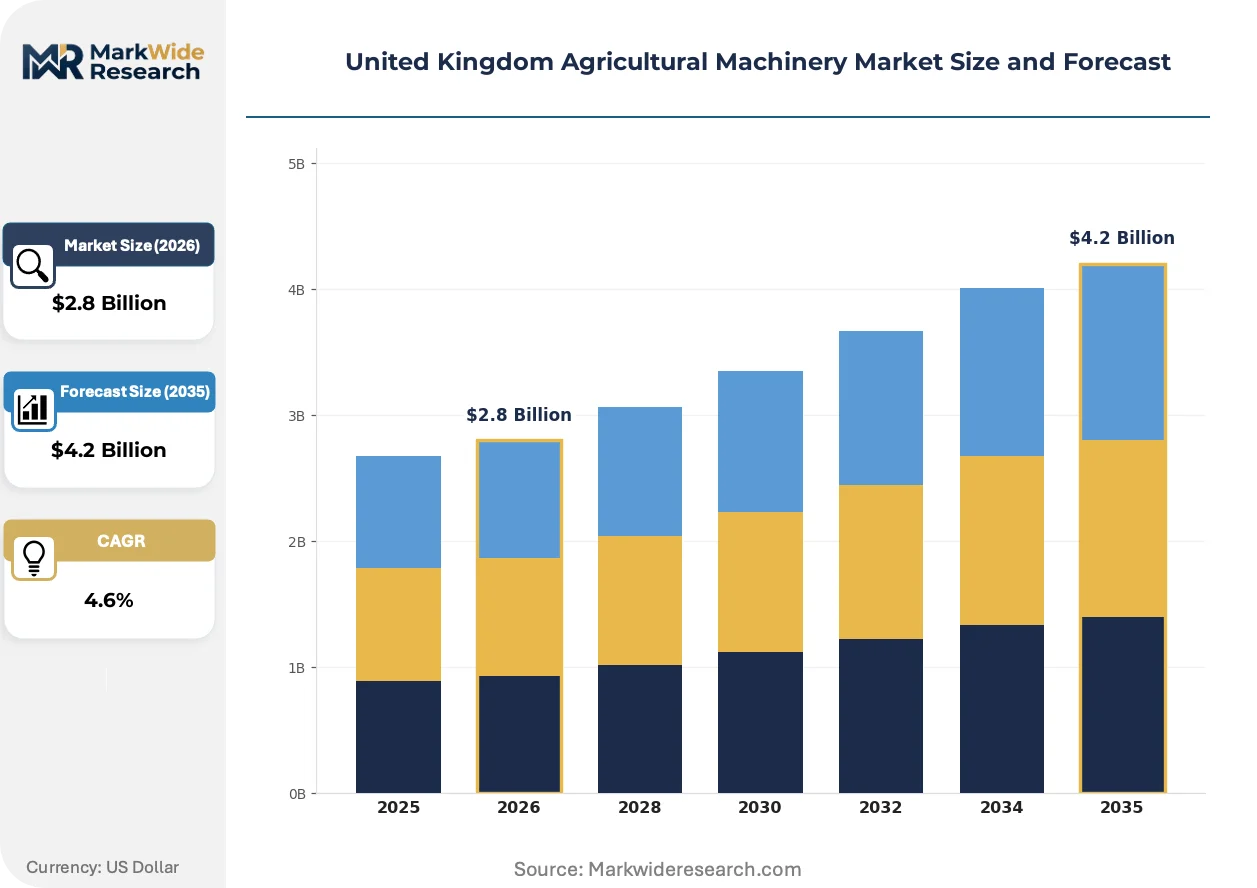
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders Technology: Precision Farming, Autonomous Machinery, Soil Sensors, Irrigation Systems End Use Industry: Crop Production, Livestock Farming, Agricultural Research, Agrochemical Production Distribution Channel: Retail, Direct Sales, Online Platforms, Agri-dealers |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, J.C. Bamford Excavators Ltd., Kubota Corporation, Claas KGaA mbH, Kuhn Group, SDF Group S.p.A., LEMKEN GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Agricultural Machinery Market Evolving Landscape
Electrification and autonomous control architectures are displacing hydraulic actuation and operator-dependent workflows across the equipment spectrum, with software-defined functionality now determining competitive differentiation more than mechanical specifications.
Sensor fusion technology for real-time soil composition mapping is miniaturizing from laboratory-grade spectrometers to tractor-embedded probes. Arable contractors in Lincolnshire are adopting these platforms at replacement cycle points. The technology is miniaturizing capital requirements for precision agriculture, compressing the performance gap between premium and mid-tier equipment configurations.
DEFRA's Environmental Land Management scheme is conditioning subsidy payments on documented soil health improvements. Equipment specification requirements now prioritize minimal disturbance tillage and targeted nutrient application. Mixed farming operations in the Cotswolds are retrofitting existing tractors with strip-till attachments to maintain eligibility.
Cooperative procurement consortia are consolidating equipment purchasing across multiple farm holdings. Traditional dealer networks face margin pressure as buying groups negotiate fleet-scale discounts directly with manufacturers. This consolidation is most visible in Cambridgeshire where estate managers coordinate synchronized replacement cycles for combines and self-propelled sprayers.
United Kingdom Agricultural Machinery Market Segmentation
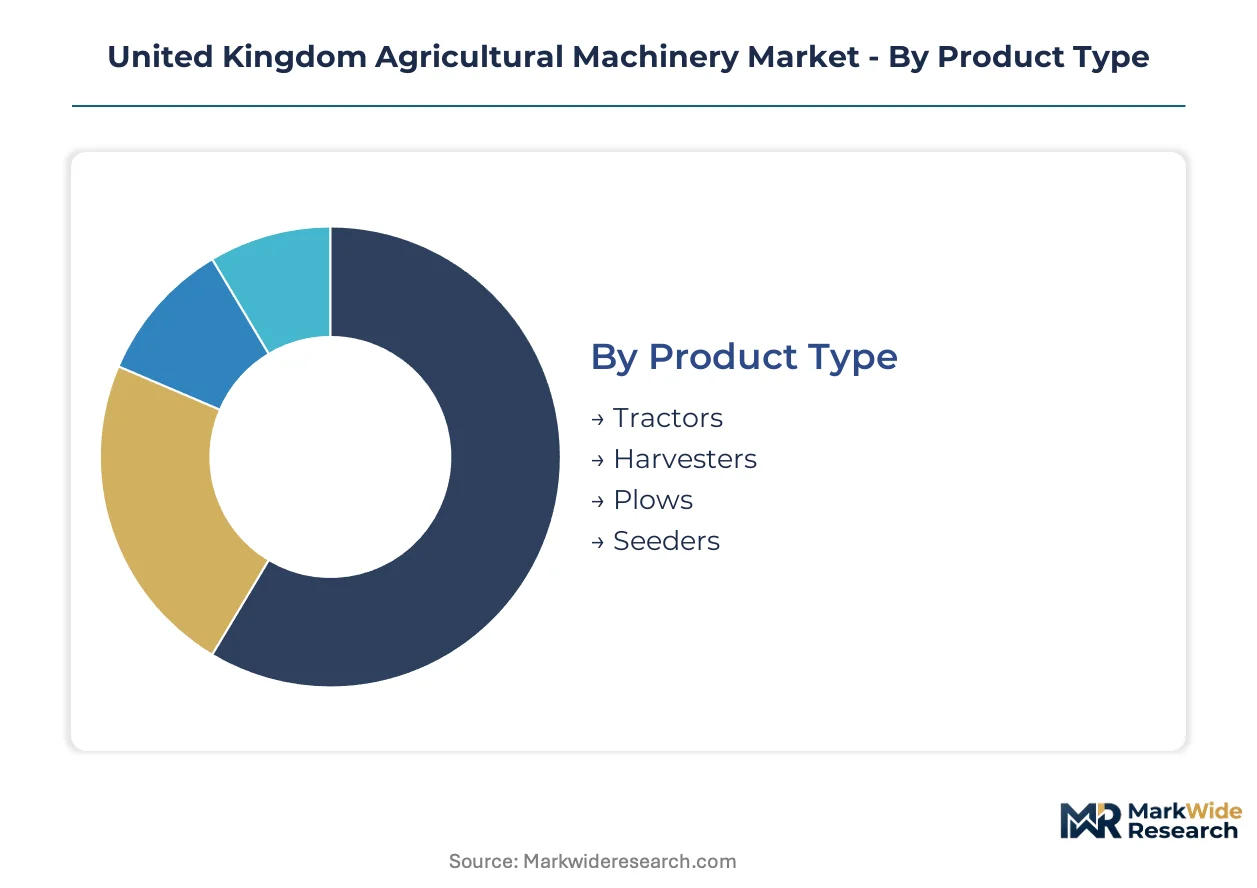
Equipment specification requirements in the United Kingdom diverge sharply across DEFRA's subsidy tiers and regional farming intensities. Manufacturers configure powertrain and precision technology bundles differently for each segment to capture replacement cycle timing and compliance-driven capital flows.
Product Type:
DEFRA's Stage V emission thresholds apply differentially across power outputs, creating regulatory pressure that concentrates upgrade investment in specific horsepower bands.
- Tractors:Self-propelled platforms ranging from 25 hp compact utility units to 600 hp articulated configurations dominate capital allocation across East Anglia's cereal belt. DEFRA's Sustainable Farming Incentive accelerates replacement cycles for mid-range powertrains that lack Tier-four compliance.
- Harvesters:Combine platforms with integrated yield mapping and real-time moisture sensing command premium positioning in Lincolnshire's contractor fleets. The Environment Agency's water quality regulations are conditioning specification requirements around precision header control and residue management systems.
- Plows:Trailed tillage implements face margin compression as minimal-disturbance subsidy conditions redirect demand toward strip-till alternatives.
- Seeders:Drilling equipment with variable-rate controllers penetrates arable operations seeking nitrogen placement optimization for ELM scheme eligibility.
Tractors handle the majority of throughput; seeders are expanding most quickly on share as precision placement technology miniaturizes.
Technology:
Margin pools concentrate where software-defined functionality displaces mechanical differentiation and recurring telemetry subscriptions supplement equipment revenue.
- Precision Farming:Integrated guidance, yield mapping, and prescription agriculture platforms now determine competitive positioning more than horsepower specifications. Arable contractors in Cambridgeshire prioritize subscription-based telemetry bundles at replacement cycle points.
- Soil Sensors:Real-time composition mapping probes are miniaturizing from laboratory-grade spectrometers to tractor-embedded units. Cotswolds mixed farming operations deploy these for documented soil health improvements required by Environmental Land Management scheme conditions.
- Autonomous Machinery:GPS-dependent self-driving systems remain constrained by field topology variability across Scottish Highlands terrain and operator trust gaps in commercial deployment.
- Irrigation Systems:Precision water application equipment penetrates specialty crop holdings in Kent's fruit belt where water abstraction licensing tightens supply security.
Precision farming commands the dominant revenue share; soil sensors are gaining share fastest as capital requirements compress performance gaps between equipment tiers.
End Use Industry:
Subsidy restructuring and regulatory compliance timelines create divergent equipment replacement urgency across production systems.
- Crop Production:Intensive arable operations in East Anglia concentrate demand for high-horsepower tractors and combine harvesters with integrated guidance. DEFRA's Sustainable Farming Incentive redirects capital toward precision-enabled platforms that document input optimization.
- Livestock Farming:Dairy and beef operations in the West Midlands remain under-mechanized for precision feeding and manure management, offering whitespace for compact automated platforms targeting nutrient application compliance.
- Agricultural Research:University and institutional fleets prioritize sensor-dense configurations for field trial documentation and breeding program data capture.
- Agrochemical Production:Corporate demonstration farms and trial stations specify equipment platforms that validate product performance claims under controlled conditions.
Crop production absorbs the bulk of equipment throughput; livestock farming is climbing fastest as precision feeding technology penetrates previously mechanical operations.
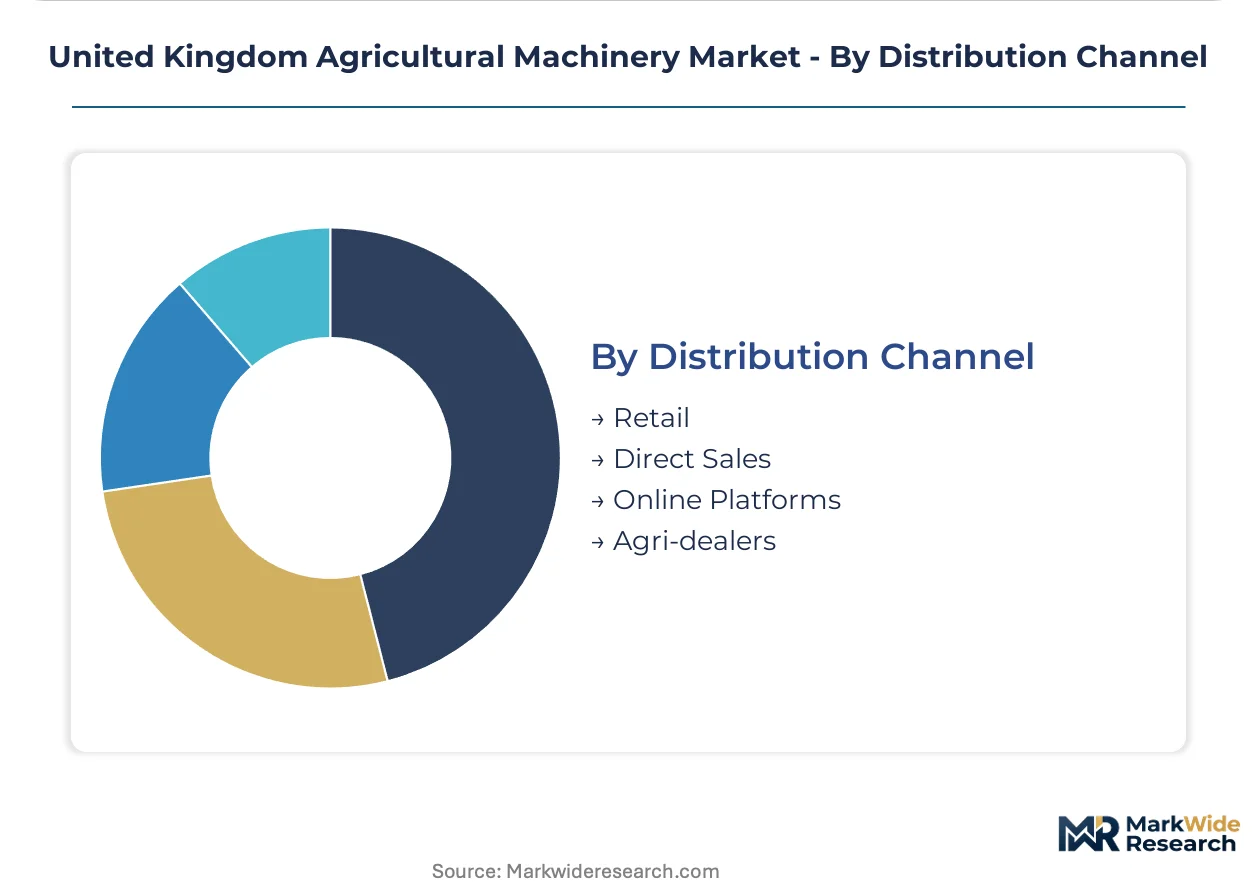
Distribution Channel:
Procurement consolidation through cooperative structures is compressing traditional dealer margins and redirecting volume toward direct manufacturer relationships.
- Agri-dealers:Established networks with service bay capacity and parts inventory dominate replacement part revenue and warranty work across England's arable belt. Technician certification requirements for Stage V powertrain maintenance protect incumbent positions.
- Direct Sales:Fleet-scale negotiations between cooperative procurement consortia and manufacturers bypass traditional retail markups. Cambridgeshire estate managers coordinate synchronized replacement cycles through direct manufacturer contracts.
- Retail:Independent storefronts with limited service infrastructure capture compact utility and attachment sales in fragmented land tenure areas.
- Online Platforms:Digital channels penetrate spare parts and consumables where specification certainty eliminates pre-purchase inspection requirements.
Agri-dealers maintain the largest transaction volume; direct sales are gaining share fastest as cooperative procurement consolidates purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom agricultural machinery market operates with a structural trade deficit in high-horsepower powertrains, importing engine blocks from Germany and Italy while exporting specialized tillage implements to Commonwealth markets. DEFRA's subsidy restructuring is redistributing equipment demand across England's arable belt and the devolved administrations.
East Anglia
Intensive cereal operations drive replacement cycles for 300-600 hp tractors and combine harvesters with integrated guidance. The Environment Agency's water quality regulations mandate precision nutrient application systems. Norfolk and Suffolk contractors concentrate demand for subscription-based telemetry platforms that document input optimization for Sustainable Farming Incentive eligibility.
West Midlands
Dairy and beef operations present under-mechanized whitespace for compact automated feeding and manure management platforms. DEFRA's Environmental Land Management scheme conditions payments on documented soil health improvements. Staffordshire maintains specialized loader manufacturing heritage serving livestock handling applications.
Scotland
Highland field topology variability constrains GPS-dependent autonomous deployment despite strong arable mechanization in the Lowlands. The Scottish Government's agricultural support frameworks prioritize environmental conditionality matching Westminster's ELM transition. Aberdeenshire contractors concentrate demand for high-horsepower configurations suited to larger land holdings.
Yorkshire
Fragmented land tenure systems accelerate rental channel adoption through agricultural cooperatives. The Health and Safety Executive's machinery guarding standards protect incumbent dealer networks with certified service bay capacity. Lincolnshire arable contractors drive soil sensor miniaturization from laboratory-grade spectrometers to tractor-embedded probes.
Wales
Upland terrain variability limits precision agriculture penetration compared to England's flatter arable districts. Welsh Government rural development programs support equipment modernization in hill farming sectors. Mixed operations in the Welsh Marches retrofit existing tractors with strip-till attachments to maintain subsidy eligibility.
United Kingdom Agricultural Machinery Market Competitive Landscape
Concentration sits with integrated precision agriculture stacks and specialized domestic manufacturers serving distinct powertrain tiers. Deere & Company anchors premium configurations through telemetry-integrated platforms, while J.C. Bamford Excavators Ltd. maintains British manufacturing presence in materials handling segments. The competitive arena splits between global full-line suppliers, regional specialists in tillage implements, and compact utility focused Asian manufacturers. Dominant competitive moves include precision technology bundling at replacement cycle points and cooperative procurement consortia negotiating fleet-scale discounts bypassing traditional dealer networks.
Among the integrated full-line suppliers, Deere & Company, CNH Industrial N.V., and AGCO Corporation represent the archetype of precision agriculture platform providers. These entities exemplify competitive positioning where software-defined functionality and recurring telemetry subscriptions displace mechanical specifications as primary differentiation. J.C. Bamford Excavators Ltd. occupies a distinct position as a British-based specialist, while Kubota Corporation anchors compact utility segments where smaller farm holdings require maneuverable configurations. Claas KGaA mbH sits within the harvester-specialist tier, and Kuhn Group exemplifies the tillage implement focused archetype serving minimal-disturbance subsidy conditions.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| J.C. Bamford Excavators Ltd. |
| Kubota Corporation |
| Claas KGaA mbH |
| Kuhn Group |
| SDF Group S.p.A. |
| LEMKEN GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Scale economies in Stage V powertrain manufacturing concentrate production among German and Italian engine specialists, compressing margin capture for UK assemblers while elevating price floors for Tier-four compliant equipment across the replacement cycle.
Pricing Analysis
Arable contractors anchor three-tier pricing structure across premium, standard, and economy levels in the United Kingdom agricultural machinery market. Price differentiation separates telemetry-integrated precision platforms from mechanical-only configurations and legacy refit options. Pricing pressure stems from steel input volatility and cooperative procurement consortia negotiating fleet-scale discounts directly with manufacturers. Tenant farmers in Yorkshire's fragmented land tenure system exhibit highest price sensitivity, while East Anglia estate managers demonstrate lowest sensitivity due to documented input optimization requirements under DEFRA's Sustainable Farming Incentive.
Supply Chain Analysis
Germany and Italy anchor engine block production for high-horsepower tractors, while China and Japan supply compact utility powertrains and precision sensor components. UK manufacturers draw from imported sheet steel for chassis fabrication, German hydraulic systems for implement actuation, and Taiwanese semiconductor components for guidance controllers. Single-source vulnerability concentrates in continental engine sourcing, exposing assemblers to extended lead times during continental production disruptions. Distribution runs through established agri-dealer networks with certified service bay capacity, though direct manufacturer contracts with cooperative procurement consortia are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subsidy restructuring under DEFRA's Environmental Land Management scheme fragments demand across precision compliance tiers, creating specialized niches for equipment configurations that document soil health improvements.
For Market Incumbents: Secure telemetry subscription retention through backward integration into farm management software platforms, defending against emerging precision agriculture specialists. Invest in certified service bay capacity expansion across East Anglia to maintain dealer network control as cooperative procurement consolidates purchasing power. Prioritize Stage V powertrain inventory positioning ahead of replacement cycle peaks.
For New Entrants and Emerging Players: Lead with compact automated feeding platforms targeting under-mechanized dairy and beef operations in the West Midlands, where precision livestock management whitespace remains unaddressed by full-line suppliers. Penetrate through agricultural cooperative rental channels in Yorkshire's fragmented land tenure system, offering short-term leasing arrangements that lower capital barriers for tenant farmers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision agriculture platform providers with subscription-based telemetry and variable-rate application systems. Target acquisition archetypes include soil sensor miniaturization specialists and strip-till attachment manufacturers positioned for minimal-disturbance subsidy compliance. Watch for inflection signals in autonomous machinery certification timelines from the Health and Safety Executive.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Technology Bundling | Telemetry-integrated platforms capture recurring revenue from DEFRA compliance documentation requirements. |
| Backward Integration into Sensors | In-house soil probe production compresses capital requirements for mid-tier equipment configurations. |
| Cooperative Procurement Partnership | Direct manufacturer contracts with Cambridgeshire estate managers bypass traditional dealer markups. |
| Livestock Sector Expansion | Compact automated platforms address precision feeding whitespace in West Midlands dairy operations. |
| Rental Channel Development | Short-term leasing through Yorkshire cooperatives lowers capital barriers for fragmented land holdings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DEFRA subsidy documentation, Environment Agency water quality regulations, Health and Safety Executive machinery standards, and customs trade data for agricultural equipment imports. Primary interviews engaged equipment procurement managers at arable contracting firms, precision agriculture specialists at dealer networks, livestock farm operators in the West Midlands, and aftermarket service heads at Staffordshire manufacturing facilities. Bottom-up equipment shipment analysis triangulates against top-down agricultural GDP attribution and replacement cycle modeling.
Segmentation dimensions modeled include product type across horsepower bands and precision technology tiers, technology category across guidance systems and sensor platforms, end-use industry across crop production and livestock operations, and distribution channel across dealer networks and direct procurement structures. CAGRs derive from replacement cycle timing analysis, subsidy transition schedules, and emission compliance deadlines. Industry-specific forecast inputs incorporate DEFRA's Environmental Land Management scheme payment timelines and Stage V powertrain adoption curves.
Forecasts assume regulatory continuity in DEFRA subsidy frameworks and Environment Agency water quality standards; material policy shifts would require re-modeling. Specific risks include autonomous machinery certification delays from the Health and Safety Executive and continental supply disruptions affecting engine block availability. Recalibration cycles align with material shifts in subsidy eligibility conditions and precision technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Brazil Agricultural Machinery Market