
 South America Agricultural Sprayers Market | 2026-2036
South America Agricultural Sprayers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agricultural Sprayers Market Analytics
The dealer network for agricultural sprayers across Brazil and Argentina is narrowing as manufacturers consolidate aftermarket service partnerships. Jacto S.A. anchors its position through captive distribution in São Paulo state and deep technical service reach. Deere & Company leverages its precision agriculture platform to bundle sprayers with subscription-based agronomy tools. Kubota Corporation competes by extending its tractor dealership footprint into attached spraying equipment across southern Brazil.
Agricultural sprayers are pressurized application systems designed to distribute crop protection chemicals, fertilizers, or biological agents across field surfaces with calibrated droplet spectra and boom widths spanning 12 to 48 meters. These machines integrate pump systems, filtration arrays, and nozzle manifolds to achieve uniform coverage while minimizing off-target drift. Tractor-mounted sprayers occupy the volume core of the South American market due to compatibility with existing farm fleets and lower capital thresholds for mid-scale operators. Self-propelled sprayers capture premium positioning where boom width and tank capacity directly correlate with daily hectare throughput. Precision agriculture technology is displacing conventional spraying in Brazil's largest cooperatives as variable-rate nozzles and GPS-guided section control reduce chemical input costs per hectare.
Brazil's MAPA certification mandates and Argentina's SENASA phytosanitary protocols jointly shape equipment specifications for chemical containment and operator safety systems. ANVISA's residue limit frameworks indirectly pressure commercial growers toward precision application technologies that minimize over-spraying. Stakeholders must weigh retrofit investments against fleet replacement cycles as regulatory stringency diverges between Mercosur member states.
Market Dynamics
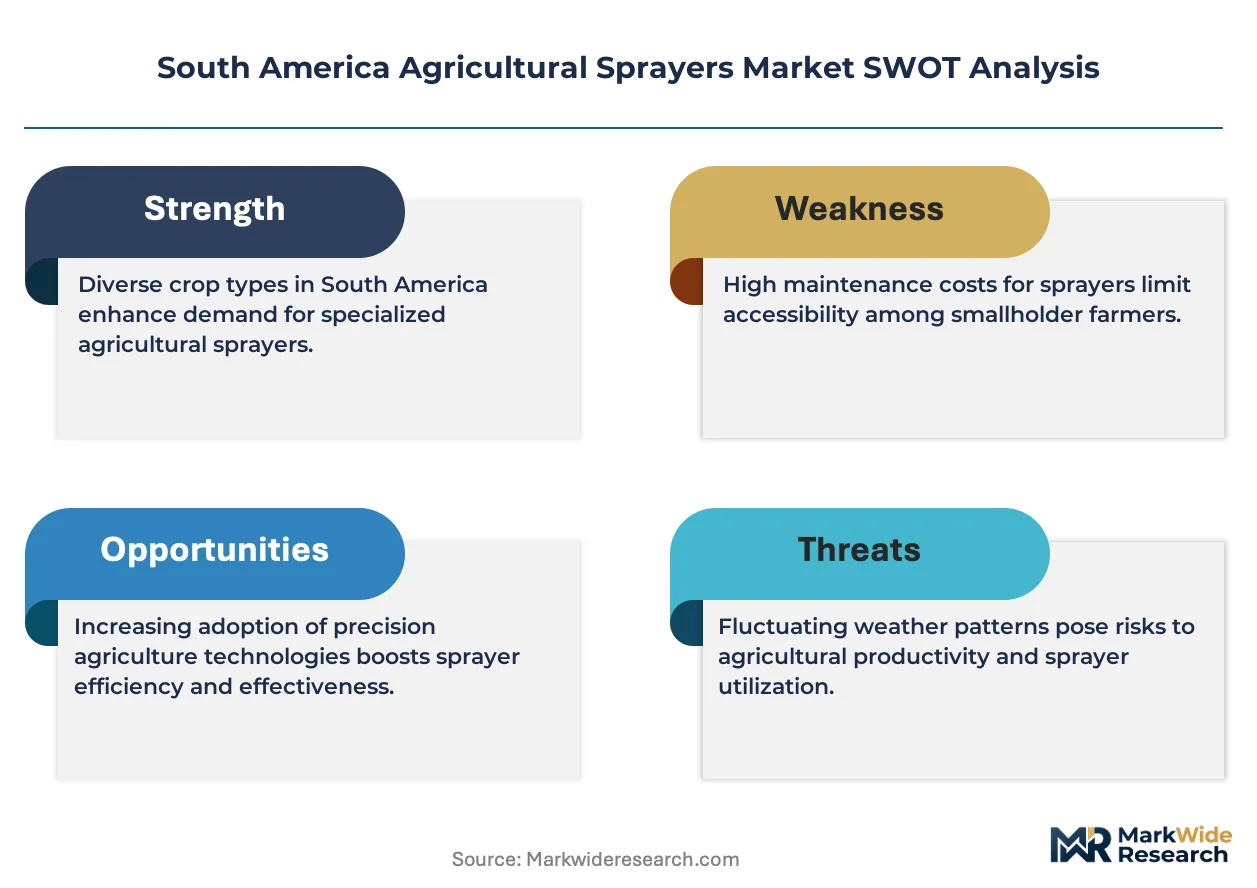
Mechanization mandates from Brazil's MAPA and Argentina's SENASA are compressing replacement cycles for legacy spraying fleets, forcing cooperatives to recalibrate capital deployment toward precision-enabled equipment before regulatory deadlines.
Growth Catalysts
- Herbicide-resistant weed pressure:Glyphosate-resistant Palmer amaranth infestations across Mato Grosso and Buenos Aires provinces are compelling soybean growers to upgrade from conventional boom sprayers to pulse-width modulation systems.
- MAPA certification mandates:Brazil's tightened operator certification requirements are disqualifying manual and backpack sprayers from commercial operations, redirecting procurement toward tractor-mounted and self-propelled platforms with enclosed cabs.
- Variable-rate nozzle adoption:GPS-guided section control with individual nozzle shutoff is reducing chemical overlap by 8-12% in large-scale operations, generating measurable input cost savings that justify equipment premiums.
Market Restraints
- Steel and aluminum input volatility:Boom fabrication costs fluctuate with regional metal pricing, compressing manufacturer margins and forcing price pass-through to capital-constrained mid-scale operators.
- Import dependency for pump assemblies:High-pressure diaphragm pumps and ceramic nozzles concentrate sourcing from Italian and German suppliers, exposing assemblers to currency risk and extended lead times.
- ANVISA residue enforcement gaps:Inconsistent maximum residue limit enforcement across Brazilian states creates demand uncertainty, delaying fleet upgrade decisions until regulatory clarity stabilizes.
Strategic Opportunities
- Paraguay's mechanization gap:Soybean expansion in Alto Paraná and Itapúa departments runs ahead of spraying equipment penetration, opening dealer network expansion for precision agriculture platforms.
- Biological agent application systems:Fungal inoculant and biopesticide spraying requires lower-pressure, larger-droplet nozzles that legacy equipment cannot accommodate, creating retrofit and replacement demand.
- Cooperative fleet pooling models:Shared-ownership structures in Rio Grande do Sul are reducing individual capital barriers while concentrating demand for high-capacity self-propelled units with telemetry integration.
Industry Challenges
- Precision agriculture technician scarcity:GPS calibration, nozzle flow mapping, and telemetry diagnostics require skills absent from traditional mechanical repair networks, forcing manufacturers to build captive training infrastructure.
- MAPA certification timeline compression:Operator retraining and equipment compliance verification must complete before planting windows, creating seasonal bottlenecks at accredited testing facilities.
- Legacy fleet interoperability:Retrofitting ISOBUS-compatible controllers onto 2015-2018 tractor models requires proprietary adapter modules that fragment precision agriculture platform performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agricultural Sprayers Market |
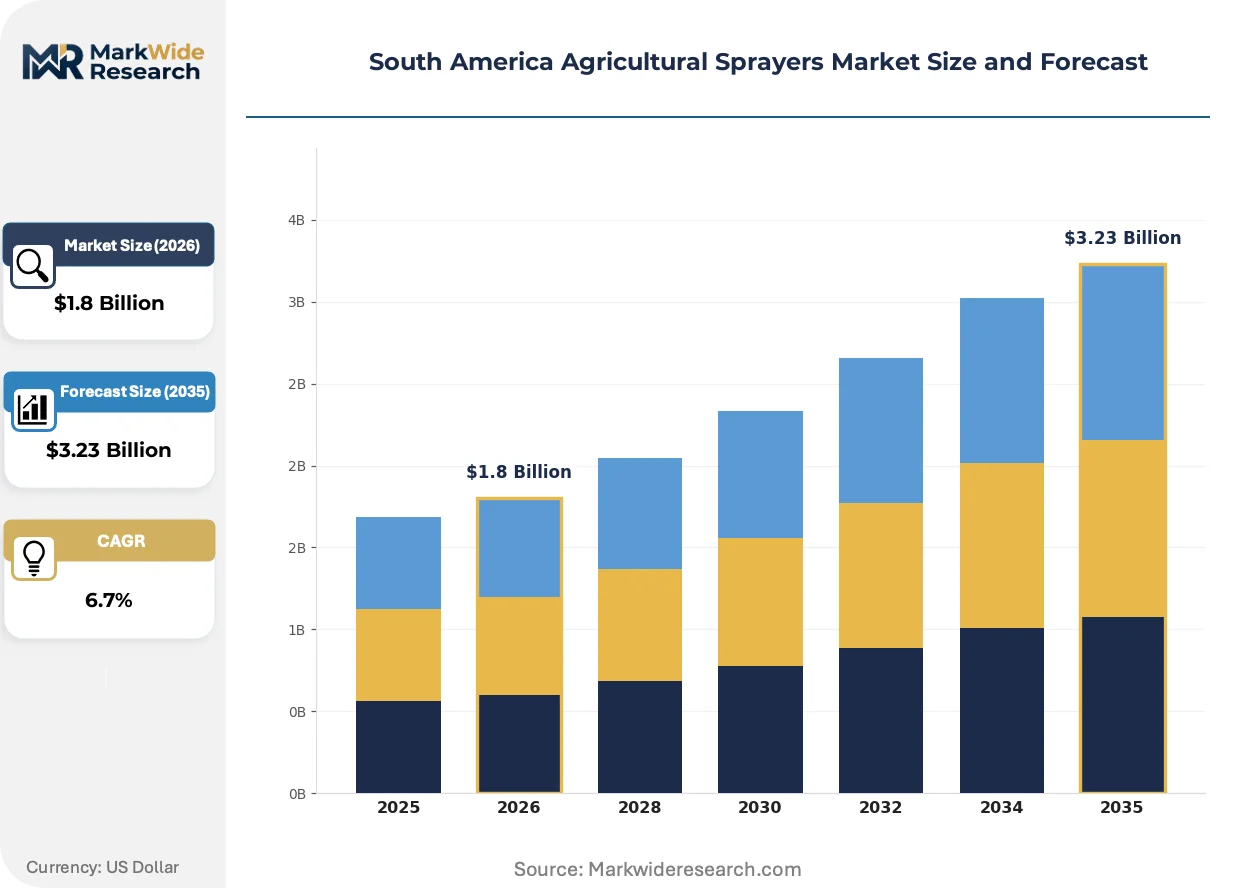
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Sprayers, Tractor-Mounted Sprayers, Self-Propelled Sprayers, Aerial Sprayers End User: Farmers, Agricultural Cooperatives, Commercial Growers, Research Institutions Technology: Conventional Spraying, Precision Agriculture, Automated Spraying, Smart Spraying Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Jacto S.A., Guarany Indústria Ltda., Deere & Company, EXEL Industries SA, Kubota Corporation, AGCO Corporation, Stara S/A, Bucher Industries AG (KUHN Group), CNH Industrial N.V., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agricultural Sprayers Market Evolving Landscape
Electrification of hydraulic functions and edge-computing for real-time drift detection are reconfiguring equipment architecture, while regulatory data-logging mandates are embedding connectivity as a standard rather than premium feature.
Electrostatic charging systems for droplet deposition are collapsing the efficiency gap between aerial and ground application in soybean and corn canopies. Large cooperatives in Mato Grosso are piloting these systems during the 2024-2025 growing season. The technology is collapsing aerial contractor dependence for mid-season fungicide applications by matching coverage uniformity at one-third the per-hectare cost.
SENASA's phytosanitary traceability protocols now mandate automated application records with GPS coordinates and weather data for all restricted-use chemicals in Argentina's core grain belt. Equipment manufacturers must pre-install data-logging hardware to achieve type approval. Self-propelled sprayer sales in Buenos Aires and Córdoba provinces are accelerating as operators replace non-compliant tractor-mounted units ahead of enforcement phase-in.
Cooperative procurement committees are consolidating annual equipment tenders into multi-year framework agreements with performance guarantees on chemical savings. Dealer networks in southern Brazil are responding with subscription-based maintenance and nozzle replacement programs. This pattern is most pronounced in Rio Grande do Sul, where three purchasing cooperatives now represent over 40% of regional self-propelled sprayer volume.
South America Agricultural Sprayers Market Segmentation
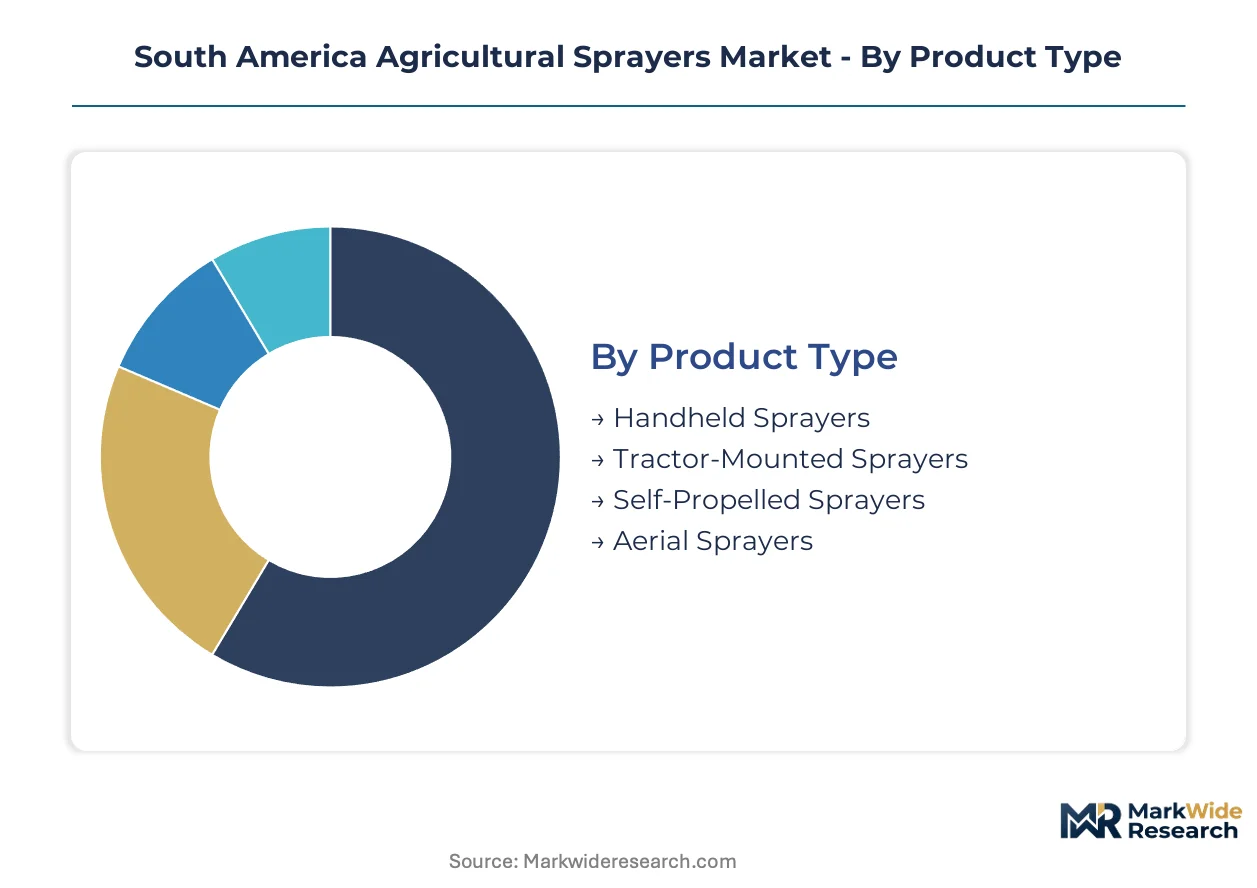
Sprayer segmentation in South America determines aftermarket service intensity, parts inventory requirements, and dealer technical training investments. Equipment complexity varies dramatically across product tiers, shaping margin structures and customer retention strategies for manufacturers.
Product Type:
After-sales-service intensity escalates with boom width, tank capacity, and precision agriculture integration, concentrating technical support demands on self-propelled platforms while tractor-mounted units rely on existing dealer mechanical networks.
- Self-Propelled Sprayers:These machines integrate 3,000-6,000 liter tanks with 24-48 meter booms and ISOBUS-compatible control systems. Mato Grosso soybean operations in Brazil's Cerrado region concentrate procurement here, driven by daily hectare throughput requirements and MAPA certification mandates for enclosed-cab chemical handling.
- Tractor-Mounted Sprayers:Units attach via three-point hitch to existing farm fleets, offering 1,000-2,500 liter capacities with 12-24 meter boom options. Mid-scale operators across Rio Grande do Sul and Santa Catarina states favor these for capital efficiency, though precision agriculture retrofit costs are compressing price advantages.
- Handheld Sprayers:Backpack and manual units serve subsistence plots and specialty crop applications with minimal technical service requirements.
- Aerial Sprayers:Fixed-wing and rotorcraft application systems address flood-prone regions and expansive soybean monocultures where ground equipment access is limited.
By volume, tractor-mounted sprayers lead. By growth pace, self-propelled platforms are expanding most quickly.
End User:
Customer scale determines procurement centralization, with large cooperatives consolidating tender processes while individual farmers prioritize equipment financing flexibility and trade-in programs.
- Agricultural Cooperatives:These entities aggregate demand from hundreds of member farms, deploying fleet-standardized equipment with telemetry integration for chemical traceability. Three purchasing cooperatives in Rio Grande do Sul now represent over 40% of regional self-propelled volume, driven by SENASA phytosanitary protocol compliance requirements in Argentina's grain belt.
- Commercial Growers:Corporate farming operations in Mato Grosso and Goiás states operate dedicated spraying fleets with in-house maintenance capabilities, prioritizing boom width and tank capacity metrics.
- Farmers:Individual owner-operators across Paraguay's Alto Paraná department and southern Brazil rely on dealer financing and seasonal service contracts.
- Research Institutions:Agricultural universities and extension services operate small-scale plot sprayers for field trial applications with specialized nozzle configurations.
By volume, farmers dominate procurement. By technology adoption speed, agricultural cooperatives are gaining share fastest.
Technology:
Technology tiering separates equipment replacement cycles, with precision-enabled platforms commanding compressed upgrade timelines against conventional systems with 10-15 year service lives.
- Precision Agriculture:GPS-guided section control, variable-rate nozzle manifolds, and individual shutoff systems reduce chemical overlap. Large cooperatives in Brazil's Mato Grosso state concentrate adoption here, compelled by measurable input cost savings and ANVISA residue limit pressures.
- Smart Spraying:Real-time canopy sensing, edge-computing drift detection, and electrostatic charging systems match aerial application uniformity. Pilot deployments during recent growing seasons in Argentina's Buenos Aires province are validating per-hectare cost advantages.
- Automated Spraying:Autonomous trajectory planning with telemetry data logging addresses labor scarcity and MAPA certification record-keeping mandates.
- Conventional Spraying:Fixed-rate, manually calibrated systems without GPS integration face regulatory disqualification from commercial operations under tightened MAPA operator certification requirements.
By installed base, conventional spraying leads. By replacement velocity, precision agriculture platforms show the steepest expansion trajectory.
Distribution Channel:
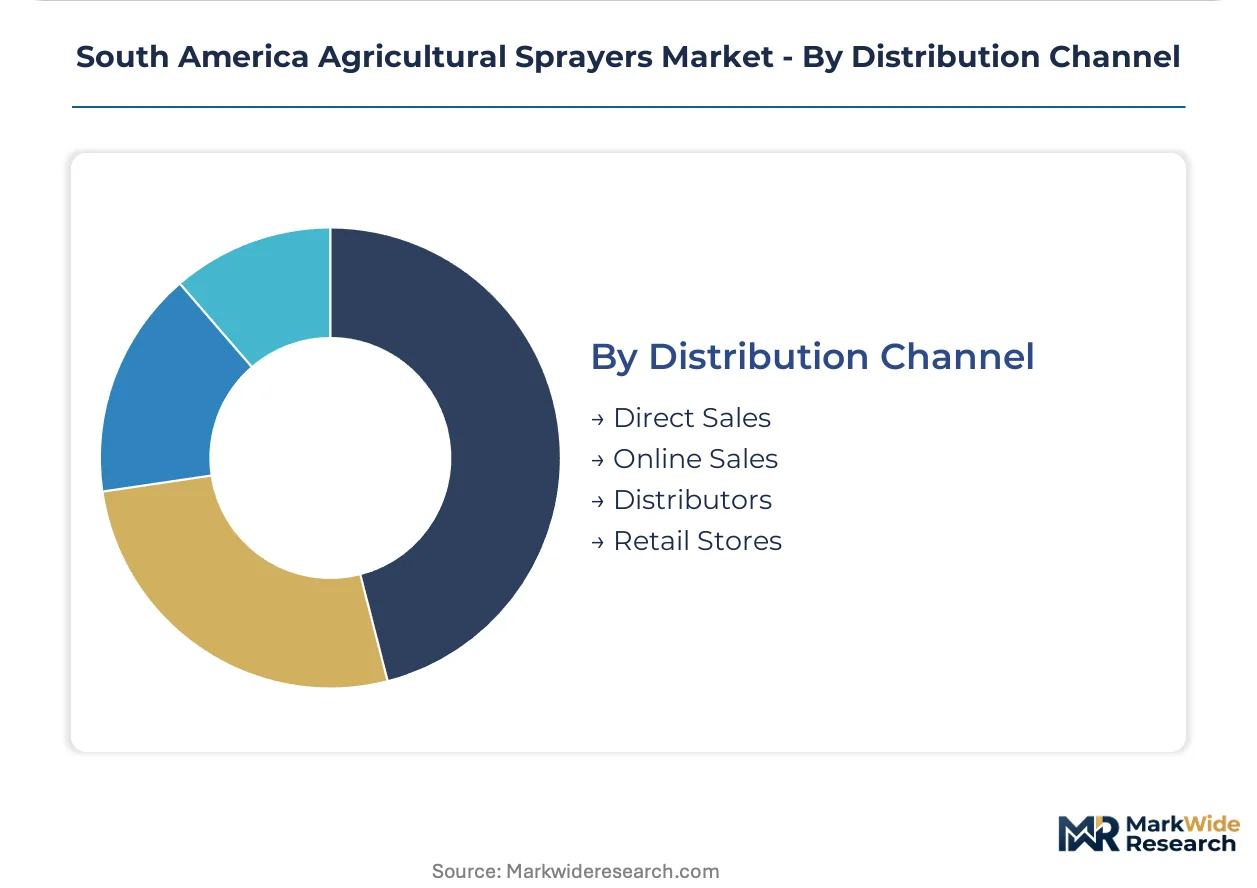
Channel structure reflects equipment complexity, with direct manufacturer relationships dominating self-propelled sales while retail networks handle consumables and replacement parts.
- Distributors:Authorized dealer networks provide technical service reach, parts inventory, and operator training infrastructure. Jacto S.A.'s captive distribution in São Paulo state exemplifies this model, anchoring market position through aftermarket service density.
- Direct Sales:Manufacturer-led procurement addresses large cooperative tenders and fleet replacement programs with customized financing structures.
- Retail Stores:Agricultural supply cooperatives and equipment dealers stock tractor-mounted sprayers and replacement nozzles for immediate availability.
- Online Sales:E-commerce platforms concentrate consumables, precision agriculture subscriptions, and smaller handheld equipment with limited technical support requirements.
By transaction volume, distributors lead. By digital penetration growth, online sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MAPA certification mandates from Brazil's Ministry of Agriculture anchor regional demand trajectories, compressing equipment replacement cycles across Mercosur member states while Paraguay's mechanization gap widens the addressable market frontier.
Brazil
Soybean expansion in Mato Grosso's Cerrado biome drives self-propelled sprayer procurement, with daily hectare throughput requirements dictating 36-48 meter boom specifications. MAPA's tightened operator certification deadlines disqualify manual application systems from commercial operations. São Paulo state concentrates captive distribution networks where technical service density determines manufacturer market share.
Argentina
SENASA phytosanitary traceability protocols mandate GPS-logged application records for restricted-use chemicals across Buenos Aires and Córdoba provinces. Non-compliant tractor-mounted units face accelerated replacement as enforcement phase-in approaches. The Pampas grain belt exhibits fastest adoption of electrostatic charging systems for mid-season fungicide applications.
Paraguay
Soybean cultivation in Alto Paraná and Itapúa departments outpaces spraying equipment penetration, creating dealer network expansion opportunities for precision agriculture platforms. Limited domestic manufacturing capacity concentrates import dependency on Brazilian and Argentine supply channels. Capital constraints among individual owner-operators favor tractor-mounted configurations over self-propelled platforms.
Uruguay
Consolidated large-scale farming operations in the country's western grain belt prioritize telemetry-integrated equipment for chemical traceability compliance. Mercosur regulatory harmonization pressures fleet standardization toward ISOBUS-compatible control systems. Montevideo-based import distributors coordinate regional spare parts logistics for Brazilian-manufactured equipment.
Bolivia
Santa Cruz department's soybean corridor exhibits nascent mechanization with backpack sprayers still prevalent among mid-scale operators. ANVISA-aligned residue limit frameworks create indirect pressure toward precision application adoption. Informal cross-border equipment flows from Brazil complicate formal dealer network development in the Chaco region.
South America Agricultural Sprayers Market Competitive Landscape
Full-line agricultural machinery conglomerates and specialized spraying equipment fabricators split the market, with captive distribution networks determining regional penetration depth. Market structure concentrates around three strategic archetypes: diversified equipment manufacturers bundling sprayers with precision agriculture subscriptions, dedicated spraying specialists leveraging technical service density, and tractor OEMs extending dealership footprints into attached application equipment. Competitive moves center on multi-year cooperative framework agreements with chemical savings guarantees and captive training infrastructure for precision agriculture technicians.
Within the diversified machinery tier, Deere & Company and Kubota Corporation exemplify platform-integration strategies, while Jacto S.A. anchors the specialist archetype through São Paulo-state distribution density. These three companies occupy positions that reflect contrasting approaches to aftermarket service reach and precision technology bundling.
| Leading Market Players |
|---|
| Jacto S.A. |
| Guarany Indústria Ltda. |
| Deere & Company |
| EXEL Industries SA |
| Kubota Corporation |
| AGCO Corporation |
| Stara S/A |
| Bucher Industries AG (KUHN Group) |
| CNH Industrial N.V. |
| Others |
Value Network & Pricing Analysis
The Santos-Paranaguá maritime corridor's freight cost volatility shapes equipment landed pricing across Mercosur markets, concentrating margin pressure on Brazilian manufacturers while enabling Argentine assemblers to capture price premiums through proximity to soybean belt demand. Steel and aluminum input swings transmit directly to boom fabrication costs, forcing distributors to differentiate tractor-mounted configurations through financing terms rather than sticker price.
Pricing Analysis
Configured-to-order pricing for self-propelled platforms commands 15-25% premiums over standard tractor-mounted specifications, with ISOBUS compatibility and enclosed-cab certification driving the spread. Three-tier pricing structure across premium precision-agriculture, standard GPS-enabled, and economy conventional tiers segments buyer archetypes, with mid-scale operators in Rio Grande do Sul exhibiting acute price sensitivity to upfront capital outlay. Cost compression in economy tiers is intensifying because ceramic nozzle and diaphragm pump import dependencies expose assemblers to currency risk pass-through. Large cooperatives in Mato Grosso show least price sensitivity, prioritizing daily hectare throughput and chemical savings guarantees over acquisition cost.
Supply Chain Analysis
Extended payment terms from Italian and German pump suppliers have become critical working capital facilities for Brazilian sprayer assemblers facing seasonal demand concentration. Manufacturing concentrates in Brazil's São Paulo and Rio Grande do Sul states, with component sourcing drawing from Germany, Italy, and China for precision agriculture electronics. High-pressure diaphragm pumps, ceramic nozzles, and ISOBUS controller modules constitute critical input dependencies. Single-source vulnerability for GPS guidance systems creates supply chain risk given limited qualified alternative suppliers. Distribution runs through captive dealer networks for self-propelled platforms, while retail agricultural supply cooperatives handle tractor-mounted volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision agriculture subscription services and telemetry-enabled maintenance contracts are expanding faster than hardware sales, repositioning equipment vendors as recurring-revenue platforms. This service-attach dynamic favors manufacturers with captive technical training infrastructure and data-logging compliance capabilities.
For Market Incumbents: Harden aftermarket service density in Mato Grosso and São Paulo states against precision-agriculture specialist entrants by embedding telemetry diagnostics into standard warranty terms. Deepen backward integration into nozzle manifold fabrication to offset ceramic component import volatility. Consolidate multi-year cooperative framework agreements with chemical savings performance guarantees before MAPA certification deadlines compress replacement windows. For New Entrants and Emerging Players: Paraguay's Alto Paraná soybean corridor offers the most penetrable geographic white space, with equipment penetration lagging cultivation expansion by 30-40% against Brazilian benchmarks. Target biological agent application systems as the fastest-growing product category underserved by legacy boom configurations. Establish dealer partnerships with Brazilian distributors already holding Mercosur customs logistics capabilities rather than building greenfield networks. For Investors and Strategic Acquirers: MAPA's phased certification enforcement reshapes the acquisition landscape toward precision-agriculture-enabled manufacturers with compliant enclosed-cab platforms. Five-to-ten year viability centers on telemetry integration and data-logging hardware as regulatory compliance infrastructure. Target acquisition archetype: mid-cap specialists with ISOBUS-compatible controller development capabilities and established cooperative customer relationships. Watch SENASA traceability protocol enforcement timing in Argentina's Buenos Aires province as the signal for regional replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Bundles GPS-guided section control with subscription-based agronomy tools for cooperative retention. |
| Captive Technical Training Infrastructure | Addresses technician scarcity for nozzle flow mapping and telemetry diagnostics calibration. |
| Biological Agent Application System Development | Captures fungal inoculant spraying demand that legacy pressure systems cannot accommodate. |
| Multi-Year Cooperative Framework Agreements | Consolidates fleet procurement through chemical savings guarantees and bundled maintenance contracts. |
| Dealer Network Expansion into Paraguay | Exploits mechanization gap in Alto Paraná soybean cultivation ahead of competitor presence. |
Research Methodology
Operator-level perspectives from precision agriculture technicians, cooperative procurement committees, MAPA-certified equipment dealers, and aftermarket service managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through customs trade records, ANVISA regulatory filings, SENASA phytosanitary protocols, and agricultural machinery registration databases. Bottom-up equipment volume estimates triangulated against top-down market sizing derived from soybean cultivation area projections and mechanization penetration benchmarks.
Scenario-bracketing around regulatory enforcement timing, commodity price volatility, and currency fluctuation bounds framed the analytical approach across the projection horizon. Segmentation modeling incorporated product type, end-user scale, technology tier, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs derived from equipment replacement cycle compression rates, precision agriculture adoption curves, and cooperative procurement consolidation patterns. Industry-specific inputs included MAPA certification deadline phasing and SENASA traceability protocol implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or pricing warfare by diversified machinery conglomerates would shift outcomes beyond modeled ranges. Forecasts assume continued Mercosur regulatory harmonization toward ISOBUS compatibility standards and stable agricultural commodity price environments. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
North America Haying and Forage Machinery Market