
 India Agricultural Tractor Market | 2026-2036
India Agricultural Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
India Agricultural Tractor Market Foresight
HP-tier upgrades toward 51-100 HP machines is reorganizing competitive dynamics across India's tractor landscape. Mahindra & Mahindra Ltd. leverages its Swaraj subsidiary to dominate the smallholder belt of central India. TAFE Motors and Tractors Limited anchors its position through captive engine manufacturing and deep distribution in the southern states. Escorts Kubota Limited differentiates via precision agriculture integration and hydraulic system specialization.
An agricultural tractor is a self-propelled power unit with diesel-driven internal combustion engines typically ranging from 15 HP to above 100 HP, designed to pull or power implements for soil preparation, planting, cultivation, and harvesting. These machines transmit engine power through mechanical or hydrostatic drivetrains to rear and optional front axles, enabling draft and rotary operations across varied soil conditions. Utility tractors and 30-50 HP machines command the volume core, serving smallholder mixed-cropping systems where versatility outweighs specialization. The 51-100 HP segment captures expanding margin pools as commercial farmers in Punjab and Haryana upgrade for heavier tillage implements and trailer haulage. Compact tractors remain nascent in India but show structural promise in Himachal Pradesh and Uttarakhand hill agriculture where maneuverability constrains standard-frame adoption.
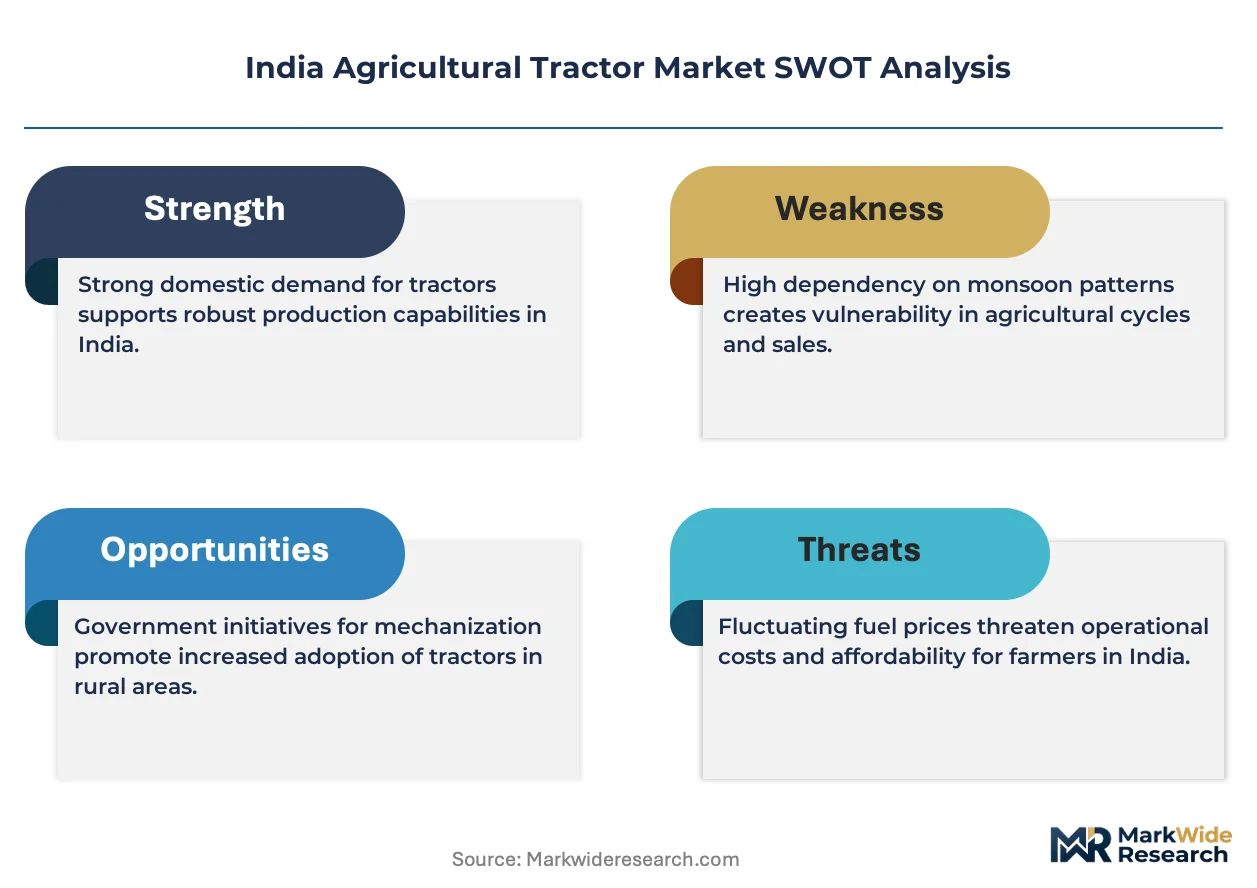
BIS emission standards, CEA agricultural electrification guidelines, and state-level farm mechanization subsidies shape product development and purchase incentives across India. The central regulator mandates progressive particulate and NOx limits that push manufacturers toward common-rail fuel injection and after-treatment systems. State agricultural departments administer differential subsidy rates that tilt demand toward domestic assembly and specified horsepower thresholds. Stakeholders must monitor how subsidy disbursement delays and credit availability through agriculture cooperatives interact to determine effective replacement velocity in the eastern states.
Market Dynamics
HP-tier migration toward 51-100 HP machines is compressing replacement cycles in the Indo-Gangetic plains while forcing manufacturers to rebalance component sourcing for heavier drivetrains.
Growth Catalysts
- FAME Scheme Adaptations:CEA agricultural electrification guidelines are channeling subsidy flows toward powertrain upgrades, accelerating farmer adoption of emission-compliant engines in Punjab and Haryana.
- Orchard Mechanization:Horticulture contractors in Maharashtra and Karnataka are expanding tractor fleets for precision canopy management and floriculture operations, creating pull for specialized PTO configurations.
- BIS Emission Norms:Progressive particulate and NOx limits are mandating common-rail fuel injection and after-treatment systems, locking in technology refresh timelines across the installed base.
Market Restraints
- Steel Price Volatility:Input cost swings for chassis-grade hot-rolled coil are compressing assembler margins on sub-40 HP price-sensitive units.
- Credit Disbursement Delays:Agriculture cooperative financing bottlenecks in Bihar and eastern Uttar Pradesh are elongating effective replacement cycles below theoretical equipment life.
- Used Equipment Substitution:Refurbished 15-year-old tractors from Punjab are flooding secondary markets in Madhya Pradesh and Rajasthan, cannibalizing new-unit demand.
Strategic Opportunities
- Hill Agriculture Compact Tractors:Maneuverability constraints in Himachal Pradesh and Uttarakhand are opening white space for sub-30 HP machines with narrow track widths and hillside stability packages.
- State-Level Subsury Arbitrage:Differential farm mechanization subsidy rates across state agricultural departments are creating channel opportunities for assemblers with flexible domestic sourcing footprints.
- Precision Agriculture Convergence:ISOBUS implement control and hydraulic load-sensing systems are converging to enable variable-rate application services in commercial farming belts.
Industry Challenges
- Emissions Calibration Talent Scarcity:Common-rail system tuning and after-treatment integration require skill sets concentrated with Tier-1 automotive suppliers, not legacy tractor engineering benches.
- Homologation Timeline Compression:BIS certification cycles for new engine families are running 18-24 months, misaligning with annual subsidy window openings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Agricultural Tractor Market |
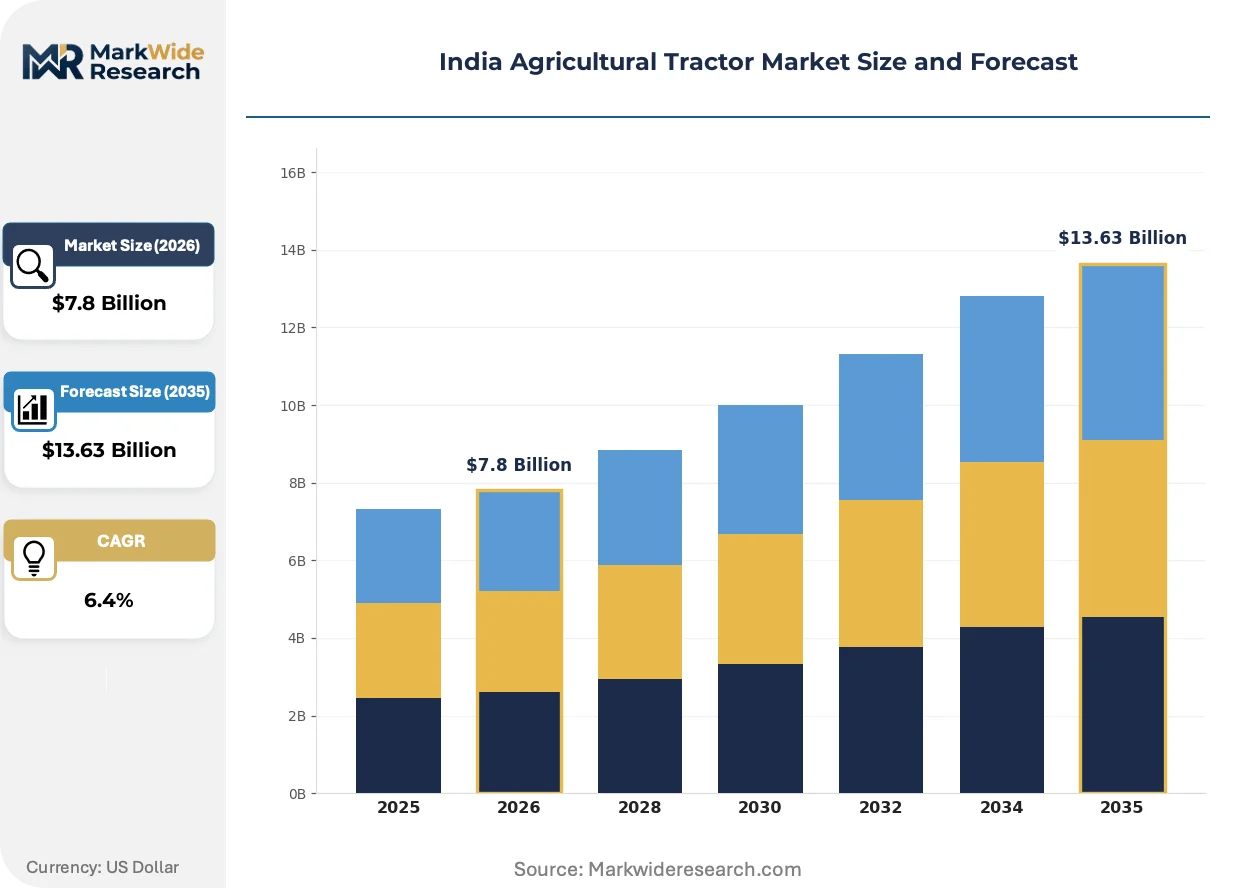
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Specialty Tractors Engine Power: Less than 30 HP, 30-50 HP, 51-100 HP, Above 100 HP Application: Paddy Cultivation, Vegetable Farming, Orchard Management, Floriculture End User: Commercial Farmers, Smallholders, Agriculture Cooperatives, Government Programs |
| Companies Covered | Mahindra & Mahindra Ltd., TAFE Motors and Tractors Limited, Escorts Kubota Limited, International Tractors Ltd., Sonalika, Deere & Company, CNH Industrial N.V., Swaraj Tractors, VST Tillers Tractors Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Agricultural Tractor Market Shifts & Advancements
Powertrain electrification pathways and precision agriculture integration are bifurcating product roadmaps, with commercial operators demanding telematics-enabled fleet management while smallholders prioritize mechanical simplicity.
Hydrostatic transmission architectures are displacing mechanical shuttle-shift systems in the 51-100 HP segment. Large contractors in Haryana are specifying hydrostatic units for loader work and repetitive field operations. This shift is displacing traditional synchronized gearbox suppliers from premium tier sourcing lists and compressing service network requirements toward fluid power specialists.
BIS Stage-V-equivalent emission norms are tightening particulate matter thresholds for agricultural diesel engines above 37 kW. Manufacturers are integrating diesel particulate filters and selective catalytic reduction hardware previously confined to commercial vehicle applications. The 51-100 HP segment bears the steepest compliance cost burden, accelerating consolidation among engine suppliers capable of after-treatment system integration.
Service unbundling is fragmenting traditional dealer revenue models. Fleet operators in Punjab are sourcing routine maintenance through independent hydraulic shops and engine rebuild specialists rather than authorized channels. This pattern is most visible in high-hour rice-wheat systems where downtime costs exceed warranty preservation value, forcing OEMs to defend parts attachment through proprietary telematics lock-in.
India Agricultural Tractor Market Segmentation
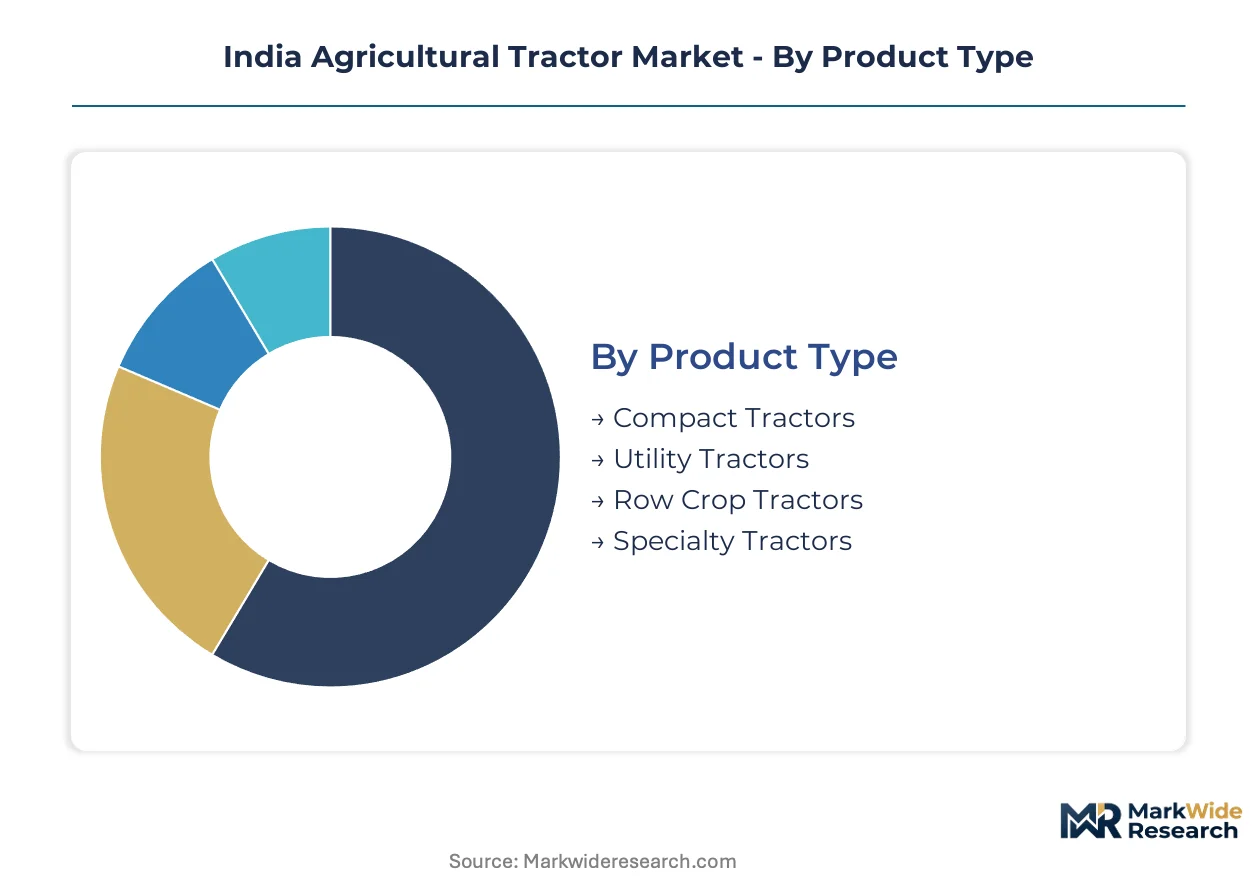
Segmentation in India's tractor market reveals divergent channel economics. Smallholders purchase through cooperative financing, while commercial operators negotiate direct with authorized dealers for precision-equipped units.
Product Type:
Channel mix varies sharply by frame size: utility tractors move through dense rural dealer networks, while specialty units require demonstration-led direct sales.
- Utility Tractors:These machines dominate volume flows through agricultural cooperative procurement channels. Punjab and Haryana commercial farmers specify utility-class frames for heavy tillage and trailer haulage, with hydrostatic transmission options gaining preference in Haryana's large contracting operations.
- Compact Tractors:Narrow-track sub-30 HP machines serve hill agriculture in Himachal Pradesh and Uttarakhand where standard-frame tractors cannot maneuver. Channel economics favor specialized horticulture equipment dealers over general agricultural distributors.
- Row Crop Tractors:High-clearance designs with adjustable wheel spacing serve sugarcane and cotton belts in Maharashtra and Karnataka.
- Specialty Tractors:Vineyard and orchard configurations with protected crop shields concentrate in Maharashtra's grape-growing Nashik belt and Karnataka's coffee districts.
By volume, Utility Tractors leads. By growth pace, Compact Tractors is ahead.
Engine Power:
Power tier selection tracks landholding size and cropping intensity across India's agricultural belts.
- 30-50 HP:This segment anchors replacement demand in mixed-cropping smallholder systems. Bihar and eastern Uttar Pradesh cooperatives concentrate procurement here, though credit disbursement bottlenecks elongate purchase cycles.
- 51-100 HP:Common-rail fuel injection and after-treatment systems push price points upward. Punjab and Haryana rice-wheat commercial operators upgrade into this band for heavier implements, with BIS emission compliance locking in technology refresh timelines.
- Less than 30 HP:Hill states and terraced operations in Uttarakhand drive demand for maneuverable low-power units.
- Above 100 HP:Large-scale sugarcane contractors in western Maharashtra specify these for deep tillage and heavy trailer operations.
By installed base, 30-50 HP leads. By margin expansion, 51-100 HP is climbing fastest.
Application:
Application-specific configurations determine PTO specification and hydraulic system design.
- Paddy Cultivation:Low-ground-pressure tires and sealed electrical systems dominate specification sheets. Eastern Uttar Pradesh and Bihar cooperatives prioritize wet-field reliability over power density.
- Orchard Management:Narrow-track frames with mid-mount PTO configurations serve Maharashtra's mango and pomegranate belts. Karnataka coffee estates specify hillside stability packages and creep-speed transmissions.
- Vegetable Farming:Frequent implement changes in peri-urban supply zones around Delhi and Bengaluru drive quick-hitch hydraulic demand.
- Floriculture:Precision canopy management in Karnataka's Bengaluru rural district and Maharashtra's Pune corridor requires specialized PTO speeds for spraying equipment.
By unit volume, Paddy Cultivation leads. By specification premium, Orchard Management is expanding most quickly.
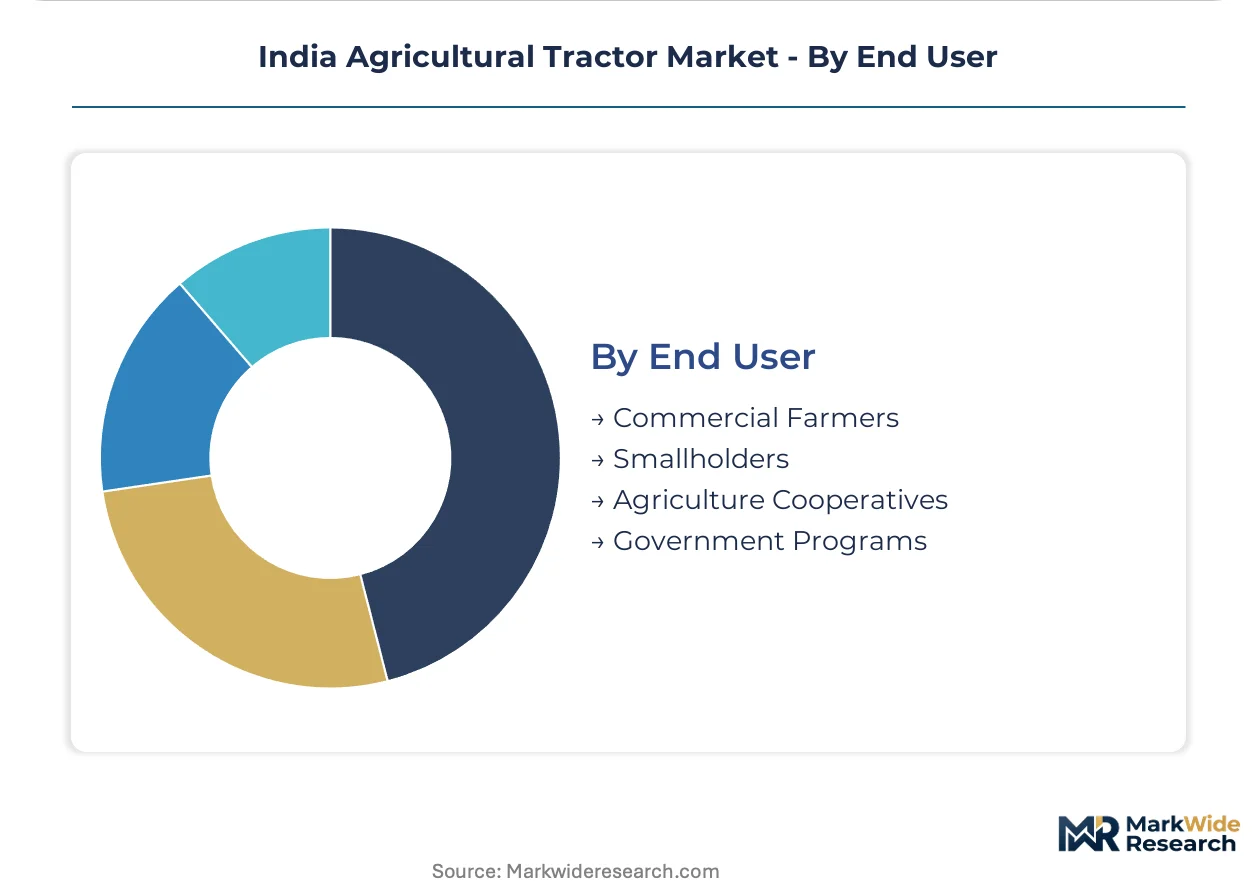
End User:
Customer type determines financing structure and service relationship expectations.
- Commercial Farmers:Punjab and Haryana large landholders purchase through direct dealer negotiation with telematics-enabled fleet management requirements. These operators unbundle service to independent hydraulic specialists, bypassing authorized channels.
- Smallholders:Central India's Madhya Pradesh and Chhattisgarh belt relies on cooperative financing and Swaraj-brand mechanical simplicity. Replacement cycles stretch beyond theoretical equipment life due to credit constraints.
- Agriculture Cooperatives:Bulk procurement in Bihar and eastern Uttar Pradesh channels volume through state agricultural department subsidy windows, with disbursement timing dictating effective demand.
- Government Programs:State-level farm mechanization subsidies in Rajasthan and Madhya Pradesh specify domestic assembly requirements and horsepower thresholds.
By transaction volume, Smallholders leads. By technology specification, Commercial Farmers is pulling ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's agricultural tractor trade flows reflect a domestic manufacturing surplus with limited export penetration. Component sourcing concentrates in the Indo-Gangetic industrial corridor while finished equipment demand distributes across state-level subsidy windows.
Punjab
Rice-wheat commercial operators drive replacement cycles for 51-100 HP machines with heavy tillage specifications. State agricultural department subsidies under the farm mechanization program channel credit through cooperative networks. Ludhiana's industrial cluster houses transmission and hydraulic system suppliers serving premium-tier assemblers.
Haryana
Large contracting operations specify hydrostatic transmission units for loader-intensive fieldwork. BIS emission compliance deadlines compress technology refresh timelines for the installed base. Hisar and Faridabad manufacturing zones concentrate engine component fabrication for northern India supply.
Maharashtra
Horticulture contractors in Nashik and Pune corridors expand fleets for orchard canopy management and floriculture precision spraying. State-level horticulture mechanization subsidies favor specialized PTO configurations. Aurangabad's engineering belt supplies axle and drivetrain assemblies for western India distribution.
Karnataka
Coffee estates in Chikmagalur and Hassan districts demand hillside stability packages with creep-speed transmissions. Bengaluru rural's peri-urban floriculture zones pull compact tractor specifications for greenhouse operations. Mandya's agricultural equipment hub assembles sub-assemblies for southern state markets.
Uttar Pradesh
Mixed-cropping smallholders in eastern districts rely on cooperative financing for 30-50 HP utility purchases. Credit disbursement bottlenecks through Bihar-border cooperatives elongate effective replacement cycles. Kanpur's legacy machinery belt fabricates implements and attachment systems for the Gangetic plains.
India Agricultural Tractor Market Competitive Landscape
Listed leaders compete with private specialists across distribution depth and subsidy channel access. Market structure concentrates around three domestic conglomerates with captive engine manufacturing, while international entrants compete through joint venture structures. Strategic archetypes separate into full-range assemblers, powertrain-integrated specialists, and precision-agriculture integrators. Dominant competitive moves include state-level subsidy arbitrage through flexible domestic sourcing footprints and hydraulic system specialization for commercial contracting segments.
Within the full-range assembler tier, Mahindra & Mahindra Ltd. and TAFE Motors and Tractors Limited occupy positions defined by distribution density and captive manufacturing integration. Escorts Kubota Limited exemplifies the precision-agriculture convergence archetype. These three anchors represent distinct strategic vectors: cooperative-channel mechanical simplicity, southern-state powertrain autonomy, and telematics-enabled fleet management for large commercial operators.
| Leading Market Players |
|---|
| Mahindra & Mahindra Ltd. |
| TAFE Motors and Tractors Limited |
| Escorts Kubota Limited |
| International Tractors Ltd. |
| Sonalika |
| Deere & Company |
| CNH Industrial N.V. |
| Swaraj Tractors |
| VST Tillers Tractors Ltd. |
| Others |
Supply & Pricing Matrix
State-level subsidy disbursement contracts lock in seasonal procurement windows for cooperative buyers, binding tractor assemblers to price visibility across BIS emission compliance cycles and steel input volatility in the Indo-Gangetic manufacturing corridor.
Pricing Analysis
Industrial OEM buyers anchor tiered pricing stratification across premium hydrostatic, standard mechanical shuttle, and economy fixed-gear configurations. Price differentiation hinges on horsepower tier certification under BIS emission norms and after-sales service bundling through authorized dealer networks. Cost compression in sub-40 HP segments is intensifying because steel price volatility erodes assembler margins on price-sensitive cooperative procurement. Smallholders in Bihar and eastern Uttar Pradesh exhibit highest price sensitivity, while Punjab commercial farmers prioritize specification over unit cost.
Supply Chain Analysis
Inventory cycles for common-rail fuel injection systems stretch 12-16 weeks, compressing assembler flexibility during subsidy window peaks. Component sourcing draws from India, China, and Germany for transmission castings, electronic control modules, and precision hydraulic pumps. Raw material dependencies center on chassis-grade hot-rolled coil, diesel engine blocks, and tire rubber compounds. Single-source vulnerability concentrates in after-treatment system suppliers for BIS Stage-V-equivalent compliance. Distribution runs through agricultural cooperative procurement channels in eastern states and direct dealer negotiation in Punjab and Haryana commercial belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's tractor market is approaching a platform-economics inflection as ISOBUS implement control and telematics-enabled fleet management converge to create interoperable service layers across previously siloed equipment ecosystems.
For Market Incumbents: Compound distribution density in cooperative-financed belts through captive engine manufacturing integration, locking out refurbished equipment substitution from Punjab secondary markets. Deepen hydraulic system specialization for Haryana contracting segments to defend margin pools against precision-agriculture integrators. BIS homologation timeline compression represents the critical regulatory threat requiring preemptive certification investment. For New Entrants and Emerging Players: Anchor in Himachal Pradesh and Uttarakhand hill agriculture compact tractor white space, where maneuverability constraints block incumbent standard-frame dominance. Target vineyard and orchard configurations in Maharashtra's Nashik belt through demonstration-led direct sales bypassing dense rural dealer networks. Pursue state-level subsidy arbitrage via flexible domestic assembly footprints. For Investors and Strategic Acquirers: Captive powertrain-integrated regional specialists with deep southern state distribution and CEA agricultural electrification guideline alignment offer strongest long-term viability. Monitor FAME scheme adaptation fund disbursement velocity as the inflection signal for electrification pathway commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrostatic Transmission Integration | Haryana large contractors specify fluid-power architectures for loader-intensive field operations. |
| Common-Rail Engine Family Certification | BIS Stage-V-equivalent compliance locks in technology refresh timelines across 51-100 HP installed base. |
| Precision Agriculture Telematics Platform | ISOBUS convergence enables variable-rate application services in Punjab commercial farming belts. |
| Hill Agriculture Compact Tractor Development | Narrow-track sub-30 HP machines address maneuverability constraints in Himachal Pradesh terraced operations. |
| State Subsidy Channel Arbitrage | Flexible domestic sourcing footprints capture differential farm mechanization disbursement windows across agricultural departments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tractor OEM product managers, agricultural cooperative procurement officers, state agricultural department subsidy administrators, and hydraulic system component suppliers. Secondary validation drew from BIS certification registries, CEA agricultural electrification guideline releases, state agricultural department disbursement records, and customs data on chassis-grade steel imports. Bottom-up unit shipment estimates triangulated against top-down value aggregation across horsepower tiers and regional subsidy windows.
Across the analysis window, volume and value outputs reflect segmentation modeling by product type, engine power tier, application configuration, and end-user financing structure. CAGRs were derived from replacement cycle velocity analysis in rice-wheat systems and orchard mechanization expansion rates in western states. Industry-specific forecast inputs incorporated BIS emission norm phase-in schedules and FAME scheme adaptation fund flow projections.
Material uncertainties — subsidy disbursement delays, credit availability contractions through cooperatives, and steel price volatility spikes — sit outside the modeled envelope. Forecasts reflect assumptions on state agricultural department budget continuity and BIS certification cycle stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market