
 North America Advanced Phase Change Materials Market | 2026-2036
North America Advanced Phase Change Materials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Advanced Phase Change Materials Market Intelligence
U.S. specialty chemical producers is rebalancing capacity toward temperature-responsive material lines after years of commodity focus. BASF SE leverages its polymer science heritage to dominate organic PCM formulation for construction adhesives. Honeywell International Inc. sustains technology leadership in salt hydrate inorganic systems through captive R&D facilities in Virginia and Illinois. Phase Change Solutions anchors regional supply of bio-derived paraffin alternatives through dedicated biorefinery partnerships in the Midwest.
Advanced phase change materials are substances engineered to absorb or release substantial latent heat at constant temperature during solid-liquid transitions, typically formulated with paraffin waxes, salt hydrates, or fatty acid esters encapsulated in polymer shells or porous matrices for thermal cycling stability. Their primary commercial purpose is passive thermal regulation in built environments, cold chain logistics, and electronic enclosures where active cooling proves energy-intensive or impractical. Organic PCMs currently occupy the largest value share due to chemical stability and tunable melt points, while composite PCMs integrating graphite or metal foam represent the fastest-expanding margin pool as conductivity-enhanced configurations command premium positioning in electronics cooling and refrigerated transport. Bio-based PCMs remain nascent but attract capital as plant-derived feedstocks align with procurement criteria tied to federal sustainability scoring.
EPA energy efficiency standards for commercial buildings, combined with DOE certification protocols for thermal storage equipment and state-level stretch codes in California's Title 24, collectively elevate product performance thresholds and filter marginal suppliers from specification channels. NHTSA cold chain guidelines for pharmaceutical distribution further tighten temperature excursion limits, directly expanding PCM demand in refrigerated packaging for vaccine and biologic logistics. Stakeholders must monitor how the convergence of federal procurement mandates and utility rebate structures reshapes specification authority between contractors, facility managers, and direct manufacturers across the value chain.
Market Dynamics
Federal procurement mandates under the Inflation Reduction Act are redistributing specification authority from contractors to facility managers, compressing traditional distribution channels and forcing reformulation toward bio-based feedstocks.
Growth Catalysts
- California's Title 24 stretch codes:Passive thermal management requirements in commercial retrofits are mandating PCM integration in building envelopes across the state's cooling-dominated climate zones.
- Biologic cold chain logistics:NHTSA pharmaceutical distribution guidelines are tightening temperature excursion limits for vaccine transport, expanding PCM demand in refrigerated packaging.
- Sun Belt construction activity:Cooling-dominated climates in Texas, Arizona, and Florida are maximizing realized energy savings from PCM building applications.
Market Restraints
- Paraffin feedstock volatility:Crude oil price fluctuations directly compress margins for organic PCM formulations, the dominant chemistry category.
- Midwest supply concentration:Bio-derived paraffin alternatives depend on dedicated biorefinery partnerships concentrated in Iowa and Illinois, creating geographic vulnerability.
- Salt hydrate thermal cycling limits:Inorganic PCMs suffer from phase separation and supercooling after repeated freeze-thaw cycles, restricting deployment in high-frequency applications.
Strategic Opportunities
- DOE thermal storage certification:Federal procurement protocols for thermal storage equipment are opening specification channels for certified PCM suppliers in federal building retrofits.
- Graphite-composite conductivity enhancement:Integration of expanded graphite into paraffin matrices is unlocking premium positioning in electronics cooling and refrigerated transport.
- New York state energy codes:Stricter envelope performance standards in the Northeast are creating demand for PCM solutions in heating-dominated climate applications.
Industry Challenges
- Encapsulation engineering talent scarcity:Polymer shell design for thermal cycling stability requires specialized materials science expertise concentrated at captive R&D facilities.
- EPA commercial building compliance timelines:Energy efficiency standard verification creates extended certification cycles that delay product specification.
- Legacy HVAC integration complexity:PCM installation in existing building systems requires coordination with mechanical contractors unfamiliar with passive thermal management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Advanced Phase Change Materials Market |
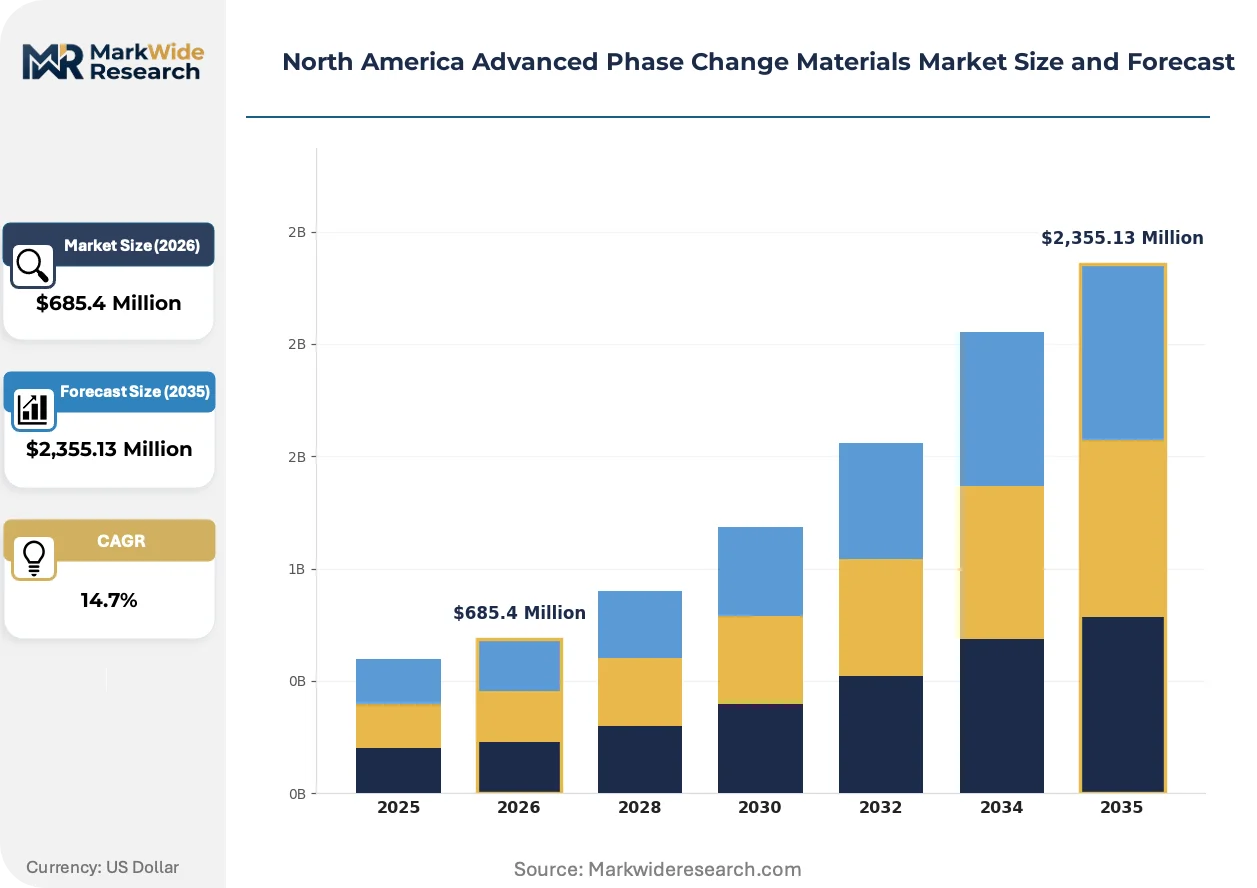
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,355.13 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic PCMs, Inorganic PCMs, Bio-based PCMs, Composite PCMs Application: Building & Construction, Thermal Energy Storage, Refrigeration, Electronics Cooling End User: Manufacturers, Contractors, Facility Managers, Homeowners Delivery Mode: Direct Sales, Distributors, Online Sales, Retail Stores |
| Companies Covered | BASF SE, Croda International Plc, Honeywell International Inc., Phase Change Solutions, PureTemp LLC, Rubitherm Technologies GmbH, Outlast Technologies LLC, 3M Company, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Advanced Phase Change Materials Market Strategic Shifts & Innovations
Formulation science and procurement authority are shifting simultaneously, with conductivity-enhanced composites capturing premium positioning while federal incentives restructure buyer-seller relationships across the value chain.
Encapsulated paraffin-graphite composites are decentralizing thermal management architecture in data center and electric vehicle battery applications. Hyperscale operators in Nevada and Arizona are specifying these materials for passive temperature regulation at the rack level. The technology is decentralizing cooling infrastructure investment from centralized mechanical systems toward distributed envelope-integrated solutions.
The Inflation Reduction Act's building efficiency incentives are restructuring contractor procurement criteria toward sustainability-scored materials. Federal facility managers in the General Services Administration are now bypassing traditional distribution channels to source directly from certified PCM manufacturers. Sun Belt states including Texas and Florida are experiencing the most rapid procurement model transformation as cooling load reduction delivers measurable utility rebate capture.
Facility managers are consolidating specification authority previously dispersed across general contractors and mechanical engineers. Direct manufacturer relationships are displacing distributor-mediated procurement in federal and large commercial retrofits. California and New York building portfolios are exhibiting the most pronounced channel compression as energy code compliance deadlines accelerate decision cycles.
North America Advanced Phase Change Materials Market Segmentation
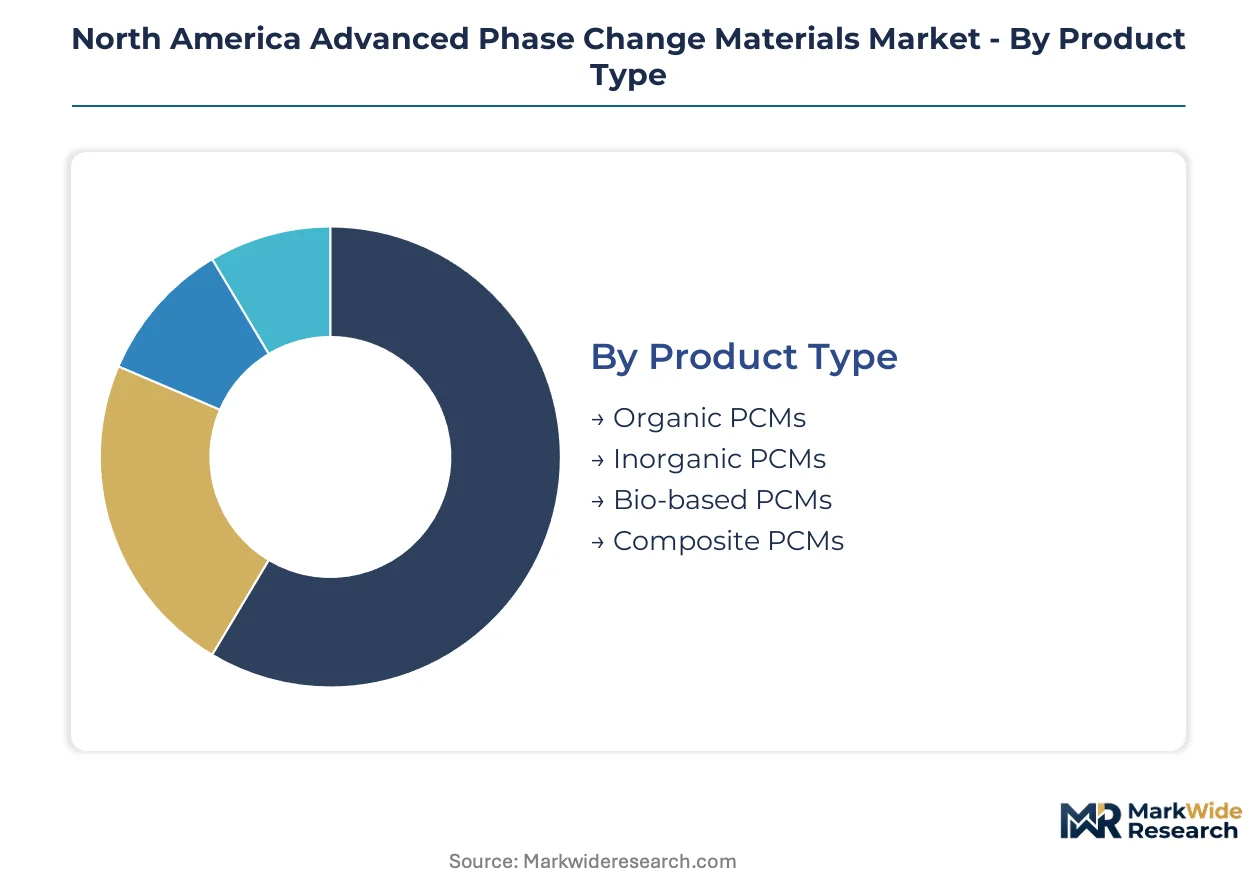
PCM procurement patterns diverge sharply between integrated building systems and standalone thermal management applications. Specification authority flows through distinct channels depending on whether materials embed within construction envelopes or deploy as discrete temperature-control solutions.
Product Type:
Integration depth separates segments formulated for direct incorporation into structural materials from those applied as surface-mounted or containerized thermal buffers.
- Organic PCMs:Paraffin waxes and fatty acid esters dominate commercial formulations due to chemical stability and precise melt-point tunability. Demand concentrates in U.S. Sun Belt building retrofits where California Title 24 stretch codes mandate passive thermal management in cooling-dominated climate zones. Paraffin feedstock volatility tied to crude oil pricing compresses margins unpredictably.
- Composite PCMs:Graphite or metal foam matrices enhance thermal conductivity beyond base PCM properties. Texas and Arizona data centers specify these for rack-level temperature regulation, displacing centralized mechanical cooling investment. Premium positioning in electronics and refrigerated transport commands margin expansion unavailable to conventional formulations.
- Inorganic PCMs:Salt hydrate systems leverage high latent heat density at lower material cost. Phase separation and supercooling after repeated cycling restrict deployment to lower-frequency thermal management applications.
- Bio-based PCMs:Plant-derived paraffin alternatives align with federal sustainability scoring under Inflation Reduction Act procurement criteria. Midwest biorefinery partnerships in Iowa and Illinois anchor regional supply.
Volume placements concentrate in Organic PCMs; the faster expansion belongs to Composite PCMs.
Application:
Cost-tier stratification separates capital-intensive building integration from consumable cold-chain packaging with divergent margin profiles.
- Building & Construction:PCM-integrated drywall, insulation, and roofing membranes deliver passive thermal regulation across envelope retrofits. New York state energy codes and California Title 24 collectively drive specification in heating-dominated and cooling-dominated climates respectively. Extended project timelines and HVAC contractor coordination complexity delay adoption in legacy building stock.
- Thermal Energy Storage:Grid-scale and building-level storage systems shift electrical demand away from peak pricing periods. DOE certification protocols for thermal storage equipment open federal procurement channels for verified suppliers.
- Refrigeration:NHTSA pharmaceutical distribution guidelines tighten temperature excursion limits for vaccine and biologic transport, expanding PCM demand in insulated packaging. Disposable cold-chain applications generate recurring revenue distinct from durable building installations.
- Electronics Cooling:Miniaturized thermal management for electric vehicle batteries and telecommunications hardware requires conductivity-enhanced formulations. Nevada and Arizona hyperscale operators deploy rack-level solutions to reduce mechanical infrastructure capital.
Revenue concentration sits with Building & Construction; Electronics Cooling climbs the fastest.
End User:
Customer-type fragmentation reflects specification authority redistribution from traditional contractors to directly engaged facility managers.
- Facility Managers:Federal and large commercial portfolio operators now bypass distributor channels to source certified PCM manufacturers directly. General Services Administration procurement under Inflation Reduction Act incentives accelerates this channel compression.
- Contractors:Mechanical and general contractors retain influence in residential and small commercial installations where rebate capture complexity discourages direct manufacturer engagement.
- Manufacturers:Building material producers integrate PCM into drywall, insulation, and roofing products at the factory level, capturing value through performance-differentiated product lines.
- Homeowners:Retail-accessible PCM solutions for attic insulation and window treatments remain limited by awareness gaps and installation complexity.
Procurement volume aggregates with Contractors; Facility Managers are gaining share fastest.
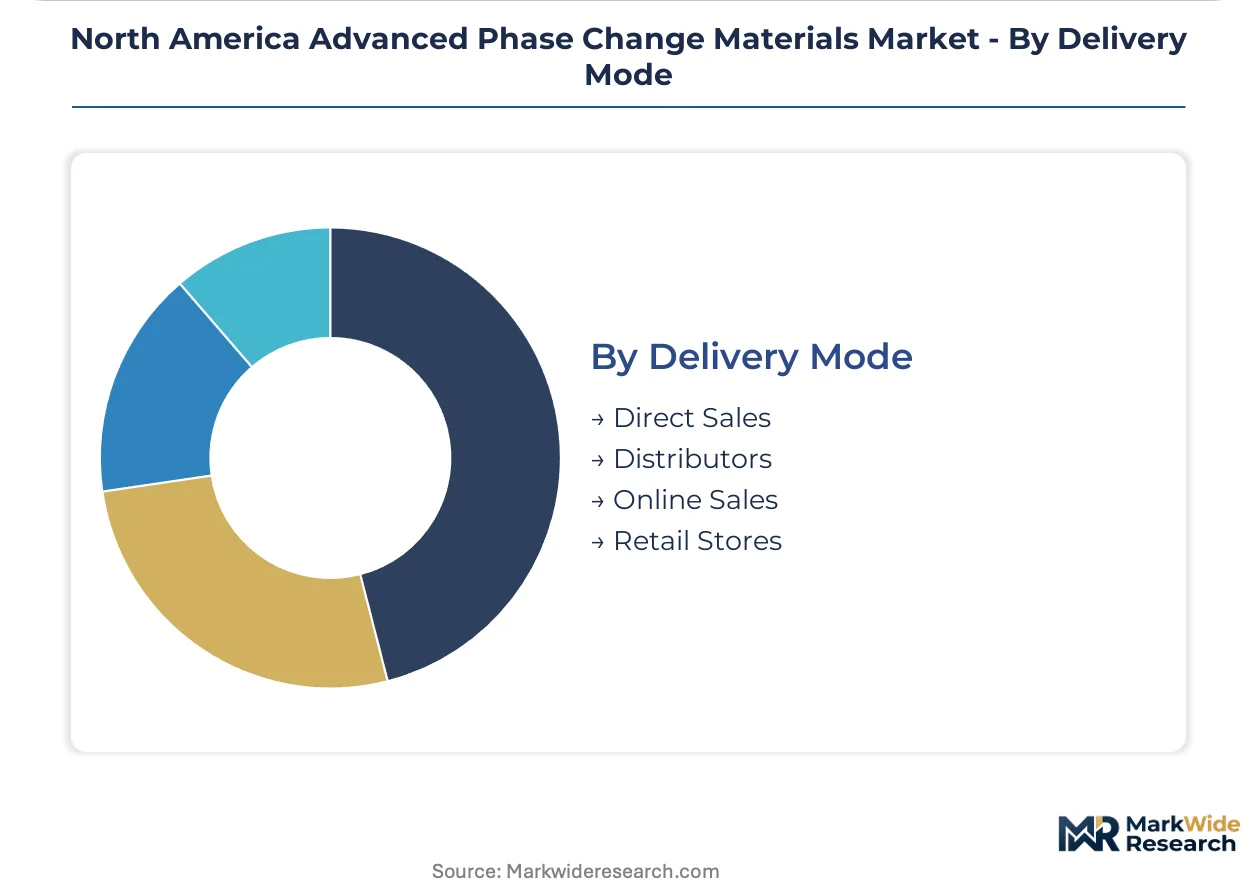
Delivery Mode:
Supply concentration shapes channel economics, with direct relationships capturing federal compliance value and distributor networks serving fragmented contractor bases.
- Direct Sales:Certified PCM manufacturers engage federal facility managers and large commercial portfolio operators for retrofit specifications. DOE thermal storage certification requirements favor direct technical engagement over intermediated distribution.
- Distributors:Regional building material distributors serve contractor-driven residential and light commercial segments where project scale does not justify direct manufacturer relationships.
- Online Sales:E-commerce channels support small-volume electronics cooling and cold-chain packaging procurement, particularly for standardized encapsulated formulations.
- Retail Stores:Big-box home improvement retailers stock limited PCM-enhanced insulation products, constrained by consumer education requirements and specialized installation protocols.
Transaction volume flows through Distributors; Direct Sales expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest biorefinery partnerships in Iowa and Illinois anchor North American bio-based PCM feedstock supply, while Sun Belt construction activity and federal procurement mandates concentrate demand across distinct sub-regional clusters.
United States
California's Title 24 stretch codes mandate passive thermal management in commercial retrofits across cooling-dominated climate zones. The Inflation Reduction Act's building efficiency incentives reshape procurement toward sustainability-scored materials through General Services Administration channels. Nevada and Arizona hyperscale data centers deploy rack-level PCM solutions to reduce mechanical cooling infrastructure capital.
Texas
Cooling-dominated climate conditions maximize realized energy savings from PCM building envelope applications in Dallas-Fort Worth and Houston metro construction. State energy rebate structures accelerate facility manager procurement model transformation away from contractor intermediation. Gulf Coast petrochemical corridors supply paraffin feedstocks for organic PCM formulations serving regional building material manufacturers.
New York
Stricter envelope performance standards in heating-dominated climates create demand for PCM solutions in commercial building retrofits across New York City and upstate portfolios. State-level stretch codes complement federal EPA commercial building efficiency timelines. Hudson Valley manufacturing clusters integrate phase change materials into factory-produced insulation and roofing membrane products.
Illinois
Dedicated biorefinery partnerships with Phase Change Solutions anchor regional supply of plant-derived paraffin alternatives for federal procurement compliance. Midwest agricultural feedstock access enables cost-competitive bio-based PCM production at scale. Chicago metropolitan construction activity applies these materials in cold-climate thermal storage applications distinct from Sun Belt cooling loads.
Canada
Ontario and Quebec building codes increasingly reference passive thermal management for commercial envelope performance, though adoption lags U.S. Sun Belt penetration. Health Canada guidelines for pharmaceutical cold chain distribution align with NHTSA temperature excursion standards, expanding PCM demand in cross-border vaccine logistics. Toronto and Montreal urban retrofit programs pilot PCM-integrated building materials in heating-dominated applications.
North America Advanced Phase Change Materials Market Key Industry Players
Global majors compete with regional champions across formulation chemistry and procurement channel access. The market exhibits tiered concentration with diversified chemical conglomerates, captive R&D specialists, and bio-based feedstock integrators occupying distinct strategic positions. Three archetypes dominate: polymer science heritage players commanding organic formulation, salt hydrate technology specialists with captive research facilities, and biorefinery partnership anchors securing sustainable feedstock access. Competitive moves concentrate on direct sales channel compression and conductivity-enhanced composite development.
Among diversified chemical conglomerates, BASF SE and Honeywell International Inc. exemplify scale-driven formulation science positions. BASF leverages polymer science heritage across construction adhesive applications, while Honeywell sustains technology leadership in inorganic systems through Virginia and Illinois R&D facilities. Phase Change Solutions occupies the bio-based integration archetype through Midwest biorefinery partnerships, securing feedstock access for federal sustainability-scored procurement. These three entities represent distinct competitive vectors: polymer formulation depth, inorganic system specialization, and renewable feedstock verticality.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Honeywell International Inc. |
| Phase Change Solutions |
| PureTemp LLC |
| Rubitherm Technologies GmbH |
| Outlast Technologies LLC |
| 3M Company |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
Captive biorefinery partnerships in Iowa and Illinois anchor both supply security and pricing power for bio-based formulations, while Gulf Coast petrochemical corridors feed organic PCM production with crude-linked feedstock volatility. This integration choice separates sustainability-scored federal procurement premiums from commodity-exposed paraffin margins.
Pricing Analysis
Warranty and technical certification bundling separates DOE-verified thermal storage suppliers from unbundled commodity formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by graphite-composite conductivity enhancement and encapsulation durability guarantees. Price differentiation hinges on federal procurement eligibility and California Title 24 compliance documentation. Cost compression in standard paraffin formulations is intensifying because crude oil price swings directly transfer to feedstock costs. Small commercial contractors exhibit highest price sensitivity; federal facility managers prioritize certification over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from General Services Administration procurement protocols require federal suppliers to qualify multiple encapsulation polymer providers and biorefinery feedstock partners. Geographic supply concentration centers on the United States Midwest for bio-derived alternatives, Texas Gulf Coast for petrochemical paraffin, and Virginia-Illinois corridors for salt hydrate R&D. Raw material dependencies rest on crude oil derivatives, plant-based fatty acid esters, and expanded graphite conductivity enhancers. Single-source vulnerability in Midwest agricultural feedstock regions threatens bio-based capacity scaling. Distribution runs through direct manufacturer relationships for federal retrofits and regional building material distributors for contractor-driven residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive biorefinery capacity and DOE certification laboratories is accelerating as players race to capture federal procurement premiums and insulate margins from paraffin feedstock volatility.
For Market Incumbents: Deepen control over Midwest biorefinery partnerships to secure plant-derived feedstock access against emerging bio-based specialists. Expand Virginia and Illinois R&D facilities to accelerate salt hydrate cycling stability improvements that threaten organic PCM dominance in high-frequency electronics cooling. Lock in General Services Administration direct sales channels before facility manager procurement consolidation completes. For New Entrants and Emerging Players: Regional distributors serving Sun Belt mechanical contractors represent the most accessible entry pathway for PCM-integrated insulation and roofing products. Target Texas and Arizona data center construction where rack-level thermal management specifications remain unsettled and hyperscale operators experiment with composite formulations. Pursue co-development partnerships with drywall and membrane manufacturers seeking performance-differentiated product lines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified chemical conglomerates seeking sustainability-scored construction material portfolios. Long-term viability favors players with verified DOE thermal storage certification and locked biorefinery offtake agreements. Watch for inflection when California Title 24 enforcement timelines compress decision cycles and filter uncertified suppliers from specification channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biorefinery Feedstock | Secures plant-derived paraffin alternatives for Inflation Reduction Act procurement compliance. |
| DOE Thermal Storage Certification Investment | Opens direct federal specification channels bypassing traditional distributor networks. |
| Graphite-Composite Formulation Development | Captures premium positioning in Nevada and Arizona hyperscale data center deployments. |
| Encapsulation Polymer R&D Expansion | Addresses talent scarcity in thermal cycling stability engineering for electronics applications. |
| Regional Distribution Partnership Consolidation | Builds contractor access in Texas and Florida where rebate complexity discourages direct engagement. |
Research Approach
Document review covered EPA energy efficiency standards, DOE thermal storage certification protocols, and NHTSA pharmaceutical distribution guidelines, complemented by interviews with plant managers at PCM formulation facilities, procurement leads at building material manufacturers, distribution channel partners in Sun Belt states, and technical R&D directors specializing in encapsulation engineering. Secondary validation drew from SEC 10-K filings of diversified chemical conglomerates, customs and trade data on paraffin wax imports, and state-level building code adoption tracking. Bottom-up project pipeline analysis and top-down construction spending forecasts were triangulated against primary field intelligence.
Segment-level projections across organic, composite, inorganic, and bio-based chemistries were generated through demand modeling incorporating California Title 24 compliance deadlines, Inflation Reduction Act incentive allocation, and regional construction permit data. CAGRs were derived from curve-fitting historical adoption patterns in cooling-dominated climate zones against projected federal procurement volumes. Industry-specific inputs included HVAC contractor familiarity thresholds with passive thermal management protocols and hyperscale data center rack-level deployment timelines.
Caveats apply where EPA commercial building compliance timeline extensions, Midwest agricultural feedstock supply disruptions, or salt hydrate supercooling breakthroughs could materially shift the outlook. Deviation in federal procurement mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
US Graphene Market
Advanced Materials
Wood Foam Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Extracellular Matrix Proteins Market