
 Carcinogenic Chemical Alternatives Market | 2026-2036
Carcinogenic Chemical Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Carcinogenic Chemical Alternatives Market Outlook
Pharmaceutical-grade purity specifications is bifurcating the competitive landscape into contract-grade suppliers and certified clean-material providers. BASF leverages its integrated fermentation platforms to secure biopolymer feedstock chains across Central Europe. DSM-Firmenich anchors its position through enzymatic catalyst portfolios that displace petrochemical-derived intermediates in personal care and pharma applications. Novozymes differentiates via high-activity enzyme concentrates purpose-built for solvent replacement in textile finishing.
Carcinogenic chemical alternatives comprise non-toxic or reduced-hazard substances engineered to replicate the functional performance of substances listed under IARC Group 1, 2A, or 2B classifications, typically achieving purity thresholds below 0.1% residual toxic content through bio-based synthesis or green chemistry process redesign. Their primary industrial purpose centers on maintaining coating adhesion, polymer flexibility, or antimicrobial protection without triggering occupational exposure limits or downstream product restrictions. Natural solvents command widening formulation share in coatings and packaging as volatile organic compound regulations harden, while bioplastics absorb capital in automotive interior programs seeking to eliminate phthalate plasticizers. Additive manufacturing materials remain nascent but carry premium positioning where medical device producers require biocompatible photopolymers free from styrene and bisphenol analogues.
REACH substance authorization, RoHS substance restrictions, and EU Green Deal industrial emissions targets collectively mandate substitution timelines that pull demand toward pre-certified alternatives. FDA food contact substance notifications and EPA Safer Choice labeling extend parallel compliance obligations for suppliers accessing North American consumer goods channels. Stakeholders must monitor regulatory amendment cycles and pre-register reformulation investments ahead of sunset date announcements rather than reacting to enacted bans.
Market Dynamics
REACH authorization deadlines are compressing substitution timelines across European manufacturing, forcing processors to pre-secure alternative feedstocks before sunset dates lock in supply contracts. This regulatory pull is restructuring procurement relationships between chemical formulators and their downstream customers.
Growth Catalysts
- EU Green Deal industrial emissions targets:Binding carbon reduction mandates accelerate capital allocation toward bio-based synthesis routes in coatings and adhesives production.
- Food contact notifications:FDA compliance requirements for North American consumer goods channels pull non-toxic formulation demand from packaging converters.
- Germany's industrial chemical corridor:Concentrated processor demand creates scale economies for certified clean-material providers serving substitution deadlines.
Market Restraints
- Feedstock cost volatility:Agricultural commodity price swings for corn and sugarcane-derived precursors compress margin stability for biopolymer producers.
- Enzyme supply concentration:High-activity catalyst manufacturing clusters in Denmark and the Netherlands create single-source vulnerability for textile finishers.
- Performance parity gaps:Bio-based plasticizers in automotive interiors currently fail durability thresholds for under-hood temperature cycling.
Strategic Opportunities
- India's pharmaceutical excipient market:CDSCO tightening on residual solvent limits creates first-mover positioning for certified clean-material providers.
- Medical device photopolymers:Biocompatible additive manufacturing materials for surgical guides and dental aligners command premium positioning.
- Enzymatic-solvent convergence:Textile processors combining biosurfactants with supercritical CO2 systems eliminate water-intensive finishing stages.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with dual expertise in petrochemical performance specifications and bio-based synthesis routes command compensation premiums that strain mid-tier producers.
- Multi-jurisdiction certification lag:Parallel REACH registration, EPA Safer Choice review, and FDA food contact notification timelines extend product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carcinogenic Chemical Alternatives Market |
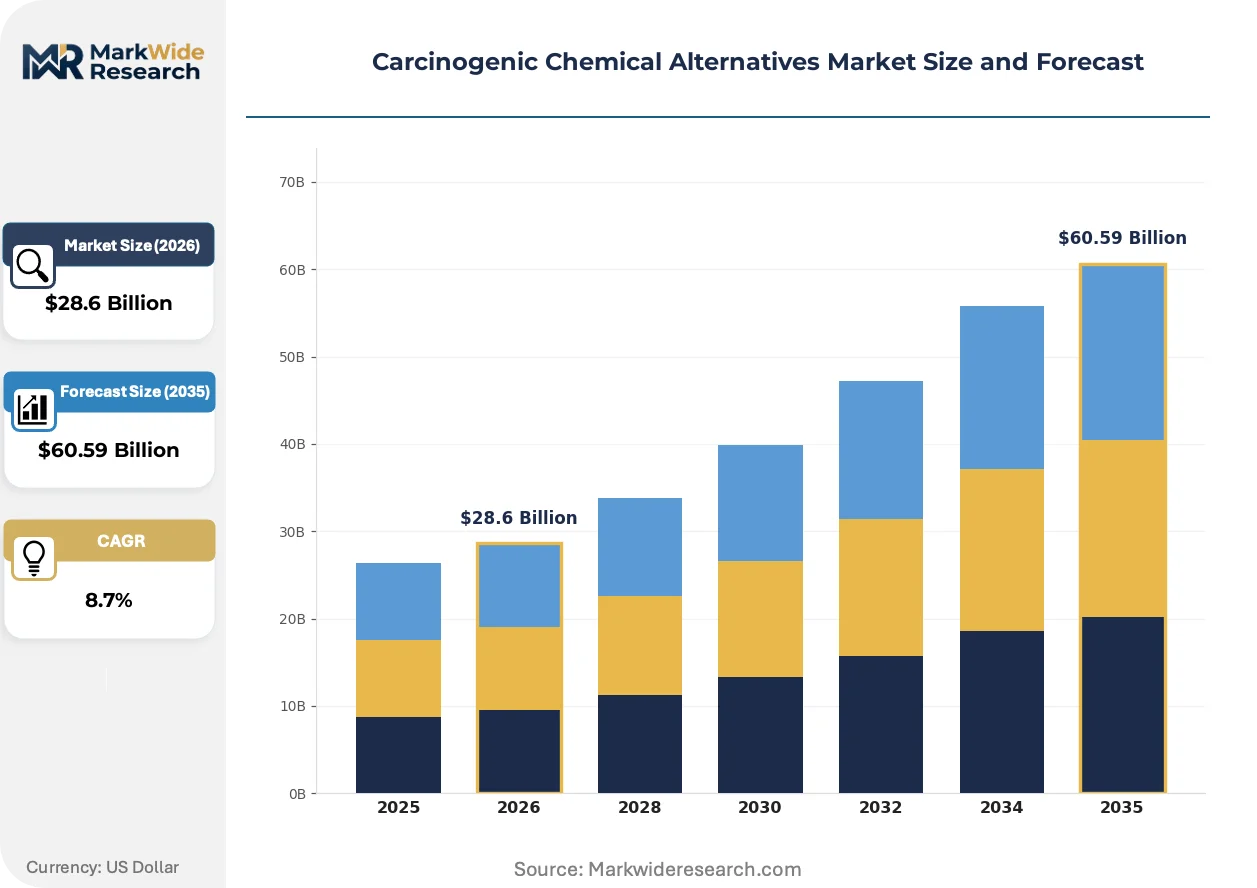
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastics, Natural Solvents, Eco-friendly Adhesives, Additive Manufacturing Materials Application: Packaging, Coatings, Textile Treatment, Construction End Use Industry: Consumer Goods, Automotive, Pharmaceutical, Food & Beverage Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | ChemSec Marketplace, Cargill, DSM-Firmenich, BASF, DuPont, Evonik Industries, Novozymes, Braskem, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carcinogenic Chemical Alternatives Market Strategic Shifts
Process intensification through continuous bioprocessing is collapsing batch cycle times and purification overhead. These advances are redrawing competitive boundaries between fermentation-based and petrochemical-derived intermediate suppliers.
Cell-free enzymatic synthesis platforms is decomposing the traditional fermentation bottleneck for high-purity specialty chemicals. Pharmaceutical API manufacturers in Switzerland and Germany are piloting these systems at 10,000-liter scale. The technology is decomposing capital barriers that previously locked bio-based production into dedicated multi-year fermentation assets.
REACH substance authorization amendments are tightening residual content thresholds for classified carcinogens in polymer additives. ECHA's 2024-2025 work program signals accelerated sunset date announcements for phthalate plasticizers and certain epoxy curing agents. Coating formulators in Italy and Poland are pre-registering reformulation investments to avoid supply disruption.
Certification-driven specification tightening is fragmenting buyer-seller relationships in food packaging. Major retail chains in France and the Netherlands now mandate third-party verified sub-0.1% residual toxic content, displacing legacy supplier qualification based on material safety data sheets alone. This behavior shift is most visible in flexible film converters serving private-label beverage brands.
Carcinogenic Chemical Alternatives Market Segmentation
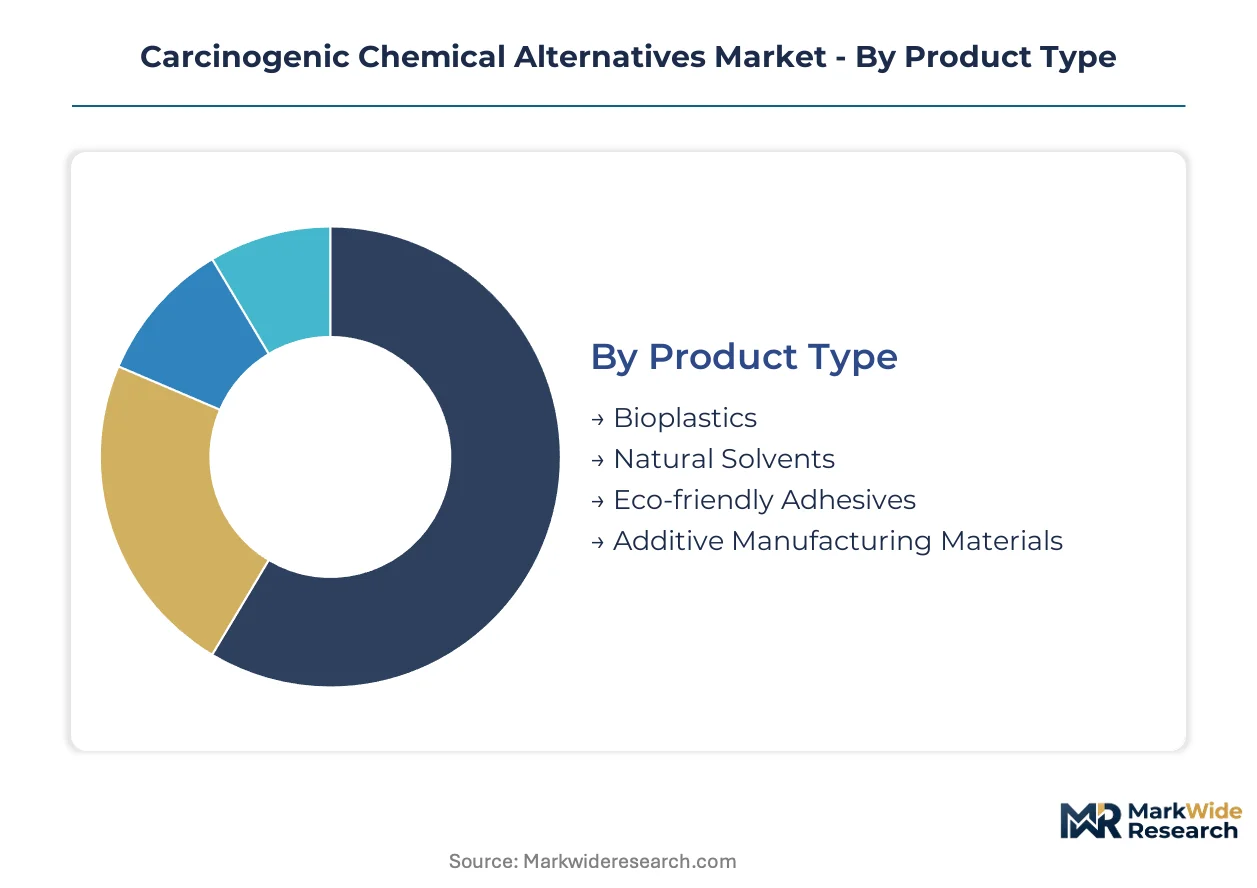
Segmentation in carcinogenic chemical alternatives reveals where procurement budgets are reallocating under regulatory pressure. Substitution timelines vary dramatically across product chemistries and end-use specifications, creating divergent margin profiles.
Product Type:
Margin pools concentrate in high-purity biopolymer grades where pharmaceutical and food contact certifications command pricing premiums over industrial contract grades.
- Bioplastics:Fermentation-derived polyesters and starch-based compounds achieve sub-0.1% residual toxic content through integrated bio-refining. Automotive interior programs in Germany's industrial chemical corridor absorb capacity as phthalate substitution deadlines tighten. REACH authorization amendments are compressing substitution timelines for classified plasticizers.
- Natural Solvents:Terpene-based and bio-ester formulations displace aromatic hydrocarbons in coating applications. Italian and Polish coating formulators are pre-registering reformulation investments ahead of ECHA sunset date announcements for toluene and xylene analogues.
- Eco-friendly Adhesives:Bio-based polyurethane and protein-bonded systems serve packaging converters facing third-party verified residual content mandates.
- Additive Manufacturing Materials:Biocompatible photopolymers for surgical guides and dental aligners occupy premium positioning where styrene-free specifications are non-negotiable.
The dominant share belongs to Bioplastics, while Additive Manufacturing Materials is closing the gap fastest.
Application:
Application segmentation tracks where regulatory enforcement is most advanced and where performance parity gaps persist between bio-based and legacy chemistries.
- Packaging:Flexible film converters serving French and Dutch retail chains face third-party verified sub-0.1% residual toxic content requirements. Certification-driven specification tightening is fragmenting legacy supplier relationships.
- Coatings:Architectural and industrial protective layers absorb natural solvent demand as volatile organic compound regulations harden across EU member states.
- Textile Treatment:Biosurfactant and enzymatic finishing systems eliminate water-intensive processing stages. High-activity enzyme supply concentrates in Denmark and the Netherlands.
- Construction:Low-emission adhesives and sealants serve green building certification schemes with binding indoor air quality thresholds.
Packaging holds the revenue concentration, though Textile Treatment is expanding most quickly through enzymatic-solvent convergence.
End Use Industry:
End-use segmentation reflects divergent purity specifications and certification burdens across consumer-facing and industrial channels.
- Consumer Goods:Personal care and household product formulators source certified clean-material grades to meet retailer-imposed substance restrictions.
- Automotive:Interior trim and under-hood applications demand durability thresholds that bio-based plasticizers currently fail for temperature cycling specifications.
- Pharmaceutical:API manufacturers in Switzerland and Germany pilot cell-free enzymatic synthesis at 10,000-liter scale for high-purity intermediate production.
- Food & Beverage:FDA food contact substance notifications and EU framework regulation compliance create parallel procurement requirements for packaging converters accessing North American and European channels simultaneously.
Food & Beverage anchors volume demand, while Pharmaceutical is climbing the fastest through enzymatic platform adoption.
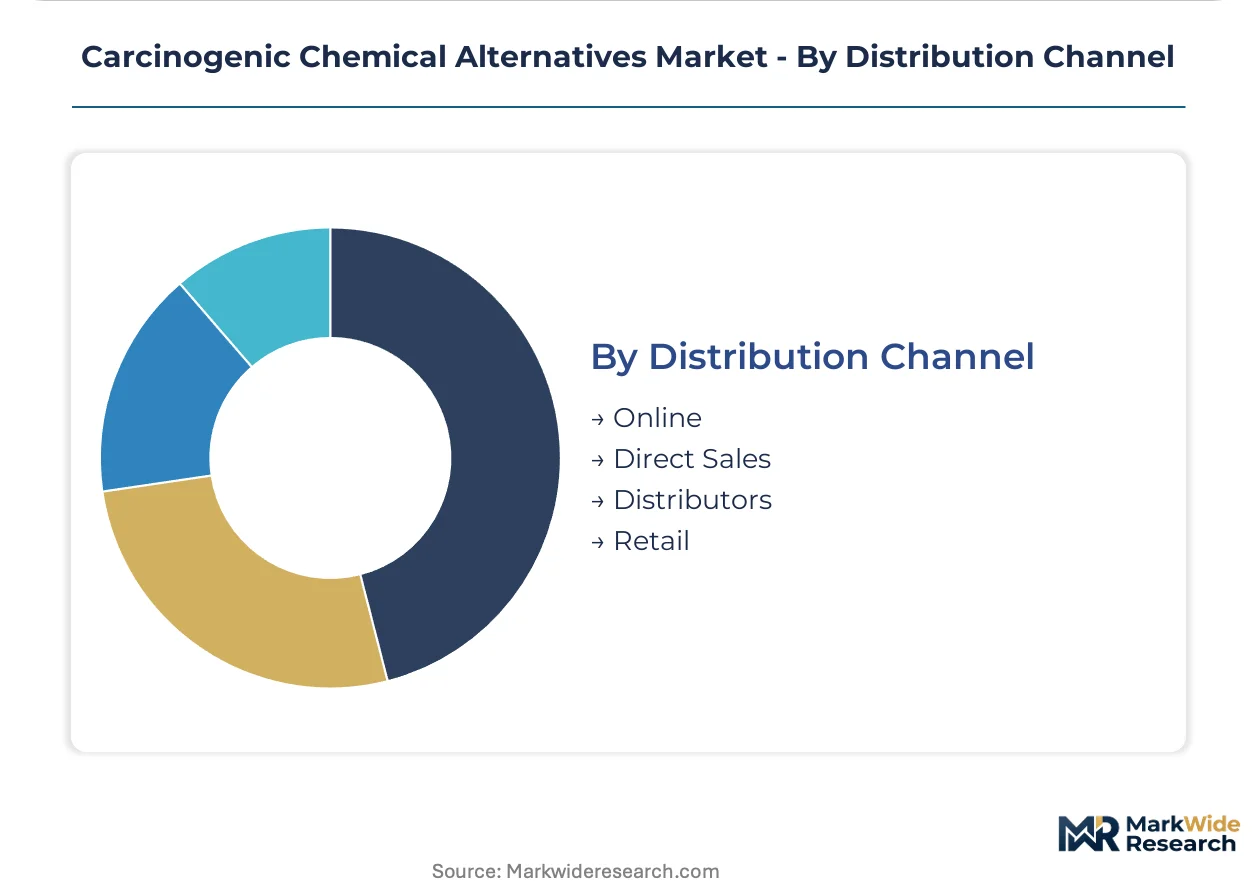
Distribution Channel:
Channel segmentation tracks how procurement relationships are restructuring under compressed substitution timelines and pre-certification requirements.
- Online:Digital procurement platforms serve mid-tier formulators seeking rapid qualification of pre-certified alternative feedstocks.
- Direct Sales:Integrated suppliers like BASF leverage fermentation platform relationships to lock in multi-year supply contracts ahead of sunset dates.
- Distributors:Regional chemical distributors carry inventory risk for agricultural commodity-derived precursors subject to price volatility.
- Retail:Limited to small-volume specialty adhesive and coating products for professional contractor segments.
Direct Sales commands the margin pool, while Online is gaining share fastest among time-constrained formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in carcinogenic chemical alternatives tilt toward net exporters in fermentation-capable economies while import-dependent processors in industrial manufacturing hubs absorb certification-compliant feedstocks. Trade flows concentrate where REACH enforcement and FDA notification requirements create parallel procurement specifications.
Germany
Automotive interior programs and coating formulators in the industrial chemical corridor drive concentrated demand for phthalate-free plasticizers and natural solvents. ECHA's REACH authorization amendments compress substitution timelines for classified carcinogens. BASF's Ludwigshafen fermentation platforms anchor biopolymer supply chains serving sunset-date procurement deadlines.
United States
Food contact substance notifications and EPA Safer Choice labeling pull non-toxic formulation demand from packaging converters accessing consumer goods channels. FDA compliance requirements for North American markets mandate pre-certified alternative feedstocks. Midwestern bioprocessing clusters absorb capital for corn-derived precursor production.
China
Dual carbon goals and tightening GB standards on industrial emissions accelerate bio-based solvent adoption in coatings and adhesives production. The country's national chemical regulator advances registration requirements for reduced-hazard alternatives. Yangtze River Delta manufacturing zones pilot enzymatic catalyst systems for textile finishing applications.
India
CDSCO tightening on residual solvent limits in pharmaceutical excipients creates first-mover positioning for certified clean-material providers. FSSAI framework regulations extend compliance obligations to food packaging converters. Gujarat and Maharashtra industrial corridors concentrate procurement relationships with fermentation-based intermediate suppliers.
Switzerland
Pharmaceutical API manufacturers pilot cell-free enzymatic synthesis platforms at commercial scale for high-purity intermediate production. Swissmedic certification requirements for medical device materials command premium positioning for biocompatible photopolymers. Basel-area biotech clusters integrate biosurfactant production with supercritical processing systems.
Carcinogenic Chemical Alternatives Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where integrated fermentation platforms face agile enzymatic catalyst developers. The vendor base spans multinational chemical conglomerates with captive bio-refining assets and mid-tier contract manufacturers serving regional substitution deadlines. Three archetypes dominate: integrated biopolymer producers, enzymatic platform specialists, and agricultural commodity processors. Competitive moves center on backward integration into fermentation feedstocks and pre-certification investments ahead of regulatory sunset dates.
Among integrated biopolymer producers, BASF and Braskem exemplify scale-driven archetypes with fermentation platform control. DSM-Firmenich occupies a position bridging enzymatic catalyst portfolios with personal care and pharmaceutical applications. Novozymes sits within the high-activity enzyme concentrate tier purpose-built for solvent replacement in textile finishing.
| Leading Market Players |
|---|
| ChemSec Marketplace |
| Cargill |
| DSM-Firmenich |
| BASF |
| DuPont |
| Evonik Industries |
| Novozymes |
| Braskem |
| Tate & Lyle |
| Others |
Value Chain & Pricing Dynamics
REACH authorization deadlines and third-party certification requirements gate both supplier qualification and price differentiation simultaneously. Food contact substance notifications under FDA and EU framework regulations create parallel compliance costs that stratify pricing tiers between certified clean-material providers and contract-grade alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with pharmaceutical and food contact purity specifications commanding substantial premiums over industrial contract grades. Cost compression in standard tiers is intensifying because agricultural commodity price volatility for corn and sugarcane-derived precursors squeezes biopolymer producer margins. Mid-tier formulators exhibit highest price sensitivity due to limited reformulation budgets, while pharmaceutical API manufacturers show lowest sensitivity given non-negotiable purity thresholds.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for enzymatic catalyst shipments originating in Denmark and the Netherlands. Supply concentrates in Germany's industrial chemical corridor, China's Yangtze River Delta manufacturing zones, and India's Gujarat pharmaceutical clusters. Raw material dependencies rest on fermentation feedstocks, high-activity enzyme concentrates, and terpene-based solvent precursors. Single-source vulnerability for textile finishing catalysts creates structural supply chain risk. Distribution runs through direct sales relationships for integrated producers and regional chemical distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of formulation chemists with dual expertise in petrochemical performance specifications and bio-based synthesis routes concentrates competitive advantage among firms with captive talent pipelines. This capability gap shapes strategic priorities across incumbent defenders, new entrants, and capital allocators.
For Market Incumbents: Shield market position by accelerating backward integration into fermentation feedstock chains ahead of REACH sunset date announcements. Prioritize pre-certification investments for FDA food contact notifications and EPA Safer Choice labeling to lock in multi-year supply contracts with packaging converters facing third-party verified residual content mandates. The threat of agile enzymatic platform specialists capturing textile finishing demand requires defensive capacity expansion in high-activity enzyme manufacturing. For New Entrants and Emerging Players: FDA food contact notification fast-tracks open positioning in North American packaging channels where incumbent qualification timelines create temporary supply gaps. Target India's pharmaceutical excipient market where CDSCO residual solvent tightening outpaces domestic clean-material supply. Penetrate through enzymatic-solvent convergence offerings for textile processors seeking water-intensive finishing stage elimination. White-space exists in medical device photopolymers where biocompatible specifications remain underserved. For Investors and Strategic Acquirers: ECHA's accelerated sunset date announcements for phthalate plasticizers and epoxy curing agents reshape the acquisition landscape toward pre-certified alternative feedstock producers. Long-term viability favors integrated fermentation platform operators with captive bio-refining assets and established REACH registration dossiers. Acquisition target archetype: mid-tier enzymatic catalyst developers with scalable cell-free synthesis technology. Monitor ECHA work program amendments as the inflection signal for substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | BASF's Ludwigshafen platforms secure biopolymer supply chains against agricultural commodity volatility. |
| Pre-Certification Investment | Early REACH registration and FDA notification completion locks in procurement relationships before sunset dates. |
| Cell-Free Enzymatic Scale-Up | Swiss and German API manufacturers pilot 10,000-liter systems that collapse traditional fermentation capital barriers. |
| Joint Venture for Textile Enzyme Supply | Denmark-Netherlands catalyst manufacturing clusters reduce single-source vulnerability for finishers. |
| Green Manufacturing Transition | Continuous bioprocessing adoption collapses batch cycle times and purification overhead for specialty chemicals. |
Study Parameters
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings. Plant managers at fermentation facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at coating formulators provided operational perspectives. Secondary sources include ECHA substance authorization databases, FDA food contact substance notifications, SEC 10-K disclosures from listed chemical producers, and customs trade data for bio-based precursor flows. Bottom-up segment sizing triangulates against top-down regulatory mandate impact assessments.
Sensitivity analysis around substitution timeline assumptions tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, certification grade, and regional regulatory cluster. CAGRs derive from regression analysis of historical procurement volume shifts correlated with REACH sunset date announcements. Industry-specific inputs incorporate ECHA work program schedules and FDA notification approval velocity.
Underlying assumptions cover regulatory enforcement continuity and feedstock cost normalization, with deviation risk concentrated in accelerated ECHA authorization amendments or prolonged agricultural commodity price spikes. Forecasts reflect these assumptions without certainty guarantees. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Pentanedione Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Spirodiclofen Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Fluorochemicals Market
Chemicals
Carbon Tetrabromide Market
Chemicals
China Amines Market
Chemicals
p-Coumaric Acid Market
Chemicals
Potassium Iodide Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Egypt Acidulants Market
Chemicals
Di Nitro Toluene Market
Chemicals
Ferric Oxide Market
Chemicals
Desalination Chemicals Market